
 Global Modular Fabrication Market | 2026-2036
Global Modular Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Modular Fabrication Market Outlook
Digital twin integration with prefabrication workflows is narrowing the gap between design intent and field assembly precision. Laing O'Rourke leverages its Design for Manufacture and Assembly methodology to control project delivery timelines across complex infrastructure bids. Skanska anchors its Nordic and UK modular operations through factory-controlled quality systems that reduce on-site labor dependency. Fluor Corporation competes in energy and industrial modules by sustaining long-term fabrication partnerships in the US Gulf Coast and Southeast Asia.
Modular fabrication encompasses the offsite production of building sections or process units in controlled factory environments, typically involving steel framing, concrete panels, or timber composites assembled to tolerances of ±2 millimeters before transport to final locations. This approach serves primary industrial and commercial purposes by compressing construction schedules, reducing weather exposure, and standardizing quality across dispersed project sites. Prefabricated structures command the largest value share due to their deployment in healthcare and education projects where speed-to-occupancy drives procurement decisions, while 3D printing represents the fastest-expanding technology segment as concrete deposition systems mature for low-rise residential applications. Traditional assembly still dominates volume in emerging markets where capital constraints limit automated manufacturing adoption.
The EU Green Deal and REACH frameworks mandate embodied carbon disclosure for construction materials entering European markets, compelling modular suppliers to certify supply chain emissions or risk exclusion from public tenders. OSHA in the US and Japan's METI both enforce factory safety standards that elevate operational compliance costs but simultaneously reduce liability exposure compared with conventional site-built construction. Australia's NCC energy efficiency provisions and BCA fire rating requirements shape product specifications for residential modules destined for multi-story developments. Stakeholders must monitor how building code harmonization between national jurisdictions affects cross-border module certification and factory utilization rates.
Market Dynamics
Labor scarcity across developed construction economies is compressing project timelines and elevating factory-based prefabrication from alternative method to default delivery mode for complex infrastructure.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Disclosure requirements for construction materials entering European markets force developers toward certified low-carbon modular systems that factory environments can document and verify.
- Remote mining operations:Australian resource extraction sites in Western Australia and Queensland generate recurring demand for rapidly deployable worker accommodation modules that withstand extreme climate conditions.
- Cross-laminated timber maturation:Engineered wood products achieve structural performance parity with steel in mid-rise applications while satisfying biogenic carbon storage preferences among institutional buyers.
Market Restraints
- Steel input cost volatility:Fluctuations in global scrap and hot-rolled coil prices compress fabrication margins and complicate fixed-price contracting for multi-year infrastructure pipelines.
- Transportation dimensional limits:Highway corridor clearances and bridge load ratings in Japan constrain module widths, forcing design fragmentation that erodes factory efficiency gains.
- Conventional site-built substitution:Low-rise residential segments in emerging markets retain cost advantages through informal labor pools that undercut factory wage structures.
Strategic Opportunities
- German hospital infrastructure backlog:Aging healthcare facilities and energy retrofit mandates create procurement windows for modular clinical wings that minimize operational disruption during installation.
- Digital twin-to-fabrication convergence:Integration of building information modeling with CNC production equipment enables mass customization without sacrificing throughput velocity.
- Japan METI factory automation incentives:Government subsidies for robotics deployment in construction manufacturing lower capital barriers for timber and steel module producers.
Industry Challenges
- Building control officer certification gaps:Jurisdictions lack sufficient inspectors qualified to evaluate factory quality systems against site-built code equivalents, delaying occupancy permits.
- Legacy MEP integration complexity:Mechanical, electrical, and plumbing systems designed for conventional construction require redesign to accommodate module joint tolerances and transport stresses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Modular Fabrication Market |
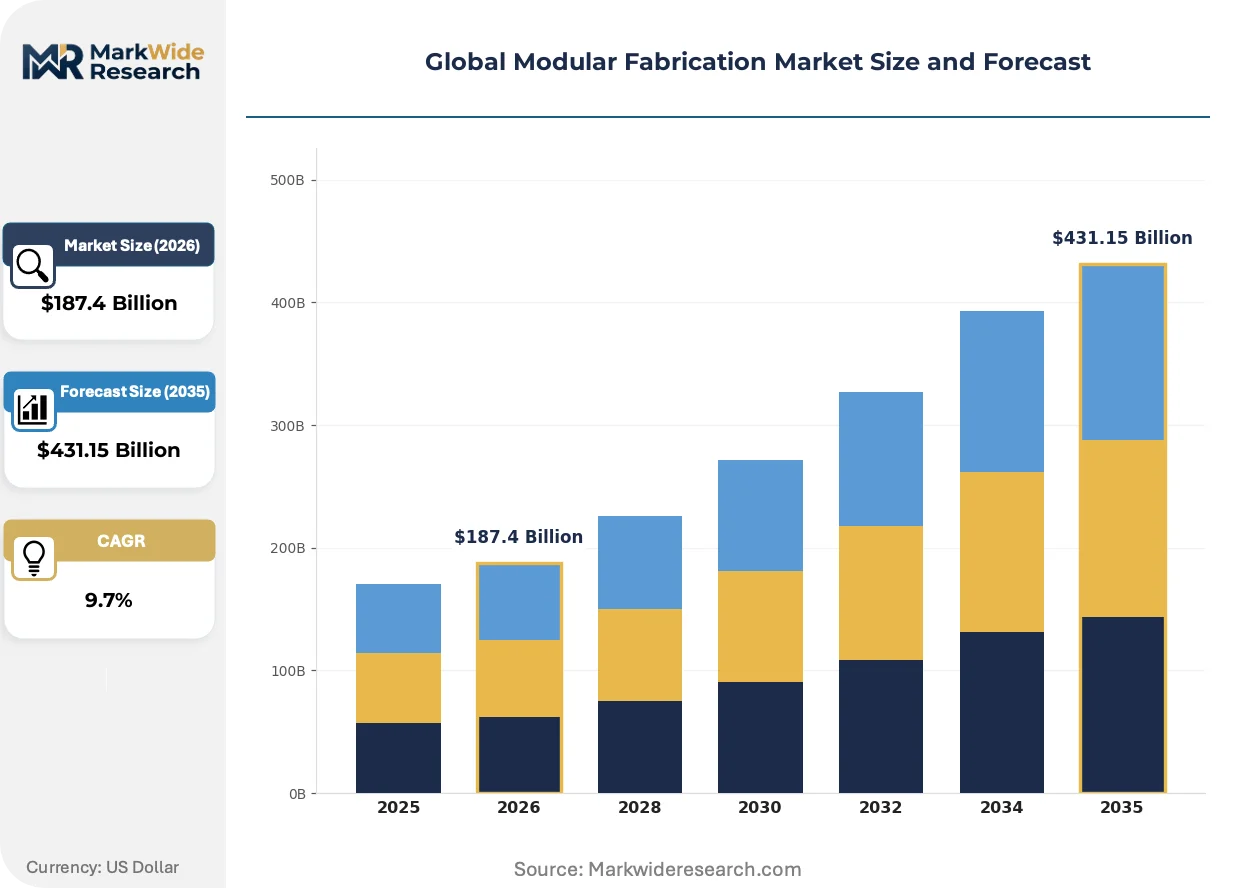
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $431.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Buildings, Prefabricated Structures, Portable Cabins, Modular Components End User: Construction Companies, Real Estate Developers, Government Agencies, Educational Institutions Technology: 3D Printing, Robotics, Automated Manufacturing, Traditional Assembly Application: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Larsen & Toubro Limited, Laing O'Rourke, Lendlease Corporation, ATCO Ltd., Skanska, Fluor Corporation, CIMC Modular Building Systems, Balfour Beatty, Kleusberg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Modular Fabrication Market Strategic Shifts
Factory-controlled production environments are enabling precision tolerances and quality documentation that site construction cannot replicate, reshaping competitive advantage around manufacturing capability rather than field supervision.
Concrete deposition systems for three-dimensional printing are migrating from experimental demonstration to commercial deployment in low-rise residential foundations and wall assemblies. German developers pilot these systems for social housing projects where speed and labor reduction outweigh aesthetic limitations. The technology is migrating from prototype installations to standardized production workflows that compress foundation schedules from weeks to days.
REACH framework amendments tighten disclosure thresholds for hazardous substances in construction products, compelling modular suppliers to requalify adhesives, coatings, and engineered wood resins. Manufacturers serving European healthcare and education sectors face reformulation deadlines that favor suppliers with established chemical management systems. Cross-border module certification now requires documented supply chain transparency that smaller fabricators struggle to assemble.
Real estate developers in Australia consolidate procurement around design-build-operate contracts that transfer lifecycle performance risk to module suppliers. This compresses traditional bid-evaluate-award cycles and rewards fabricators with in-house maintenance networks. Mining sector buyers in Western Australia now specify ten-year service agreements alongside initial capital purchases, privileging vendors with regional spare parts logistics.
Global Modular Fabrication Market Segmentation
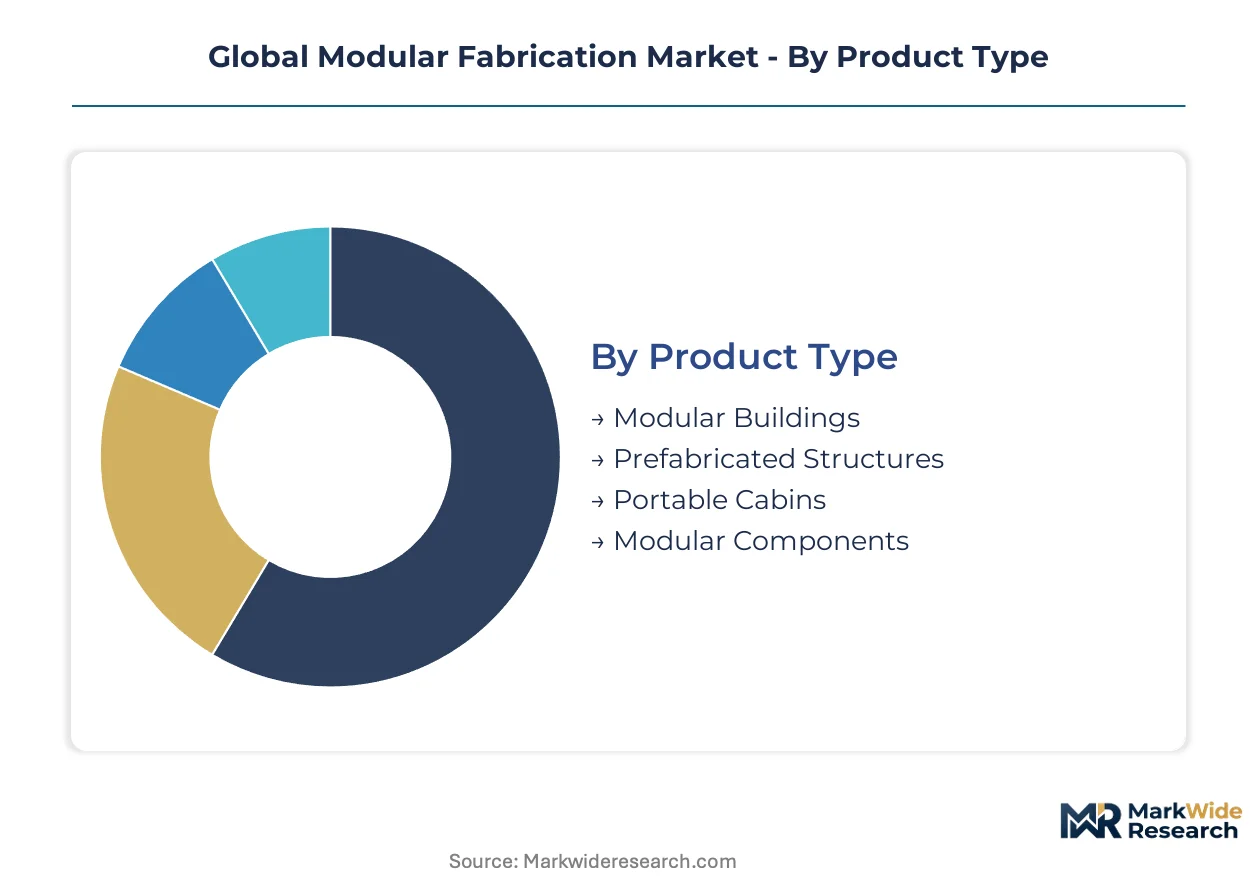
Segmentation in modular fabrication reveals how factory-based production methods align with distinct procurement priorities across project types. Understanding these divisions exposes where standardization conflicts with customization demands and which technology investments yield differential returns.
Product Type:
Cost tier stratification across product categories determines capital intensity requirements and margin profiles for fabrication facilities.
- Modular Buildings:Fully enclosed volumetric units complete with MEP systems and interior finishes, delivered as sealed weather-tight assemblies. Demand concentrates in Australian healthcare and education procurement where speed-to-occupancy clauses penalize schedule overruns.
- Prefabricated Structures:Panelized or component-based systems requiring on-site assembly and integration. German hospital infrastructure backlogs drive specification for clinical wings that minimize operational disruption during installation.
- Portable Cabins:Relocatable single-module units for temporary workforce accommodation. Western Australian mining operations generate recurring orders for climate-resilient rapid-deployment units.
- Modular Components:Sub-assemblies such as bathroom pods, plant rooms, or facade cassettes. Japanese METI automation incentives accelerate robotics adoption for precision component production.
Prefabricated structures hold installed capacity. Modular buildings are rotating up the share rankings.
End User:
Customer type diversity creates divergent contracting structures, from fixed-price manufacturing to design-build-operate risk transfer arrangements.
- Construction Companies:General contractors procuring modules as schedule compression tools on complex infrastructure bids. Laing O'Rourke's Design for Manufacture and Assembly methodology exemplifies integration of fabrication workflows into construction management.
- Real Estate Developers:Asset owners seeking lifecycle performance guarantees and accelerated revenue recognition. Australian developers consolidate procurement around ten-year service agreements that privilege vendors with regional maintenance networks.
- Government Agencies:Public sector buyers with mandated embodied carbon disclosure requirements under EU Green Deal frameworks. Procurement specifications increasingly require certified supply chain emissions documentation.
- Educational Institutions:University and school districts with occupancy-driven funding cycles. Speed-sensitive buyers prioritize modules that compress summer construction windows.
Construction companies dominate current procurement volume. Real estate developers are climbing the fastest as risk-transfer contracting expands.
Technology:
Production method maturity spans experimental demonstration through standardized commercial deployment, with capital barriers stratifying competitive participation.
- 3D Printing:Concrete deposition systems achieving commercial scale for low-rise residential foundations and wall assemblies. German social housing pilots validate speed and labor reduction advantages.
- Robotics:Automated welding, cutting, and material handling systems deployed in controlled factory environments. Japan's METI subsidies lower capital barriers for timber and steel module producers.
- Automated Manufacturing:CNC-controlled production equipment integrated with building information modeling for mass customization without throughput sacrifice.
- Traditional Assembly:Labor-intensive fabrication methods retaining cost advantages in emerging markets where informal construction labor pools undercut factory wage structures.
Traditional assembly maintains volume leadership. 3D printing is gaining share fastest as concrete deposition technology standardizes.
Application:
End-use sector requirements shape module specifications for durability, code compliance, and aesthetic performance.
- Residential:Single and multi-family housing modules subject to national building code variations that complicate cross-border certification. Australian NCC energy efficiency provisions shape specifications for multi-story developments.
- Commercial:Office and retail modules demanding facade flexibility and MEP adaptability for tenant customization.
- Industrial:Process equipment enclosures and utility modules for energy and manufacturing facilities. Fluor Corporation sustains fabrication partnerships in the US Gulf Coast and Southeast Asia for this segment.
- Institutional:Healthcare and education modules with stringent fire rating and infection control requirements. Skanska anchors Nordic and UK operations through factory-controlled quality systems that reduce on-site labor dependency.
Institutional applications anchor premium pricing. Residential is rotating up the share rankings as 3D printing technology penetrates low-rise construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German modular fabricators export cross-laminated timber systems to Dutch and Scandinavian buyers seeking embodied carbon compliance, while Australian producers ship climate-resilient worker accommodation modules to remote mining sites across Southeast Asia and the Pacific.
United States
Energy sector demand drives industrial module fabrication along the Gulf Coast, where petrochemical expansions require rapidly deployable process enclosures. OSHA factory safety standards elevate compliance costs but reduce liability exposure versus conventional construction. Houston-area fabrication yards anchor production capacity for Fluor Corporation's energy and industrial module partnerships.
Germany
Hospital infrastructure backlogs and energy retrofit mandates create procurement windows for modular clinical wings. EU Green Deal embodied carbon disclosure requirements force developers toward certified low-carbon systems that factory environments can document. Bavarian timber engineering clusters supply cross-laminated timber modules meeting institutional biogenic carbon storage preferences.
Japan
Labor scarcity and METI factory automation subsidies accelerate robotics deployment in timber and steel module production. Highway corridor dimensional limits constrain module widths, forcing design fragmentation that erodes factory efficiency. Osaka-Nagoya industrial corridors concentrate automated manufacturing investments for precision component output.
Australia
Government infrastructure pipelines and Western Australian mining operations drive modular hospital and worker accommodation orders. NCC energy efficiency provisions and BCA fire rating requirements shape specifications for multi-story residential developments. Queensland fabrication facilities specialize in climate-resilient rapid-deployment units for resource extraction sites.
United Kingdom
Skanska anchors Nordic and UK modular operations through factory-controlled quality systems reducing on-site labor dependency. Laing O'Rourke leverages Design for Manufacture and Assembly methodology to control project delivery timelines across complex infrastructure bids. Midlands fabrication clusters serve healthcare and education procurement where speed-to-occupancy clauses penalize schedule overruns.
Global Modular Fabrication Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven fabricators, technology-integrated constructors, and regional component suppliers occupy distinct competitive positions. The market fragments across construction conglomerates diversifying into factory-based delivery, pure-play modular specialists, and industrial engineering firms with captive fabrication networks. Two archetypes dominate: integrated design-build-operate platforms capturing lifecycle value, and component-focused suppliers embedding into broader construction supply chains. Capacity expansion and strategic partnerships constitute the primary competitive moves, with fabricators securing long-term offtake agreements and technology licensors.
Among construction-integrated fabricators, Laing O'Rourke and Skanska exemplify the design-build-operate archetype, while Fluor Corporation occupies a position within industrial module specialization for energy sector applications. These three entities represent contrasting strategic postures: methodology-driven construction management, factory-quality system anchoring, and fabrication partnership sustainment across geographically dispersed energy markets.
| Leading Market Players |
|---|
| Larsen & Toubro Limited |
| Laing O'Rourke |
| Lendlease Corporation |
| ATCO Ltd. |
| Skanska |
| Fluor Corporation |
| CIMC Modular Building Systems |
| Balfour Beatty |
| Kleusberg |
| Others |
Value Chain & Pricing Dynamics
Houston-area fabrication yards on the US Gulf Coast concentrate industrial module capacity for energy sector buyers, compressing delivery timelines and elevating pricing power for fabricators with long-term offtake agreements. This supply concentration feeds directly into how project developers negotiate fixed-price contracts across multi-year infrastructure pipelines.
Pricing Analysis
Current-generation automated manufacturing systems command substantial premiums over traditional assembly methods, while next-generation 3D printing technologies remain priced at pilot-scale premiums. Project-based contract pricing dominates procurement for complex infrastructure, with price differentiation driven by certification grade under EU Green Deal frameworks and geographic delivery cost to remote sites. Cost compression in standard modular components is intensifying because steel input volatility erodes fabrication margins. Mining sector buyers in Australia exhibit the lowest price sensitivity due to ten-year service agreement structures, while emerging market residential developers remain highly price-sensitive to factory wage premiums.
Supply Chain Analysis
Export-control restrictions on advanced robotics and CNC production equipment limit technology transfer to certain fabrication markets, constraining capacity expansion in targeted regions. Supply concentrates in Germany, Australia, and Japan, with raw material dependencies on cross-laminated timber feedstock, hot-rolled steel coil, and engineered wood resins. Single-source vulnerability runs through specialized MEP component suppliers qualified for healthcare module specifications. Distribution runs through design-build-operate platforms that capture lifecycle value rather than transactional component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The widening gap between factory-automated and site-built capability creates asymmetric returns for players that master precision manufacturing workflows. Firms with documented quality systems and certified supply chain transparency command procurement preference in institutional segments.
For Market Incumbents: Build captive maintenance networks as the primary moat against pure-play fabricators. Incumbents should anchor factory-controlled quality systems in Nordic and UK operations to reduce on-site labor dependency, while securing long-term offtake agreements with Australian mining operators to defend against emerging regional competitors. Certification investment under EU Green Deal disclosure requirements represents a critical lever for margin protection. For New Entrants and Emerging Players: German hospital infrastructure backlogs represent the most penetrable entry point for modular clinical wing specialists lacking established energy sector relationships. New entrants should target Western Australian worker accommodation modules where climate-resilient rapid-deployment specifications create technical barriers that filter out conventional construction competitors. A design-build-operate contracting structure enables risk transfer capabilities that differentiate from component-only suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a manufacturing-capability consolidation play because factory automation subsidies in Japan and embodied carbon mandates in Europe structurally favor scaled producers over fragmented site-built competition. Acquisition targets should display integrated digital twin-to-fabrication workflows and established chemical management systems for REACH compliance. The signal to watch is building code harmonization progress between national jurisdictions, which would accelerate cross-border module certification and unlock factory utilization rate improvements.| Strategic Initiative | Industry Significance |
|---|---|
| Factory Automation Investment | Japan's METI subsidies lower capital barriers for timber and steel module producers seeking precision output. |
| Digital Twin Integration | BIM-to-CNC convergence enables mass customization without sacrificing throughput velocity for institutional buyers. |
| Cross-Laminated Timber Certification | EU Green Deal biogenic carbon storage preferences drive Bavarian timber engineering cluster expansion. |
| Design-Build-Operate Platform | Australian developers consolidate procurement around ten-year service agreements privileging regional maintenance networks. |
| Building Code Harmonization | National jurisdiction alignment affects cross-border module certification and factory utilization rates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs filings, factory utilization databases, and building code regulatory texts to validate market sizing. Primary interviews engaged fabrication plant managers, hospital procurement officers, mining sector project developers, and modular construction engineering leads across Germany, Australia, Japan, and the United States. Secondary sources included EU Green Deal implementation guidance, OSHA factory safety standard documentation, METI automation subsidy program filings, and Australian NCC energy efficiency provisions. Bottom-up capacity assessments triangulated against top-down construction spending allocations.
Forecast inputs span product type segmentation across modular buildings, prefabricated structures, portable cabins, and component sub-assemblies, with technology generation tracked through traditional assembly, automated manufacturing, robotics, and 3D printing deployment. End-use segmentation captures construction companies, real estate developers, government agencies, and educational institutions with divergent contracting structures. CAGRs derive from modeled capacity expansion timelines, regulatory implementation schedules, and substitution elasticity estimates for site-built construction across the analysis window. Industry-specific inputs include steel price volatility indices and labor scarcity metrics by national construction economy.
Practitioners should monitor steel input cost trajectories, building code harmonization negotiations, and factory automation subsidy program renewals for early signals of forecast deviation. Forecasts reflect assumptions regarding sustained EU Green Deal enforcement, continued Australian mining investment cycles, and stable METI industrial policy support. Material shifts in global scrap and hot-rolled coil pricing, abrupt regulatory rollback in embodied carbon disclosure, or major automation technology export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
Construction Market
Building Construction
Prefabricated Buildings Market
Building Construction
Vertical Garden Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
France Prefab Homes Market
Building Construction
Guatemala Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Energy-Efficient Building Market
Building Construction
Europe Modular Construction Market
Building Construction
Indonesia Construction Market
Building Construction
Spain Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
GCC Cement Market
Building Construction
France Prefab Wood Building Market
Building Construction
GCC Construction Market