
 Malaysia Construction Market | 2026-2036
Malaysia Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Construction Market Outlook
Industrial project pipelines is recalibrating the contractor order book mix across Peninsular Malaysia. Gamuda Berhad anchors its position through tunneling and mass rapid transit specialization. UEM Group Berhad leverages its government-linked project portfolio to sustain recurring infrastructure awards. IJM Corporation Berhad competes aggressively in highway concessions and port development.
Malaysia construction encompasses the planning, assembly, and commissioning of built structures using reinforced concrete frameworks, structural steel systems, and engineered timber composites for residential, commercial, and civil end uses. The sector delivers fixed capital assets that enable manufacturing, logistics, and urban habitation. Residential and infrastructure project types carry the deepest current backlog, while green building construction methods are attracting premium margin pools as energy compliance tightens. Precast methods are gaining share in high-rise residential towers where labor scarcity pressures traditional site-cast alternatives.
CIDB Malaysia enforces contractor grading and Industrialised Building System adoption thresholds that filter market access by technical capability. The Department of Standards Malaysia administers MS ISO standards for structural materials and green building certification that shape procurement specifications. Stakeholders must monitor how Bumiputera participation requirements and domestic content rules evolve in federal infrastructure tenders to align partnership structures and supply chain commitments.
Market Dynamics
CIDB Malaysia's Industrialised Building System mandates are compressing traditional contractor margins while elevating technically capable players. The Klang Valley infrastructure surge is redistributing project pipelines toward tunneling and mass transit specialization.
Growth Catalysts
- Mass Rapid Transit Expansion:The Klang Valley MRT line extensions are generating sustained demand for tunnel boring machinery and specialized civil engineering contracts across Kuala Lumpur and Selangor.
- CIDB Grading Thresholds:Malaysia's contractor classification system filters market access toward firms with proven IBS capability, concentrating awards among technically qualified bidders.
- Green Building Certification:MS ISO standards for energy compliance are driving premium specifications for low-carbon concrete and solar-integrated building envelopes in commercial towers.
Market Restraints
- Steel Price Volatility:Reinforcement bar costs fluctuate with regional mill capacity, squeezing fixed-price contract margins for mid-tier contractors without backward integration into steel trading.
- Foreign Labor Dependency:Construction sites rely on migrant workers from Bangladesh and Indonesia, exposing projects to visa policy shifts and remittance cost spikes.
- Cement Supply Concentration:Domestic clinker production clusters in Perak and Pahang, creating logistics bottlenecks for East Malaysia projects that must absorb barge and transshipment premiums.
Strategic Opportunities
- Iskandar Malaysia Corridor:Johor's special economic zone offers tax-advantaged project structures for Singapore-linked logistics and residential developments with cross-border capital flows.
- Digital Twin Integration:Building Information Modeling convergence with IoT sensors is enabling predictive maintenance contracts that extend contractor revenue streams post-handover.
- Bumiputera Partnership Models:Federal infrastructure tenders require domestic equity participation, creating JV structures that channel technical expertise through locally registered entities.
Industry Challenges
- Skilled Tunneling Engineer Scarcity:MRT and hydropower projects compete for a limited pool of geotechnical specialists certified in soft-ground excavation methods.
- IBS Component Standardization Lag:Precast concrete interoperability between Malaysian, Singaporean, and Thai suppliers remains unharmonized, complicating multi-source procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Construction Market |
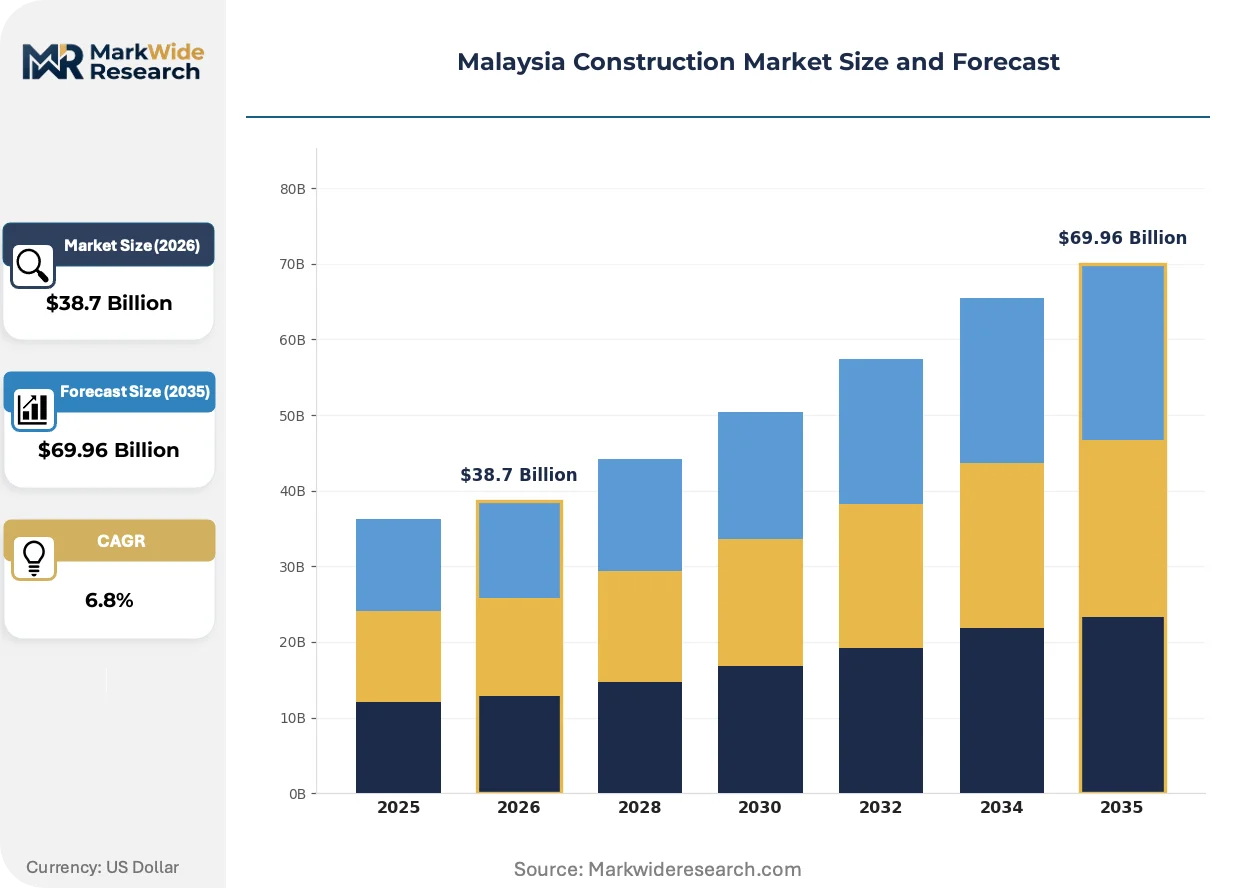
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Construction Method: Traditional, Modular, Precast, Green Building Material Type: Cement, Steel, Timber, Glass End User: Government, Developers, Contractors, Homeowners |
| Companies Covered | UEM Group Berhad, YTL Corporation Berhad, Gamuda Berhad, Ekovest Berhad, Malaysian Resources Corporation Berhad, IJM Corporation Berhad, WCT Holdings Berhad, Hock Seng Lee Berhad, Sunway Construction Group Berhad, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Construction Market Strategic Shifts
Construction methodology in Malaysia is pivoting from labor-intensive site casting toward factory-controlled production systems. Regulatory pressure and site productivity limits are accelerating technology adoption curves.
Prefabricated volumetric modules are electrifying high-rise residential delivery in the Klang Valley. Developers facing labor quota restrictions are specifying bathroom and kitchen pods manufactured in Selangor-based plants. This shift is compressing on-site construction schedules from 36 to 24 months for typical 40-storey towers.
CIDB Malaysia's phased IBS scoring requirements are tightening material traceability obligations. Contractors must now document precast component origin through digital chain-of-custody records. Steel-reinforced concrete suppliers in Penang and Johor are retrofitting plants with RFID tagging systems to maintain grading eligibility.
Penang's manufacturing base is pivoting contractor selection criteria toward energy performance guarantees. Electronics multinationals occupying Bayan Lepas industrial parks now specify chilled beam HVAC and photovoltaic-integrated roofing as standard lease conditions. Facility managers are unbundling traditional design-build contracts to retain independent commissioning agents who validate actual versus modeled consumption.
Malaysia Construction Market Segmentation
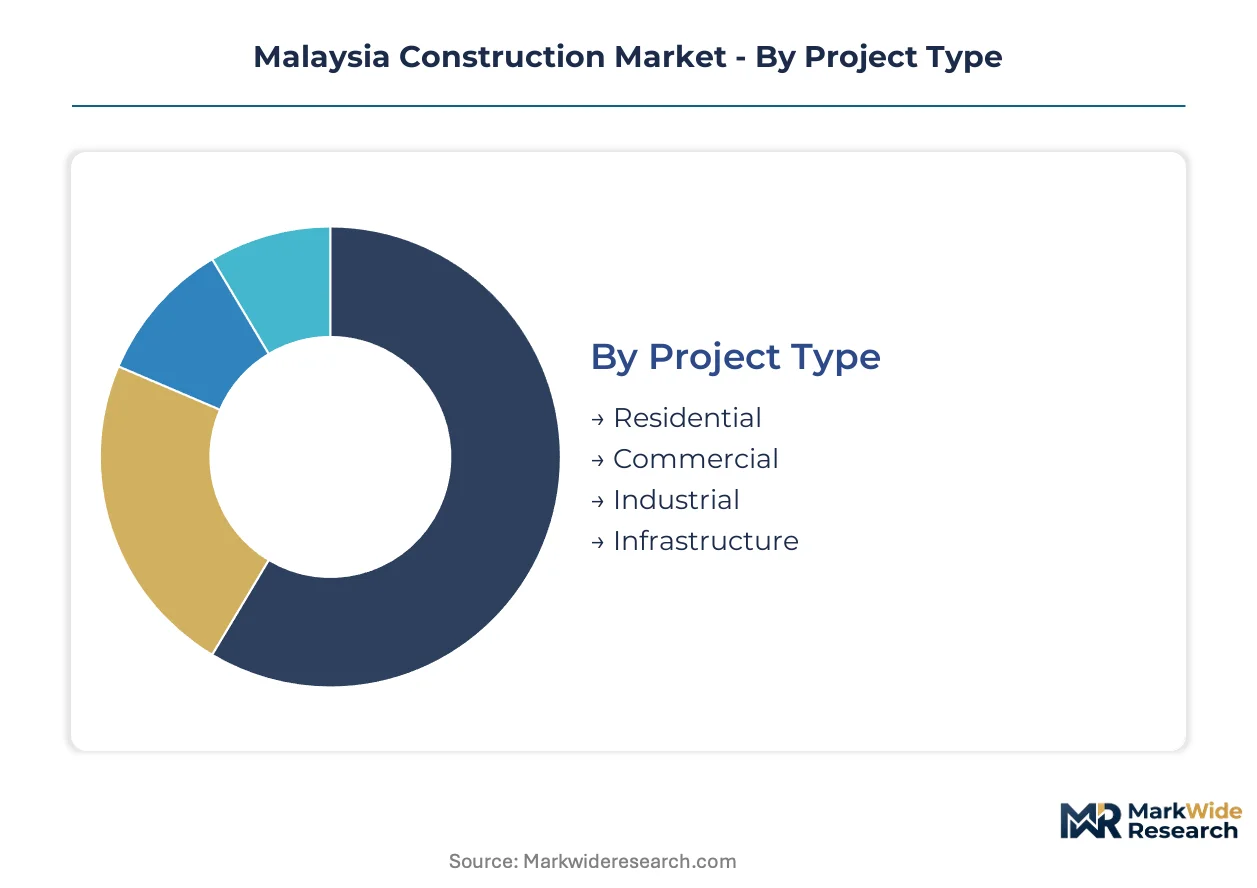
Malaysia's construction market fragments across project scale, technical methodology, material specifications, and procurement authority. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape contractor positioning and capital allocation priorities.
Project Type:
Standardization varies sharply across this category, from speculative residential towers with repeatable designs to bespoke infrastructure megaprojects requiring geotechnical customization.
- Residential:High-rise condominiums and landed housing estates dominate contractor backlogs in Selangor and Johor. Klang Valley land scarcity pushes developers toward vertical density, compressing per-unit construction timelines through IBS mandates.
- Infrastructure:MRT tunneling, highway extensions, and hydropower dams demand specialized civil engineering capabilities with decade-long revenue visibility. CIDB G7 grading thresholds filter awards toward technically qualified consortia with proven mass transit delivery records.
- Commercial:Office towers and retail complexes in Kuala Lumpur's Golden Triangle integrate green building certification as lease-competitive necessities.
- Industrial:Electronics manufacturing facilities in Penang and Bayan Lepas specify cleanroom-grade construction with stringent vibration control specifications.
Leading the category by volume: Residential. Expanding most quickly: Infrastructure.
Construction Method:
Cost tier stratification separates labor-intensive traditional approaches from capital-heavy industrialized alternatives with divergent break-even scales.
- Traditional:Site-cast concrete and manual steel fixing persist in smaller-scale projects across East Malaysia where IBS compliance thresholds remain lower. Labor quota dependencies expose margins to migrant worker visa volatility.
- Precast:Factory-manufactured structural elements reduce on-site labor headcount by 40% in typical Klang Valley high-rise deployments. Selangor-based precast plants face capacity constraints as CIDB scoring deadlines tighten.
- Modular:Volumetric bathroom and kitchen pods manufactured in Johor accelerate tower completion schedules for developers facing carrying cost pressure.
- Green Building:MS ISO energy compliance specifications command premium pricing in commercial segments where multinational tenants mandate carbon disclosure.
Dominant by project value: Precast. Steepest adoption trajectory: Green Building.
Material Type:
Supply concentration geography determines procurement risk exposure across this segmentation axis.
- Cement:Domestic clinker production clusters in Perak and Pahang, creating logistics premiums for East Malaysia projects dependent on barge transshipment through Port Klang.
- Steel:Reinforcement bar costs track regional mill capacity in Indonesia and Vietnam, squeezing fixed-price contract margins for contractors without captive trading operations.
- Timber:Engineered timber composites gain specification in low-rise commercial and institutional projects targeting biophilic design credentials.
- Glass:Curtain wall systems for Kuala Lumpur commercial towers source primarily from Thai and Chinese fabricators, exposing projects to currency hedging requirements.
Highest volume throughput: Cement. Fastest specification growth: Engineered timber.
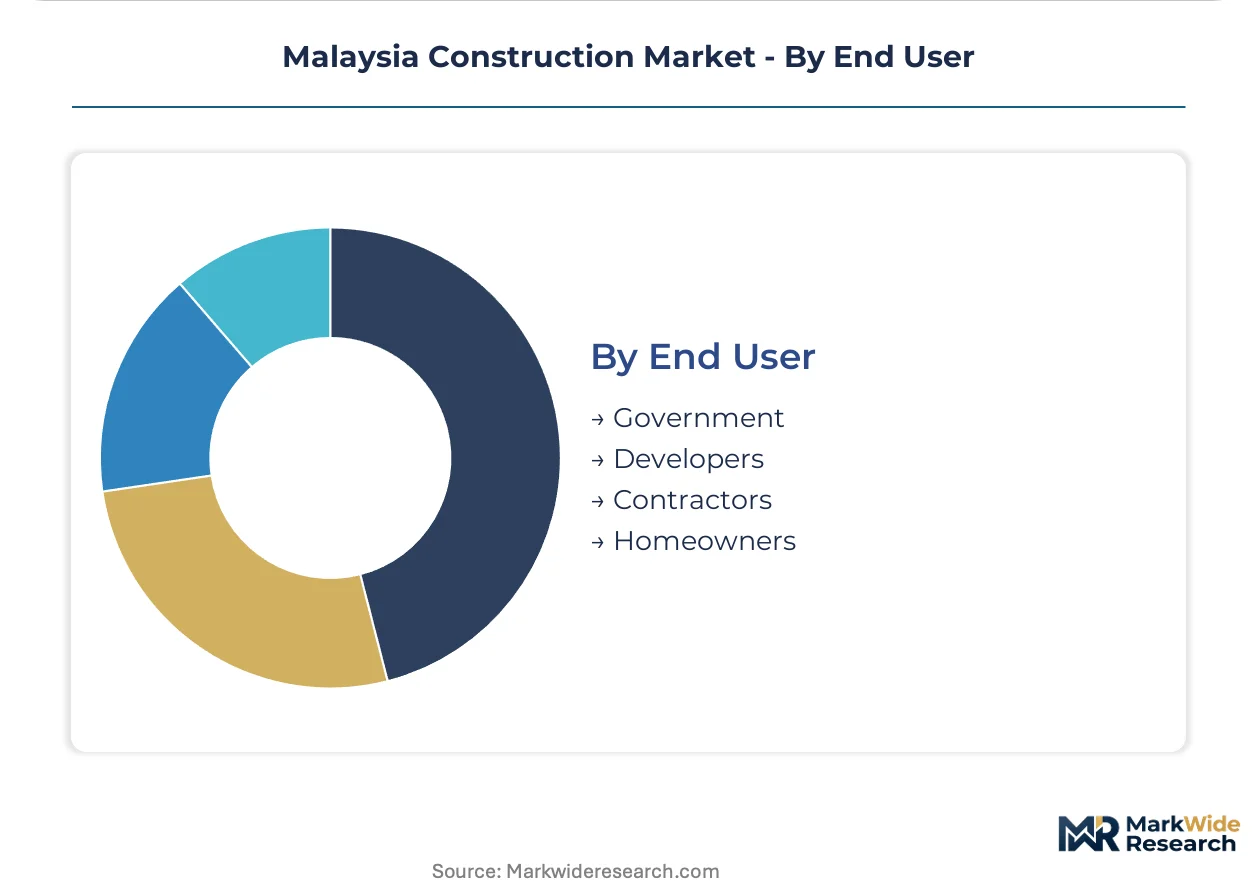
End User:
Procurement authority concentration shapes payment security and contract structure complexity across this final segmentation dimension.
- Government:Federal infrastructure tenders through CIDB channels mandate Bumiputera equity participation and domestic content verification. UEM Group and Gamuda anchor recurring award pipelines through government-linked enterprise relationships.
- Developers:Private sector residential and commercial sponsors in the Klang Valley prioritize speed-to-market over lowest-bid procurement, creating margin premiums for IBS-capable contractors.
- Contractors:Subcontracting tiers fragment risk across specialist trades including MEP, facade installation, and geotechnical works.
- Homeowners:Individual landed housing projects represent dispersed, low-scale demand concentrated in Selangor and Johor suburban corridors.
Largest contract value concentration: Government. Most price-sensitive segment: Homeowners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iskandar Malaysia anchors investment concentration through tax-advantaged structures attracting Singapore-linked capital flows. CIDB Malaysia enforces uniform grading standards nationwide while regional supply chains fragment across Peninsular and East Malaysia logistics corridors.
Selangor
Klang Valley infrastructure surge drives tunneling and mass transit specialization demand. CIDB G7 grading thresholds filter awards toward technically qualified consortia with proven delivery records. Petaling Jaya and Shah Alam host precast manufacturing clusters facing capacity constraints as IBS scoring deadlines tighten.
Kuala Lumpur
MRT line extensions generate sustained demand for tunnel boring machinery and specialized civil engineering contracts. MS ISO energy compliance specifications command premium pricing in commercial towers where multinational tenants mandate carbon disclosure. Golden Triangle office developments integrate green building certification as lease-competitive necessities.
Johor
Iskandar Malaysia special economic zone offers tax-advantaged project structures for logistics and residential developments. Bumiputera participation requirements in federal tenders shape JV partnership structures for cross-border capital flows. Johor Bahru-based plants manufacture volumetric bathroom and kitchen pods accelerating high-rise completion schedules.
Penang
Electronics manufacturing facilities in Bayan Lepas specify cleanroom-grade construction with stringent vibration control specifications. Energy performance guarantees now dominate contractor selection criteria for multinational electronics occupiers. Georgetown industrial parks mandate chilled beam HVAC and photovoltaic-integrated roofing as standard lease conditions.
Sarawak
Hydropower dams and rural infrastructure projects compete for limited geotechnical specialists certified in soft-ground excavation methods. Domestic clinker production logistics create barge and transshipment premiums for cement-dependent developments. Kuching construction sites rely on migrant worker pipelines exposed to visa policy volatility.
Malaysia Construction Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with government-linked enterprises dominating infrastructure awards while private developers prioritize IBS-capable technical partners. The vendor base concentrates around three tiers: G7-graded infrastructure specialists, mid-tier precast-integrated contractors, and regional subcontractors fragmenting risk across specialist trades. Two competitive moves define current positioning: strategic partnerships channeling foreign technical expertise through Bumiputera-registered JVs, and backward integration into captive precast manufacturing securing CIDB scoring compliance.
Among government-linked infrastructure anchors, UEM Group Berhad and Gamuda Berhad exemplify the G7-graded specialist archetype securing recurring federal awards through proven mass transit delivery records. IJM Corporation Berhad occupies a position representing the diversified contractor model competing across highway concessions and port development. These three entities anchor the competitive structure while mid-tier precast-integrated players and regional specialist subcontractors fragment the remaining award pipeline.
| Leading Market Players |
|---|
| UEM Group Berhad |
| YTL Corporation Berhad |
| Gamuda Berhad |
| Ekovest Berhad |
| Malaysian Resources Corporation Berhad |
| IJM Corporation Berhad |
| WCT Holdings Berhad |
| Hock Seng Lee Berhad |
| Sunway Construction Group Berhad |
| Others |
Value Chain & Pricing Dynamics
Reinforcement bar costs originating from Indonesian and Vietnamese regional mill capacity flow through three distinct pricing tiers downstream, with contractors lacking captive steel trading operations absorbing compressed margins on fixed-price federal infrastructure awards while G7-graded specialists command schedule premiums for MRT tunneling contracts.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent project schedules from standard procurement cycles, with CIDB G7-graded contractors extracting 15-20% premiums for guaranteed MRT line completion windows against spot-market mid-tier bidders competing on landed housing estates. Price differentiation hinges on IBS certification tier and Bumiputera partnership equity depth, with green building MS ISO compliance adding further margin layers. Pricing pressure stems from steel reinforcement bar volatility squeezing fixed-contract exposure. Government-linked developers show least price sensitivity; individual homeowners in Selangor suburban corridors exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with domestic clinker production clustering in Perak and Pahang, exposing East Malaysia projects to barge transshipment premiums through Port Klang. Cement, structural steel, and engineered timber composites draw from Indonesia, Vietnam, and Thailand respectively. Supply chain risk centers on migrant worker visa policy volatility disrupting site labor pipelines. Distribution runs through CIDB-registered contractor grading channels filtering market access by technical capability tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia construction operates as a supply-constrained market where precast manufacturing capacity shortages in Selangor and Johor prop pricing power for IBS-compliant contractors against traditional site-cast competitors.
For Market Incumbents: Extend backward integration into captive precast manufacturing plants in Shah Alam and Johor Bahru to secure CIDB scoring compliance against emerging mid-tier competitors. Anchor recurring revenue through predictive maintenance contracts leveraging Building Information Modeling convergence with IoT sensors, defending position against pure-play modular specialists.
For New Entrants and Emerging Players: Begin with volumetric bathroom and kitchen pod manufacturing for Klang Valley high-rise residential developers facing 36-to-24-month schedule compression mandates. Target Iskandar Malaysia logistics facilities requiring cleanroom-grade construction with less entrenched incumbent presence. Lead with Bumiputera JV structures channeling foreign technical expertise through locally registered entities.
For Investors and Strategic Acquirers: CIDB G7 grading threshold enforcement acceleration is the leading indicator that technical capability scarcity will concentrate award pipelines among proven mass transit delivery records. Position for 5-10 year infrastructure visibility through contractors with tunnel boring machinery specialization and government-linked enterprise relationships. Target acquisition archetype: mid-tier precast-integrated contractors with retrofit RFID tagging systems and Selangor plant assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precast Manufacturing | CIDB IBS scoring compliance secures eligibility for federal infrastructure tenders in Klang Valley. |
| Bumiputera Joint Venture Structuring | Domestic equity participation channels foreign technical expertise through locally registered entities. |
| Digital Twin Platform Development | BIM-IoT convergence enables predictive maintenance contracts extending revenue post-handover. |
| Green Building Certification Investment | MS ISO energy compliance specifications command premium pricing in Golden Triangle commercial towers. |
| Iskandar Malaysia Geographic Expansion | Tax-advantaged project structures attract Singapore-linked cross-border capital flows into Johor. |
Study Parameters
Multi-period observation of CIDB contractor grading distributions, IBS adoption rates, and MRT line extension award patterns anchored the trend analysis, supplemented by interviews with project directors at G7-graded infrastructure specialists, procurement leads at Selangor-based developers, precast plant operations managers, and federal tender evaluation committees. Secondary validation drew from CIDB annual reports, Department of Standards Malaysia MS ISO publications, customs cement and steel trade data, and Bumiputera equity participation filings. Bottom-up project pipeline aggregation triangulated against top-down construction value-add estimates from national accounts data.
Segment-weighting across project type, construction method, material specification, and procurement authority dimensions shaped the analytical framework, with residential, infrastructure, commercial, and industrial categories modeled separately throughout the forecast period. CAGRs derived from trend extrapolation of award volumes adjusted for regulatory compliance threshold phase-ins. Industry-specific inputs included CIDB IBS scoring deadline schedules and Klang Valley land scarcity trajectory.
Steel price volatility, migrant worker visa policy shifts, and cement logistics bottlenecks are the dominant revision risks that could compress or extend projected contractor margin trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Germany Prefabricated Buildings Market
Building Construction
India Commercial Construction Market
Building Construction
China Building Construction Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Sweden New Construction Market
Building Construction
Europe Prefab Wood Buildings Market
Building Construction
Guatemala Construction Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Egypt Residential Construction Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
Prefabricated Buildings Market
Building Construction
Construction Market
Building Construction
US Offsite Construction Market
Building Construction
UK Construction Market