
 India Prefabricated Buildings Market | 2026-2036
India Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
India Prefabricated Buildings Market Foresight
Multi-sourced procurement is pivoting toward integrated design-build contracts as Indian developers seek faster project delivery. Larsen & Toubro Limited anchors large-scale industrial prefab through its in-house engineering capabilities. EPACK Prefab specializes in modular commercial structures across northern India. Everest Industries Limited dominates panelized roofing and cladding systems for institutional buyers.
Prefabricated buildings are structural assemblies manufactured off-site under controlled conditions, with steel structures typically fabricated to IS 800 standards and modular units built for transport in standard truckable dimensions. Their primary purpose is compressing construction schedules while maintaining quality consistency across remote or labor-scarce sites. Steel structures command the largest product share due to seismic resilience requirements in high-risk zones, while modular construction methods attract the fastest growth as hospital and school projects adopt repeatable room pods. Government client contracts concentrate margin pools through scale-driven tenders, though developer demand is expanding fastest in tier-two cities.
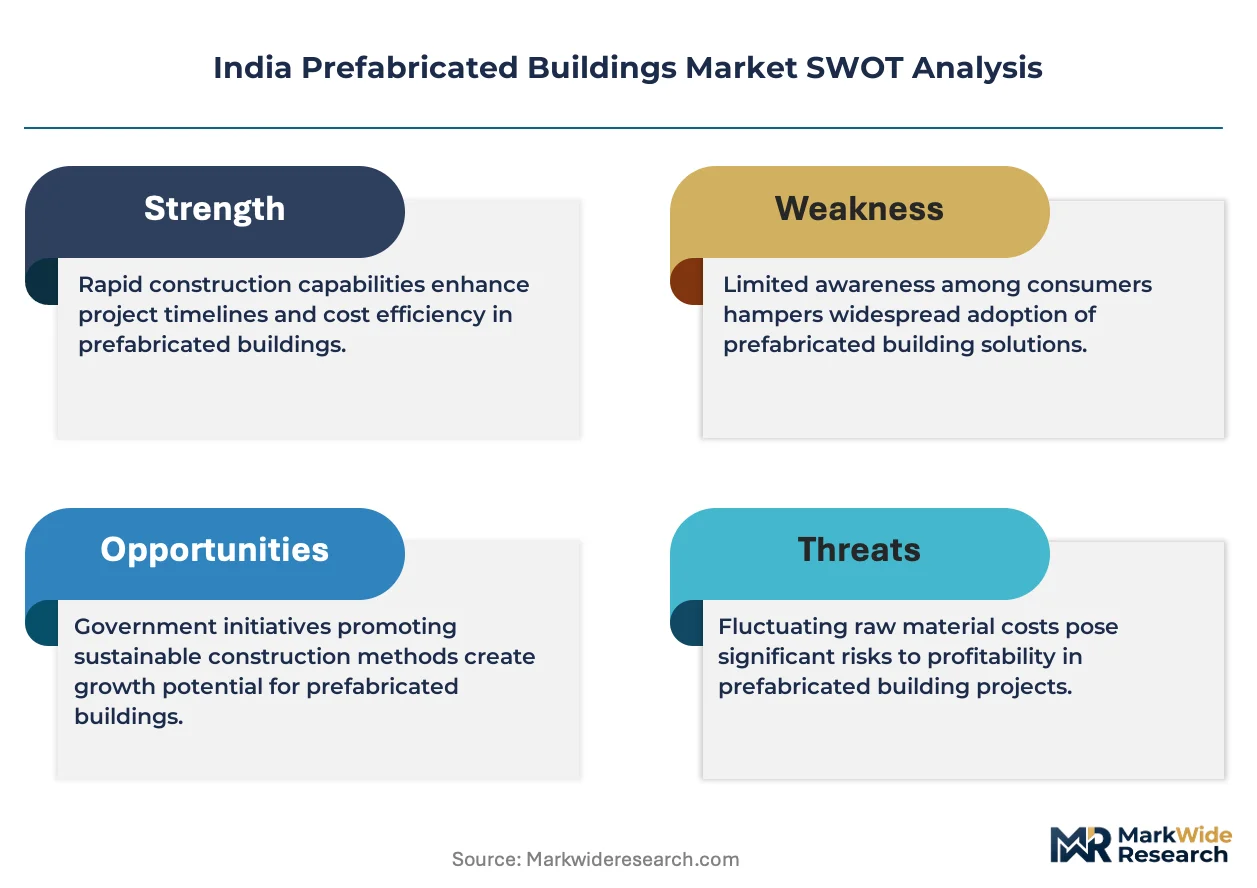
BIS mandates structural steel certification under IS 875 and IS 1893, while CEA guidelines enforce electrical safety in factory-assembled units, and state-level RERA authorities impose completion timelines that favor off-site methods. These frameworks collectively push conventional contractors toward certified prefab partners. Stakeholders must track how upcoming state affordable-housing mandates incorporate factory-built quotas into their technical specifications.
Market Dynamics
Integrated design-build contracts are compressing project timelines across India's affordable housing sector, with BIS certification mandates forcing conventional contractors toward factory-certified prefab partners.
Growth Catalysts
- BIS structural mandates:Certification requirements under IS 800 and IS 875 standards are disqualifying uncertified contractors from government tenders.
- Seismic zone construction:Steel prefab systems meet IS 1893 requirements in high-risk Himalayan and northeastern fault zones where conventional masonry fails.
- CEA electrical guidelines:Factory-assembled electrical systems bypass on-site inspection bottlenecks that delay hospital and school completions.
Market Restraints
- Hot-rolled steel price volatility:Input cost swings of 15-20 percent quarterly compress margins for fabricators locked into fixed-price government contracts.
- Specialized welding labor scarcity:IS-certified structural welders concentrate in Maharashtra and Gujarat, limiting expansion capacity elsewhere.
- Transport dimension limits:Standard truckable widths cap modular room pods at 3.5 meters, forcing design compromises for institutional corridors.
Strategic Opportunities
- Tier-two city hospital expansion:State health departments in Madhya Pradesh and Rajasthan are issuing design-build tenders for 100-bed modular facilities.
- PLI scheme alignment:Domestic steel fabrication incentives reduce landed cost gaps against Chinese panel imports for certified producers.
- RERA timeline compression:Maharashtra and Karnataka authorities are shortening completion windows to 24 months, favoring off-site methods.
Industry Challenges
- IS 800 welding certification backlog:Bureau of Indian Standards inspector capacity constraints delay factory approvals by 8-12 weeks.
- On-site integration complexity:Foundation tolerance mismatches between cast-in-situ bases and steel frame anchor bolts require costly field adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Prefabricated Buildings Market |
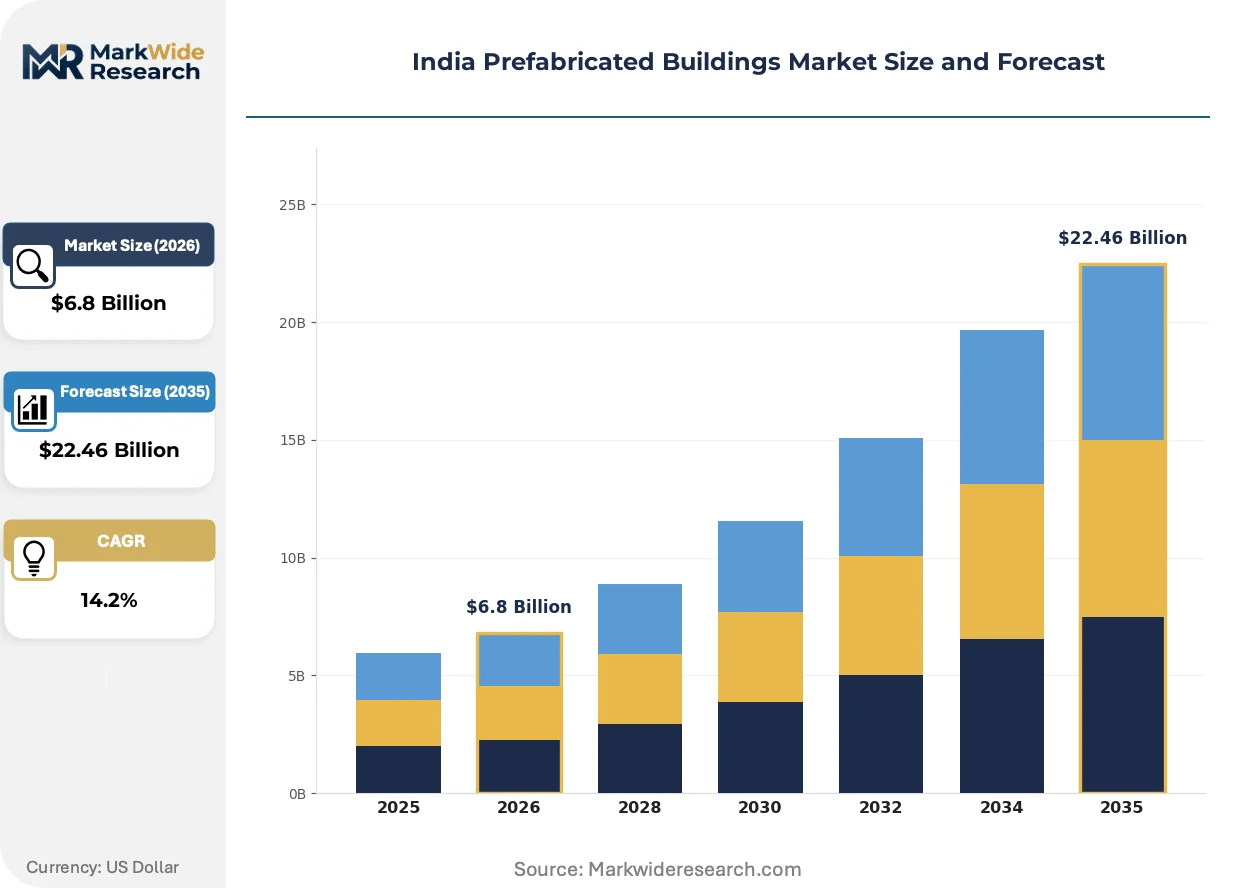
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Structures, Concrete Panels, Wooden Frames, Modules Application: Residential, Commercial, Industrial, Retail Construction Method: Modular, Panelized, Hybrid, Off-site Client Type: Government, Developers, Contractors, Individuals |
| Companies Covered | Pennar Industries Limited, Darshan Steel Infrastructure, Larsen & Toubro Limited, Alliance Integrated Metaliks Limited, Bajaj Steel Industries Limited, EPACK Prefab, Everest Industries Limited, Multi Arch Structures Private Limited, Interarch Building Solutions Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Prefabricated Buildings Market Shifts & Advancements
Digital fabrication and regulatory digitization are converging to compress design-to-occupancy cycles, while procurement authority consolidates among integrated developers.
BIM-to-fabrication workflows are unifying structural steel detailing with CNC plasma cutting systems. Large affordable housing developers in NCR and Mumbai MMR are mandating BIM deliverables for all tenders above 500 units. This unifying technology is collapsing rework rates from 8 percent to under 2 percent by eliminating dimensional drift between design intent and factory output.
State RERA authorities are digitizing completion certificate workflows. Maharashtra's MahaRERA portal now accepts factory inspection reports as equivalent to progressive on-site checks. Institutional buyers in the education sector are restructuring payment milestones around factory dispatch rather than civil milestone completion.
Consolidated procurement authority is shifting from fragmented contractor networks to single-source design-build entities. Tier-two city developers in Indore, Surat, and Lucknow are awarding turnkey contracts to prefab specialists rather than managing civil and MEP contractors separately. This concentration is most visible in mid-rise residential projects where speed-to-market determines financing viability.
India Prefabricated Buildings Market Segmentation
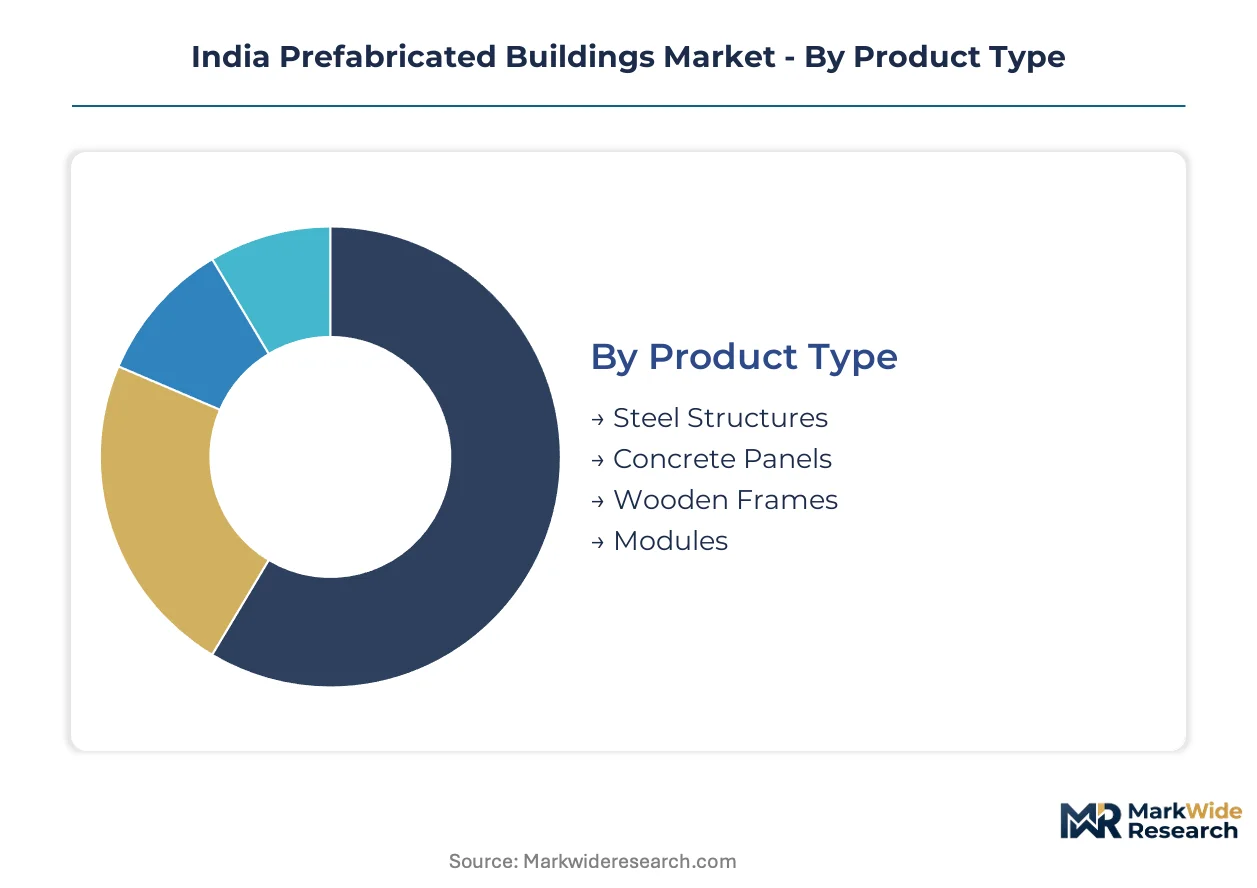
Product architecture, application intensity, construction methodology, and procurement authority each create distinct margin profiles and capability requirements for prefab suppliers. Buyers prioritize seismic resilience in high-risk zones, speed-to-market in urban infill, and cost certainty in government tenders.
Product Type:
Material selection hinges on structural load requirements, seismic zone classification, and transport logistics rather than unit cost alone.
- Steel Structures:Hot-rolled and cold-formed sections fabricated to IS 800 standards dominate multi-story institutional projects. Maharashtra and Gujarat developers specify steel frames for 8-12 story affordable housing blocks where IS 1893 seismic compliance is mandatory.
- Concrete Panels:Precast wall and floor systems deliver thermal mass advantages for climate-responsive design. Rajasthan and Madhya Pradesh state health departments specify concrete panel construction for 100-bed modular hospitals requiring fire resistance ratings.
- Wooden Frames:Engineered timber and bamboo composites serve low-rise residential and eco-tourism applications in Kerala and Uttarakhand where seismic risk is moderate and aesthetic integration matters.
- Modules:Fully fitted room pods integrate MEP rough-ins at factory. Hospital and school projects in tier-two cities adopt repeatable bathroom and patient room modules to compress commissioning schedules.
Steel structures lead on scale; modules lead on momentum.
Application:
End-use intensity determines specification grade, certification depth, and payment milestone structure across the project lifecycle.
- Residential:Affordable housing dominates volume, with PMAY-Urban projects in NCR and Mumbai MMR specifying panelized construction for 500-unit minimum tenders. RERA timeline compression favors off-site methods.
- Commercial:IT parks and co-working spaces in Bengaluru and Hyderabad demand 3.5-meter clear spans and flexible floor plates. Developers specify hybrid steel-concrete systems for speed-to-occupancy.
- Industrial:Warehousing and manufacturing facilities prioritize wide clear spans and crane loading capacity. Gujarat industrial corridor projects specify portal frame steel buildings for rapid deployment.
- Retail:Quick-service restaurants and convenience stores adopt compact modular units for highway and township locations. Franchise operators value factory-controlled branding consistency.
Residential commands absolute volume; commercial offers the steepest expansion trajectory.
Construction Method:
Method selection trades transport efficiency against on-site integration complexity, with regulatory acceptance varying by state RERA authority.
- Modular:Volumetric units arrive 90-95% complete, minimizing site labor. Hospital projects in Lucknow and Indore specify modular patient wards for 24-month completion mandates.
- Panelized:Flat-packed wall and floor panels maximize transport density. Affordable housing developers in Surat prefer panelized systems for mid-rise construction with local civil contractor integration.
- Hybrid:Combines steel frames with panelized infill for architectural flexibility. Institutional buyers in Karnataka specify hybrid systems for campus expansion projects.
- Off-site:Broad category encompassing precast and prefabricated elements fabricated under factory control. BIS certification mandates are accelerating off-site adoption across all government tenders.
Panelized systems lead on current deployment scale; modular construction gains share fastest as healthcare and education sectors standardize.
Client Type:
Procurement authority concentration shapes contract structure, margin pool distribution, and technical specification rigor.
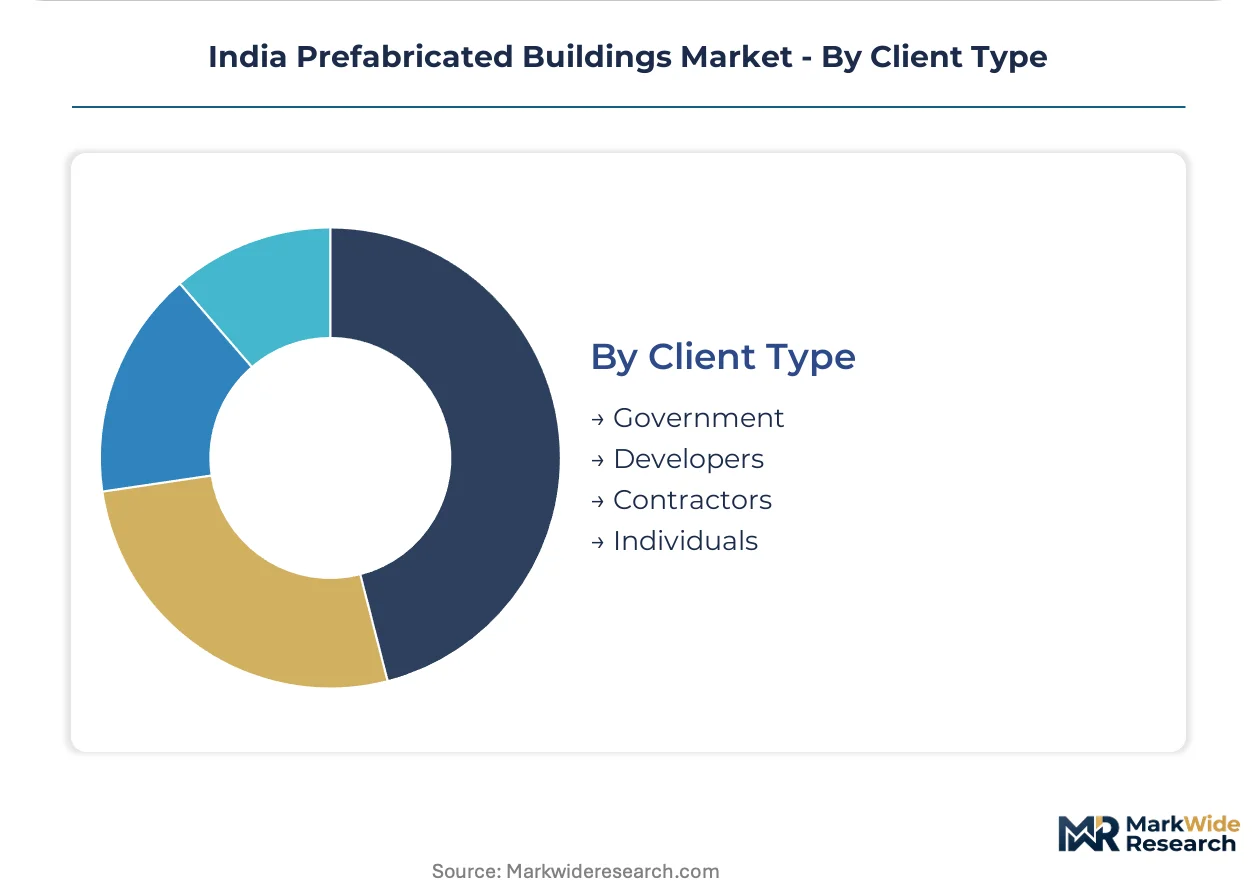
- Government:Central and state agencies drive scale through design-build tenders. PMAY-Urban and state health department contracts specify BIS-certified fabrication with milestone payments tied to factory dispatch.
- Developers:Integrated real estate companies in tier-two cities are consolidating procurement authority under single-source design-build contracts. Financing viability depends on speed-to-market execution.
- Contractors:Traditional civil contractors are partnering with certified prefab fabricators to meet RERA timelines. IS 800 welding certification requirements favor established steel specialists.
- Individuals:Farmhouses, weekend homes, and rural housing represent fragmented demand. Kerala and Himachal Pradesh see individual adoption of wooden frame and light gauge steel systems for remote sites.
Government contracts anchor revenue concentration; developer demand is climbing the fastest as tier-two urbanization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between states with streamlined BIS approval processes and those with inspector bottlenecks are redistributing fabrication capacity toward Maharashtra and Gujarat. Factory certification timelines vary by 8-12 weeks across state boundaries, creating arbitrage opportunities for mobile production assets.
Maharashtra
PMAY-Urban projects in Mumbai MMR and Pune drive demand for 500-unit affordable housing tenders. MahaRERA's digitized completion certificate workflows accept factory inspection reports as equivalent to on-site checks. Thane and Nashik industrial corridors host concentrated steel fabrication clusters serving western India.
Gujarat
Industrial warehousing and manufacturing facilities along the Delhi-Mumbai Industrial Corridor specify portal frame steel buildings for rapid deployment. State urban development authorities enforce 24-month RERA completion windows that favor off-site methods. Ahmedabad and Surat anchor the highest density of IS 800-certified welding capacity in India.
Karnataka
IT parks and co-working spaces in Bengaluru demand hybrid steel-concrete systems with 3.5-meter clear spans. State RERA authorities are shortening completion timelines, compressing developer procurement decisions. The Bengaluru-Tumkur industrial belt concentrates panelized system fabricators serving southern markets.
Telangana
State health department tenders for 100-bed modular hospitals in tier-two cities specify repeatable room pods. CEA electrical guidelines for factory-assembled systems bypass on-site inspection bottlenecks. Hyderabad's pharmaceutical and life sciences corridor generates parallel demand for cleanroom-compatible modular construction.
Tamil Nadu
Educational infrastructure expansion in Chennai and Coimbatore adopts panelized systems for campus projects. State public works department contracts increasingly specify BIS-certified fabrication with milestone payments tied to factory dispatch. Sriperumbudur and Oragadam industrial zones host emerging steel fabrication capacity serving southeastern markets.
India Prefabricated Buildings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized modular applications and tier-two city penetration. The market structures around three capability tiers: integrated engineering-construction conglomerates with in-house fabrication, dedicated prefab specialists with certified welding capacity, and regional panel assemblers serving local developer networks. Dominant competitive moves include design-build contract consolidation and backward integration into steel rolling to hedge input cost volatility.
Among diversified engineering conglomerates, Larsen & Toubro Limited anchors large-scale industrial prefab through captive engineering capabilities. Everest Industries Limited occupies a position within the panelized roofing and cladding segment for institutional buyers. EPACK Prefab exemplifies the modular commercial specialist archetype concentrated in northern Indian markets. These three represent distinct strategic postures: full vertical integration, component specialization, and regional module assembly.
| Leading Market Players |
|---|
| Pennar Industries Limited |
| Darshan Steel Infrastructure |
| Larsen & Toubro Limited |
| Alliance Integrated Metaliks Limited |
| Bajaj Steel Industries Limited |
| EPACK Prefab |
| Everest Industries Limited |
| Multi Arch Structures Private Limited |
| Interarch Building Solutions Limited |
| Others |
Supply & Pricing Matrix
IS 800-certified structural welders concentrated in Maharashtra and Gujarat create labor-cost differentials that widen pricing-tier spreads between certified factory-built systems and uncertified on-site construction across India's tier-two markets.
Pricing Analysis
Distributor margins on steel prefab systems compress as direct-to-developer contracts expand. Project-based pricing stratifies across BIS-certified premium tiers, standard IS 800-compliant mid-tiers, and uncertified economy alternatives. Price differentiation hinges on welding certification grade and seismic zone compliance requirements. Cost compression in economy-tier panel systems intensifies as Chinese imports undercut domestic fabricators. Government tenders show lowest price sensitivity; individual farmhouse buyers exhibit highest.
Supply Chain Analysis
Freight costs from Maharashtra and Gujarat fabrication clusters to Madhya Pradesh and Rajasthan project sites add 8-12 percent to delivered steel frame costs. Supply concentrates in India for structural steel fabrication, with China supplying secondary panel components. Raw material dependencies center on hot-rolled steel coils, zinc-aluminum coating inputs, and IS-certified welding consumables. Single-source vulnerability runs through Maharashtra's concentrated BIS inspector capacity. Distribution runs through design-build contractors consolidating procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Prefabricated Buildings Market functions as a geographic-arbitrage play where BIS certification timelines vary 8-12 weeks across state boundaries, rewarding mobile production assets that relocate to inspector-uncongested jurisdictions.
For Market Incumbents: To counter emerging modular specialists in tier-two hospital segments, anchor market position through backward integration into hot-rolled steel rolling and captive IS 800 welding academies. Lock in government tender pipelines by pre-certifying factory capacity across multiple state RERA jurisdictions. For New Entrants and Emerging Players: Capture white-space in 100-bed modular hospital projects across Madhya Pradesh and Rajasthan where design-build procurement is consolidating. Target panelized affordable housing in Surat and Indore where speed-to-market financing drives developer decisions. Lead with BIM-to-fabrication workflows as the go-to-market differentiator. For Investors and Strategic Acquirers: Integrated engineering-construction conglomerates are the most active acquirer in this space, seeking certified welding capacity and state-level BIS approvals. Over the long-term viability window, acquisition targets center on regional fabricators with Maharashtra or Gujarat welding certification and established state health department relationships. Watch for PLI scheme domestic steel incentive announcements as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Rolling | Captive hot-rolled coil supply hedges quarterly price volatility affecting government contract margins. |
| BIM-to-Fabrication Workflow Deployment | CNC plasma cutting integration collapses rework rates for affordable housing developers above 500 units. |
| Multi-State BIS Certification Expansion | Factory approvals across Maharashtra, Gujarat, and Karnataka unlock geographic arbitrage on inspector bottlenecks. |
| Design-Build Contract Consolidation | Single-source procurement authority captures margin pools shifting from fragmented civil-MEP contractor networks. |
| IS 800 Welding Academy Investment | Certified labor pipelines address scarcity constraining expansion beyond Maharashtra and Gujarat clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged prefab fabrication plant managers, state health department procurement officers, affordable housing developer project directors, and BIS certification inspectors. Secondary validation drew from BIS standard publications, state RERA regulatory filings, PLI scheme administrative documents, and steel trade association production data. Bottom-up project pipeline aggregation and top-down construction sector sizing were triangulated for coherence.
Historical reference periods anchored volume and value trajectories across the modeling period. Segmentation dimensions spanned product architecture, construction methodology, application intensity, and procurement authority concentration. CAGRs were derived from regression-adjusted trend extrapolation. Industry-specific forecast inputs incorporated state affordable housing mandate implementation schedules and BIS inspector capacity expansion plans.
Underlying measurement precision varies by segment; government tender pipelines carry tighter precision than fragmented individual farmhouse demand. Forecasts reflect assumptions on RERA timeline enforcement consistency and PLI scheme continuation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
South Africa Prefabricated Buildings Market
Building Construction
Indonesia Infrastructure Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
Spain Construction Market
Building Construction
US Modular Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
Europe Prefab Wood Buildings Market
Building Construction
Guatemala Construction Market
Building Construction
Kuwait Construction Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
Prefabricated Construction Market
Building Construction
India Construction Market
Building Construction
US Prefabricated Buildings Market