
 South America Swine Feed Market | 2026-2036
South America Swine Feed Market Size, Share, and Industry Trends Forecast 2026-2036
South America Swine Feed Market Analytics
The capital-intensity divergence between integrated multinationals and regional blenders is unwinding competitive stability across the South America swine feed landscape. Cargill Incorporated leverages its captive soybean processing network to anchor margin control from oilseed crush through finished feed delivery. BRF Global sustains formulation leadership through in-house veterinary R&D pipelines tied to its integrated pork production system. De Heus Animal Nutrition competes via localized mill infrastructure that reduces last-mile logistics costs for midsize commercial farms.
South America swine feed encompasses nutritionally complete rations, concentrates, supplements, and functional additives formulated to meet the metabolic requirements of swine across gestation, nursery, grower, and finisher phases, typically comprising processed grains, oilseed meals, amino acid fortifiers, and enzyme preparations manufactured through extrusion, pelleting, or mash blending. Complete Feed occupies the dominant value share as commercial farms in Brazil and Argentina outsource total diet responsibility to millers rather than mixing on-farm. Custom Blends within formulation types represent the fastest-growing margin pool, driven by corporate producers seeking phase-specific diets calibrated to genetic line performance targets. Direct Sales channels control the largest volume flow, though Agricultural Co-ops are gaining ground among backyard farms transitioning toward semi-commercial scale.
Brazil's MAPA, Argentina's SENASA, and Colombia's ICA collectively enforce feed safety standards that shape ingredient sourcing decisions and mill certification requirements across national borders. ANVISA in Brazil and equivalent national pharmaceutical regulators elsewhere govern antibiotic growth promoter restrictions that redirect formulation investment toward acidifiers, phytogenics, and probiotic alternatives. Stakeholders must monitor the divergence between Mercosur harmonization talks and unilateral national mycotoxin protocols when allocating capital across cross-border milling assets.
Market Dynamics
Brazil's MAPA enforcement of tighter mycotoxin thresholds is forcing feed millers to rebuild ingredient sourcing infrastructure and accelerate on-site quality testing investments.
Growth Catalysts
- Integrated Production Systems:Commercial farms across Santa Catarina and Rio Grande do Sul are consolidating feed-milling capacity within pork production complexes, reducing logistics friction and ingredient spoilage.
- ANVISA Antibiotic Restrictions:Brazil's pharmaceutical regulator is redirecting formulation R&D toward acidifiers, phytogenics, and probiotic alternatives, opening margin pools in functional additive categories.
- Argentina's SENASA Certification Alignment:Cross-border harmonization of feed safety protocols is enabling Argentine millers to supply Brazilian integrated producers under unified quality standards.
Market Restraints
- Soybean Meal Price Volatility:Argentine crushing capacity constraints and currency instability transmit input cost shocks directly into finished feed pricing.
- Mercosur Regulatory Divergence:Unilateral national mycotoxin protocols in Brazil, Argentina, and Colombia fragment cross-border sourcing strategies and complicate mill network planning.
- Concentrate Import Dependency:Domestic amino acid and vitamin premix production remains underdeveloped, exposing formulators to currency-driven supply interruptions.
Strategic Opportunities
- Colombian Commercial Farm Transition:Backyard operations in Antioquia and Valle del Cauca are scaling toward semi-commercial status, creating first-mover advantages for localized mill infrastructure.
- Custom Blend Formulation Services:Phase-specific diets calibrated to genetic line performance targets represent an underexploited margin pool for nutrition service providers.
- Agricultural Co-op Channel Development:Cooperative purchasing structures in southern Brazil and eastern Argentina are consolidating fragmented demand into contractible volume blocks.
Industry Challenges
- Feed Safety Technician Shortage:Qualified mycotoxin analysts and quality assurance specialists remain scarce across Brazilian milling operations, extending certification timelines.
- Legacy ERP Integration:Midscale Argentine millers struggle to connect formulation software with traceability systems required for SENASA compliance reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Swine Feed Market |
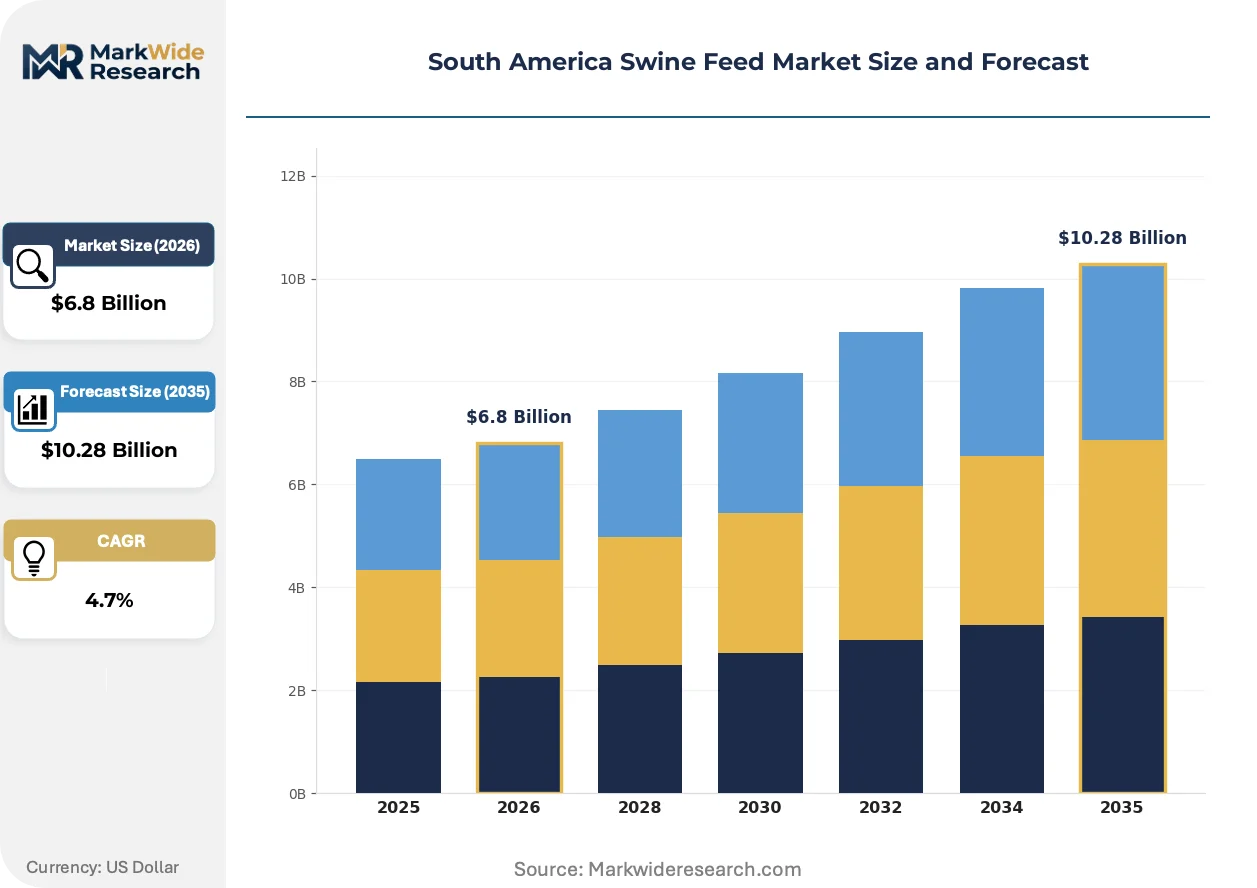
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Concentrated Feed, Supplements, Additives Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Agricultural Co-ops Formulation Type: Standard Formulation, Organic Formulation, Custom Blends, High-Protein End User: Commercial Farms, Backyard Farms, Corporate Producers, Breeding Operations |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, BRF Global, SHV Holdings, De Heus Animal Nutrition, Charoen Pokphand Group, New Hope Group, Alltech Inc., CJ Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Swine Feed Market Evolving Landscape
Digital feed formulation platforms and precision nutrition protocols are compressing the gap between genetic potential and realized performance in commercial pork operations.
Near-infrared spectroscopy for real-time ingredient analysis is miniaturizing quality control infrastructure. Integrated producers in Brazil's southern pork belt are deploying portable NIR units at receiving bays to reject contaminated shipments before unloading. This technology is miniaturizing capital requirements for on-site testing, enabling midsize farms to bypass centralized laboratory dependencies.
ANVISA's progressive tightening of antibiotic growth promoter approvals is restructuring additive portfolios across Brazilian formulation houses. Acidifier and probiotic suppliers are capturing formulation slots previously occupied by pharmacological growth enhancers. Southern Brazilian integrated producers are responding fastest, driven by export market access requirements from EU and Asian buyers.
Corporate procurement teams at large integrated operations are consolidating supplier relationships around full-service nutrition partners capable of delivering phase-specific diets. Traditional commodity feed transactions are yielding to long-term formulation service contracts with embedded technical support. This pattern concentrates most visibly among Santa Catarina-based producers supplying export-oriented pork processors.
South America Swine Feed Market Segmentation
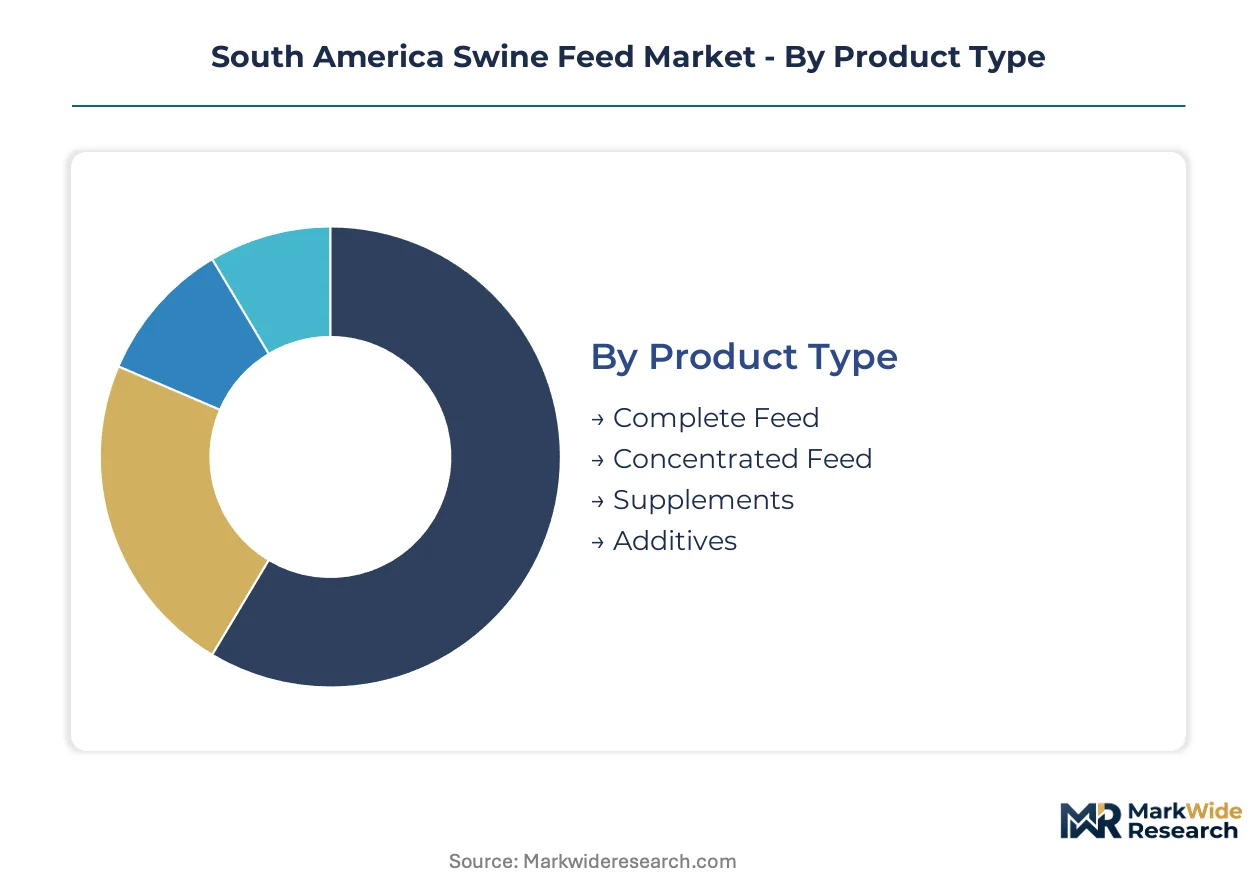
Segmentation in South America swine feed reveals how product flows align with farm scale and procurement sophistication. Channel selection directly determines margin capture for millers and cost structure for end users across Brazil, Argentina, and Colombia.
Product Type:
Channel-mix patterns show complete feed dominating direct sales to commercial farms, while concentrates and supplements flow through agricultural co-ops serving smaller operations.
- Complete Feed:Nutritionally balanced rations containing processed grains, oilseed meals, and micronutrients in single-package form ready for immediate consumption. Demand concentrates among Santa Catarina and Rio Grande do Sul integrated producers who outsource total diet responsibility to eliminate on-farm mixing labor and quality risk.
- Concentrated Feed:Protein-dense formulations requiring grain dilution at the farm level, typically 15-40% inclusion rates. Backyard farms in Colombia's Antioquia department favor this format through co-op purchasing to reduce capital tied up in feed inventory.
- Supplements:Vitamin-mineral premixes and amino acid fortifiers added to base rations. Argentine commercial farms source these through specialty stores to customize diets for specific genetic lines.
- Additives:Functional ingredients including acidifiers, phytogenics, enzymes, and probiotics. ANVISA antibiotic restrictions are redirecting formulation investment toward this category as growth promoter replacements.
By volume, Complete Feed leads. By growth pace, Additives is expanding most quickly.
Distribution Channel:
Cost tier differentiation separates premium technical service channels from commodity volume routes, with direct sales commanding formulation customization premiums.
- Direct Sales:Mill-to-farm contractual relationships with embedded nutrition consulting and delivery logistics. Corporate producers across Brazil's southern pork belt consolidate procurement through this channel to secure phase-specific diet calibration and quality traceability.
- Agricultural Co-ops:Member-owned purchasing cooperatives aggregating fragmented demand into volume blocks. Eastern Argentine and southern Brazilian backyard farms transitioning toward semi-commercial scale rely on co-ops to access pricing power previously reserved for large integrated operations.
- Specialty Stores:Regional feed retailers offering standard formulations and supplement components. Midsize commercial farms in Colombia's Valle del Cauca use this channel for emergency restocking and diet experimentation before committing to direct mill contracts.
- Online Retail:Digital platforms enabling price comparison and scheduled delivery of packaged feed products. Urban-proximate hobby farms in São Paulo state and Buenos Aires province represent the primary addressable base for this emerging channel.
Direct Sales captures the largest revenue pool. Agricultural Co-ops are gaining share fastest among transitioning operations.
Formulation Type:
Application-specific requirements drive formulation selection, with genetic performance targets and export market access requirements determining premium willingness.
- Custom Blends:Phase-specific diets calibrated to nursery, grower, finisher, and gestation metabolic requirements tied to genetic line performance curves. BRF Global and similar integrated producers in Santa Catarina specify these formulations to maximize feed conversion ratios for EU and Asian export qualification.
- Standard Formulation:Generic rations meeting baseline nutritional specifications without genetic line optimization. Cost-sensitive backyard farms across Colombia and northeastern Brazil default to this category, accepting performance trade-offs for procurement simplicity.
- Organic Formulation:Certified feed products excluding synthetic additives and genetically modified ingredients. Niche demand from specialty pork processors in Argentina's Buenos Aires province and Brazil's organic-certified export channels.
- High-Protein:Elevated amino acid density formulations for accelerated lean tissue deposition. Breeding operations and show hog producers in southern Brazil utilize this category for genetic stock development.
Standard Formulation dominates volume throughput. Custom Blends commands the steepest expansion trajectory as genetic specialization intensifies.
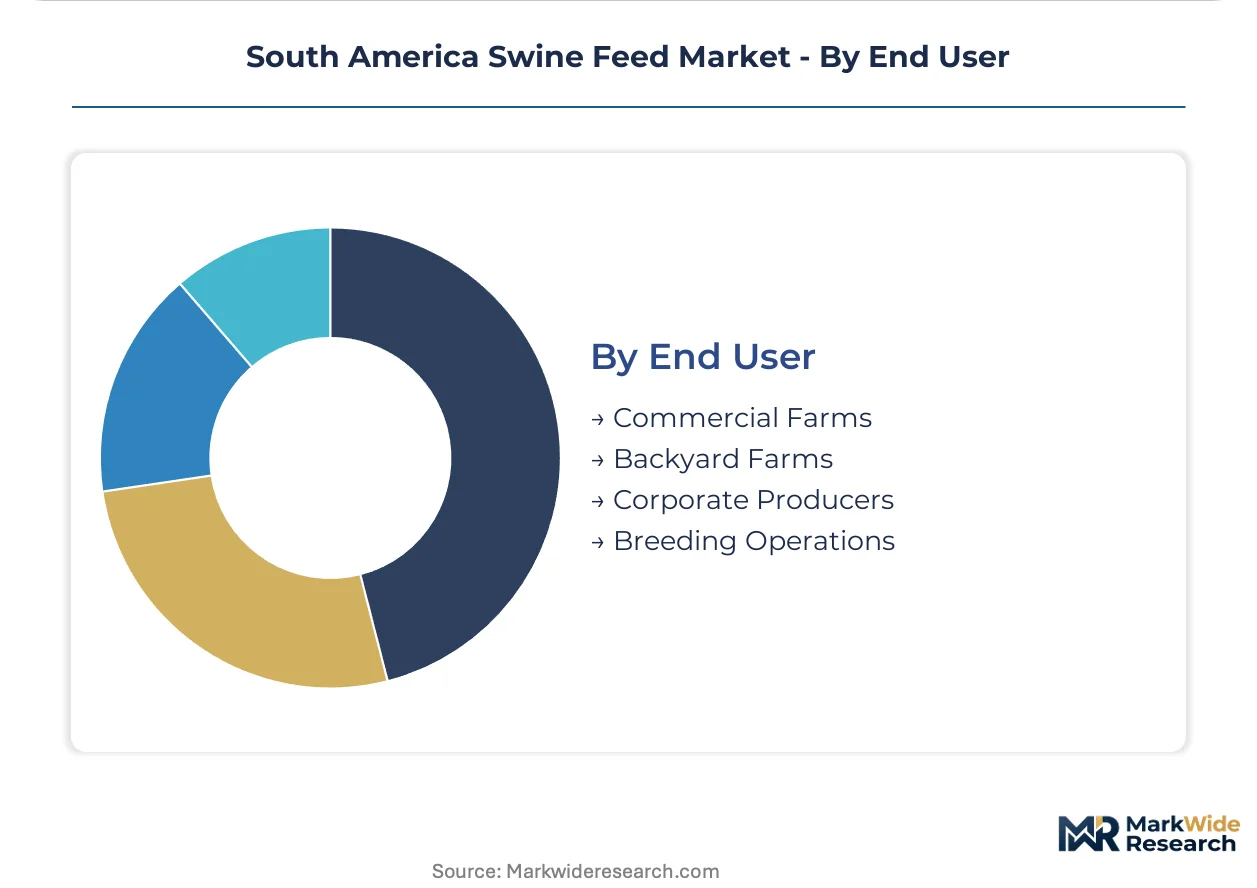
End User:
Customer type segmentation reveals diverging service intensity requirements, with corporate producers demanding full nutrition partnerships and backyard farms prioritizing price accessibility.
- Commercial Farms:Professionally managed operations with dedicated nutrition staff and quality control infrastructure. Rio Grande do Sul and Santa Catarina operations in the 500-5,000 sow range represent the core demand base for complete feed and custom formulation services.
- Corporate Producers:Vertically integrated pork production systems with captive feed milling or exclusive mill partnerships. These entities specify formulation parameters directly and capture margin through supply chain control rather than third-party procurement.
- Backyard Farms:Small-scale operations with fewer than 50 sows, often family-managed with limited technical capacity. Colombia's Antioquia and Valle del Cauca regions contain concentrated populations transitioning toward semi-commercial scale.
- Breeding Operations:Genetic multiplier farms and nucleus herds requiring specialized gestation and lactation nutrition. These facilities in Argentina's Córdoba province and Brazil's Paraná state prioritize reproductive performance over growth rate optimization.
Commercial Farms absorb the largest feed tonnage. Corporate Producers are climbing the fastest as consolidation accelerates across the southern cone.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing power through integrated southern pork complexes while Argentine millers absorb currency-driven input cost volatility. This asymmetry structures cross-border trade flows and investment allocation across the continent.
Brazil
Santa Catarina and Rio Grande do Sul integrated producers drive complete feed demand through captive milling capacity. MAPA enforces stricter mycotoxin thresholds that force ingredient sourcing infrastructure rebuilds. On-site quality testing investments accelerate across receiving bays from Chapecó to Pelotas.
Argentina
SENASA certification alignment enables Argentine millers to supply Brazilian integrated producers under unified quality standards. Currency instability transmits soybean meal price shocks directly into finished feed pricing. Córdoba province breeding operations prioritize reproductive performance formulations for genetic multiplier herds.
Colombia
Backyard operations in Antioquia and Valle del Cauca scale toward semi-commercial status, creating localized mill infrastructure opportunities. ICA feed safety standards shape ingredient sourcing decisions and mill certification requirements. Medellín-area cooperative purchasing structures consolidate fragmented demand into contractible volume blocks.
Chile
Metropolitan Santiago pork belt operations professionalize herd management, expanding compound feed consumption as farm scale increases. The country's national agricultural regulator enforces traceability systems that redirect procurement toward certified suppliers. Central Valley production clusters near Rancagua consolidate feed-milling partnerships with export-oriented processors.
Paraguay
Emerging commercial farm transitions in the Eastern Region generate first-mover advantages for cross-border millers from Brazil and Argentina. Mercosur regulatory harmonization talks create pathway uncertainty for feed safety protocol alignment. Ciudad del Este logistics corridors enable ingredient sourcing arbitrage between Brazilian and Argentine supply networks.
South America Swine Feed Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South America swine feed landscape. The market structure consolidates around multinational integrated nutrition providers, regional milling specialists, and commodity-trading conglomerates with captive oilseed processing assets. Three strategic archetypes dominate: full-service nutrition partners delivering phase-specific formulation consulting, scale-driven commodity millers optimizing logistics density, and vertically integrated pork producers with captive feed operations. M&A activity concentrates on acquiring localized mill infrastructure, while portfolio diversification moves target functional additive categories displaced by antibiotic growth promoter restrictions.
Among multinational integrated nutrition providers, Cargill Incorporated and Archer Daniels Midland Company occupy positions anchored by captive soybean processing networks that control margin from oilseed crush through finished feed delivery. BRF Global exemplifies the vertically integrated pork producer archetype, sustaining formulation leadership through in-house veterinary R&D pipelines tied to production system control. De Heus Animal Nutrition represents the regional specialist tier, competing via localized mill infrastructure that reduces last-mile logistics costs for midsize commercial farms across Brazil's southern pork belt and Argentina's Pampas region.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| BRF Global |
| SHV Holdings |
| De Heus Animal Nutrition |
| Charoen Pokphand Group |
| New Hope Group |
| Alltech Inc. |
| CJ Group |
| Others |
Value Network & Pricing Analysis
Sixty-day soybean meal inventory cycles at Brazilian crushing facilities concentrate pricing power among integrated processors with captive oilseed assets, while Argentine millers absorb currency-driven cost volatility that fragments regional procurement strategies. This lead-time asymmetry between Brazilian supply security and Argentine input instability structures cross-border feed economics across the southern cone.
Pricing Analysis
The customization-premium spread between configured-to-order custom blends and standard formulations runs wide across Brazil's southern pork belt, with phase-specific diets commanding substantial technical service premiums over commodity complete feed. Contract-based long-term offtake agreements dominate volume flows to corporate producers, while spot purchasing persists among backyard operations. Price differentiation rests on volume scale and certification tier under MAPA quality protocols. Cost compression in standard formulations is intensifying because Argentine currency instability transmits directly into regional soybean meal benchmarks. Backyard farms in Colombia's Antioquia department exhibit highest price sensitivity, whereas Santa Catarina integrated producers prioritize feed conversion performance over unit cost.
Supply Chain Analysis
Inventory compression at Brazilian receiving bays—driven by portable NIR deployment for real-time mycotoxin screening—is shortening quality assurance lead times from weeks to hours across southern milling operations. Geographic supply concentrates in Brazil, Argentina, and Paraguay, with Brazilian crushing capacity anchoring regional oilseed meal flows. Raw material dependencies center on soybeans, corn, and imported amino acid premixes from Asian manufacturing hubs. Single-source vulnerability in vitamin and mineral concentrate imports exposes formulators to currency-driven supply interruptions. Distribution runs through direct mill-to-farm contractual channels for commercial operations, with agricultural co-ops consolidating fragmented backyard demand in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
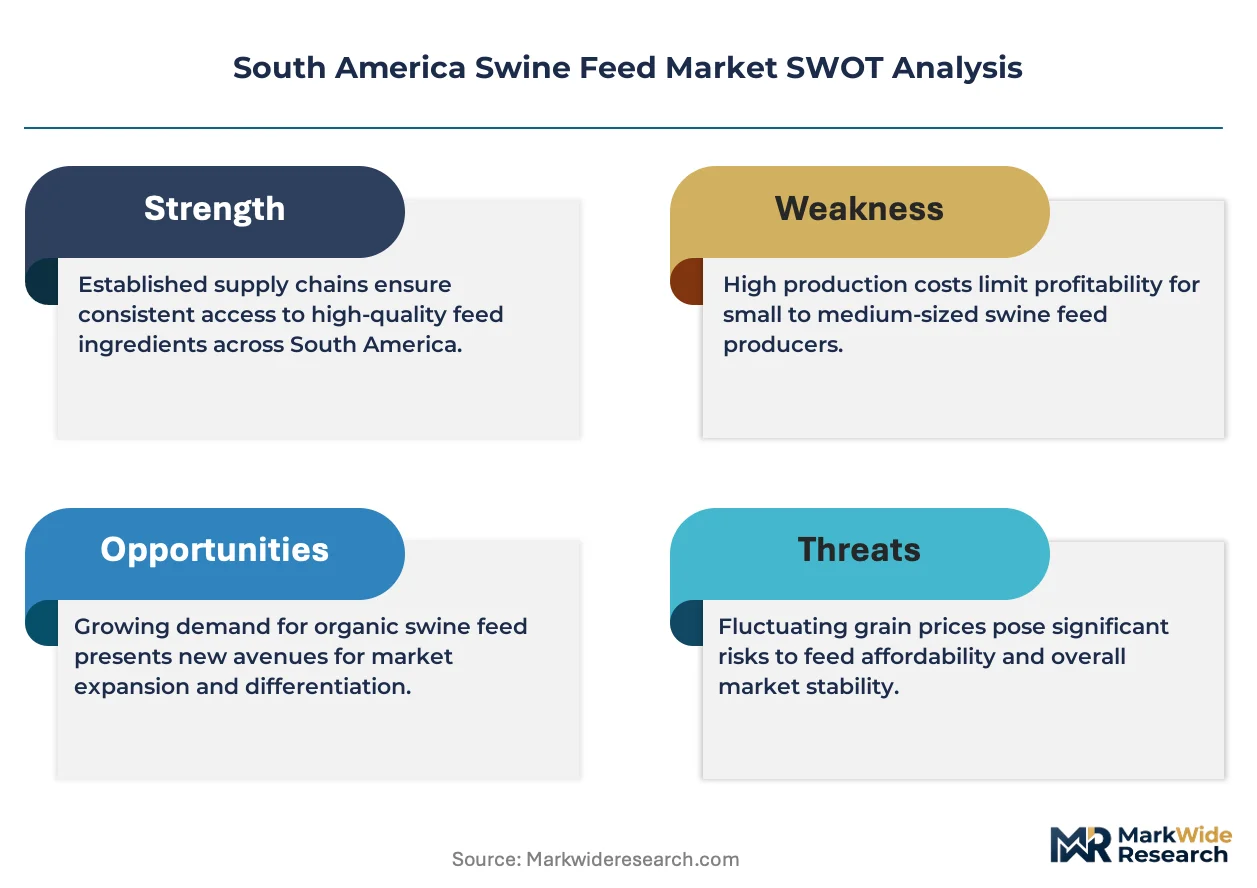
The South America swine feed market constitutes a defensive-moat opportunity anchored in regulatory entrenchment: MAPA, SENASA, and ICA certification requirements create switching costs that bind commercial producers to qualified millers and lock out unqualified competitors.
For Market Incumbents: Compound formulation leadership through backward integration into specialty additive manufacturing, capturing margin pools displaced by ANVISA antibiotic restrictions. Deepen captive supply of acidifier and probiotic inputs to defend against emerging functional ingredient specialists. Prioritize certification investment in Colombian ICA compliance ahead of Antioquia farm scaling to preempt competitor positioning.
For New Entrants and Emerging Players: Lead with localized mill infrastructure in Colombia's Valle del Cauca corridor, where semi-commercial farm transitions concentrate unmet demand for quality-assured feed. Target agricultural co-op channel partnerships as the most penetrable route, consolidating fragmented backyard procurement into contractible volume blocks. Differentiate through embedded technical service capabilities that regional commodity millers cannot replicate.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across custom blend formulation services as genetic specialization demands dedicated R&D infrastructure and phase-specific manufacturing lines. Long-term viability favors full-service nutrition partners with captive technical consulting capabilities rather than commodity volume millers. Acquisition target archetype: regional specialists with established ICA or SENASA certification and underutilized capacity in Colombian or Paraguayan growth corridors. Signal to monitor: MAPA mycotoxin threshold tightening velocity as indicator of quality-assured sourcing premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captures margin pools in acidifiers and probiotics displaced by ANVISA antibiotic restrictions. |
| Localized Mill Infrastructure Expansion | Reduces last-mile logistics costs for midsize commercial farms in Colombia's transitioning corridors. |
| Certification Pre-Positioning | Locks in ICA compliance ahead of Antioquia farm scaling to preempt competitor access. |
| Cooperative Channel Partnership Development | Consolidates fragmented backyard demand into contractible volume blocks with pricing power. |
| Precision Nutrition Platform Deployment | Compresses the gap between genetic potential and realized performance for export-qualified producers. |
Research Methodology
Operator-level perspectives from feed mill operations managers, veterinary nutritionists at integrated pork producers, agricultural co-op procurement committees, and MAPA quality assurance inspectors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation across customs trade records, ANVISA regulatory filings, SENASA certification databases, and SEC disclosures from listed agribusiness conglomerates. Bottom-up volume modeling from individual facility throughput and top-down demand estimation from herd size projections were triangulated to constrain forecast variance.
Sensitivity analysis around soybean meal price volatility, currency fluctuation bands, and regulatory enforcement intensity shaped scenario boundaries across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, formulation complexity tier, and farm scale category. CAGRs were derived from compound growth trajectory fitting to historical volume patterns and structural demand drivers. Industry-specific forecast inputs incorporated genetic line performance curve evolution and export market access requirement tightening from EU and Asian buyers.
The analysis sits within stated boundaries; outcomes outside sustained MAPA enforcement intensity, Mercosur harmonization progress, or Colombian farm transition velocity would require recalibration. Forecasts reflect documented assumptions regarding input cost trajectories and regulatory implementation timelines. Specific risks that could revise projections include unilateral mycotoxin protocol divergence, concentrate import disruption, and feed safety technician supply constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Cattle Head Catch Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Livestock Dewormers Market
Livestock Management
Swine Feed Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
United States Swine Feed Market
Livestock Management
North America Ruminant Feed Premix Market
Livestock Management
Hog Production and Pork Market
Livestock Management
Pig Feed Market
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Layer Breeding System Market
Livestock Management
Animal Feed Protease Market
Livestock Management
Hominy Feed Market
Livestock Management
Cattle Squeeze Market
Livestock Management
Wild Birds Products Market