
 China Swine Feed Market | 2026-2036
China Swine Feed Market Size, Share, and Industry Trends Forecast 2026-2036
China Swine Feed Market Intelligence
Veterinary pharmacist shortages across county-level feed mills is unwinding quality control capacity at smaller compounders. New Hope Group leverages integrated breeding-to-processing operations across Sichuan and Shandong to sustain margin capture from captive hog farms. Wen's Foodstuff Group anchors its position through proprietary breeding stock paired with in-house premix manufacturing in Guangdong. CP Group competes on imported genetic lines and controlled-environment farming protocols that reduce feed conversion ratios.
China swine feed denotes nutritionally formulated rations combining energy sources, protein meals, micronutrient premixes, and functional additives, typically processed through steam-pelleting at 80-85°C to reduce pathogen load and improve digestibility for monogastric livestock. Pellet formulations command premium positioning among large-scale integrators due to reduced feed waste and uniform nutrient delivery, while mash feeds retain cost-sensitive penetration in backyard and smallholder operations. Complete feed formulations dominate volume flows as commercial farms outsource total ration design to compounders, whereas premix and concentrate segments concentrate margin pools with veterinary pharmacies and integrated producers who blend on-farm.
China's Ministry of Agriculture and Rural Affairs enforces the National Feed Quality Safety Standard and antibiotic reduction mandates through provincial agricultural bureaus, while SAMR monitors commercial labeling and additive claims under feed safety regulations. MIIT's industrial policy for agricultural processing equipment indirectly shapes pelleting technology upgrades through machinery subsidies. Stakeholders must monitor county-level enforcement variance and the pace of full antibiotic growth promoter elimination to calibrate formulation R&D budgets and premix portfolio transitions.
Market Dynamics
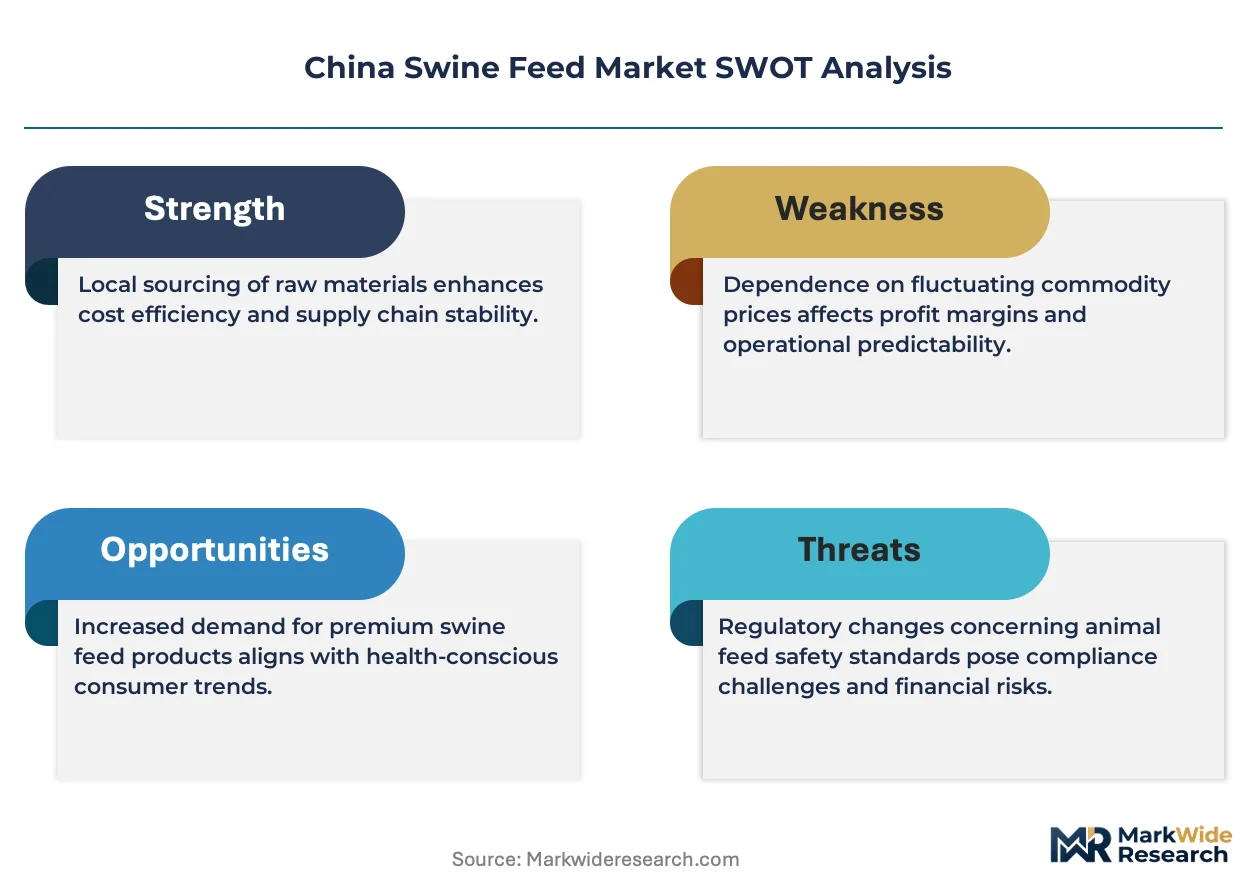
The National Feed Quality Safety Standard is decomposing antibiotic-dependent formulations across Sichuan and Henan provinces, forcing compounders to rebuild premix portfolios around phytogenic and acidifier alternatives while county-level enforcement variance creates uneven compliance timelines.
Growth Catalysts
- Henan Province Concentration:Commercial swine farms in Henan are scaling complete feed procurement as integrators consolidate breeding-to-processing operations, creating captive demand for compound feed volumes.
- National Feed Quality Safety Standard:Antibiotic residue mandates under this framework are accelerating reformulation R&D budgets toward functional additives that maintain growth performance without growth promoters.
- Pelleting Technology:Steam-pelleting at 80-85°C is reducing pathogen load in monogastric rations, enabling large-scale integrators to capture feed conversion efficiency gains and reduce waste.
Market Restraints
- Soybean Meal Volatility:Protein meal input costs fluctuate with import dependency, compressing margin pools for independent compounders lacking long-term supply contracts.
- Veterinary Pharmacist Scarcity:County-level feed mills face quality control capacity erosion as trained personnel concentrate in integrated operations across Sichuan and Shandong.
- Substitution Pressure:In-house premix manufacturing by Wen's Foodstuff Group and similar integrators diverts margin capture from external compounders toward captive blending operations.
Strategic Opportunities
- Guangdong Breeding Stock:Proprietary genetic lines paired with controlled-environment farming protocols offer white space for premium feed formulations targeting reduced feed conversion ratios.
- MIIT Machinery Subsidies:Industrial policy for agricultural processing equipment creates channel for pelleting technology upgrades among mid-scale compounders in central China.
- Dual Carbon Goals:Methane-reducing feed additives align with MEE emissions targets, opening regulatory tailwind for novel formulation categories in commercial farm supply contracts.
Industry Challenges
- Formulation Talent Gap:Veterinary pharmacists with antibiotic-to-alternative transition expertise concentrate in integrated groups, leaving county mills dependent on generic premix suppliers.
- Certification Timeline Compression:SAMR additive claim reviews and provincial agricultural bureau inspections create compliance bottlenecks for novel functional ingredient introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Swine Feed Market |
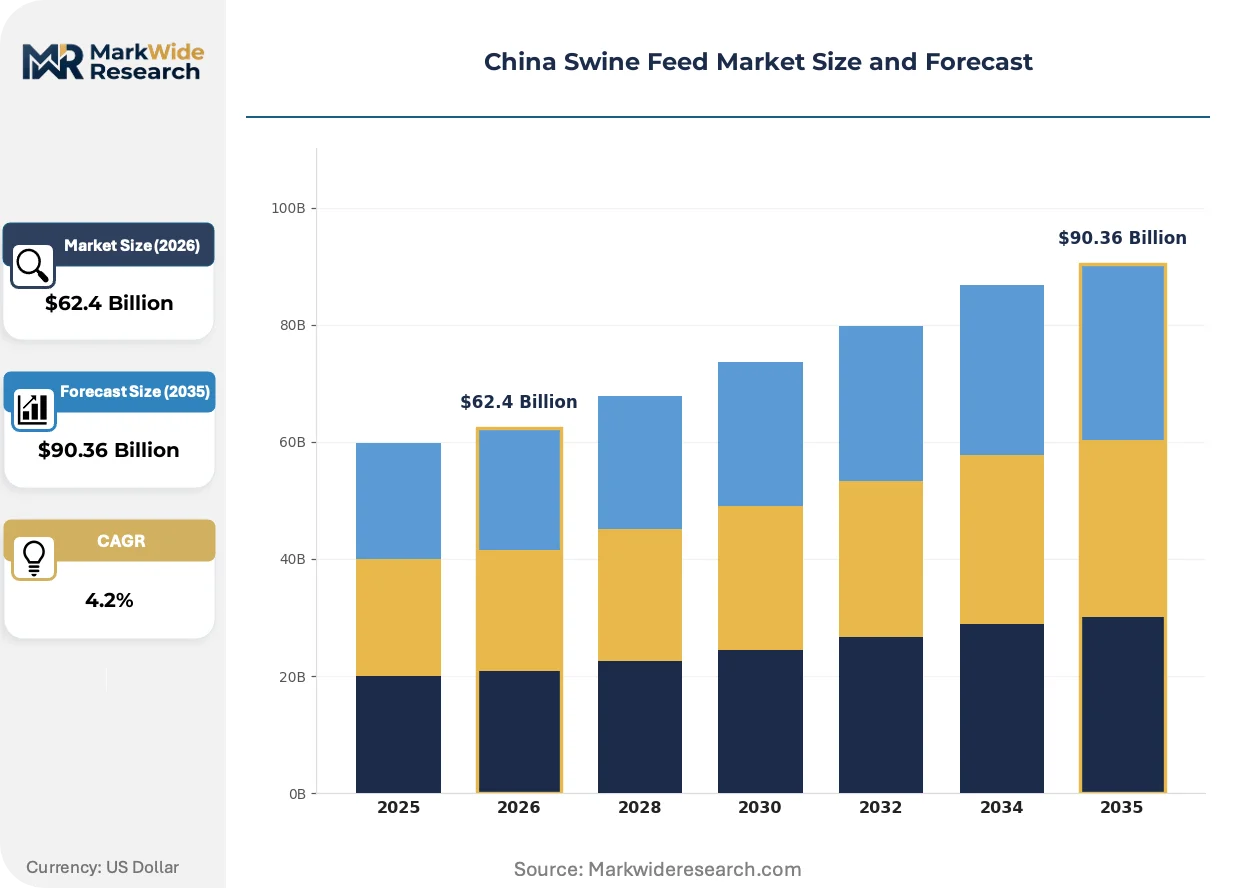
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $90.36 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Mash, Crumbles, Liquid Ingredient Type: Corn, Soybean Meal, Wheat Bran, Additives Formulation Type: Complete Feed, Supplementary Feed, Premix, Concentrate Distribution Channel: Online Retail, Feed Stores, Wholesalers, Distributors |
| Companies Covered | New Hope Group, Wen's Foodstuff Group, CP Group, Haid Group, Twins Group, Tongwei Group, Cargill, COFCO, CJ Tianjin Feed Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Swine Feed Market Strategic Shifts & Innovations
Functional additive categories are displacing legacy antibiotic growth promoters as the primary margin pool in premix manufacturing, while precision nutrition tools and alternative protein sourcing reshape formulation architecture.
Enzyme-supplemented rations is decomposing conventional energy-protein balance assumptions in monogastric nutrition. Large-scale integrators in Sichuan are adopting multi-enzyme complexes at accelerated procurement cycles. This technology is compressing the addressable market for standard vitamin-mineral premixes by shifting value capture toward bioactive compound specialists.
SAMR feed safety regulations and provincial labeling enforcement are tightening additive claim substantiation requirements. Industrial consequence falls heaviest on small compounders lacking in-house toxicology data. Backyard and smallholder operations in peripheral provinces face reduced access to novel functional ingredients as distributors withdraw unverified product lines.
Direct contracting between genetic stock suppliers and feed compounders is consolidating procurement decisions into fewer bilateral relationships. Distributor networks in Henan and Shandong are losing volume share to captive supply arrangements. This pattern is most visible among operations running imported breeding lines with performance-guaranteed nutrition protocols.
China Swine Feed Market Segmentation
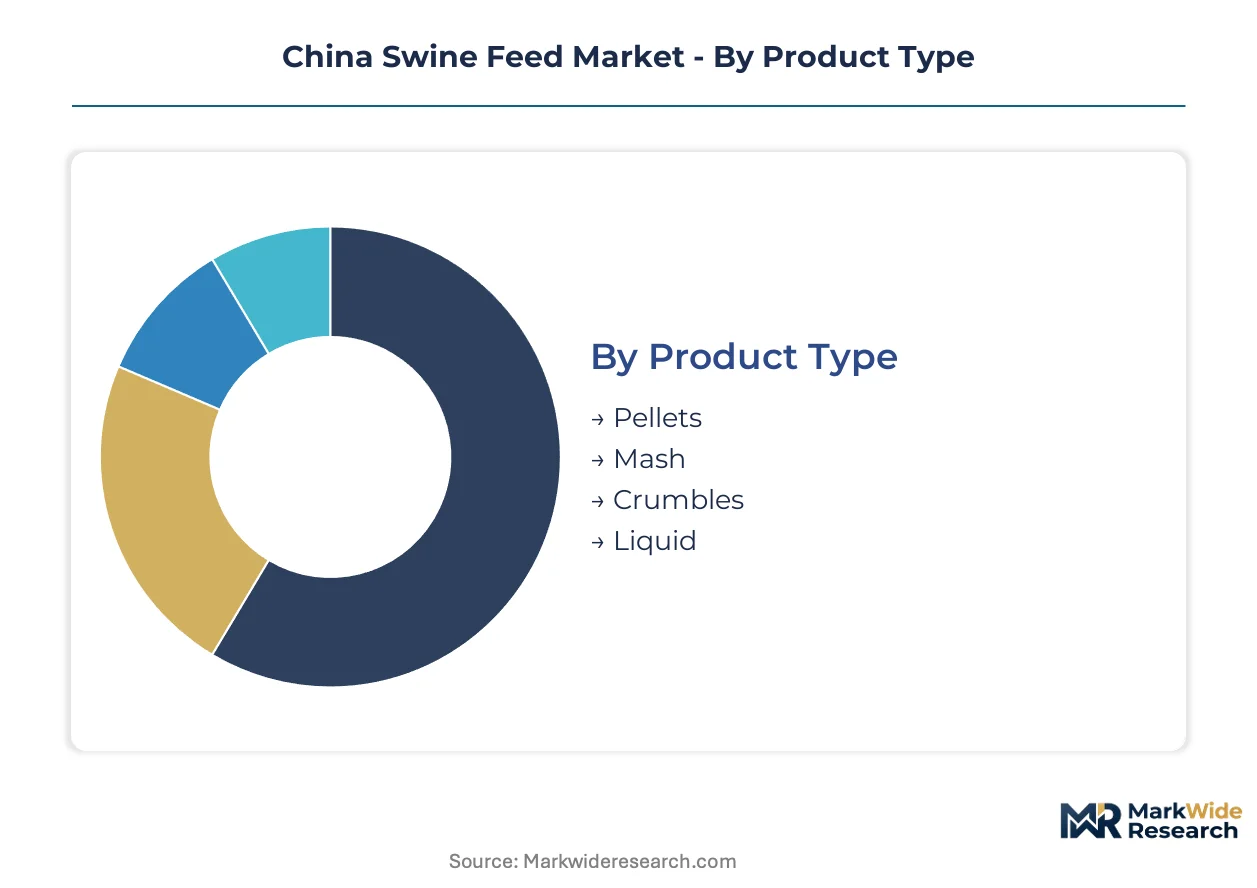
Segmentation in China's swine feed market reflects divergent compliance capabilities across provincial enforcement zones and the operational scale of end-users. SAMR labeling requirements and county-level agricultural bureau inspections create tiered access barriers that reshape channel economics and formulation procurement patterns.
Product Type:
Regulatory differentiation separates pathogen-reduction compliant formats from legacy processing methods, with steam-pelleting mandates under National Feed Quality Safety Standard creating technology tiering.
- Pellets:Steam-pelleting at 80-85°C reduces pathogen load and improves digestibility for monogastric livestock. Henan integrators running imported breeding lines specify pellet formulations to capture feed conversion efficiency gains and minimize waste.
- Mash:Unprocessed grain-meal mixtures retain cost-sensitive penetration among backyard and smallholder operations in peripheral provinces. County-level enforcement variance permits continued mash use where pelleting infrastructure investment exceeds operational scale.
- Crumbles:Broken pellet fragments offer intermediate texture for nursery-stage swine. Sichuan commercial farms deploy crumbles during weaning transitions to reduce feed refusal rates.
- Liquid:Slurry-based rations support automated delivery systems in Guangdong controlled-environment facilities. Wen's Foodstuff Group operates proprietary liquid feed protocols paired with in-house premix manufacturing.
Established volume favors pellets; emerging adoption favors liquid formats in coastal integrator facilities.
Ingredient Type:
Cost tier separation dominates procurement decisions, with import-dependent protein meals compressing margin pools for compounders lacking long-term supply contracts.
- Corn:Primary energy source in complete feed formulations, sourced from domestic production in Northeast China. MIIT machinery subsidies support processing equipment upgrades for corn grinding operations in central province mills.
- Soybean Meal:Protein meal input costs fluctuate with import dependency, forcing independent compounders toward alternative amino acid sourcing strategies. New Hope Group leverages integrated operations to secure supply contract stability.
- Wheat Bran:Fiber-rich milling byproduct supplies cost-reducing bulk in grower-finisher rations. Smallholders in Shandong substitute wheat bran for soybean meal during price spike periods.
- Additives:Functional categories including enzymes, acidifiers, and phytogenics displace legacy antibiotic growth promoters. County mills lacking veterinary pharmacist expertise depend on generic premix suppliers for additive blending.
Volume concentration rests with corn; steepest expansion trajectory belongs to functional additive categories under antibiotic reduction mandates.
Formulation Type:
Customer type stratification separates outsourced total ration design from captive blending operations, with margin capture diverting toward integrated producers.
- Complete Feed:Outsourced total ration design dominates volume flows as commercial farms delegate formulation to compounders. Tongwei Group expands pellet production capacity across central China to serve this procurement pattern.
- Premix:Micronutrient concentrates concentrate margin pools with veterinary pharmacies and integrated producers who blend on-farm. Wen's Foodstuff Group anchors position through proprietary premix manufacturing in Guangdong.
- Concentrate:Protein-vitamin-mineral blends require on-farm grain addition, serving mid-scale operations with limited storage infrastructure. Henan distributors stock concentrate formats for farms transitioning from backyard to commercial scale.
- Supplementary Feed:Specialty rations address specific production phases or health challenges. CP Group deploys controlled-environment farming protocols that reduce feed conversion ratios through precision supplementary feeding.
Complete feed commands current volume; premix manufacturing gains share fastest through backward integration by large integrators.
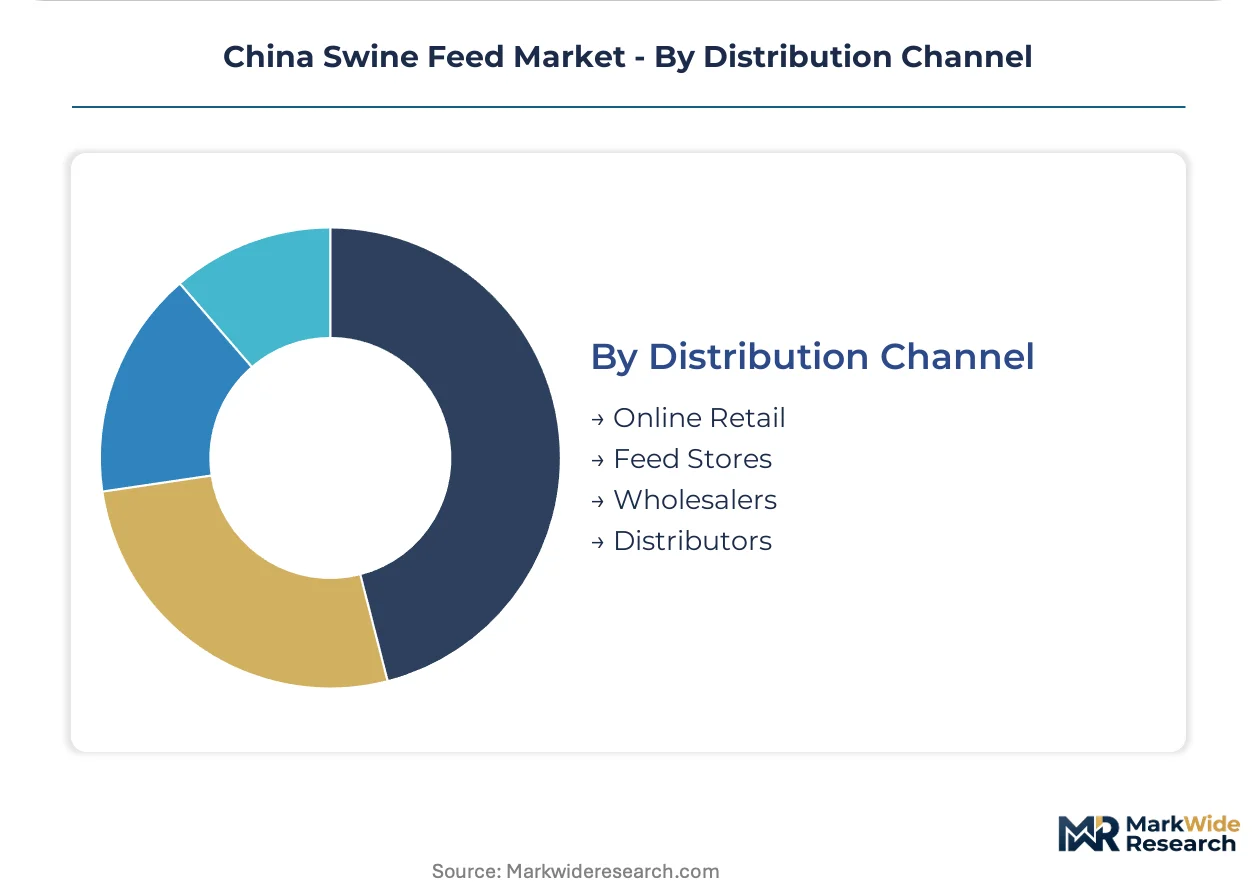
Distribution Channel:
Supply concentration patterns reshape procurement decisions, with direct contracting consolidating volume into fewer bilateral relationships outside traditional distributor networks.
- Feed Stores:County-level retail points serve smallholders and backyard operations with bagged complete feed. Veterinary pharmacist shortages across these outlets limit technical consultation quality.
- Distributors:Regional networks in Henan and Shandong are losing volume share to captive supply arrangements. Genetic stock suppliers increasingly contract directly with compounders for performance-guaranteed nutrition protocols.
- Wholesalers:Bulk procurement intermediaries supply mid-scale farms without direct manufacturer relationships. Price volatility in soybean meal compresses wholesaler margin sustainability.
- Online Retail:E-commerce platforms penetrate peripheral provinces where physical distribution infrastructure remains underdeveloped. SAMR feed safety regulations tighten additive claim substantiation for digital channel listings.
Feed stores retain smallholder access; distributor networks face structural compression from direct contracting trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sichuan and Henan provinces deploy complete feed formulations at commercial scale, while backyard operations in peripheral provinces retain mash-based rations. This consumption-mix differential reflects enforcement variance under the National Feed Quality Safety Standard.
Sichuan Province
Commercial integrators in Sichuan are scaling pellet procurement for imported breeding lines. The Ministry of Agriculture and Rural Affairs enforces antibiotic residue standards through provincial agricultural bureaus. Chengdu and Mianyang host concentrated compounder capacity serving captive hog farms with steam-pelleted formulations.
Henan Province
Breeding-to-processing consolidation in Henan is driving complete feed demand from large-scale operations. SAMR monitors commercial labeling and additive claims under national feed safety regulations. Zhengzhou and Nanyang cluster feed mill infrastructure expanding pellet production capacity.
Shandong Province
Integrated producers in Shandong leverage backward control over premix manufacturing to capture margin pools. County-level enforcement of the National Feed Quality Safety Standard varies across agricultural bureaus. Qingdao and Weifang concentrate veterinary pharmacist talent in corporate operations.
Guangdong Province
Controlled-environment facilities in Guangdong deploy liquid feed systems with proprietary premix protocols. MEE emissions targets under dual carbon goals incentivize methane-reducing additive categories. Foshan and Guangzhou anchor Wen's Foodstuff Group operations pairing breeding stock with in-house formulation.
Central China Cluster
Mid-scale compounders across Hubei and Hunan are accessing MIIT machinery subsidies for pelleting technology upgrades. Provincial agricultural bureaus inspect county-level mills for compliance with antibiotic reduction mandates. Wuhan and Changsha distribute concentrate formats to farms transitioning from backyard to commercial scale.
China Swine Feed Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in China's swine feed market. The upper tier captures margin through captive breeding-to-processing operations and in-house premix manufacturing. Specialist compounders compete on formulation R&D and regional distribution density. Dominant competitive moves include backward integration into premix production and direct contracting with genetic stock suppliers.
Among integrated leaders, New Hope Group exemplifies the captive supply archetype through Sichuan and Shandong operations. Wen's Foodstuff Group occupies a position representing proprietary breeding stock paired with controlled-environment protocols. Tongwei Group anchors the scale-driven compounder tier expanding pellet capacity across central China.
| Leading Market Players |
|---|
| New Hope Group |
| Wen's Foodstuff Group |
| CP Group |
| Haid Group |
| Twins Group |
| Tongwei Group |
| Cargill |
| COFCO |
| CJ Tianjin Feed Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at steam-pelleting facilities across Henan and Sichuan shapes both supply concentration and price floors for compound feed. Large integrators operating at scale capture procurement leverage that county-level mills cannot match, compressing margin sustainability for independent producers while antibiotic-free formulation premiums widen price dispersion.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated hog farms and compounders, insulating volume buyers from soybean meal spot volatility. Pricing stratifies across premium, standard, and economy tiers based on pathogen-reduction certification grade and volume scale. Cost compression in standard-tier complete feed is intensifying because import-dependent protein meals expose independent compounders to margin erosion. Backyard operations in peripheral provinces exhibit highest price sensitivity, while Wen's Foodstuff Group and similar integrators absorb premium positioning through captive supply arrangements.
Supply Chain Analysis
Soybean import terminals at Dalian and Tianjin ports constitute a chokepoint that constrains protein meal flows to central China compounders. Domestic corn production in Northeast China, Brazilian soybean meal imports, and domestic wheat bran from Shandong milling operations anchor raw material sourcing. Single-source vulnerability concentrates in ocean freight lanes connecting South American ports to Chinese crushing facilities. Distribution runs through captive supply arrangements between genetic stock suppliers and large integrators, bypassing traditional distributor networks in Henan and Shandong.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic elimination mandates under the National Feed Quality Safety Standard are disrupting legacy formulation economics and opening white space for functional additive specialists. This regulatory inflection compresses timelines for R&D investment decisions across the value chain.
For Market Incumbents: Consolidate procurement relationships with imported breeding line suppliers to lock in performance-guaranteed nutrition protocols. Expand pelleting capacity in Sichuan and Henan to capture volume concentration from breeding-to-processing consolidation. Defend against margin diversion from in-house premix manufacturing by Wen's Foodstuff Group and similar integrators through exclusive supply contracts with mid-scale farms transitioning from backyard operations.
For New Entrants and Emerging Players: Lead with methane-reducing feed additive formulations targeting Guangdong controlled-environment facilities under dual carbon goals. Target county-level feed mills in Hubei and Hunan facing veterinary pharmacist scarcity with outsourced premix blending services. Establish technical consultation partnerships with provincial agricultural bureaus to navigate SAMR additive claim reviews.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive hog farm networks spanning breeding-to-processing operations. Long-term viability over a multi-year horizon favors compounders with backward integration into premix manufacturing and direct genetic stock supplier relationships. Monitor county-level enforcement variance of antibiotic residue standards as the inflection indicator for formulation R&D budget allocation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premix Manufacturing | Wen's Foodstuff Group captures margin pools through proprietary Guangdong blending operations. |
| Pelleting Technology Upgrade | MIIT machinery subsidies enable mid-scale Henan compounders to achieve pathogen-reduction compliance. |
| Direct Genetic Stock Contracting | CP Group reduces feed conversion ratios through performance-guaranteed nutrition protocols. |
| Functional Additive R&D Expansion | Phytogenic and acidifier alternatives displace legacy antibiotic growth promoters under SAMR enforcement. |
| Controlled-Environment Facility Partnership | Liquid feed system deployment in Guangdong aligns with MEE methane reduction targets. |
Research Approach
Operator-level perspectives from compounder procurement directors, veterinary pharmacists at county-level mills, hog farm operations managers, and SAMR regulatory affairs specialists anchored the qualitative base. These primary insights combined with secondary validation from Ministry of Agriculture and Rural Affairs inspection reports, customs trade data on soybean meal imports, MIIT machinery subsidy disclosures, and provincial agricultural bureau enforcement records. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Sensitivity analysis tested forecast robustness across alternative scenarios for antibiotic elimination pace and protein meal price volatility. The analytical framework modeled product type, ingredient category, formulation architecture, and distribution channel dimensions across the projection horizon. CAGRs derived from regression analysis against historical procurement volume patterns and regulatory compliance timeline assumptions. Industry-specific inputs included county-level veterinary pharmacist density and pelleting equipment installation rates.
Forecasts assume regulatory continuity in National Feed Quality Safety Standard enforcement and dual carbon goal implementation; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as provincial agricultural bureau inspection intensity and soybean import tariff regimes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Bird Feeder Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Herd Management Software Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Wild Birds Products Market
Livestock Management
South America Ruminant Feed Market
Livestock Management
North America Swine Feed Market
Livestock Management
Pig Feed Market
Livestock Management
Hominy Feed Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Morocco Poultry Market
Livestock Management
Layer Feed Market
Livestock Management
North America Feed Binders Market
Livestock Management
North America Ruminant Feed Premix Market