
 Asia Pacific Poultry Market | 2026-2036
Asia Pacific Poultry Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Poultry Market Outlook
Multi-source feed procurement is repositioning cost structures across the Asia Pacific poultry value chain. Charoen Pokphand Foods PCL leverages its integrated aquafeed-poultry operations to control input volatility across Thailand and Vietnam. New Hope Liuhe anchors volume leadership through its captive breeding networks spanning Sichuan and Shandong provinces. Tyson Foods, Inc. competes by exporting dark-meat cuts to price-sensitive Southeast Asian food manufacturers, offsetting domestic breast-meat oversupply in its home market.
Asia Pacific poultry encompasses broilers, turkeys, ducks, and layers raised for meat and egg output, with commercial operations typically achieving slaughter weights of 1.8–2.2 kilograms within 35–42 days through controlled-environment housing and formulated feed rations. The sector serves food manufacturers, quick-service restaurants, and retail channels requiring standardized portioning and cold-chain integrity. Broilers dominate absolute volume due to feed conversion efficiency, while layers command margin resilience through long-term egg supply contracts with institutional bakers and processors. Duck production retains regional concentration in China and Vietnam, where traditional cuisine sustains premium pricing over commodity broiler cuts.
China's Ministry of Agriculture and Rural Affairs enforces GB standards for veterinary drug residues, while India's FSSAI mandates licensing for all poultry processing facilities under its Food Safety Act. Indonesia's national drug and food control agency regulates import quotas for parent stock, directly constraining domestic flock expansion rates. Stakeholders must monitor how antibiotic restriction timelines in China and India will reshape breeding stock sourcing and veterinary service models without triggering supply discontinuities.
Market Dynamics
China's tightening GB standards on veterinary drug residues are forcing processing upgrades throughout the Asia Pacific poultry value chain, compressing margins for operators dependent on legacy antibiotic protocols while accelerating investment in alternative health management systems.
Growth Catalysts
- Quick-service restaurant expansion:Southeast Asian food service chains are scaling poultry procurement as protein preferences shift toward affordable white meat, particularly across Indonesia's urban corridor from Jakarta to Surabaya.
- Feed conversion efficiency gains:Controlled-environment housing and formulated feed rations are enabling commercial broiler operations to achieve slaughter weights of 1.8–2.2 kilograms within 35–42 days, compressing production cycles.
- Egg supply contract resilience:Long-term institutional agreements with bakers and processors are stabilizing layer margins against commodity broiler price volatility in China and Vietnam.
Market Restraints
- Antibiotic residue compliance costs:China's GB standards and India's FSSAI licensing mandates are forcing capital-intensive processing upgrades throughout the value chain.
- Parent stock import quotas:Indonesia's national drug and food control agency directly constrains domestic flock expansion rates through restrictive import licensing.
- Cold chain infrastructure gaps:Quick-service restaurant expansion outpaces refrigerated logistics development across Southeast Asian secondary cities, limiting distribution reach.
Strategic Opportunities
- Duck production premiumization:Traditional cuisine sustains above-commodity pricing for duck in China and Vietnam, creating margin expansion potential for specialized operators.
- Integrated aquafeed-poultry operations:Cross-species feed manufacturing is enabling input cost volatility management across Thailand and Vietnam.
- Dark-meat export arbitrage:Southeast Asian food manufacturers are absorbing price-sensitive cuts that face oversupply pressure in developed markets.
Industry Challenges
- Veterinary service model reconfiguration:Antibiotic restriction timelines in China and India are forcing breeding stock sourcing shifts without triggering supply discontinuities.
- Captive breeding network complexity:Scaling geographically dispersed parent stock operations across provinces like Sichuan and Shandong requires specialized technical talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Poultry Market |
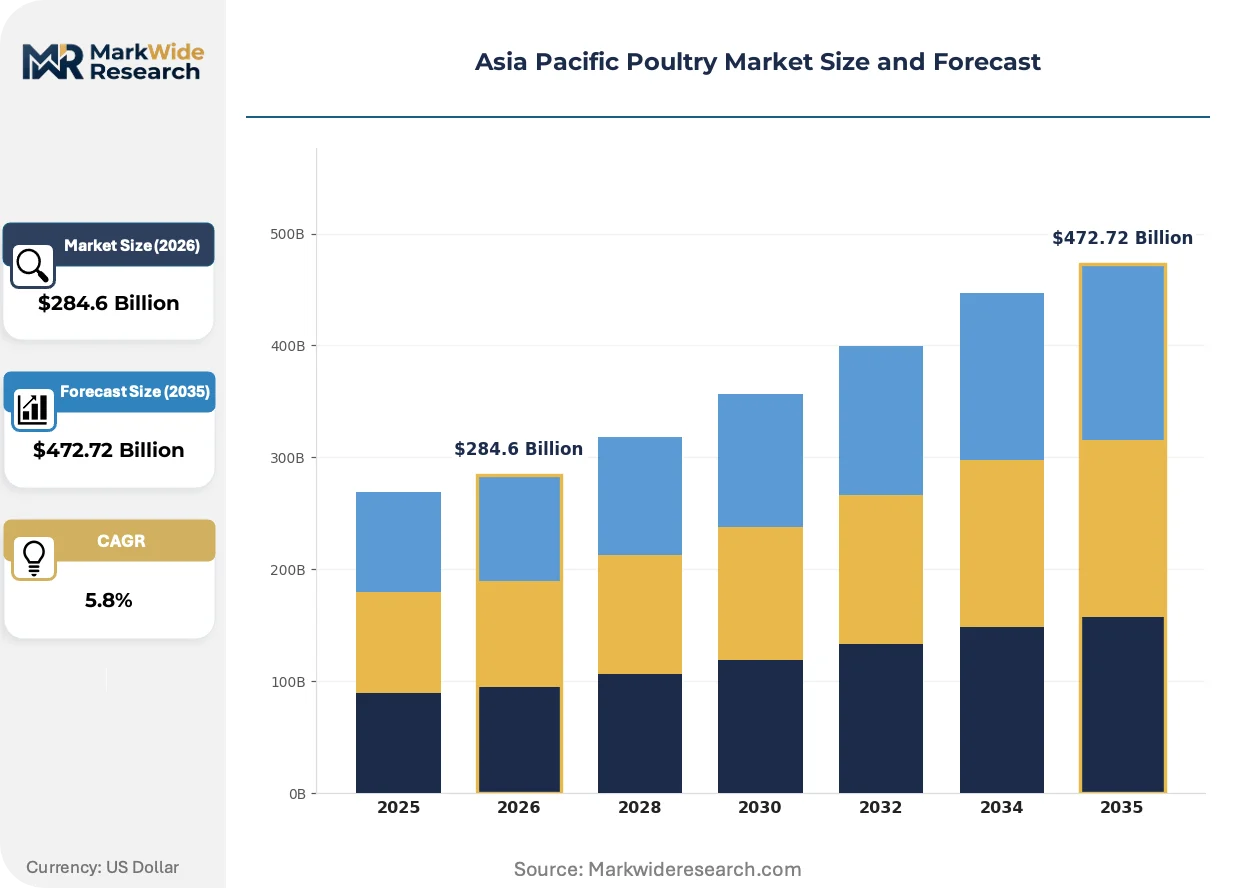
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $472.72 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broilers, Turkeys, Ducks, Layers Application: Meat Production, Egg Production, Breeding, Food Processing Distribution Channel: Wholesale, Retail, Direct Sales, E-commerce Customer Type: Consumers, Restaurants, Food Service, Food Manufacturers |
| Companies Covered | NH Foods Ltd., Tyson Foods, Inc., Charoen Pokphand Foods PCL, New Hope Liuhe, VH Group, Wen's Foodstuff Group Co. Ltd., Cargill, Baiada Poultry Pty Ltd, Suguna Foods Pvt. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Poultry Market Strategic Shifts
Automation and digital traceability systems are compressing production cycles while regulatory pressure on residue management is accelerating alternative health technology adoption across the Asia Pacific poultry sector.
Computer vision-based grading and robotic processing equipment is automating carcass inspection and portioning workflows in large-scale Thai and Vietnamese processing facilities. Major quick-service restaurant suppliers are deploying these systems to meet chain-level consistency requirements. The technology is automating quality control labor previously dependent on manual inspection, reducing throughput variability.
China's Ministry of Agriculture and Rural Affairs is progressively tightening GB standard enforcement timelines for veterinary drug residues, with full compliance deadlines accelerating facility upgrade investments. Processing operators are responding by consolidating slaughter capacity into fewer, larger certified facilities. Broiler operations in Shandong and Henan provinces face the steepest compliance cost curves.
Direct procurement relationships between quick-service restaurant chains and integrated poultry operators are displacing traditional wholesale market intermediaries across Indonesia and the Philippines. Chains are mandating farm-to-fork traceability documentation that fragmented wholesale channels cannot provide. This pattern concentrates most visibly in the Jakarta-Surabaya corridor where cold chain investment lags demand growth.
Asia Pacific Poultry Market Segmentation
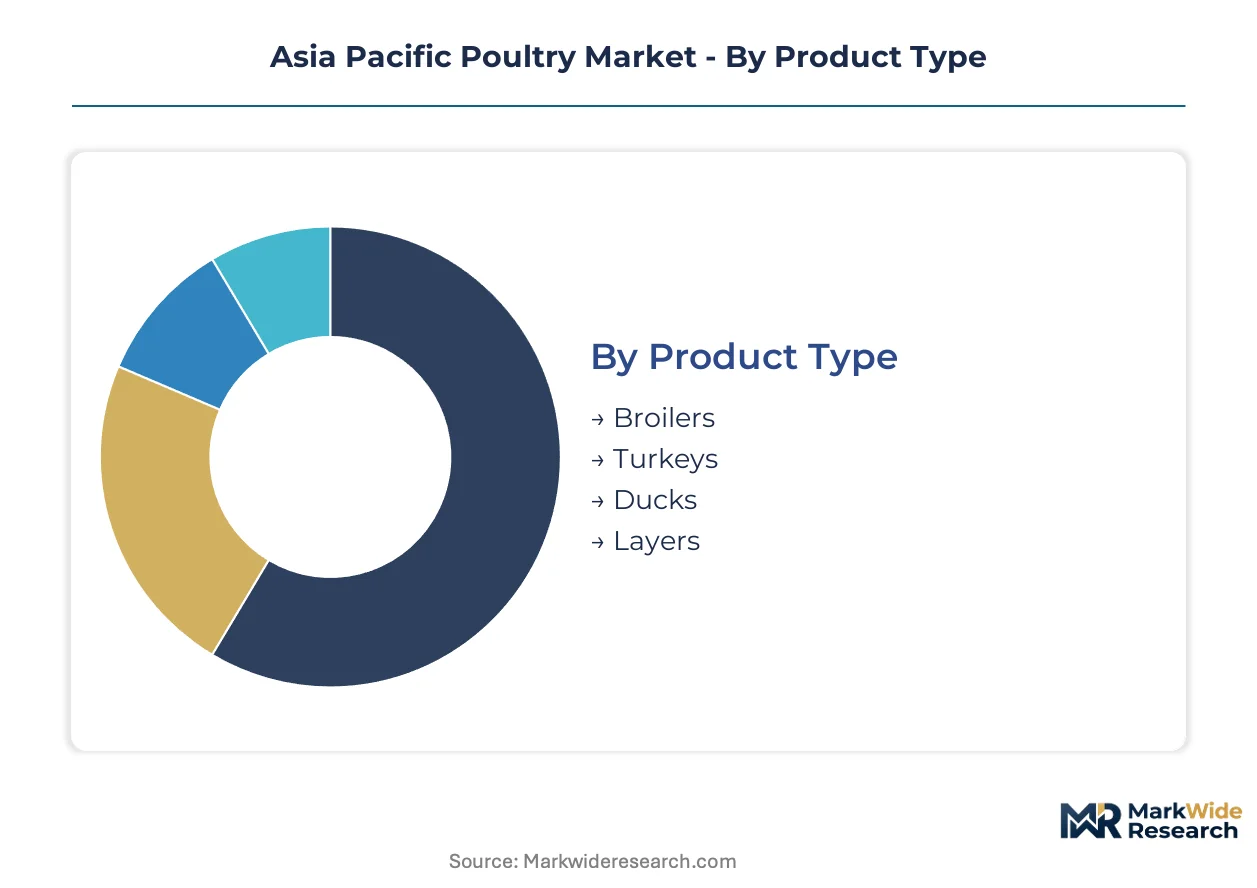
Segmentation in Asia Pacific poultry reveals how protein flows diverge across species, applications, and channel structures. Supply concentration varies dramatically by segment, with broilers and layers commanding fundamentally different capital intensity profiles and margin dynamics.
Product Type:
Supply concentration in breeding stock and processing infrastructure varies sharply across avian species, shaping competitive barriers and regional production gravity.
- Broilers:Commercial operations achieve 1.8–2.2 kilogram slaughter weights within 35–42 days through controlled-environment housing and precision-formulated feed rations. Demand concentrates in Indonesia's Jakarta-Surabaya urban corridor where quick-service restaurant expansion outpaces cold chain development, forcing processors to absorb logistics inefficiencies.
- Layers:Long-term egg supply contracts with institutional bakers and processors in China and Vietnam provide margin resilience against commodity price swings. Shandong and Henan provinces anchor China's layer concentration, with vertical integration into feed milling reducing input cost volatility.
- Ducks:Traditional cuisine in China and Vietnam sustains premium pricing above commodity broiler cuts, though breeding stock availability constrains rapid scaling.
- Turkeys:Limited regional demand restricts commercial scale, with production concentrated around festive and export-oriented processing.
Today's leader: Broilers. Tomorrow's challenger: Layers.
Application:
Margin stability diverges across application types based on contract structure and perishability constraints.
- Meat Production:Slaughter and portioning operations serving quick-service restaurants require farm-to-fork traceability documentation that fragmented wholesale channels cannot provide, concentrating procurement relationships with integrated operators.
- Egg Production:Institutional supply agreements with food manufacturers stabilize revenue streams against spot market volatility.
- Breeding:Parent stock import quotas in Indonesia directly constrain domestic flock expansion rates, creating supply bottlenecks.
- Food Processing:Further-processed products command value-add margins but face tightening GB standard compliance costs for veterinary drug residue management.
Meat production captures current volume leadership. Egg production offers the steadiest margin trajectory.
Distribution Channel:
Channel selection determines traceability compliance burden and working capital intensity.
- Direct Sales:Quick-service restaurant chains mandate documentation standards that displace traditional wholesale intermediaries across Indonesia and the Philippines.
- Wholesale:Traditional wet markets persist in secondary Southeast Asian cities where cold chain gaps limit alternative channel penetration.
- Retail:Supermarket expansion in Vietnam and Thailand drives packaged poultry growth, requiring standardized portioning investments.
- E-commerce:Emerging channel constrained by last-mile cold chain reliability in dense urban corridors.
Direct sales leads contract value. E-commerce climbs fastest from minimal base.
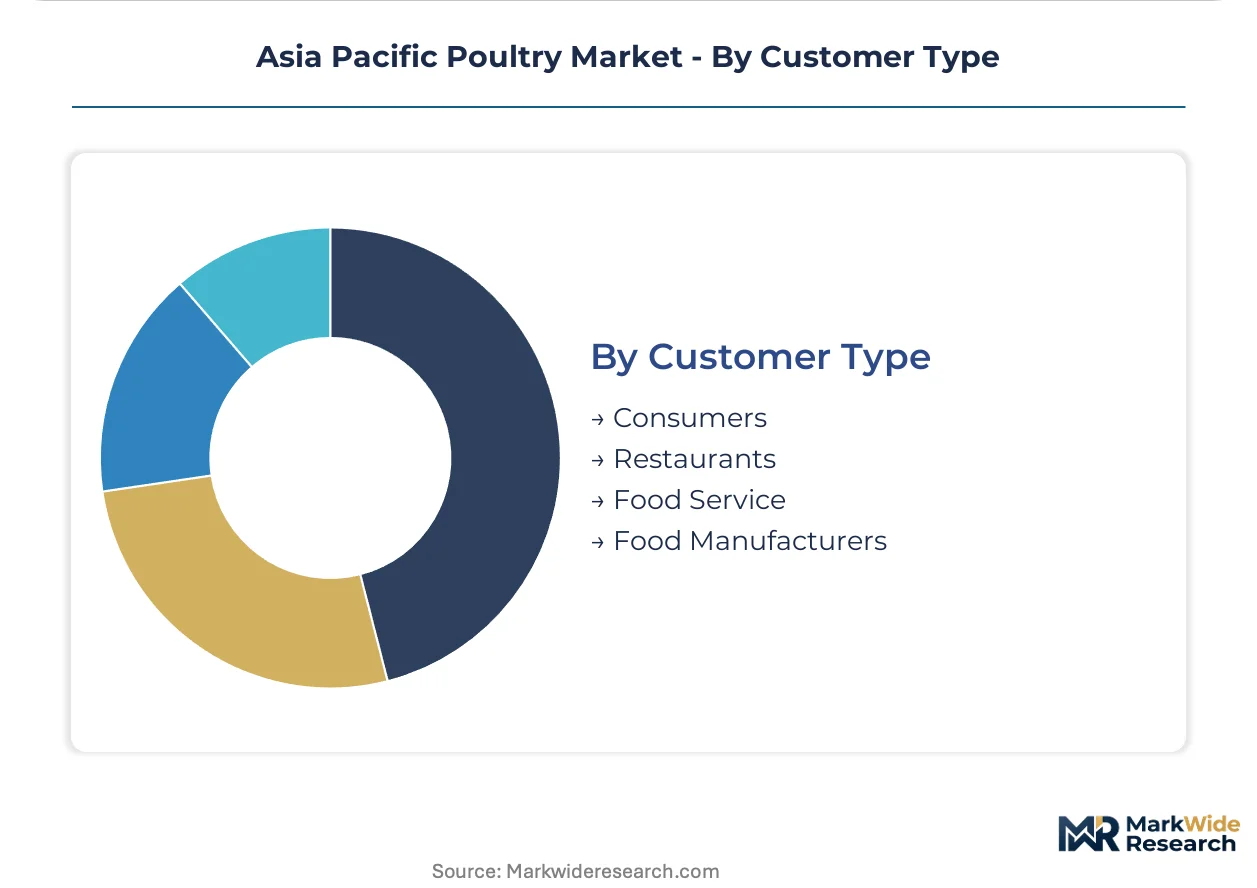
Customer Type:
Customer scale determines procurement sophistication and specification stringency.
- Food Service:Chain-level consistency requirements drive automation adoption in Thai and Vietnamese processing facilities.
- Food Manufacturers:Absorb price-sensitive dark-meat cuts facing oversupply pressure in developed markets, creating arbitrage opportunities.
- Restaurants:Independent operators rely on wholesale markets with limited traceability documentation.
- Consumers:Retail purchasing concentrates in urban centers with reliable cold chain infrastructure.
Food service dominates procurement innovation. Food manufacturers offer volume absorption flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jakarta-Surabaya urban corridor anchors Asia Pacific poultry demand expansion, where quick-service restaurant density outpaces cold chain infrastructure deployment. Indonesia's national drug and food control agency regulates parent stock import quotas, constraining domestic flock growth rates. Processing operators absorb logistics inefficiencies while scaling standardized portioning capacity for chain-level procurement contracts.
China
Shandong and Henan provinces concentrate layer operations with captive feed milling networks reducing input cost volatility. The Ministry of Agriculture and Rural Affairs enforces progressively tightening GB standards on veterinary drug residues, accelerating facility consolidation into fewer certified slaughter plants. Broiler operations face steepest compliance cost curves as antibiotic restriction timelines compress margin structures.
Indonesia
Quick-service restaurant chains mandate farm-to-fork traceability documentation that fragmented wholesale channels cannot provide, displacing traditional intermediaries across the Jakarta-Surabaya corridor. The national drug and food control agency restricts parent stock import licensing, directly capping domestic flock expansion velocity. Cold chain investment lags demand growth, forcing processors to absorb distribution inefficiencies.
Thailand
Integrated aquafeed-poultry operations leverage cross-species feed manufacturing to manage input cost volatility across commercial broiler networks. Charoen Pokphand Foods PCL anchors production gravity through controlled-environment housing achieving 35-42 day slaughter cycles. Processing automation adoption concentrates in facilities supplying chain-level consistency requirements for quick-service restaurant procurement.
Vietnam
Traditional cuisine sustains premium pricing for duck production above commodity broiler cuts, though breeding stock availability constrains rapid scaling. Long-term egg supply contracts with institutional bakers stabilize layer margins against spot market volatility. Computer vision-based grading systems automate carcass inspection workflows in large-scale processing facilities serving export-oriented food manufacturers.
India
The Food Safety and Standards Authority of India mandates licensing for all poultry processing facilities under its Food Safety Act, forcing capital-intensive upgrades throughout the value chain. FSSAI compliance timelines reshape breeding stock sourcing and veterinary service models without triggering supply discontinuities. VH Group and Suguna Foods occupy positions within the fragmented processor landscape serving price-sensitive food service channels.
Asia Pacific Poultry Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue integrated aquafeed-poultry synergies and dark-meat export arbitrage. The market structures around three maturity tiers: multinational exporters leveraging home-market oversupply, domestic integrated operators controlling captive breeding networks, and regional specialists capturing traditional cuisine premiums. Strategic archetypes include feed-to-fork integrators, dark-meat arbitrageurs, and layer contract stabilizers. Competitive moves concentrate on processing automation deployment and direct procurement relationships displacing wholesale intermediaries.
Among Asia Pacific-based integrators, Charoen Pokphand Foods PCL and New Hope Liuhe exemplify the feed-to-fork archetype through geographically dispersed operations spanning Thailand, Vietnam, Sichuan and Shandong. Tyson Foods, Inc. occupies a position as the dark-meat export specialist, absorbing price-sensitive cuts facing oversupply pressure in developed markets. NH Foods Ltd. and Baiada Poultry Pty Ltd represent quality-tier positioning for markets demanding standardized portioning and cold-chain integrity documentation.
| Leading Market Players |
|---|
| NH Foods Ltd. |
| Tyson Foods, Inc. |
| Charoen Pokphand Foods PCL |
| New Hope Liuhe |
| VH Group |
| Wen's Foodstuff Group Co. Ltd. |
| Cargill |
| Baiada Poultry Pty Ltd |
| Suguna Foods Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap processors across Thailand and Vietnam anchor supply discipline through generational control of breeding networks, translating feed cost volatility into contract pricing power with quick-service restaurant chains. Their refusal to cede margin to wholesale intermediaries reinforces farm-to-fork traceability premiums that multinational exporters struggle to match.
Pricing Analysis
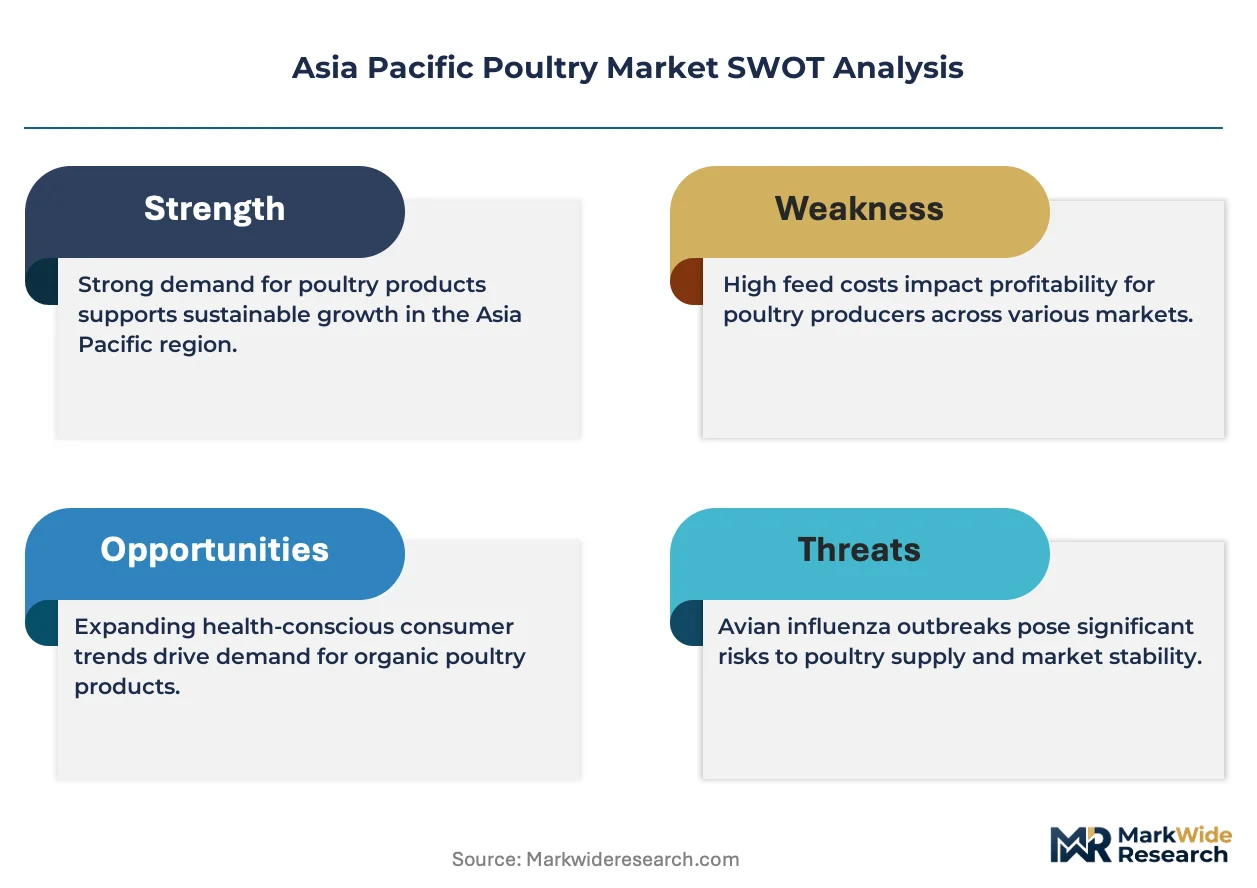
Feed ingredient pass-through dominates pricing mechanics across the Asia Pacific poultry value chain, with soybean meal and corn futures anchoring contract escalators in Thailand and Vietnam. Three-tier pricing structure across premium, standard, and economy levels separates antibiotic-free certified cuts from conventional portions and commodity dark-meat exports. Pricing pressure stems from China's GB standard compliance timelines forcing capital-intensive facility upgrades. Food manufacturers absorbing dark-meat arbitrage cuts exhibit highest price sensitivity, while quick-service restaurant chains purchasing traceability-guaranteed portions accept premium positioning.
Supply Chain Analysis
Reverse-logistics flows for breeding stock returns and parent stock quarantine cycles constrain flock replenishment velocity across Indonesia and the Philippines. Supply concentrates in China, Thailand, and Vietnam, with Shandong and Henan provinces anchoring layer breeding density. Raw material dependencies center on Brazilian soybean meal, Ukrainian corn, and domestic aquafeed byproducts. Single-source vulnerability pervades parent stock genetics concentrated with three global breeders. Distribution runs through direct procurement relationships displacing Jakarta-Surabaya wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific poultry functions as a regulatory compounder where China's Ministry of Agriculture and Rural Affairs GB standard enforcement timelines are accelerating demand for certified processing capacity upgrades.
For Market Incumbents: Acquire captive breeding networks in Sichuan and Shandong provinces to lock in parent stock supply security against Indonesia-style import quota contagion. Consolidate slaughter capacity into fewer certified facilities before China's GB standard deadlines compress margin structures for fragmented competitors.
For New Entrants and Emerging Players: Capture duck production premiums in Vietnam's traditional cuisine corridors where breeding stock constraints limit incumbent scaling velocity. Penetrate institutional egg supply contracts with bakers and processors seeking long-term margin stability against broiler commodity volatility.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Indonesian processors facing parent stock import licensing bottlenecks. Long-term viability favors operators with backward integration into feed milling and controlled-environment housing infrastructure. Monitor China's GB standard enforcement acceleration as the inflection signal for regional consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Processing Automation Deployment | Computer vision grading in Thai facilities meets chain-level consistency mandates from quick-service restaurant procurement. |
| Captive Breeding Network Expansion | Sichuan and Shandong parent stock concentration reduces import quota exposure for layer operations. |
| Direct Procurement Relationship Formation | Farm-to-fork traceability documentation displaces fragmented wholesale intermediaries across Indonesia's Jakarta-Surabaya corridor. |
| Alternative Health Technology Investment | Antibiotic-free protocols respond to China's GB standard tightening while avoiding supply discontinuities. |
| Cross-Species Feed Manufacturing Integration | Aquafeed-poultry synergies in Thailand and Vietnam buffer soybean meal and corn price volatility. |
Study Parameters
Multiple input streams — structured interviews with poultry processing executives, regulatory affairs specialists at China's Ministry of Agriculture and Rural Affairs, quick-service restaurant procurement directors, and veterinary service providers — were reconciled against trade flow databases, customs records, and FSSAI licensing registries. Bottom-up volume modeling triangulated with top-down value estimates derived from feed cost indices and protein substitution elasticities.
Data-stream reconciliation anchored forecast construction across the projection horizon, with segmentation dimensions spanning product type, application, distribution channel, and customer archetype. CAGRs emerged from iterative reconciliation of breeder stock placement trends, slaughter capacity utilization rates, and cold chain infrastructure deployment trajectories. Industry-specific inputs incorporated parent stock import licensing velocity and GB standard compliance cost curves.
Underlying measurement precision varies by segment; broiler and layer volume estimates carry tighter precision than duck production figures constrained by informal sector opacity. Forecasts reflect assumptions regarding regulatory enforcement continuity and feed grain supply stability. Practitioners should monitor China's GB standard deadline acceleration and Indonesia's parent stock quota adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poultry Farming Equipment
Commercial Chicken Plucker Market
Poultry Farming Equipment
Poultry Plucker Market
Poultry Farming Equipment
Egg Grading Machines Market
Poultry Farming Equipment
Poultry Farming Equipment Market
Poultry Farming Equipment
Automated Poultry Farm Market
Poultry Farming Equipment
Poultry Brooder Market
Poultry Farming Equipment
Duck Plucker Machine Market
Poultry Farming Equipment
Rabbit Cages Market
Poultry Farming Equipment
Poultry Incubator Market
Poultry Farming Equipment
Turkey Poultry Market
Poultry Farming Equipment
Poultry House Ventilation System Market
Poultry Farming Equipment
Poultry Brooders, Feeders, and Waterers Market
Poultry Farming Equipment
Egg Breaking Machine Market
Poultry Farming Equipment
Poultry Keeping Machinery Market
Poultry Farming Equipment
Multi-Layer Poultry Cage Market