
 Africa Ruminant Feed Premix Market | 2026-2036
Africa Ruminant Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Ruminant Feed Premix Market Outlook
Nigeria's northern cattle corridor is rewriting feed procurement patterns across West Africa. Cargill Inc. leverages its regional blending facilities to secure supply chain continuity for large-scale dairy cooperatives. Nutreco NV anchors its position through specialized mineral premix formulations tailored to Sahelian forage deficiencies. Godrej Agrovet Limited competes by extending its veterinary distribution network into Ethiopia's emerging commercial beef sector.
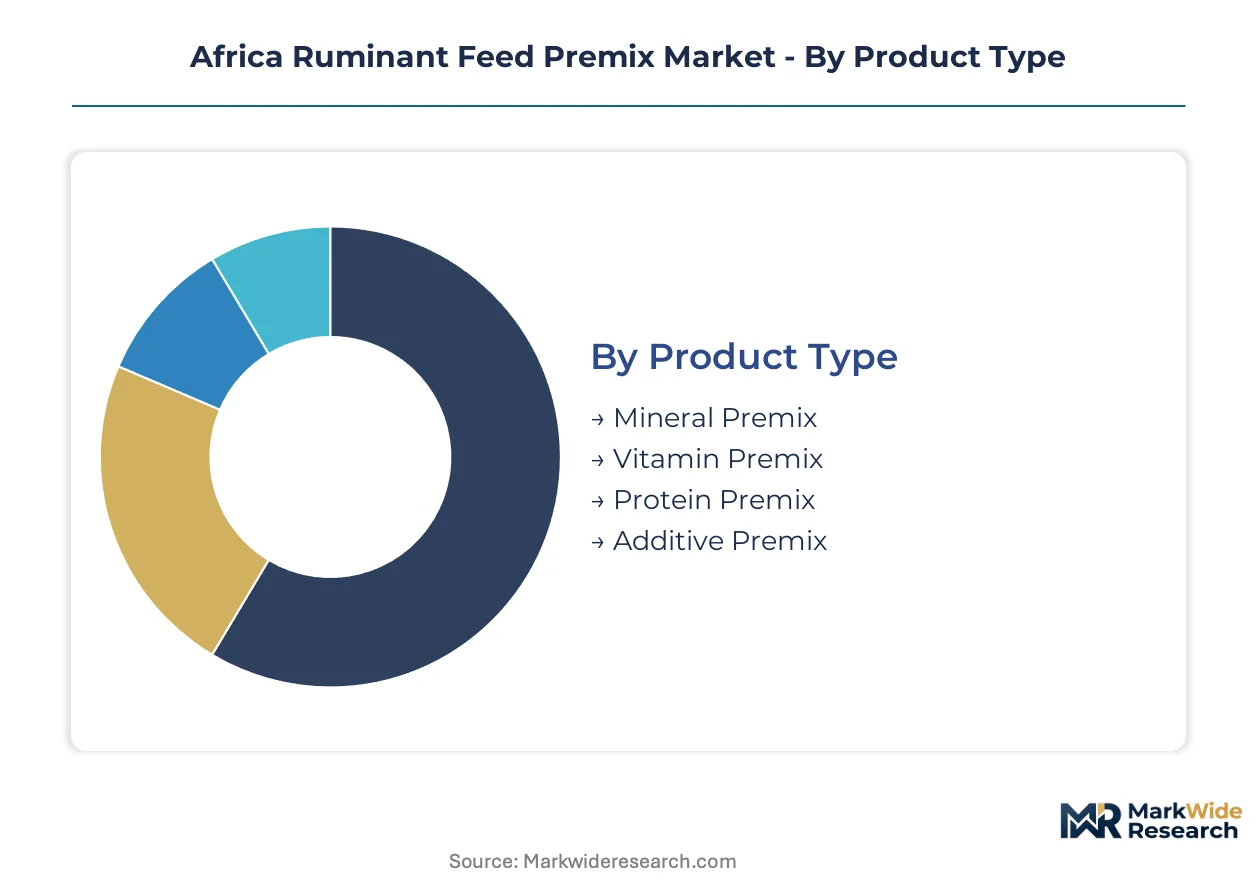
Africa ruminant feed premix denotes a precisely compounded mixture of vitamins, minerals, amino acids, and functional additives dosed at grams per kilogram of total ration to optimize rumen fermentation and nutrient absorption. Manufacturers employ batch blending with near-infrared spectroscopy verification to guarantee micronutrient homogeneity across variable raw material qualities. Mineral premix dominates current volume flows due to widespread soil-deficiency correction needs across East African dairy belts. Protein premix represents the fastest-expanding category as Ethiopian and Kenyan feedlots shift from extensive to semi-intensive finishing systems. Additive premix commands concentrated margin pools where yeast cultures and rumen modifiers address acidosis in high-concentrate diets.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces compulsory registration under the Fertilizers, Farm Feeds, Seeds and Remedies Act, creating compliance barriers for unverified imports. The African Union's Interafrican Bureau for Animal Resources harmonizes cross-border sanitary standards that shape regional trade corridors for premix ingredients. Ethiopia's Ministry of Agriculture implements feed quality certification mandates that redirect procurement toward accredited suppliers. Stakeholders must monitor how divergent national enforcement capacities fragment market access and where harmonization investments yield procurement scale advantages.
Market Dynamics
East African dairy cooperatives are consolidating procurement power through vertical integration into feed manufacturing, compressing distributor margins and forcing premix suppliers to reconfigure their route-to-market strategies around direct technical service models.
Growth Catalysts
- Sahelian mineral deficiency protocols:Ethiopia's Ministry of Agriculture mandates iodine and selenium supplementation in commercial dairy rations, creating guaranteed demand for certified mineral premix formulations across the highland dairy belt.
- Feedlot densification:Nigeria's northern cattle corridor is replacing transhumant grazing with confined finishing operations that require precise amino acid balancing through protein premix to achieve target slaughter weights.
- Near-infrared spectroscopy adoption:South African blending facilities deploy real-time micronutrient verification systems that reduce batch rejection rates and accelerate inventory turnover for high-volume distributors.
Market Restraints
- Input cost volatility:Vitamin A and E prices fluctuate with global fishmeal and palm oil markets, squeezing formulation margins for premix manufacturers serving price-sensitive East African cooperatives.
- Supply concentration risk:China dominates synthetic vitamin precursor production; African blenders face currency mismatch exposure when hedging six-month raw material positions against volatile local exchange rates.
- Regulatory friction:Divergent national enforcement of the African Union's Interafrican Bureau for Animal Resources sanitary standards fragments cross-border ingredient trade and elevates compliance costs for regional suppliers.
Strategic Opportunities
- Kenyan highland dairy expansion:Smallholder cooperatives around Nakuru and Eldoret are professionalizing feed management, opening technical advisory contracts for premix suppliers with embedded veterinary services.
- Rumen modifier convergence:Yeast culture and live yeast additive combinations that stabilize rumen pH in high-concentrate diets command premium positioning in South African commercial beef finishing yards.
- Mobile quality verification:Blockchain-traceable premix certificates accessed via USSD codes are penetrating Nigerian feedlot procurement, displacing paper-based quality assurance documentation.
Industry Challenges
- Technical formulation expertise gap:Few African universities train ruminant nutritionists capable of balancing metabolizable protein against rumen-degradable protein in commercial premix specifications.
- Accreditation timeline compression:Ethiopia's feed quality certification mandates require 18-24 month validation cycles that outpace the operational planning horizons of emerging commercial feedlots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Ruminant Feed Premix Market |
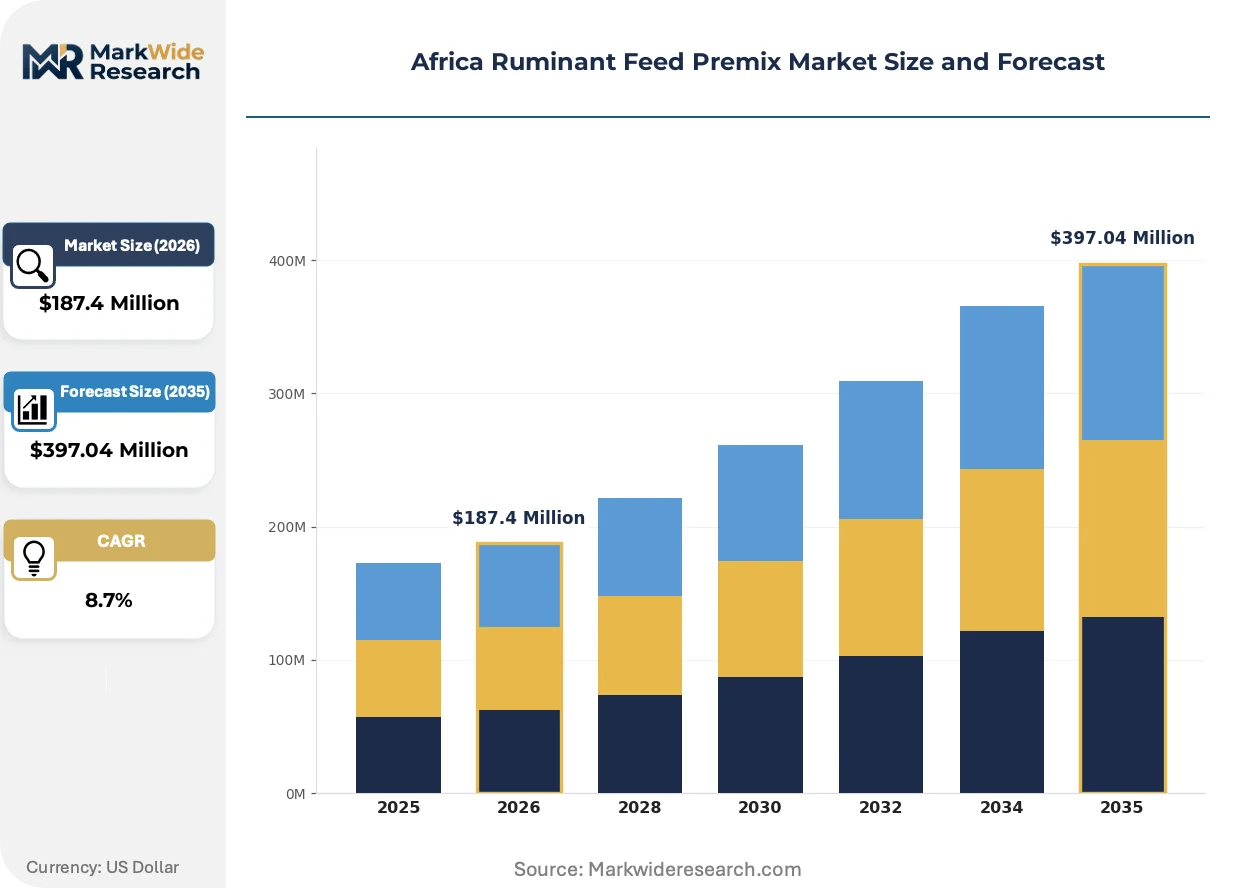
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Premix, Vitamin Premix, Protein Premix, Additive Premix End User: Dairy Farms, Beef Cattle Farms, Goat Farms, Others Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Stores Application: Animal Nutrition, Weight Gain, Milk Production, Health Improvement |
| Companies Covered | BASF SE, Cargill Inc., ADM Animal Nutrition, Nutreco NV, DSM-Firmenich, Charoen Pokphand, Lallemand Inc., Godrej Agrovet Limited, Alltech, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Ruminant Feed Premix Market Strategic Shifts
Precision livestock technologies and regulatory digitization are converging to transform how premix formulations are specified, verified, and procured across African ruminant operations. Three interconnected developments are redefining competitive advantage.
Near-infrared spectroscopy coupled with cloud-based formulation software is digitizing quality assurance workflows at regional blending facilities. Kenyan and South African premix manufacturers deploy these systems to verify micronutrient homogeneity within 90 seconds per batch. Large-scale dairy cooperatives now demand spectroscopic certificates as a condition of supply contracts, compressing the market share of facilities without capital reserves for equipment upgrades.
South Africa's Department of Agriculture, Land Reform and Rural Development is tightening enforcement of the Fertilizers, Farm Feeds, Seeds and Remedies Act through digital registration portals that accelerate product approval timelines for compliant applicants while creating procedural barriers for informal importers. This regulatory digitization favors established manufacturers with dedicated regulatory affairs functions and is redirecting procurement volumes toward accredited domestic blenders in the Gauteng and Western Cape feed manufacturing clusters.
Ethiopian commercial beef feedlots are unbundling premix procurement from complete feed supply, establishing direct technical relationships with specialized mineral and additive premix suppliers. This disintermediation of traditional compound feed distributors concentrates purchasing power among operators with >5,000 head capacities around Addis Ababa and Hawassa. Smaller feedlots retain bundled procurement, creating a bifurcated channel structure that rewards premix suppliers with flexible packaging and logistics configurations.
Africa Ruminant Feed Premix Market Segmentation
Premix procurement patterns diverge sharply across African ruminant operations based on herd scale, technical sophistication, and regulatory exposure. Segment-specific formulation requirements and channel economics determine supplier profitability and route-to-market design.
Product Type:
Inventory velocity varies dramatically: mineral premix turns monthly due to universal soil-deficiency protocols, while additive premix cycles quarterly as feedlot operators test rumen modifier efficacy.
- Mineral Premix:Compounded mixtures of macro and trace minerals dosed at 0.5-2% of total ration mass to correct calcium, phosphorus, and selenium deficiencies endemic to East African highland soils. Demand concentrates in Ethiopian and Kenyan dairy cooperatives where the Ministry of Agriculture mandates iodine supplementation for commercial herds, creating guaranteed procurement volumes for certified suppliers.
- Additive Premix:Functional ingredients including yeast cultures, rumen buffers, and mycotoxin binders delivered at grams-per-ton inclusion rates to stabilize fermentation in high-concentrate finishing diets. Nigerian feedlots in the northern cattle corridor are displacing traditional grazing with confined operations that require acidosis prevention, driving rapid category expansion.
- Vitamin Premix:Fat-soluble and water-soluble vitamin blends stabilized against oxidation for tropical storage conditions.
- Protein Premix:Amino acid concentrates and bypass protein sources for metabolizable protein balancing in semi-intensive systems.
Mineral premix dominates installed base. Additive premix is where expansion concentrates.
End User:
Customer scale determines technical service intensity and contract structure, with large dairy cooperatives demanding embedded nutrition advisory while smallholders purchase through distributor networks.
- Dairy Farms:Commercial milk producers operating 50+ head herds in Kenya's Rift Valley and Ethiopia's central highlands that require precise mineral balancing to sustain lactation curves above 15 liters daily. Procurement is professionalizing through cooperative consolidation around Nakuru and Eldoret, compressing distributor margins and forcing direct supplier relationships.
- Beef Cattle Farms:Feedlot operators in Nigeria's northern corridor and South African commercial yards finishing cattle on high-concentrate rations for 90-120 day periods. These operations unbundle premix procurement from complete feed supply to access specialized rumen modifier formulations, concentrating purchasing power among operators exceeding 5,000 head capacity.
- Goat Farms:Emerging commercial dairy goat operations in South Africa's Western Cape requiring copper and selenium supplementation.
- Others:Smallholder mixed livestock holdings and emerging camel dairy operations in the Horn of Africa.
Dairy farms anchor current volume. Beef cattle farms are gaining share fastest.
Distribution Channel:
Channel selection reflects buyer technical sophistication and regulatory compliance requirements, with accredited direct sales displacing informal retail in formalizing markets.
- Direct Sales:Manufacturer-to-farm relationships supported by technical service teams that formulate rations and verify premix homogeneity through near-infrared spectroscopy. South African and Kenyan large-scale cooperatives mandate direct relationships to satisfy feed safety audit requirements under the Fertilizers, Farm Feeds, Seeds and Remedies Act.
- Distributors:Regional wholesalers stocking standardized mineral premix formulations for small and mid-scale operations without dedicated nutrition staff. Ethiopian distribution networks are consolidating as the Ministry of Agriculture's quality certification mandates redirect procurement toward accredited suppliers with validated supply chains.
- Online Sales:Emerging digital procurement platforms serving tech-adopting commercial farms with traceable documentation.
- Retail Stores:Agro-dealer networks supplying smallholders with generic premix in variable package sizes.
Distributors maintain broadest reach. Direct sales capture margin expansion.
Application:
Functional purpose determines formulation complexity and pricing architecture, with production-targeted applications commanding premium positioning over maintenance nutrition.
- Milk Production:Lactation-stage premix formulations optimizing energy-corrected milk yield through rumen-protected choline and balanced anion-cation differences. Kenyan highland cooperatives professionalizing feed management are the primary demand concentration, opening technical advisory contracts for suppliers with embedded veterinary diagnostics.
- Weight Gain:Finishing-phase premixes maximizing average daily gain through rumen-degradable protein optimization and acidosis prevention. Nigerian feedlot densification is replacing transhumant grazing with confined operations that require precise amino acid balancing to achieve target slaughter weights within compressed timelines.
- Animal Nutrition:Basal maintenance formulations for herd health and reproductive performance.
- Health Improvement:Therapeutic premixes addressing specific deficiency conditions or metabolic disorders.
Animal nutrition holds foundational volume. Milk production commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blending capacity concentrates in South Africa and Nigeria, with satellite operations in Kenya and Ethiopia serving highland dairy belts. East African procurement networks are professionalizing faster than West African feedlot corridors.
South Africa
Commercial beef finishing yards around Gauteng and the Western Cape drive additive premix demand for acidosis prevention in high-concentrate diets. The Department of Agriculture, Land Reform and Rural Development enforces registration under the Fertilizers, Farm Feeds, Seeds and Remedies Act, elevating compliance barriers for informal imports. Cape Town and Port Elizabeth host the continent's most sophisticated near-infrared spectroscopy verification facilities.
Nigeria
Feedlot densification across the northern cattle corridor from Kano to Sokoto is displacing transhumant grazing with confined finishing operations. The country's national agricultural regulator mandates feed safety documentation that redirects procurement toward accredited suppliers. Kaduna and Zaria are emerging as procurement hubs where commercial operators unbundle premix from complete feed supply.
Ethiopia
Highland dairy cooperatives around Addis Ababa and Hawassa are consolidating into professionalized procurement entities. The Ministry of Agriculture implements feed quality certification mandates with 18-24 month validation cycles that favor established suppliers. The central highlands dairy belt generates guaranteed demand for iodine and selenium supplementation protocols.
Kenya
Smallholder cooperatives around Nakuru and Eldoret are shifting from distributor networks to direct manufacturer relationships. Kenya's national agricultural standards body enforces cooperative audit requirements that compress middleman margins. The Rift Valley feed manufacturing cluster is deploying cloud-based formulation software to verify micronutrient homogeneity within 90 seconds per batch.
Africa Ruminant Feed Premix Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in mineral and additive formulation. The supplier base stratifies between multinational nutrition platforms with regional blending facilities and domestic distributors with veterinary service networks. Three archetypes dominate: integrated nutrition platforms, specialized mineral formulators, and veterinary-distribution hybrids. Competitive moves concentrate on backward integration into raw material sourcing and geographic expansion through cooperative technical service contracts.
Among integrated nutrition platforms, BASF SE and DSM-Firmenich occupy positions exemplifying the scale-driven archetype with diversified micronutrient portfolios. Cargill Inc. represents the supply-chain-integrated model with regional blending infrastructure. These anchors sit within a competitive structure where technical advisory capabilities determine contract capture rates among professionalizing dairy cooperatives.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Inc. |
| ADM Animal Nutrition |
| Nutreco NV |
| DSM-Firmenich |
| Charoen Pokphand |
| Lallemand Inc. |
| Godrej Agrovet Limited |
| Alltech |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Kenyan blending facilities is driving supplier consolidation and amplifying pricing power for accredited manufacturers serving East African dairy cooperatives. South Africa's Fertilizers, Farm Feeds, Seeds and Remedies Act compliance costs are compressing margins for informal importers while elevating premium positioning for domestic producers with spectroscopic verification capabilities.
Pricing Analysis
South Africa's Fertilizers, Farm Feeds, Seeds and Remedies Act dictates the pricing tier structure across the African ruminant feed premix landscape. Three-tier pricing separates certified mineral formulations with full regulatory documentation from standard-grade products with partial compliance, and economy-tier generic blends without spectroscopic verification. Price differentiation hinges on certification grade under Ethiopian Ministry of Agriculture mandates and volume scale in Nigerian feedlot procurement. Cost compression in economy-tier vitamin premix is intensifying because of currency mismatch exposure when hedging against volatile local exchange rates. Smallholder cooperatives in Kenya's Rift Valley exhibit the highest price sensitivity, while South African commercial beef yards with embedded veterinary services demonstrate the least.
Supply Chain Analysis
Export-control regimes on synthetic vitamin precursor technologies are constraining raw material flows into African blending operations. Supply concentrates in China for vitamin A and E precursors, South Africa for regional formulation and packaging, and the Netherlands for specialized yeast culture additives. The sector draws from fishmeal derivatives, palm oil stabilizers, and crystalline amino acids as core inputs. Single-source vulnerability in Chinese vitamin precursor production creates acute exposure to supply disruption. Distribution runs through accredited direct sales channels for large-scale cooperatives and consolidated distributor networks for smallholder penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of ruminant nutritionists capable of balancing metabolizable protein against rumen-degradable protein is constraining formulation quality across East African commercial feedlots. This capability gap favors suppliers with captive technical advisory capacity and creates defensive moats for established players with veterinary service networks.
For Market Incumbents: Insulate market position by embedding veterinary diagnostics into technical service contracts with Kenyan highland cooperatives around Nakuru and Eldoret, and accelerate backward integration into mineral sourcing to offset currency volatility in vitamin precursor procurement. The threat of disintermediation by Ethiopian feedlots unbundling premix from complete feed supply demands channel control through direct manufacturer relationships. Certification investment under Ethiopia's 18-24 month validation cycles is the critical lever for procurement redirection. For New Entrants and Emerging Players: Build out mobile quality verification platforms leveraging blockchain-traceable certificates accessed via USSD codes to penetrate Nigerian feedlot procurement in the northern cattle corridor from Kano to Sokoto. The most penetrable segment lies in additive premix for acidosis prevention where yeast culture and live yeast combinations command premium positioning. A veterinary-distribution hybrid go-to-market angle captures smallholder cooperatives transitioning from informal retail to accredited supply. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across near-infrared spectroscopy verification infrastructure as Kenyan and South African facilities deploy real-time micronutrient verification systems. Long-term viability over the next decade rests on technical advisory capabilities rather than commodity blending scale. Acquisition targets should prioritize specialized mineral formulators with validated supply chains under African Union Interafrican Bureau for Animal Resources standards. The signal to watch is consolidation velocity among Ethiopian dairy cooperatives around Addis Ababa and Hawassa as procurement professionalization accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Near-Infrared Spectroscopy Deployment | Real-time verification reduces batch rejection rates at South African blending facilities. |
| Regulatory Certification Investment | Ethiopia's Ministry of Agriculture mandates redirect procurement toward accredited suppliers. |
| Mobile Quality Verification Platforms | Blockchain-traceable USSD certificates displace paper documentation in Nigerian feedlots. |
| Technical Advisory Service Integration | Embedded veterinary diagnostics capture Kenyan cooperative contracts around Nakuru. |
| Backward Integration into Mineral Sourcing | Captive supply of macro and trace minerals hedges against currency volatility exposure. |
Study Parameters
A spread of perspectives from ruminant nutritionists at commercial feedlots, procurement managers at dairy cooperatives, regulatory affairs specialists at blending facilities, and distribution channel partners converged on the working assumptions shaping this analysis. Primary interviews with these stakeholders combined with secondary validation against African Union Interafrican Bureau for Animal Resources sanitary standards, national feed safety filings under South Africa's Fertilizers, Farm Feeds, Seeds and Remedies Act, Ethiopian Ministry of Agriculture certification databases, and customs records of vitamin precursor imports. Bottom-up volume estimates from individual facility capacities triangulated against top-down demand calculations from herd size projections and premix inclusion rate norms.
Demand-supply balance dynamics anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-user scale, distribution channel structure, and application purpose alongside regional regulatory enforcement capacity as an industry-specific dimension. CAGRs derived from fitted growth curves applied to baseline volume and value estimates, with cross-checks against historical adoption patterns in comparable emerging markets. Key forecast inputs incorporated feedlot densification rates in Nigeria's northern cattle corridor and dairy cooperative consolidation velocity in Kenya's Rift Valley.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational nutrition platforms with regional blending infrastructure would shift outcomes beyond modeled ranges. Material shifts in African Union sanitary standard harmonization enforcement or abrupt changes in Chinese vitamin precursor export licensing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Herd Management Software Market
Livestock Management
Animal Identification Market
Livestock Management
Layer Feed Market
Livestock Management
Roughage Feed Market
Livestock Management
North America Ruminant Feed Premix Market
Livestock Management
Bird Feeder Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Animal Feed Protease Market
Livestock Management
Hog Production and Pork Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
Morocco Poultry Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Livestock Dewormers Market
Livestock Management
North America Feed Binders Market
Livestock Management
Cattle Feeder Market