
 Layer Breeding System Market | 2026-2036
Layer Breeding System Market Size, Share, and Industry Trends Forecast 2026-2036
Layer Breeding System Market Insights
Plastic composites are decoupling from galvanized steel in layer cage construction, cutting corrosion-related replacement costs for tropical installations. Big Dutchman leverages its European manufacturing base to supply fully automated aviary systems across Germany and the Netherlands. Chore-Time Brock anchors North American demand through integrated feeding and climate control packages designed for large-scale operations. Vencomatic Group specializes in welfare-oriented nest and perch configurations that command premium positioning in Scandinavian markets.
A layer breeding system encompasses the integrated housing, feeding, climate control, and egg collection infrastructure purpose-built for maintaining and reproducing genetically selected laying hen populations, typically operating at densities of 60-90 birds per square meter in enriched cage configurations while managing ventilation rates of 3-6 cubic meters per hour per kilogram of live weight. The primary commercial purpose centers on maximizing egg production efficiency while enabling genetic progress through controlled pedigree tracking and performance recording across multi-generation breeding pyramids. Hybrid product lines dominate commercial volume due to their heterosis-driven feed conversion advantages, while genomic selection technology captures the fastest expansion as SNP arrays and imputation pipelines slash generation intervals from twelve months to under six. Traditional breeding methods retain significant share in developing markets where capital constraints limit laboratory infrastructure deployment.
EU Green Deal farm-to-fork targets and REACH chemical compliance for cage coatings are tightening product specifications across European member states, while FDA veterinary feed directive rules and USDA organic certification standards shape input and housing requirements in United States operations. China's GB standards for livestock facility construction and NMPA oversight of veterinary biologics used in breeding programs add compliance layers for equipment and genetic material suppliers. Stakeholders must monitor divergence between welfare-driven European regulations and productivity-focused standards in major exporting nations when allocating R&D and certification investments.
Market Dynamics
Genomic selection is compressing breeding cycles from twelve months to under six, forcing capital redeployment toward SNP array infrastructure and pedigree tracking systems across multi-generation breeding pyramids.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Member states face binding reductions in agricultural emissions, accelerating cage-free aviary system installations in Germany and the Netherlands.
- Embrapa tropical genetics programs:Brazil's agricultural research corporation advances heat-tolerant layer lines suited to Southeast Asian climatic stress, opening export corridors for breeding stock.
- Automated climate control:Precision ventilation systems managing 3-6 cubic meters per hour per kilogram of live weight cut mortality in high-density configurations across commercial poultry farms.
Market Restraints
- Galvanized steel price volatility:Cage construction materials face input cost swings that destabilize equipment procurement budgets for mid-scale operators.
- REACH chemical compliance:European coating standards add certification layers that extend lead times for cage manufacturers supplying EU member states.
- Laboratory infrastructure gaps:Capital constraints in developing markets limit deployment of genomic selection pipelines, trapping breeders in traditional twelve-month generation intervals.
Strategic Opportunities
- Scandinavian welfare premium positioning:Nest and perch configurations command price differentiation in markets where consumer sentiment drives retail egg labeling requirements.
- China's cage-free transition guidelines:Ministry of Agriculture and Rural Affairs mandates create equipment replacement cycles across provincial commercial farms.
- SNP array and imputation pipeline convergence:Genomic selection technology merges with automated performance recording to enable real-time genetic progress tracking.
Industry Challenges
- Multi-generational pedigree tracking complexity:Breeding pyramids require integrated data systems spanning parent stock through commercial layers, creating IT integration bottlenecks.
- Veterinary biologics compliance timelines:NMPA oversight in China and FDA veterinary feed directive rules in the United States impose parallel certification tracks that fragment R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Layer Breeding System Market |
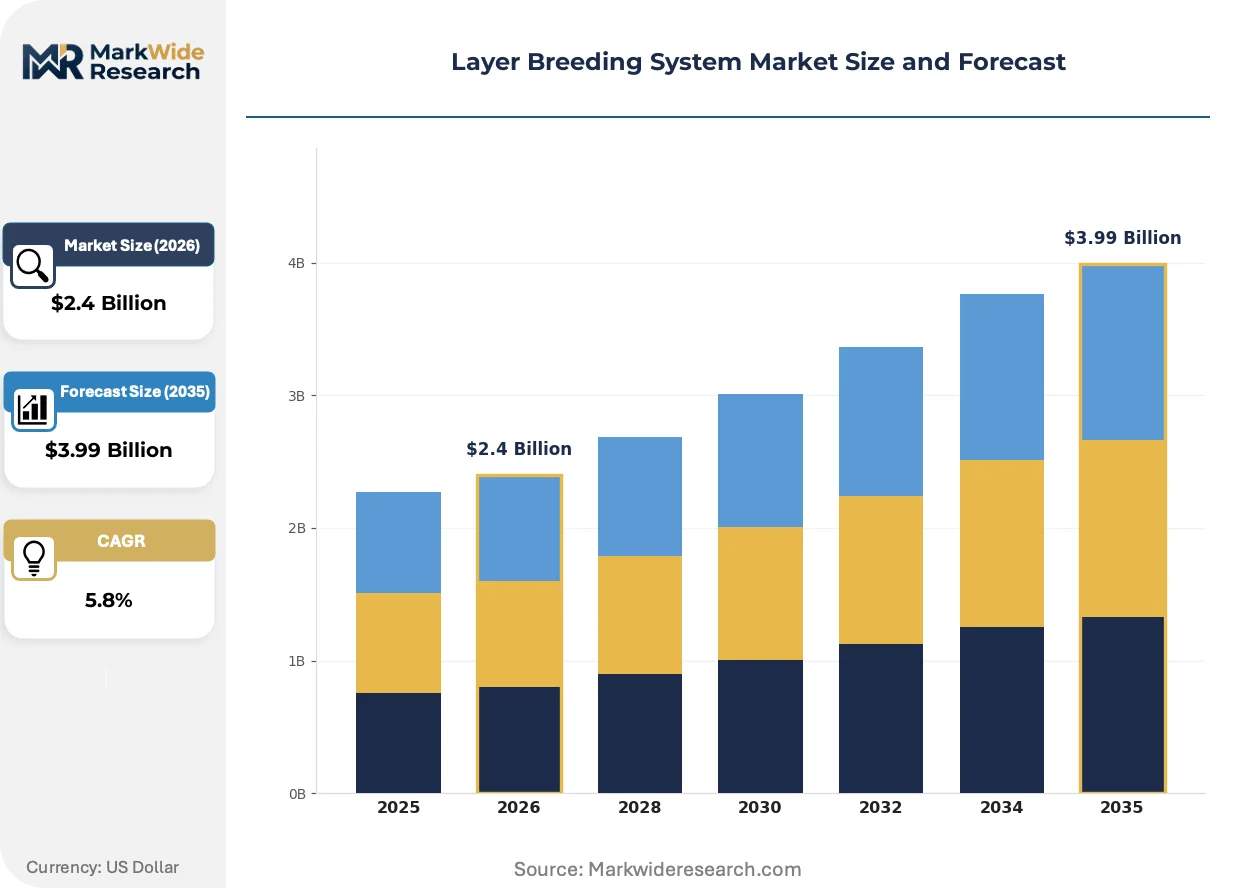
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
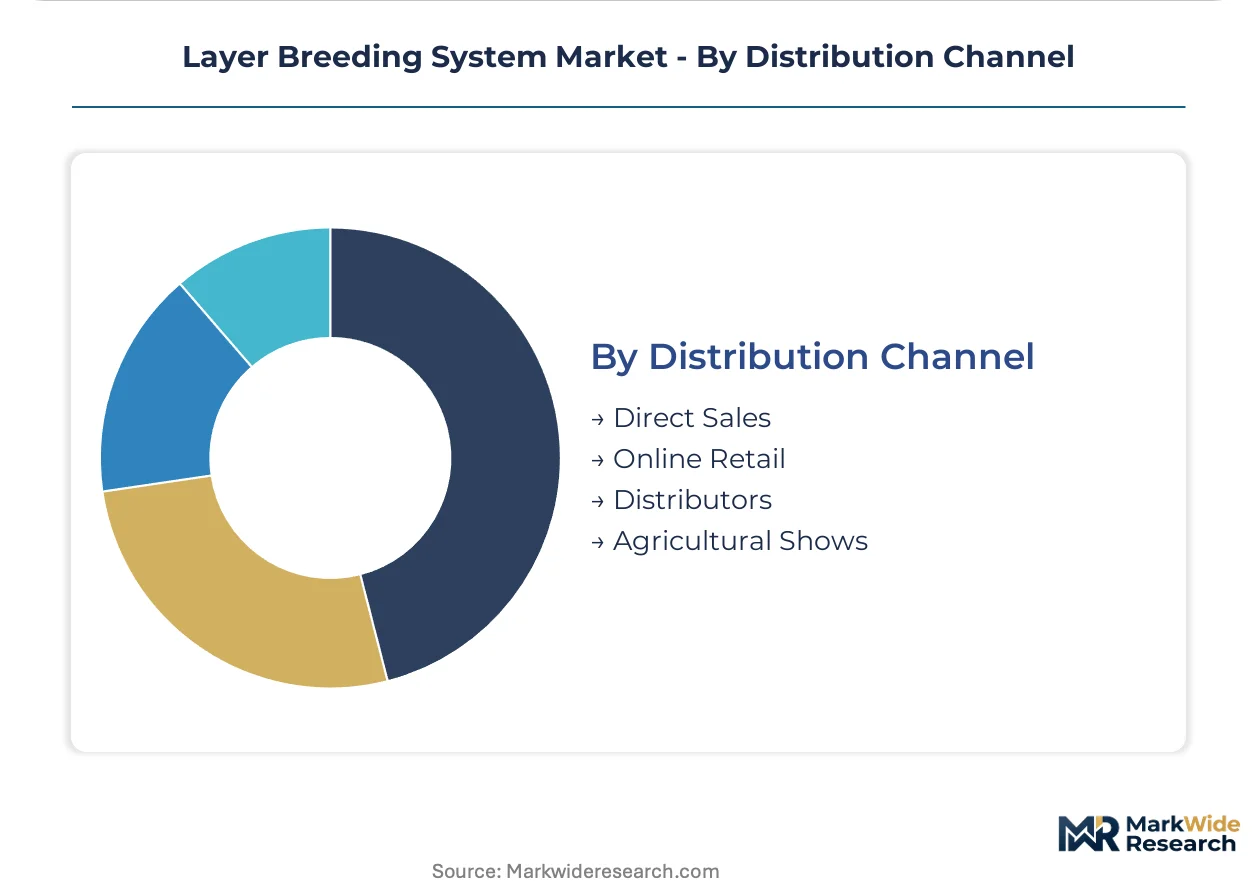
| Segmentation | Product Type: Hybrid, Pure Line, Commercial, Backcross Breeding Technology: Traditional, Genomic Selection, Marker-Assisted Selection, CRISPR End User: Poultry Farms, Research Institutions, Breeding Companies, Consultants Distribution Channel: Direct Sales, Online Retail, Distributors, Agricultural Shows |
| Companies Covered | Big Dutchman, Chore-Time Brock, Facco, Big Herdsman Machinery, Guangdong Guangxing, Shanghai Extra Machinery, Texha, Vencomatic Group, Lohmann Breeders, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Layer Breeding System Market Trends and Innovations
Automation is penetrating layer housing at the intersection of climate control, feeding precision, and egg collection robotics, compressing labor inputs while tightening environmental parameter management.
Sensor-driven ventilation algorithms are converging with machine learning-based feed optimization to enable real-time microclimate adjustments at the cage row level. Large-scale operations in the Netherlands and Germany deploy these integrated systems to maintain 60-90 birds per square meter densities without heat stress mortality spikes. This convergence is compressing the performance gap between enriched cage and aviary configurations on feed conversion metrics.
China's GB standards for livestock facility construction are tightening structural specifications for multi-tier cage systems in provincial breeding centers. The industrial consequence is a qualification barrier for equipment suppliers lacking in-country testing infrastructure. Domestic manufacturers with established relationships with the Ministry of Agriculture and Rural Affairs capture provincial procurement tenders that exclude European competitors on compliance timeline grounds.
Retail-led certification requirements are reshaping buyer specifications for welfare-tracked egg supply chains. German and Dutch supermarket chains now mandate third-party audited perch access and nesting behavior metrics that propagate backward through breeding stock contracts. Scandinavian integrated producers respond by specifying aviary-compatible genetic lines from the grandparent generation, locking in housing configuration decisions three breeding cycles ahead of commercial flock placement.
Layer Breeding System Market Segmentation

Layer breeding system buyers face divergent capital constraints and genetic sophistication requirements across commercial, research, and breeding company channels. Segmentation reveals where hybrid volume economics clash with genomic selection infrastructure investments, and which distribution paths capture provincial procurement versus international equipment tenders.
Product Type:
Cost tier separates commodity egg producers from pedigree breeding operations with multi-generation tracking obligations.
- Hybrid:Crossbred lines exploit heterosis for feed conversion efficiency in commercial layer flocks. Demand concentrates in Southeast Asian poultry farms expanding automated housing capacity, driven by genomic selection tools compressing breeding cycle timelines.
- Pure Line:Genetically stable populations serve as foundational stock for hybrid breeding pyramids. Breeding companies in Germany and the Netherlands maintain these lines under strict pedigree protocols to supply grandparent stock contracts.
- Commercial:Terminal cross products deliver standardized laying performance for egg production facilities.
- Backcross:Specialized lines reintroduce specific traits into breeding populations through controlled mating programs.
Volume sits with Hybrid; growth tilts toward Pure Line as pedigree tracking infrastructure expands.
Breeding Technology:
Application maturity ranges from capital-light phenotypic selection to laboratory-dependent genomic pipelines.
- Genomic Selection:SNP arrays and imputation algorithms slash generation intervals from twelve months to under six. Research institutions in Brazil leverage Embrapa's tropical genetics programs to accelerate heat-tolerant layer line development.
- Traditional:Phenotype-based selection persists where laboratory infrastructure gaps constrain capital deployment. Poultry farms across developing markets retain these methods due to equipment procurement budget limitations.
- Marker-Assisted Selection:DNA markers guide trait selection without full genomic sequencing infrastructure.
- CRISPR:Gene editing enables precise trait modification in experimental breeding programs.
Traditional methods retain volume dominance; Genomic Selection climbs fastest as SNP infrastructure costs decline.
End User:
Customer type determines whether procurement emphasizes equipment durability, research flexibility, or genetic material traceability.
- Poultry Farms:Commercial operations prioritize housing density optimization and automated climate control systems managing 3-6 cubic meters per hour per kilogram of live weight.
- Breeding Companies:Integrated genetic suppliers require multi-generational pedigree tracking across parent stock and commercial layer pyramids.
- Research Institutions:Academic and government facilities conduct trait validation and tropical adaptation studies.
- Consultants:Advisory services guide farm conversion to cage-free configurations under tightening welfare guidelines.
Poultry Farms absorb the heaviest equipment volume; Breeding Companies drive premium system specifications.
Distribution Channel:
Supply concentration varies between provincial tender processes and direct manufacturer relationships for large-scale deployments.
- Direct Sales:Manufacturers with in-country testing infrastructure capture procurement tenders under China's GB standards for livestock facility construction. Domestic suppliers with Ministry of Agriculture and Rural Affairs relationships exclude European competitors on compliance timelines.
- Distributors:Regional networks serve mid-scale operators in markets where galvanized steel price volatility destabilizes equipment budgets.
- Online Retail:Digital platforms facilitate spare parts and component procurement for existing system maintenance.
- Agricultural Shows:Trade exhibitions enable equipment demonstration and welfare-oriented nest configuration showcasing for Scandinavian buyers.
Direct Sales command the largest transaction values; Distributors penetrate fragmented mid-scale demand most deeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the heaviest equipment procurement volume as provincial breeding centers modernize multi-tier cage infrastructure under tightened GB standards. Brazil's tropical genetics programs and Southeast Asia's automated housing expansion create secondary demand poles with distinct climatic adaptation requirements.
China
Provincial commercial farms drive equipment replacement cycles under Ministry of Agriculture and Rural Affairs cage-free transition guidelines. GB standards for livestock facility construction now mandate structural specifications that exclude European competitors lacking in-country testing infrastructure. Domestic manufacturers with established regulator relationships capture procurement tenders across Jiangsu and Shandong breeding clusters.
Brazil
Embrapa's tropical-adapted layer genetics programs open export corridors for heat-tolerant breeding stock into Southeast Asian markets. ANVISA veterinary biologics oversight shapes compliance timelines for genetic material shipments. São Paulo and Minas Gerais house integrated breeding operations that supply grandparent stock contracts across Latin American poultry networks.
Germany
EU Green Deal farm-to-fork targets accelerate aviary system installations across Lower Saxony and Bavaria commercial operations. REACH chemical compliance for cage coatings extends manufacturer lead times while reshaping supplier qualification criteria. Big Dutchman leverages its European manufacturing base to supply fully automated systems meeting welfare-tracked egg supply chain mandates.
Netherlands
Retail-led certification requirements from supermarket chains mandate third-party audited perch access metrics that propagate through breeding stock contracts. Vencomatic Group specializes in welfare-oriented nest configurations commanding premium positioning in this market. Precision ventilation systems managing 3-6 cubic meters per hour per kilogram of live weight deploy across high-density operations in Gelderland and Noord-Brabant.
United States
USDA organic certification standards and FDA veterinary feed directive rules shape input and housing requirements for large-scale operations. Chore-Time Brock anchors North American demand through integrated feeding and climate control packages. Midwest poultry belts in Iowa and Indiana concentrate automated layer housing capacity expansion as genomic selection tools reduce breeding cycle timelines.
Layer Breeding System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system providers commanding premium positioning in welfare-regulated European markets while regional fabricators serve cost-sensitive procurement in developing economies. The vendor base organizes into three strategic archetypes: European welfare-system specialists, North American integrated-package providers, and Asian scale manufacturers. Competitive moves concentrate on geographic licensing partnerships and in-country testing infrastructure deployment to satisfy divergent certification timelines.
Among European welfare-system specialists, Vencomatic Group exemplifies premium-tier positioning through welfare-oriented configuration expertise. Big Dutchman occupies a position as an integrated-system anchor with manufacturing concentration in Germany and the Netherlands. Chore-Time Brock represents the North American integrated-package archetype, serving large-scale operations with combined feeding and climate control offerings. These three companies illustrate how geographic origin and product-system integration level stratify competitive positioning across regulatory environments.
| Leading Market Players |
|---|
| Big Dutchman |
| Chore-Time Brock |
| Facco |
| Big Herdsman Machinery |
| Guangdong Guangxing |
| Shanghai Extra Machinery |
| Texha |
| Vencomatic Group |
| Lohmann Breeders |
| Others |
Pricing and Supply Chain Analysis
Welfare-certification tier divergence between EU-compliant aviary systems and commodity cage configurations splits pricing power across divergent supply chain footprints. Premium nest-and-perch configurations command 40-60% equipment cost premiums over standard enriched cages, with Scandinavian retail mandates propagating backward through grandparent stock contracts to lock in housing decisions three breeding cycles ahead.
Pricing Analysis
Volume-vs-margin split concentrates commodity equipment sales in Southeast Asian expansion projects while welfare-premium systems capture margin in European markets. Three-tier pricing structure across premium aviary, standard enriched cage, and economy retrofit configurations reflects certification grade and automation depth as primary differentiation drivers. Pricing pressure stems from galvanized steel input volatility destabilizing mid-scale operator procurement budgets. Smallholder cooperatives in developing markets exhibit highest price sensitivity; integrated European producers demonstrate lowest sensitivity due to retail-led certification requirements.
Supply Chain Analysis
Dual-sourcing requirements from large-scale operators mandate multi-supplier qualification across equipment manufacturers to mitigate single-source vulnerability. Manufacturing concentrates in Germany, the Netherlands, and China, with domestic Chinese suppliers capturing provincial tenders through Ministry of Agriculture and Rural Affairs relationships. Supply chains draw from galvanized steel, plastic composites, and precision ventilation components. Tariff exposure on European-manufactured systems entering Chinese markets creates procurement timeline fragmentation. Distribution runs through direct sales for large-scale deployments and regional distributor networks for mid-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration race dynamics intensify as breeding companies pursue captive control over SNP array infrastructure and pedigree tracking systems to compress generation intervals below six months.
For Market Incumbents: To counter genomic selection technology commoditization, Big Dutchman and Vencomatic Group should deepen backward integration into precision ventilation component manufacturing and secure exclusive certification partnerships with EU Green Deal implementation bodies. Capacity expansion in Jiangsu and Shandong breeding clusters captures China's cage-free transition replacement cycles. For New Entrants and Emerging Players: Enter via tropical-adapted genetics equipment white space opened by Embrapa's heat-tolerant layer programs targeting Southeast Asian climatic stress. Brazil-to-Asia export corridors for breeding stock infrastructure remain underpenetrated by established European suppliers. Go-to-market angle: partner with provincial agricultural universities for in-country testing infrastructure deployment. For Investors and Strategic Acquirers: Re-rating potential sits with SNP array infrastructure specialists given convergence with automated performance recording enabling real-time genetic progress tracking. Long-term viability favors breeding technology platforms over pure equipment manufacturers. Signal to watch: NMPA veterinary biologics compliance timeline acceleration in China as inflection indicator for genetic material supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SNP Array Infrastructure | Captive control over genomic selection pipelines compresses generation intervals from twelve months to under six. |
| In-Country Testing Infrastructure Deployment | Domestic qualification under China's GB standards excludes European competitors on compliance timeline grounds. |
| Welfare Certification Partnership | Third-party audited perch access metrics propagate through German and Dutch supermarket chain mandates. |
| Tropical Genetics Equipment Development | Heat-tolerant layer line infrastructure opens Brazil-to-Southeast Asia export corridors for breeding stock. |
| Multi-Generational Pedigree Tracking Platform | Integrated data systems spanning parent stock through commercial layers resolve IT integration bottlenecks. |
Research Methodology
Trade databases, veterinary biologics regulatory filings, and poultry equipment customs records formed the secondary backbone for this analysis. Primary interviews with breeding company geneticists, provincial procurement officers at China's Ministry of Agriculture and Rural Affairs, climate control system engineers, and grandparent stock contract managers validated demand assumptions. Bottom-up equipment shipment tallies triangulated against top-down breeding pyramid population estimates.
Historical trendline analysis tracked automated housing capacity expansion and genomic selection adoption curves across the projection horizon. Segmentation modeling incorporated product type tier, breeding technology maturity, end-user scale classification, and distribution channel concentration. CAGRs derived from equipment procurement cycle timing and genetic material shipment patterns. Forecast inputs included SNP infrastructure cost decline trajectories and cage-free transition mandate implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under galvanized steel price volatility spikes and REACH chemical compliance timeline extensions. Deviation in China's provincial tender award timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Layer Feed Market
Livestock Management
Morocco Poultry Market
Livestock Management
Swine Feed Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
China Swine Feed Market
Livestock Management
Hog Production and Pork Market
Livestock Management
Cattle Feeder Market
Livestock Management
Europe Swine Feed Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Cattle Head Catch Market
Livestock Management
Cattle Squeeze Market
Livestock Management
Pig Feed Market
Livestock Management
Poultry Concentrate Market
Livestock Management
Global Smart Ear Tags Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Poultry Feed Market