
 Animal Feed Protease Market | 2026-2036
Animal Feed Protease Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed Protease Market Analysis
A capital-intensity divergence between integrated enzyme manufacturers and formulation specialists is bifurcating competitive returns in the animal feed protease sector. Novonesis leverages its microbial strain libraries and fermentation infrastructure to sustain cost advantages in bulk neutral-protease production. Kemin Industries anchors its position through precision-delivery technologies that protect enzyme activity during pelleting. BASF SE competes by extending its global distribution network into aquaculture-intensive zones where technical service requirements run high.
Animal feed protease denotes a class of hydrolytic enzymes that cleave peptide bonds in dietary proteins, typically operating at pH ranges between 2.5 and 7.5 depending on the specific protease class, to liberate absorbable amino acids and reduce antinutritional factors in soybean and rapeseed meals. The primary industrial purpose centers on improving protein digestibility coefficients, lowering nitrogen excretion rates, and enabling partial substitution of expensive protein meals with lower-quality alternatives. Microbial-sourced proteases dominate volume flows due to scalable submerged fermentation yields and regulatory familiarity, while acid-protease variants command premium positioning in gastric pH-optimized poultry applications. Powder formulations retain the largest share of commodity shipments, though liquid proteases are gaining traction in automated dosing systems at integrated feed mills.
The European Food Safety Authority evaluates novel proteases under Regulation EC 1831/2003, creating a multi-year approval timeline that filters out undercapitalized entrants. The U.S. Food and Drug Administration and the Association of American Feed Control Officials jointly oversee enzyme categorization, with GRAS self-affirmation pathways offering faster market access for well-characterized strains. China's Ministry of Agriculture and Rural Affairs maintains a positive list system for feed additives that restricts import eligibility. Stakeholders must monitor evolving substrate-specificity requirements as precision nutrition programs demand proteases tailored to regionally dominant protein sources rather than generic broad-spectrum formulations.
Market Dynamics
The animal feed protease sector is compressing around substrate-specific formulations as precision nutrition programs replace generic broad-spectrum enzymes. Feed mills now demand proteases calibrated to regional protein meals rather than one-size-fits-all solutions, forcing manufacturers to rebuild strain libraries around local soybean, rapeseed, and fishmeal compositions.
Growth Catalysts
- EU Feed Additives Regulation:Tighter nitrogen emission standards under EC 1831/2003 are mandating enzyme adoption to reduce environmental discharge from livestock operations.
- Poultry sector expansion:Southeast Asian broiler producers are scaling enzyme programs to improve feed conversion ratios amid volatile soybean meal pricing.
- Fermentation yield improvements:Submerged bioreactor optimization is decomposing unit production costs for microbial-sourced proteases.
Market Restraints
- Multi-year EFSA approval timelines:Novel protease strains face 24-36 month safety evaluations that filter out undercapitalized entrants.
- Concentrated fermentation capacity:Bulk neutral-protease supply clusters in Denmark and China, creating geographic vulnerability to energy price shocks.
- Acid-protease thermal stability limits:Gastric-optimized variants degrade during high-temperature pelleting above 85°C, restricting formulation flexibility.
Strategic Opportunities
- Vietnam aquaculture penetration:Shrimp and pangasius feed producers remain undersupplied with protease formulations optimized for fishmeal substitution.
- Automated liquid dosing systems:Integrated feed mills are retrofitting spray lines that favor liquid protease delivery over powder handling.
- Brazilian export certification alignment:Protease suppliers securing MAPA equivalency can access Mercosur protein meal trade flows.
Industry Challenges
- Strain characterization documentation:GRAS self-affirmation pathways require exhaustive whole-genome sequencing that strains analytical budgets.
- Pelleting temperature protocols:Protecting enzyme activity through conditioning and cooling stages demands capital-intensive process control upgrades.
- Cross-border positive list navigation:China's Ministry of Agriculture and Rural Affairs maintains import restrictions that complicate multi-territory product registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed Protease Market |
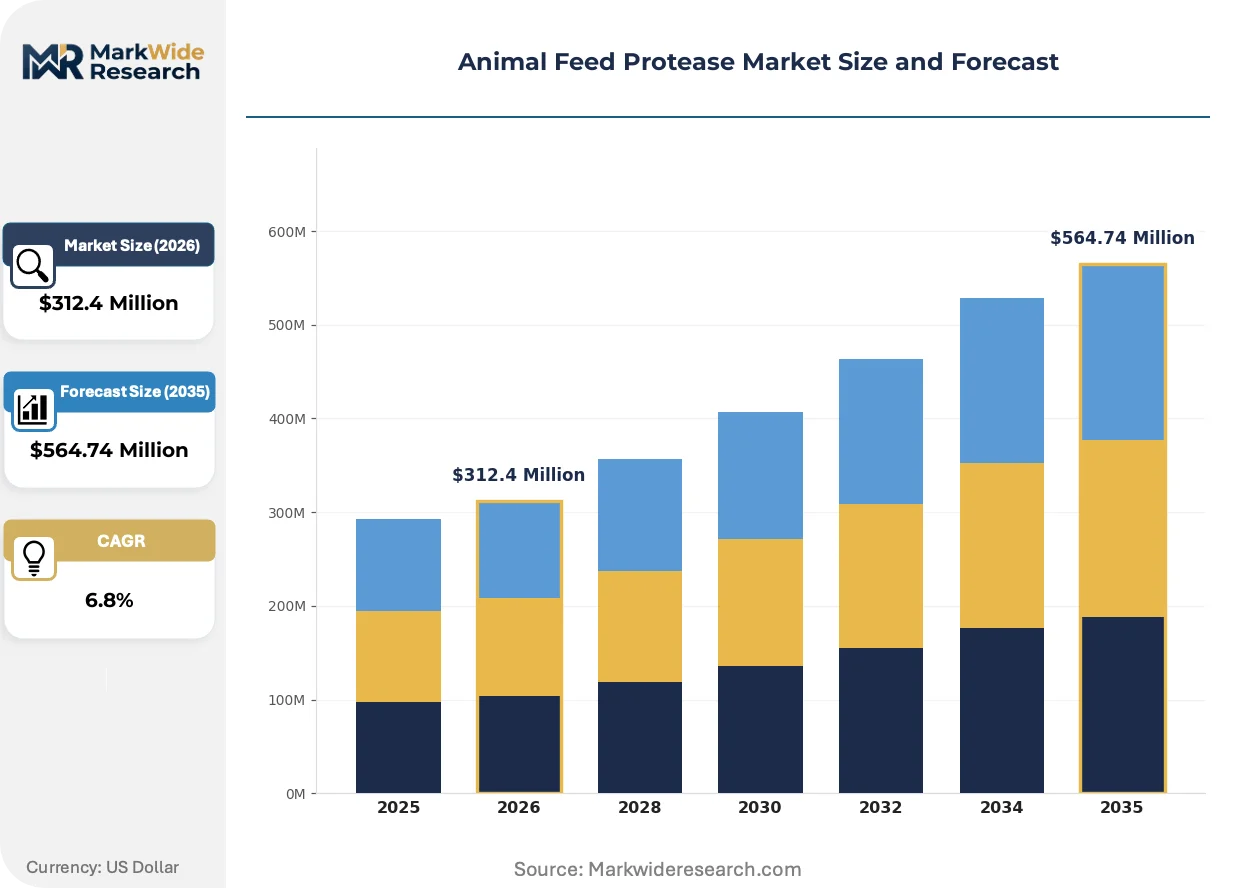
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endo-Protase, Exo-Protase, Acid-Protase, Neutral-Protase Source: Microbial, Plant, Animal, Fermentation Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granules, Pellets |
| Companies Covered | International Flavors & Fragrances, Kemin Industries, Novonesis, Cargill, Associated British Foods, BASF SE, Adisseo, Archer Daniels Midland, DSM-Firmenich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed Protease Market Emerging Trajectories
Protease engineering is pivoting from activity maximization toward stability optimization as feed processing intensifies. Manufacturers now prioritize enzyme survival through pelleting over raw catalytic efficiency.
Encapsulation technology is decomposing the trade-off between thermal protection and release kinetics. Precision-delivery coatings using lipid matrices or polymer shells shield acid-proteases through conditioning temperatures above 90°C. Poultry integrators in Thailand and Vietnam are adopting these formulations at accelerating rates. The structural consequence is decomposing price premiums for unprotected liquid alternatives in automated dosing applications.
EFSA's 2023 guidance on microbial production strains is tightening characterization requirements for novel proteases. The regulation now demands whole-genome sequencing and comparative pathogenicity assessments that extend development timelines. European compound feed manufacturers are responding by consolidating supplier relationships toward established strain libraries rather than experimental candidates.
Integrated feed mills are consolidating procurement around full-service enzyme packages that bundle protease, carbohydrase, and phytase dosing. This bundling displaces standalone protease purchasing in automated facilities. The shift is most visible in Brazil's southern feed corridor, where Cargill and BRF-aligned mills are negotiating multi-enzyme supply agreements with single-source technical service providers.
Animal Feed Protease Market Segmentation
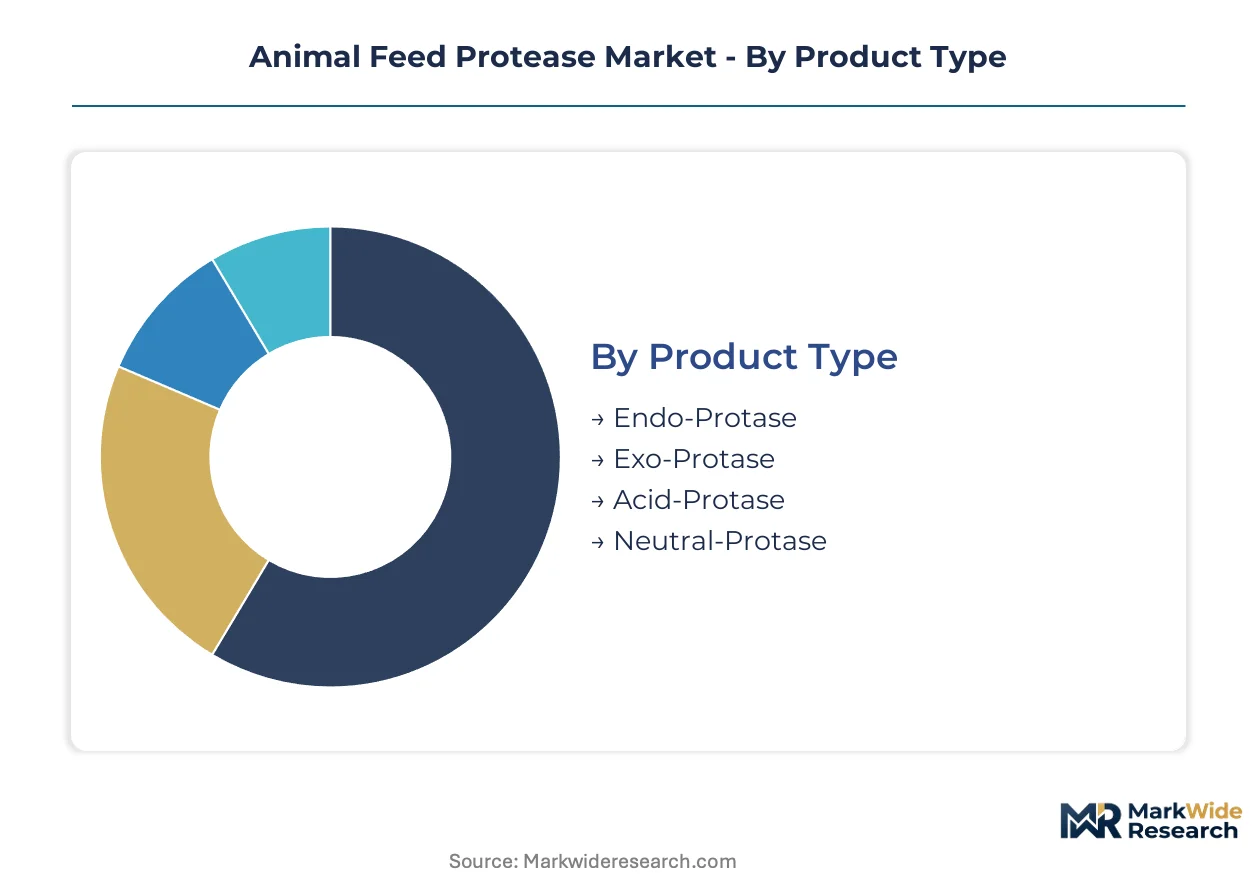
Segmentation in the animal feed protease market reflects divergent technical requirements across livestock species and processing conditions. Manufacturers calibrate strain selection, formulation stability, and dosing systems to match the digestive physiology of target animals and the thermal stress of feed manufacturing.
Product Type:
Domestic consumption in Vietnam and Thailand drives demand for acid-stable variants, while export-oriented Brazilian mills favor neutral-protease formulations compatible with Mercosur trade specifications.
- Endo-Protase:Cleaves internal peptide bonds within protein chains, generating polypeptides of varying lengths. Brazilian poultry integrators deploy these enzymes to improve soybean meal digestibility in high-density broiler rations. Thermal degradation during pelleting above 85°C remains the primary constraint for unprotected formulations.
- Exo-Protase:Hydrolyzes terminal amino acids from peptide chain ends, liberating free amino acids for direct absorption. Shrimp feed producers in Vietnam's Mekong Delta specify exo-protease blends to maximize fishmeal substitution rates in low-protein aquaculture diets. The segment commands premium positioning due to strain development complexity.
- Acid-Protase:Optimized for gastric pH environments between 2.5 and 3.5, these variants dominate poultry applications where proventriculus conditions favor acid-stable catalysis.
- Neutral-Protase:Operates at pH 6.0 to 7.5, making these enzymes suitable for ruminant and swine applications where intestinal pH neutrality prevails.
Neutral-protase holds the largest share; momentum sits with acid-protase as Southeast Asian poultry expansion accelerates.
Source:
Cost tiers separate fermentation-derived enzymes from extraction-based alternatives, with capital intensity determining competitive positioning across supplier categories.
- Microbial:Submerged fermentation of Bacillus subtilis or Aspergillus oryzae strains yields scalable, consistent protease titers. Danish and Chinese fermentation clusters supply the bulk of global volume, with Denmark's Novonesis and China's major state-owned enzyme producers anchoring regional supply.
- Fermentation:Advanced bioreactor optimization and strain engineering now push specific productivity above 50,000 units per milliliter in industrial-scale production. Vietnamese import demand concentrates on fermentation-sourced acid-proteases for automated dosing systems.
- Plant:Papain and bromelain extracts from papaya and pineapple tissue retain niche positioning in organic-certified feed segments.
- Animal:Pancreatic extracts and other tissue-derived proteases face regulatory headwinds under EFSA transmissible spongiform encephalopathy guidelines, restricting deployment in European compound feeds.
Microbial sources dominate volume; fermentation is climbing the fastest as yield improvements compress unit economics.
Application:
Customer type fragmentation separates integrated poultry operators from independent aquaculture feed mills, with technical service requirements driving supplier selection.
- Poultry:Broiler and layer operations in Thailand, Vietnam, and Brazil represent the primary demand concentration. Feed conversion ratio improvements of 3-5 percentage points justify enzyme program investments amid volatile soybean meal pricing. Acid-protease formulations optimized for proventriculus pH command the largest share of poultry-specific procurement.
- Aquaculture:Shrimp and pangasius producers in Vietnam's Mekong Delta and Indonesia's Java Sea corridor drive formulation innovation. Proteases enabling partial fishmeal substitution address sustainability certification requirements for European export markets.
- Swine:Post-weaning diets in Brazilian farrow-to-finish operations incorporate neutral-proteases to reduce soybean antigen exposure in piglet gut development.
- Ruminants:Dairy and beef operations deploy proteases to improve bypass protein utilization, though rumen microbial degradation limits enzyme efficacy compared to monogastric applications.
Poultry holds the largest share; aquaculture is gaining share fastest as fishmeal substitution pressures intensify.
Form:
Supply concentration in powder processing equipment versus liquid dosing infrastructure creates divergent distribution economics across formulation types.
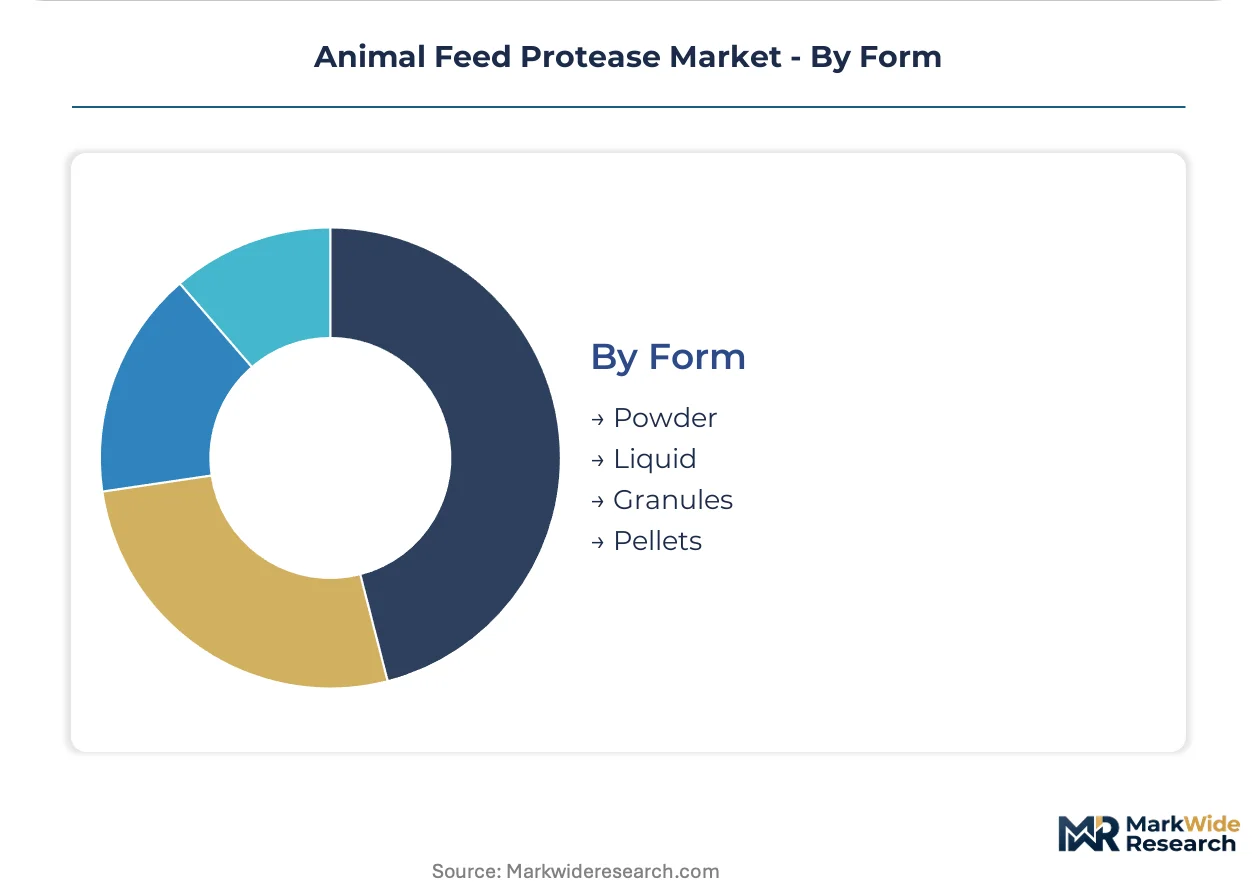
- Powder:Spray-dried enzyme concentrates blended with carriers such as wheat middlings or rice hulls retain dominant volume share. Brazilian and Vietnamese feed mills with legacy handling equipment favor powder logistics, though dust exposure and dosing inconsistency create operational friction.
- Liquid:Stabilized aqueous formulations enable precision dosing through automated spray systems at integrated feed mills. Thailand's Charoen Pokphand-aligned facilities and Brazil's southern feed corridor are retrofitting liquid lines at accelerating rates.
- Granules:Agglomerated enzyme preparations with improved flow characteristics address handling challenges in humid tropical climates.
- Pellets:Enzyme incorporation directly into feed pellets during extrusion requires thermal protection technologies that add formulation cost.
Powder holds the largest share; liquid is expanding most quickly as automation investment concentrates in integrated mill networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnam and Thailand demonstrate the highest price elasticity, squeezing margins on unprotected liquid formulations, while Brazilian integrators absorb premium encapsulation costs to secure export certification compliance.
Brazil
Poultry integrators in São Paulo and Paraná states are retrofitting automated liquid dosing lines to capture feed conversion improvements. The Ministry of Agriculture, Livestock and Food Supply maintains MAPA equivalency requirements that filter import eligibility for enzyme suppliers. Southern feed mills aligned with BRF and JBS are consolidating procurement around multi-enzyme technical service packages.
Vietnam
Shrimp and pangasius producers in the Mekong Delta drive acid-protease demand for fishmeal substitution in low-protein aquaculture diets. The Ministry of Agriculture and Rural Affairs restricts import eligibility through a positive list system for feed additives. Ho Chi Minh City-based feed compounders are accelerating adoption of encapsulated formulations to survive pelleting temperatures above 85°C.
Thailand
Charoen Pokphand-aligned broiler operations are scaling enzyme programs amid volatile soybean meal pricing from Argentine supply disruptions. The Department of Livestock Development enforces feed additive registration timelines that favor established strain libraries over novel candidates. Bangkok corridor feed mills represent Southeast Asia's most active retrofit zone for automated spray line infrastructure.
Denmark
Fermentation capacity clusters around Copenhagen and Kalundborg supply bulk neutral-protease volumes to European compound feed manufacturers. The European Food Safety Authority evaluates novel proteases under Regulation EC 1831/2003, creating 24-36 month approval timelines. Novonesis leverages microbial strain libraries and submerged bioreactor infrastructure to sustain cost advantages in commodity enzyme production.
China
State-owned enzyme producers in Shandong and Jiangsu provinces anchor regional supply of fermentation-sourced acid-proteases. The Ministry of Agriculture and Rural Affairs maintains import restrictions that complicate multi-territory product registration for foreign suppliers. Yangtze River Delta feed mills are consolidating procurement around domestic technical service providers to navigate positive list compliance.
Animal Feed Protease Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive returns across the animal feed protease sector. Integrated fermentation specialists with captive strain libraries dominate bulk neutral-protease economics, while formulation specialists command premiums through precision-delivery technologies. Three archetypes structure rivalry: microbial platform owners, encapsulation technology specialists, and global distribution integrators. Capacity expansion in Vietnamese and Brazilian dosing infrastructure and strategic partnerships for multi-enzyme bundling represent the dominant competitive moves reshaping supplier relationships.
Among microbial platform owners, Novonesis and DSM-Firmenich AG exemplify the fermentation-scale archetype, leveraging submerged bioreactor infrastructure to supply commodity volume. BASF SE occupies a position within the global distribution tier, extending technical service networks into aquaculture-intensive zones. Kemin Industries represents the precision-delivery specialist archetype, anchoring competitive position through thermal protection technologies that preserve enzyme activity during high-temperature pelleting.
| Leading Market Players |
|---|
| International Flavors & Fragrances |
| Kemin Industries |
| Novonesis |
| Cargill |
| Associated British Foods |
| BASF SE |
| Adisseo |
| Archer Daniels Midland |
| DSM-Firmenich AG |
| Others |
Supply Flow & Price Mechanics
Fermentation scale economies in Danish and Chinese bioreactor clusters compress unit production costs for bulk neutral-proteases while simultaneously anchoring price floors for acid-stable variants. This geographic concentration of submerged fermentation capacity creates asymmetric pricing power across protease classes.
Pricing Analysis
Technical service contracts and multi-enzyme bundling agreements drive lifetime value for formulation specialists. Three-tier pricing structure across premium, standard, and economy levels separates encapsulated acid-proteases with thermal protection from unprotected liquid alternatives and commodity powder formulations. Cost compression in unprotected liquid tiers is intensifying because Vietnamese and Thai buyers demonstrate high price elasticity. Independent aquaculture feed mills in the Mekong Delta exhibit the greatest price sensitivity, while Brazilian poultry integrators aligned with export certification requirements absorb premium encapsulation costs with minimal elasticity.
Supply Chain Analysis
Strait of Malacca transit routes and Copenhagen-Kalundborg logistics corridors concentrate bulk enzyme movements between Asian demand centers and European fermentation hubs. Manufacturing gravity centers on Denmark, China, and Brazil for fermentation-derived proteases, with formulation finishing distributed across Vietnam and Thailand for regional customization. Production rests on Bacillus subtilis and Aspergillus oryzae strain libraries, corn steep liquor fermentation media, and precision-delivery coating chemistries. Single-source vulnerability in Danish bulk neutral-protease supply creates exposure to energy price shocks. Distribution runs through technical service partnerships with integrated feed mills rather than commodity trading channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substitution threats from precision fermentation-derived amino acids and improved plant protein processing technologies compel incumbents to defend their value proposition through formulation innovation rather than commodity scale alone.
For Market Incumbents: Compound thermal protection capabilities with automated dosing system integration to lock in multi-enzyme technical service contracts at Thailand's Charoen Pokphand-aligned facilities. Expand backward integration into strain engineering to reduce dependency on external microbial platform licensing. Encapsulation technology specialists face margin compression from unprotected liquid alternatives; defend through EFSA equivalency investments that filter competitor access to European compound feed manufacturers. For New Entrants and Emerging Players: Lead with Vietnam's aquaculture segment where shrimp and pangasius producers remain undersupplied with fishmeal-optimized protease formulations. Target Ho Chi Minh City-based compounders seeking MAPA equivalency pathways for Mercosur export certification. White-space exists in automated liquid dosing infrastructure retrofit services for legacy powder-handling mills. Go-to-market through precision-delivery coating partnerships with established fermentation suppliers rather than greenfield strain development. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-delivery specialists with captive encapsulation IP over commodity fermentation operators facing yield plateau pressures. Long-term viability hinges on substrate-specific formulation capabilities as precision nutrition programs displace broad-spectrum enzymes. Acquisition targets should demonstrate strain libraries calibrated to regional protein meal compositions. Watch EFSA's evolving whole-genome sequencing requirements as the inflection indicator for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Expansion | Calibrated proteases for Vietnamese fishmeal and Brazilian soybean compositions capture precision nutrition premiums. |
| Encapsulation Technology Licensing | Lipid matrix and polymer shell IP protects acid-protease activity through pelleting temperatures above 90°C. |
| Multi-Enzyme Bundling Agreements | Integrated protease-carbohydrase-phytase packages displace standalone procurement at Brazil's southern feed corridor. |
| Automated Liquid Dosing Infrastructure | Spray line retrofits at Thailand's Bangkok corridor mills shift volume from powder toward stabilized aqueous formulations. |
| Regulatory Equivalency Certification | MAPA and EFSA alignment unlocks Mercosur trade flows and European compound feed manufacturer procurement. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation plant managers, feed mill procurement leads at integrated poultry operations, technical R&D directors at formulation specialists, and distribution channel partners across Southeast Asian aquaculture corridors. Secondary validation drew from EFSA additive approval databases, Chinese Ministry of Agriculture positive list filings, Brazilian MAPA equivalency registers, and customs trade flow records. Bottom-up volume modeling triangulated against top-down market sizing across producer capacity disclosures.
Across the analysis window, projections incorporate segmentation dimensions spanning protease class, livestock species application, formulation stability tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves tied to soybean meal price volatility and nitrogen emission compliance timelines. Forecast inputs include pelleting temperature protocol evolution at integrated mills and automation investment rates in Vietnamese and Brazilian dosing infrastructure.
The analysis sits within stated boundaries; outcomes outside sustained fermentation yield improvements or abrupt regulatory pathway tightening would require recalibration. Forecasts reflect documented assumptions regarding strain characterization cost trajectories and encapsulation technology diffusion rates. Practitioners should keep alternative scenarios live as EFSA whole-genome sequencing requirements and Chinese positive list modifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Hog Production and Pork Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Swine Feed Market
Livestock Management
North America Feed Binders Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Feed Management Software Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Roughage Feed Market
Livestock Management
Pig Feed Market
Livestock Management
Smart Feeding Systems Market
Livestock Management
North America Swine Feed Market
Livestock Management
Livestock Dewormers Market
Livestock Management
United States Swine Feed Market
Livestock Management
Wild Birds Products Market
Livestock Management
Poultry Health Market
Livestock Management
Poultry Concentrate Market