
 Layer Feed Market | 2026-2036
Layer Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Layer Feed Market Insights
Brazil is narrowing the cost gap with Asian suppliers through soybean-meal integration and automated milling investments. Cargill Inc. leverages its grain-trading infrastructure to anchor South American supply chains. Charoen Pokphand Foods PCL dominates Southeast Asian markets through captive breeding-to-feed operations. De Heus Animal Nutrition specializes in precision nutrition formulations for tropical climates.
Layer feed denotes nutritionally complete rations formulated to sustain egg production in laying hens, typically containing 16-18% crude protein, calcium at 3.5-4.5% for shell integrity, and amino acid profiles optimized for daily output. Pelleted feed commands premium positioning due to reduced waste and uniform intake among caged flocks. Protein meals, particularly soybean and insect-derived alternatives, represent the fastest-growing ingredient category as sustainability pressures mount. Direct sales channels capture margin pools through long-term contracts with integrated poultry farms, while retail distribution serves fragmented backyard farmer segments.
The EU Green Deal and REACH frameworks restrict antibiotic growth promoters and mandate feed carbon footprint disclosures, forcing reformulation investments. The FDA and USDA enforce Salmonella prevention standards that dictate prebiotic and acidifier inclusion rates in US-bound products. Stakeholders must monitor emerging mycotoxin regulations in major grain-producing jurisdictions and decide between regional formulation adaptation versus global standardization strategies.
Market Dynamics
The EU Green Deal's carbon footprint disclosure mandates are forcing feed manufacturers to restructure ingredient sourcing and reformulation strategies across multiple continents simultaneously.
Growth Catalysts
- Export-grade egg demand:Commercial producers in Brazil are expanding flock sizes to capture premium export markets, driving volume requirements for high-performance layer rations with optimized amino acid profiles.
- REACH framework restrictions:The phased elimination of antibiotic growth promoters across European member states is accelerating prebiotic and acidifier inclusion rates in commercial formulations.
- Integrated contract farming:India's shift from fragmented backyard systems to consolidated poultry operations creates sustained demand for nutritionally complete pelleted feed with standardized mineral content.
Market Restraints
- Soybean meal price volatility:Protein meal costs fluctuate with South American harvest cycles, compressing margin pools for formulators dependent on commodity soy derivatives.
- Mycotoxin regulatory fragmentation:Divergent maximum residue limits across Brazil, India, and EU jurisdictions force manufacturers to maintain multiple regional specification tiers.
- Insect protein scale limitations:Black soldier fly and mealworm meal production remains concentrated in pilot facilities, constraining supply for sustainability-driven reformulation targets.
Strategic Opportunities
- Southeast Asian captive breeding integration:Backward control over parent stock and hatchery operations enables feed-to-table margin capture in Thailand and Vietnam expansion zones.
- Precision nutrition software:Climate-specific formulation algorithms for tropical humidity conditions differentiate technical service offerings in equatorial production belts.
- Indian FSSAI feed safety certification:Mandatory quality standards for commercial layer operations create compliance-driven switching demand from unorganized feed sources.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in calcium-to-phosphorus ratio optimization for shell integrity remains concentrated among veteran nutritionists approaching retirement.
- Legacy mill retrofit costs:Automated pelleting and temperature-controlled conditioning systems require capital deployment that fragmented regional mills struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Layer Feed Market |
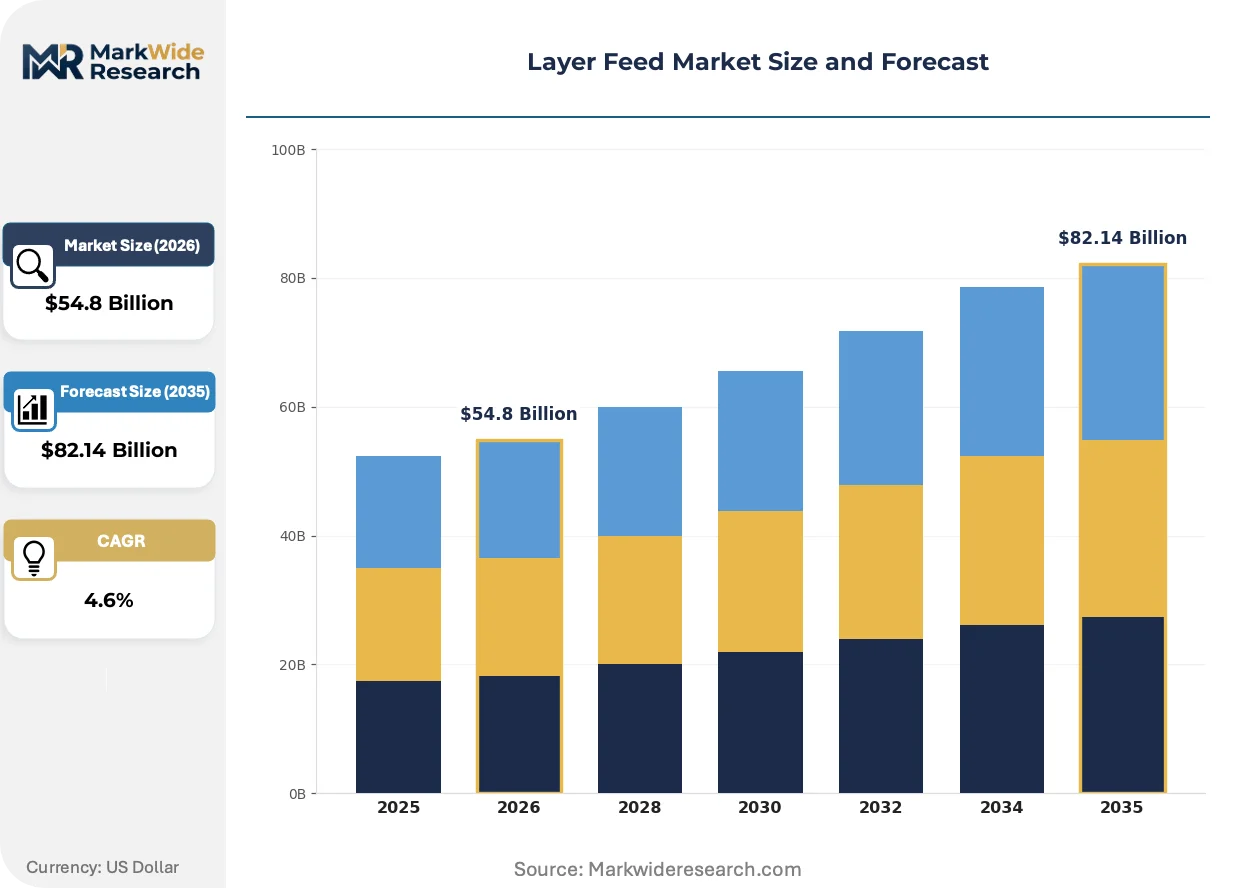
| Market Size in 2026 | $54.8 Billion |
| Market Size in 2035 | $82.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feed Type: Pelleted Feed, Mash Feed, Crumble Feed, Liquid Feed Ingredient Type: Cereal Grains, Protein Meals, Vitamins, Minerals Distribution Channel: Retail, Wholesale, Online, Direct Sales End User: Poultry Farms, Commercial Producers, Backyard Farmers, Agribusinesses |
| Companies Covered | Cargill Inc., Archer Daniels Midland Company, Charoen Pokphand Foods PCL, Nutreco N.V., Alltech Inc., Land O'Lakes Inc., New Hope Liuhe Co. Ltd, De Heus Animal Nutrition, ForFarmers N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Layer Feed Market Trends and Innovations
Formulation science is converging with digital agriculture platforms, enabling real-time diet adjustments based on flock performance data and environmental conditions.
Enzyme-supplemented feed technology is hybridizing conventional corn-soy matrices with non-starch polysaccharide degraders to improve metabolizable energy extraction. Large-scale integrated operations in Brazil and India are adopting these formulations at accelerating rates to reduce feed conversion ratios. This enzymatic approach is hybridizing traditional cost structures by enabling cheaper alternative grains to substitute premium corn without performance penalties.
The EU Green Deal's carbon footprint disclosure requirements now mandate lifecycle assessment documentation for imported feed ingredients. Manufacturers must trace soy provenance to deforestation-free certified origins or face exclusion from European supply chains. Layer feed destined for Netherlands and Germany retail channels carries the strictest verification burdens, pushing suppliers toward blockchain-enabled chain-of-custody systems.
Direct contracting between feed mills and integrated poultry farms is displacing traditional distributor networks in India's rapidly consolidating market. Volume commitments spanning 12-24 month horizons lock in supply security for expanding operations while stripping margin from agricultural input retailers. This channel compression is most visible in Andhra Pradesh and Tamil Nadu, where contract farming clusters now source 60% of compound feed through mill-direct procurement desks.
Layer Feed Market Segmentation
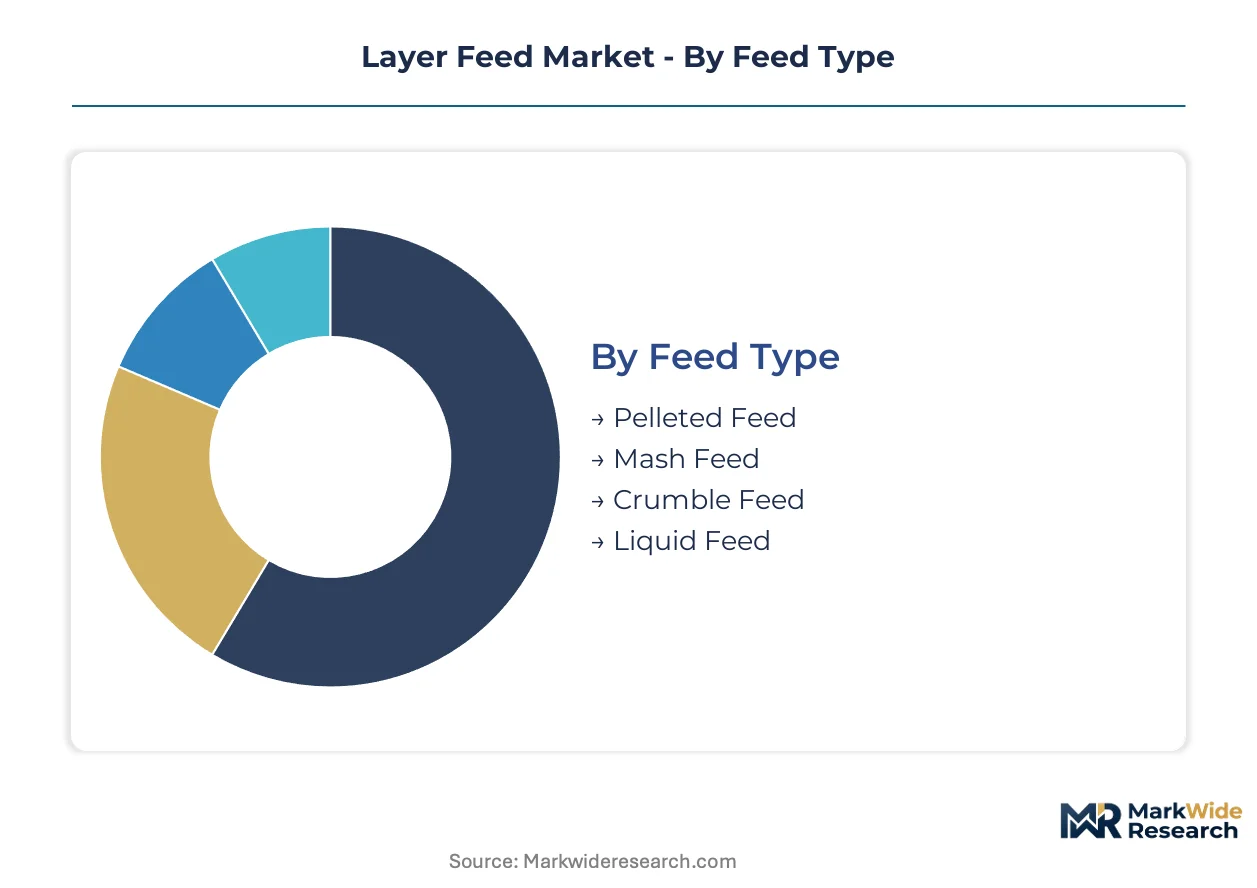
Layer feed segmentation reflects divergent production scales, from automated caged operations demanding uniform intake to backyard systems prioritizing cost minimization. Feed form, ingredient sourcing, and channel configuration each carry distinct margin implications and technical service requirements across the value chain.
Feed Type:
Form selection tracks directly against housing infrastructure sophistication and waste tolerance thresholds.
- Pelleted Feed:Compressed cylindrical rations with 3-5mm diameter specifications reduce dust generation and enable precise automated dispensing in high-density cage systems. Demand concentrates in Brazil's expanding commercial export-oriented operations, where feed conversion ratio optimization justifies 15-20% price premiums over mash alternatives.
- Mash Feed:Ground meal formulations with particle size distributions below 2mm serve lower-investment operations with manual or semi-automated distribution systems. Backyard farmer clusters in India's Bihar and Uttar Pradesh states rely on mash for its lower capital barrier, though ingredient separation during transport elevates nutritional variability risks.
- Crumble Feed:Intermediate texture produced by partial pelleting followed by breaking attracts transitional operations upgrading from mash without full automation investment.
- Liquid Feed:Suspension-based delivery systems incorporating molasses or fermentation byproducts address specific humidity-stressed tropical environments where dry feed palatability degrades.
The dominant share belongs to Pelleted Feed, while Crumble Feed is closing the gap fastest.
Ingredient Type:
Raw material composition determines formulation cost volatility and regulatory compliance burden across import-dependent supply chains.
- Cereal Grains:Corn and wheat provide metabolizable energy foundations at 2800-3200 kcal/kg, with sorghum and millet substituting in drought-affected harvest cycles. Brazilian integrators leverage captive soybean-meal crushing to anchor protein-carbohydrate cost structures against Asian import competition.
- Protein Meals:Soybean meal at 44-48% crude protein content dominates amino acid provision, though insect-derived alternatives from black soldier fly larvae are gaining formulation share in EU-bound products facing deforestation certification requirements.
- Vitamins:Fat-soluble A, D, E, K and water-soluble B-complex premixes prevent deficiency disorders in high-output genetic lines pushing 330+ eggs annually per hen.
- Minerals:Calcium sources including limestone and oyster shell maintain 3.5-4.5% dietary levels critical for shell integrity in extended production cycles.
Cereal Grains command volume leadership, though Protein Meals carry the steepest price volatility exposure.
Distribution Channel:
Channel selection separates consolidated procurement desks from fragmented retail-dependent sourcing patterns.
- Direct Sales:Mill-to-farm contracting with 12-24 month volume commitments strips distributor margins while securing supply certainty for expanding integrated operations. Andhra Pradesh and Tamil Nadu contract farming clusters now source 60% of compound feed through this channel.
- Wholesale:Aggregator networks serving mid-scale independent farms with 5,000-50,000 bird capacities combine logistical efficiency with credit extension capabilities.
- Retail:Agricultural input shops with 50kg bag breakdown serve fragmented backyard segments requiring flexible purchase timing.
- Online:Digital platforms with technical consultation overlays penetrate remote geographies lacking physical distribution density.
Direct Sales expansion is displacing Wholesale intermediation fastest in consolidating production belts.
End User:
Customer scale determines formulation precision requirements and technical service intensity.
- Commercial Producers:Operations exceeding 100,000 birds demand phase-feeding programs with weekly nutrient density adjustments matched to production curves. Brazil's export-grade egg specialists drive premium ration adoption with amino acid profiles optimized for shell color uniformity.
- Poultry Farms:Mid-scale enterprises with 10,000-100,000 birds balance cost control with performance consistency, often relying on feed company technical representatives for flock management guidance.
- Agribusinesses:Diversified agricultural conglomerates with captive feed milling capacity source premixes and concentrates rather than complete feeds.
- Backyard Farmers:Subsistence and semi-commercial operations below 1,000 birds prioritize lowest-cost mash options with minimal supplementation.
Commercial Producers dominate value capture, though Poultry Farms represent the deepest volume pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean-meal crushing capacity concentrates in Brazil and Argentina, anchoring South American supply chains against Asian import competition. Feed manufacturers in these markets leverage captive grain-trading infrastructure to compress protein meal costs. Regional regulatory divergence on mycotoxin limits and carbon disclosure mandates fragments formulation standards across export destinations.
Brazil
Export-grade egg demand from European and Middle Eastern buyers drives flock expansion in São Paulo and Minas Gerais states. ANVISA enforces Salmonella prevention standards that dictate prebiotic inclusion rates in commercial formulations. Integrated operations in the Center-West region deploy automated pelleting systems to optimize feed conversion ratios for premium shell color uniformity.
India
Contract farming clusters in Andhra Pradesh and Tamil Nadu replace fragmented backyard systems with consolidated procurement desks. FSSAI mandates feed safety certification for commercial layer operations, forcing unorganized feed sources out of formal supply chains. Telangana's integrated poultry corridors source compound feed through 12-24 month mill-direct volume commitments.
United States
Large-scale cage-free transition programs in Iowa and Ohio reshape nutrient density requirements for extended production cycles. FDA and USDA jointly enforce Salmonella prevention standards that elevate acidifier and prebiotic formulation rates. California's Proposition 12 compliance costs push commercial producers toward precision nutrition software for phase-feeding optimization.
Germany
Retail channel sustainability requirements in Bavaria and North Rhine-Westphalia drive deforestation-free soy certification adoption. EU Green Deal carbon footprint disclosure mandates force lifecycle assessment documentation for all imported feed ingredients. Dutch-German border region mills invest in blockchain-enabled chain-of-custody systems to verify soy provenance for supermarket supply chains.
China
Integrated breeding-to-feed operations in Shandong and Henan provinces displace independent formulators through captive crushing capacity. NMPA and SAMR coordinate feed safety standards that restrict antibiotic growth promoter residues in export-oriented production. Yangtze River Delta commercial farms adopt enzyme-supplemented formulations to substitute alternative grains for premium corn without performance penalties.
Layer Feed Market Competitive Landscape
Grain-trading conglomerates and captive breeding specialists split the market into distinct capability tiers. Consolidation pressures concentrate margin capture among integrated players with upstream oilseed crushing and downstream distribution control. Three archetypes dominate: multinational agribusinesses with commodity-trading infrastructure, regional specialists in tropical precision nutrition, and integrated poultry operators with captive feed milling. Competitive moves center on backward integration into parent stock breeding and automated mill retrofit programs.
Among grain-trading conglomerates, Cargill Inc. and Archer Daniels Midland Company anchor North and South American supply chains through captive infrastructure. Charoen Pokphand Foods PCL represents the integrated poultry operator archetype, with breeding-to-feed control spanning Southeast Asian expansion zones. De Heus Animal Nutrition occupies a specialist position in tropical climate formulation, serving equatorial production belts with humidity-optimized ration design.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland Company |
| Charoen Pokphand Foods PCL |
| Nutreco N.V. |
| Alltech Inc. |
| Land O'Lakes Inc. |
| New Hope Liuhe Co. Ltd |
| De Heus Animal Nutrition |
| ForFarmers N.V. |
| Others |
Pricing and Supply Chain Analysis
Soybean meal price volatility determines both the spread between premium and economy feed tiers and the geographic configuration of crushing capacity investments. Brazilian integrators leverage captive soybean processing to compress protein costs, while import-dependent Asian formulators absorb margin compression from South American harvest cycles.
Pricing Analysis
EU Green Deal carbon disclosure mandates dictate the pricing tier structure across export-bound formulations. Three-tier pricing separates deforestation-certified premium rations from standard commercial grades and unverified economy alternatives. Certification premiums for blockchain-traced soy origins widen spreads as Dutch and German retail channels enforce strictest verification. Price differentiation hinges on carbon footprint documentation and amino acid density optimization. Cost compression in economy tiers intensifies as Indian contract farming clusters consolidate procurement volumes.
Supply Chain Analysis
Upstream feedstock sourcing centers on Brazil, Argentina, and the United States for soybean meal crushing capacity. Corn and wheat supplies draw from North American and Black Sea harvest regions, with sorghum substituting during drought cycles. Single-source vulnerability concentrates in South American protein meal exports subject to El Niño disruption. Distribution runs through mill-direct contracting channels displacing traditional agricultural input retailers in consolidating production belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around carbon disclosure and feed safety certification creates formidable switching costs for established supply relationships. Network effects in technical service and formulation expertise compound defensive advantages for incumbent players.
For Market Incumbents: Insulate margin pools through backward integration into parent stock breeding and automated pelleting capacity in São Paulo and Minas Gerais expansion corridors. Capture stranded volume from unorganized feed sources as FSSAI certification mandates consolidate India's formal supply chains. Prioritize blockchain-enabled chain-of-custody investments to defend European retail channel positioning against deforestation-free compliance requirements. For New Entrants and Emerging Players: Mid-scale poultry farms in Vietnam and Thailand transitioning from mash to crumble formulations represent the most penetrable entry point for humidity-optimized precision nutrition services. Telangana's integrated poultry corridors offer white-space for enzyme-supplemented formulation specialists lacking legacy mill infrastructure. Lead with climate-specific technical consultation to differentiate against commodity feed distributors. For Investors and Strategic Acquirers: EU Green Deal implementation milestones reshape the acquisition landscape toward deforestation-certified supply chain assets and carbon accounting capabilities. Long-term viability favors integrated players with captive crushing and breeding-to-feed control spanning tropical expansion zones. Target acquisition archetypes include regional formulators with FSSAI certification and established contract farming relationships. Monitor black soldier fly protein scale-up milestones as inflection indicators for insect-derived alternative feed viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Parent Stock Breeding | Captures margin pools from genetic lines through slaughter in Southeast Asian expansion corridors. |
| Automated Pelleting Capacity Expansion | Reduces feed conversion ratios for Brazilian export-grade egg operations targeting European retail channels. |
| Blockchain Chain-of-Custody Implementation | Verifies deforestation-free soy provenance for EU Green Deal compliance in Dutch-German border mills. |
| Enzyme-Supplemented Formulation Launch | Enables alternative grain substitution without performance penalties in Yangtze River Delta commercial farms. |
| FSSAI Certification Investment | Forces compliance-driven switching from unorganized feed sources in Andhra Pradesh contract farming clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with layer farm operations managers, feed mill procurement directors, poultry nutritionists, and agricultural input distributors. Secondary validation drew from ANVISA regulatory filings, FSSAI certification databases, EU Green Deal implementation directives, customs trade data for soybean meal flows, and SEC disclosures from grain-trading conglomerates. Bottom-up volume estimates from regional production clusters were triangulated against top-down value projections from compound feed manufacturing capacity.
Calibration against historical feed conversion ratio improvements and amino acid price elasticity informed the analytical framework across the projection horizon. Segmentation dimensions modeled include feed form type, ingredient sourcing category, distribution channel configuration, and end-user scale tier. CAGRs were derived from trend extrapolation of flock expansion rates and regulatory compliance cost trajectories. Industry-specific inputs incorporated phase-feeding program adoption curves and deforestation certification penetration assumptions.
Practitioners should monitor South American harvest yield revisions and mycotoxin regulatory harmonization efforts for early signals of forecast deviation. Cross-checking against USDA grain production estimates and Brazilian agricultural ministry flock inventory reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
China Swine Feed Market
Livestock Management
North America Ruminant Feed Premix Market
Livestock Management
Pig Feed Market
Livestock Management
Wagyu Beef Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
Poultry Health Market
Livestock Management
Feed Management Software Market
Livestock Management
Hog Production and Pork Market
Livestock Management
Poultry Concentrate Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Layer Breeding System Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Cattle Feeder Market
Livestock Management
Animal Identification Market