
 Europe Ruminant Feed Premix Market | 2026-2036
Europe Ruminant Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ruminant Feed Premix Market Foresight
Poland is rewriting ruminant feed premix capacity dynamics as domestic compound feed production scales to serve Central European dairy expansion. Cargill Inc. leverages its Poznań milling complex to anchor regional mineral premix supply for Polish and Baltic cooperatives. Nutreco N.V. competes through its Selko feed additive division, specializing in precision-delivery vitamin matrices for high-yielding Holstein herds. Koninklijke DSM N.V. differentiates via its enzyme-modified nutrient platforms that sustain rumen bypass efficiency under EFSA-reviewed health claims.
Europe ruminant feed premix denotes a homogenized blend of vitamins, minerals, amino acids, and functional additives dosed at 0.5-3% of total ration mass, manufactured through multi-stage micro-pulverization and thermal-stabilized coating to preserve bioavailability through pelleting and storage. Its commercial purpose centers on closing nutritional gaps in base forages and grains to optimize rumen fermentation, reproductive performance, and meat or milk output per animal unit. Minerals occupy the largest value pool across product types due to baseline inclusion rates in every complete and supplementary formulation, while probiotics represent the fastest-ascending segment as dairy operators substitute antibiotic growth promoters with EFSA-registered live cultures. Medicated feed formulations face structural contraction under EU Veterinary Medicines Regulation restrictions on prophylactic antibiotic use, compressing margin pools toward non-medicated concentrates and complete feeds with enhanced amino acid density.
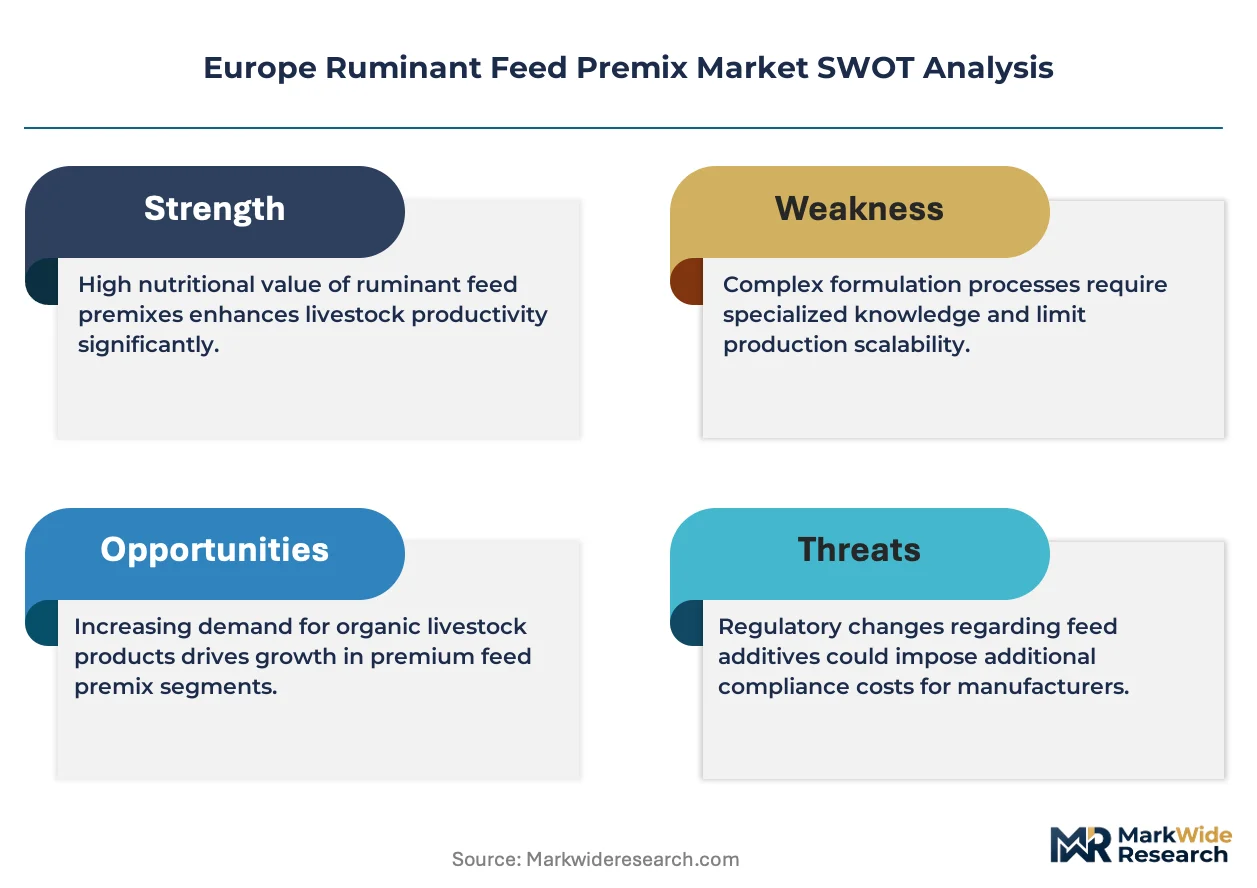
EFSA evaluates all novel feed additives through centralized scientific opinions that determine market authorization across member states, while the EU Green Deal's Farm to Fork strategy mandates 50% reduction in antimicrobial sales for food-producing animals, directly reshaping premix formulation portfolios toward non-medicated alternatives. REACH and F-Gas Regulation compliance adds material cost layers to vitamin synthesis and preservative chemistries, filtering smaller blenders from premium contract supply chains. Stakeholders must monitor EMA and EFSA parallel review timelines for next-generation rumen modifiers, as regulatory lag between scientific opinion and commercial approval creates first-mover windows for premix innovators with dossier-ready microbial strains.
Market Dynamics
EU Green Deal mandates are compressing antibiotic-dependent premix portfolios while accelerating probiotic formulation development across Dutch and German dairy supply chains.
Growth Catalysts
- EFSA-registered live cultures:Dairy cooperatives in the Netherlands substitute antibiotic growth promoters with validated probiotic strains, creating pull for precision-delivery premix matrices.
- Farm to Fork antimicrobial reduction targets:The EU mandate for halving antimicrobial sales in food-producing animals forces reformulation toward mineral-dense and enzyme-modified alternatives.
- Polish compound feed scaling:Central European dairy expansion drives regional premix capacity buildup to serve cross-border Baltic cooperatives.
Market Restraints
- Vitamin synthesis cost layers:REACH and F-Gas Regulation compliance adds material expense to preservative chemistries and thermal-stabilized coating processes.
- Regulatory lag windows:EMA and EFSA parallel review timelines for novel rumen modifiers create uncertainty between scientific opinion and commercial authorization.
- Prophylactic antibiotic compression:EU Veterinary Medicines Regulation restrictions contract medicated feed margin pools toward non-medicated concentrate alternatives.
Strategic Opportunities
- Rumen bypass efficiency platforms:Enzyme-modified nutrient technologies that sustain bioavailability under EFSA-reviewed health claims capture premium positioning in high-yielding Holstein operations.
- Integrated feed supply chain penetration:Intensive dairy clusters in the Netherlands create concentrated demand for homogenized vitamin-mineral blends dosed through automated feeding systems.
- Precision-delivery vitamin matrices:Micro-pulverization and thermal-stabilized coating innovations enable differentiation in pelleting and storage performance for compound feed manufacturers.
Industry Challenges
- Dossier-ready microbial strain development:Premix innovators face extended R&D cycles to generate EFSA-compliant safety and efficacy data for novel probiotic candidates.
- Multi-stage manufacturing capex:Micro-pulverization equipment and thermal coating infrastructure demands capital commitment that filters smaller blenders from premium contract tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ruminant Feed Premix Market |
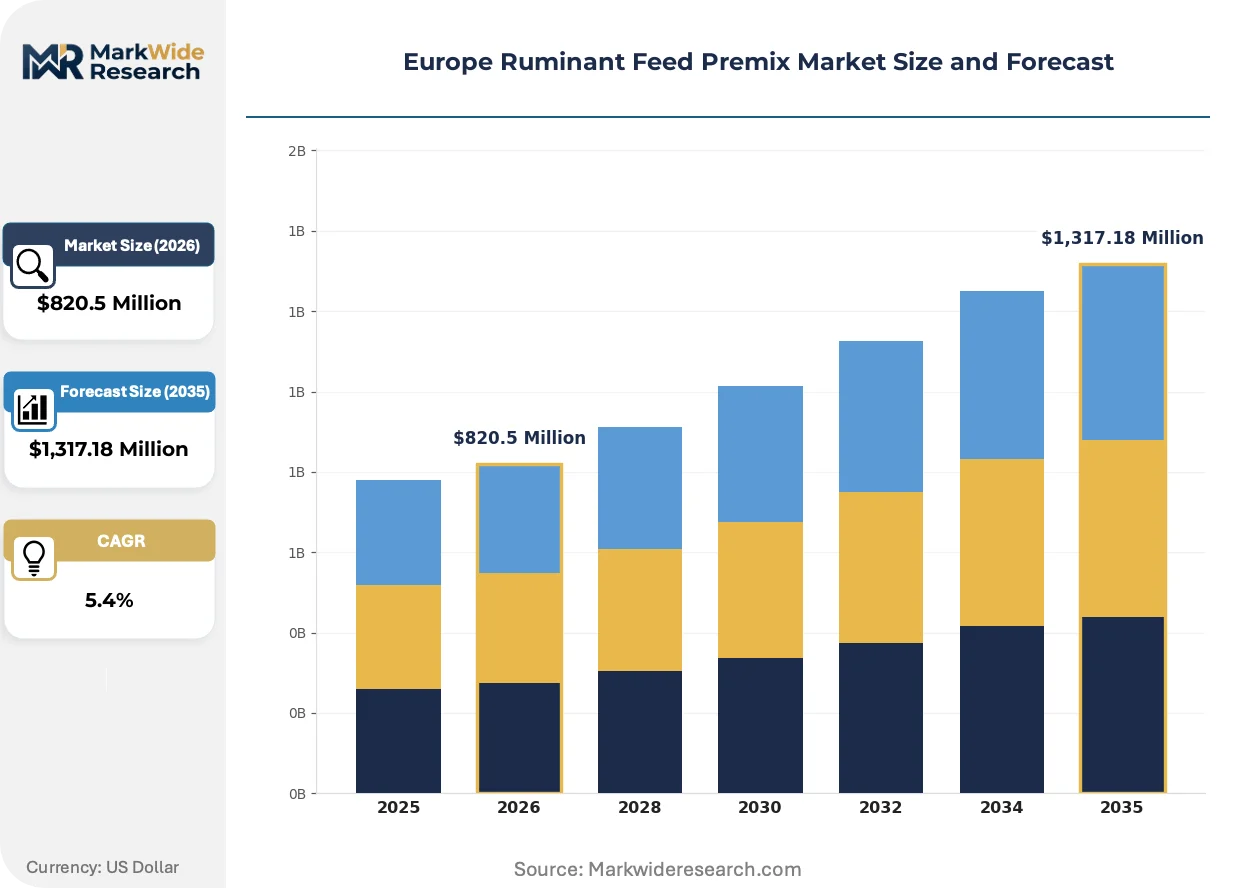
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,317.18 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minerals, Vitamins, Amino Acids, Probiotics Formulation Type: Complete Feed, Supplementary Feed, Concentrates, Medicated Feed End User: Dairy Farms, Beef Cattle Operations, Goat Farms, Research Institutions Packaging Type: Bags, Bulk, Pallets, Drums |
| Companies Covered | Cargill Inc., Nutreco N.V., Koninklijke DSM N.V., Archer-Daniels-Midland Company, Kemin Industries Inc., BASF SE, Alltech Inc., Novus International, Adisseo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ruminant Feed Premix Market Shifts & Advancements
Formulation science and regulatory compliance are converging to reshape premix development priorities, with bioavailability preservation and live culture validation dominating R&D resource allocation.
Near-infrared spectroscopy coupled with automated batching systems is digitizing quality control across premix manufacturing. Large dairy cooperatives in Germany deploy real-time nutrient verification to reduce formulation variance. This precision infrastructure is digitizing compliance documentation for EFSA traceability requirements while compressing manual assay labor.
REACH authorization timelines for novel preservative chemistries are extending vitamin synthesis project horizons. Manufacturers reformulate antioxidant systems to maintain shelf stability under tightened substance restrictions. French and Dutch premix blenders accelerate alternative stabilizer testing to preempt supply discontinuities.
Cooperative procurement consolidation is compressing supplier negotiation cycles across North European dairy operations. Buyers bundle mineral and vitamin premix contracts with compound feed supply agreements, displacing spot-market purchasing. This concentration is most visible in the Netherlands, where integrated feed supply chains absorb smaller independent blenders into captive sourcing arrangements.
Europe Ruminant Feed Premix Market Segmentation

Premix segmentation in Europe reflects divergent maturity trajectories across nutritional technologies and regulatory compliance tiers. Dairy operators select formulations based on herd productivity targets, EFSA authorization status, and integration with automated feeding infrastructure.
Product Type:
Mature mineral and vitamin categories dominate current formulation volumes, while emerging live culture segments capture reformulation investment under antimicrobial reduction mandates.
- Minerals:Baseline inclusions of calcium, phosphorus, and trace elements constitute the foundational premix layer dosed across every complete and supplementary ration. German and Dutch dairy cooperatives specify chelated mineral forms to optimize bioavailability in high-yielding Holstein herds facing metabolic stress. Minerals handle the majority of throughput; probiotics are climbing the fastest on share.
- Vitamins:Fat-soluble and water-soluble vitamin matrices require thermal-stabilized coating to preserve activity through pelleting and extended storage. French premix blenders emphasize vitamin E and selenium synergies for reproductive performance in expanding dairy operations.
- Amino Acids:Rumen-protected lysine and methionine formulations close protein gaps in cereal-based rations across Polish and Baltic compound feed production.
- Probiotics:EFSA-registered live cultures including Saccharomyces cerevisiae and Lactobacillus strains substitute for antibiotic growth promoters under Farm to Fork targets.
Mineral and vitamin platforms anchor current revenue; probiotic formulations are expanding most quickly as regulatory pressure accelerates microbiome-based solutions.
Formulation Type:
Cost tier differentiation separates commodity-complete feeds from precision concentrates and regulated medicated categories facing margin compression.
- Complete Feed:Fully formulated rations incorporating premix at 0.5-3% inclusion serve intensive Dutch dairy operations with automated feeding systems. These integrated supply chains demand homogenized mineral-vitamin blends with batch-to-batch consistency verified through near-infrared spectroscopy.
- Supplementary Feed:Partial formulations allow Polish and Baltic cooperatives to customize base forage rations with targeted nutrient additions. Regional compound feed scaling drives supplementary premix demand as domestic milling capacity expands to serve Central European dairy growth.
- Concentrates:High-density nutrient packages enable precision supplementation for high-yielding herds in Germany and France.
- Medicated Feed:Prophylactic antibiotic formulations face structural contraction under EU Veterinary Medicines Regulation restrictions.
Complete feeds absorb the largest formulation volumes; concentrates are gaining share fastest as precision nutrition intensifies.
End User:
Customer type concentration centers on scaled dairy operations with procurement leverage, while specialized goat and research segments occupy niche positioning.
- Dairy Farms:Intensive operations across the Netherlands, Germany, and Denmark drive premium premix demand for Holstein herds exceeding 10,000 liters annual milk yield. Automated feeding systems require homogenized vitamin-mineral matrices with flowability characteristics compatible with pneumatic delivery.
- Beef Cattle Operations:Polish and Irish finishing systems utilize amino acid-dense concentrates to optimize feed conversion in cereal-based rations.
- Goat Farms:Specialized Mediterranean and Alpine operations specify selenium and vitamin E formulations for reproductive performance in dairy goat herds.
- Research Institutions:Wageningen University and INRAE facilities validate novel rumen modifier efficacy under EFSA pre-authorization protocols.
Dairy farms command the dominant procurement volumes; beef cattle operations are expanding fastest as Polish finishing capacity scales.
Packaging Type:
Supply chain configuration separates bulk delivery for integrated mill operations from bagged formats serving decentralized farm storage.
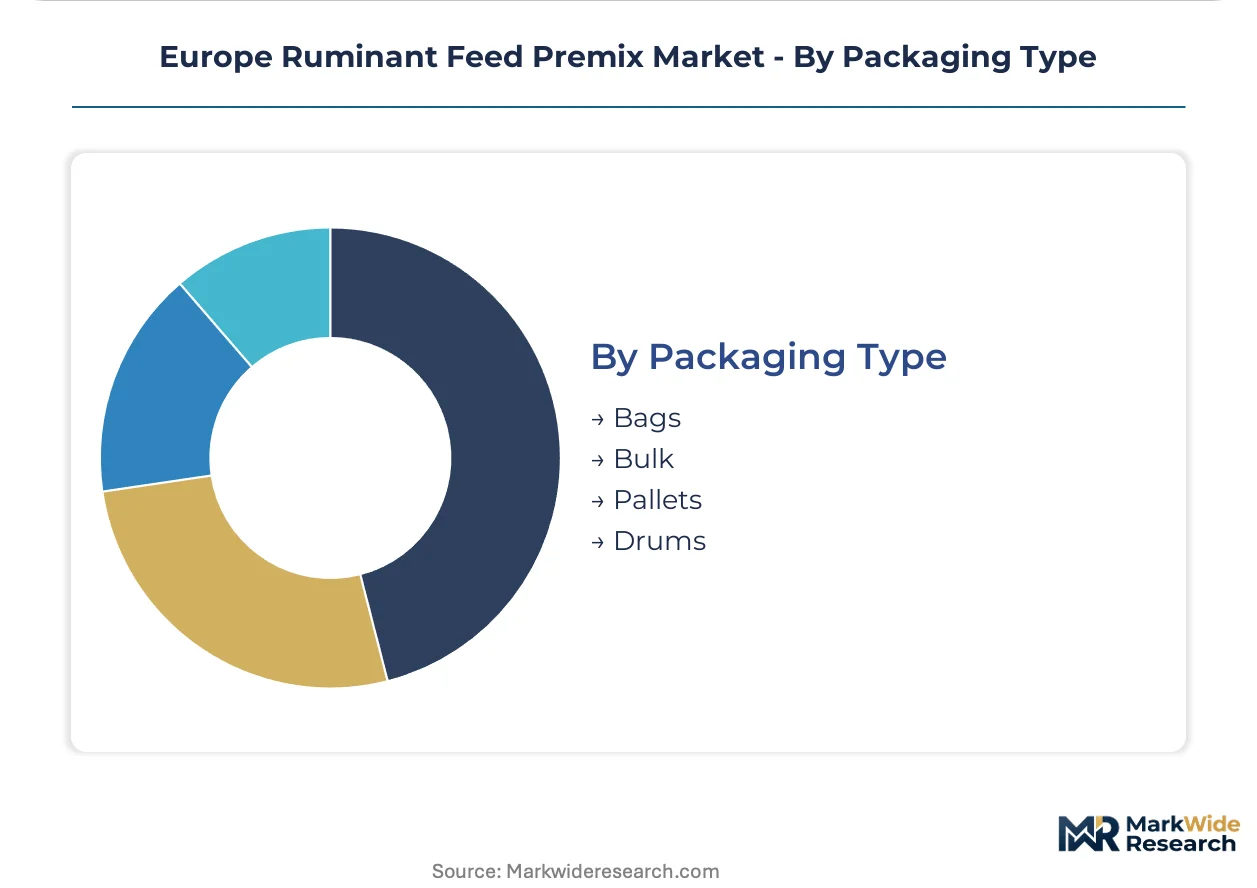
- Bulk:Unpackaged premix delivered by pneumatic tanker serves Dutch and German compound feed manufacturers with continuous production schedules. These integrated supply chains eliminate packaging material costs while requiring dedicated silo infrastructure and moisture-controlled storage.
- Bags:25kg multi-layer paper-plastic laminates protect vitamin activity through Polish and Baltic farm storage conditions with variable humidity control.
- Pallets:Unitized bag configurations streamline logistics for mid-scale French dairy cooperatives with centralized procurement.
- Drums:Sealed metal containers preserve probiotic viability for specialized live culture formulations requiring oxygen barrier protection.
Bulk delivery handles the largest throughput; bagged formats are expanding fastest as Baltic farm-level premix adoption deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA authorization protocols anchor premix demand across Dutch and German dairy supply chains. The EU Green Deal's Farm to Fork strategy tightens antimicrobial restrictions while accelerating probiotic adoption. National implementation timelines vary across member states.
Netherlands
Intensive dairy operations in Gelderland and Friesland drive premium premix demand for high-yielding Holstein herds exceeding 10,000 liters annual milk yield. The EU Green Deal mandates 50% antimicrobial reduction by 2030, forcing rapid reformulation toward EFSA-registered live cultures. Wageningen University clusters validate novel rumen modifiers under pre-authorization protocols.
Germany
Cooperative procurement consolidation across Bavaria and Lower Saxony compresses supplier negotiation cycles for mineral-vitamin matrices. REACH compliance adds material cost layers to thermal-stabilized coating processes. The Rhine-Ruhr industrial corridor hosts multi-stage micro-pulverization facilities serving cross-border dairy operations.
France
Expanding dairy farms in Brittany and Normandy specify chelated mineral forms to optimize bioavailability under metabolic stress. EMA and EFSA parallel review timelines create regulatory lag windows for novel feed additives. INRAE research facilities in Paris-Saclay anchor pre-commercial validation protocols.
Poland
Central European dairy expansion drives regional premix capacity buildup to serve Baltic cooperatives. Domestic compound feed production scales rapidly under EU structural fund support. The Poznań milling complex anchors mineral premix supply for Polish and cross-border operations.
Denmark
Automated feeding systems in Jutland require homogenized vitamin-mineral blends with flowability characteristics compatible with pneumatic delivery. F-Gas Regulation compliance filters smaller blenders from premium contract tiers. Copenhagen-based feed technology clusters digitize batch-to-batch consistency verification.
Europe Ruminant Feed Premix Market Competitive Landscape
Vertically integrated multinationals and specialized additive specialists split the market between scale-driven commodity supply and precision-differentiated formulations. The vendor base concentrates around four to six dominant players with EFSA dossier capabilities and multi-stage manufacturing infrastructure. Two strategic archetypes predominate: integrated agribusiness conglomerates with captive feed supply chains, and focused biotechnology specialists with enzyme-modified nutrient platforms. Competitive moves center on capacity expansion in Central European dairy corridors and strategic partnerships for probiotic strain commercialization.
Within the integrated agribusiness tier, Cargill Inc. and Archer-Daniels-Midland Company represent scale-driven supply chain anchors with compound feed manufacturing footprints. Nutreco N.V. exemplifies the precision-specialist archetype through feed additive divisions targeting high-yielding herd segments. Koninklijke DSM N.V. occupies a position bridging both categories with enzyme-modified nutrient technologies. These three entities collectively illustrate the competitive tension between volume throughput and formulation differentiation that defines European premix supply.
| Leading Market Players |
|---|
| Cargill Inc. |
| Nutreco N.V. |
| Koninklijke DSM N.V. |
| Archer-Daniels-Midland Company |
| Kemin Industries Inc. |
| BASF SE |
| Alltech Inc. |
| Novus International |
| Adisseo |
| Others |
Supply & Pricing Matrix
REACH authorization timelines for novel preservative chemistries compress margin buffers across vitamin synthesis operations while simultaneously filtering smaller blenders from premium contract tiers. This regulatory chokepoint widens price spreads between EFSA-dossier-ready multinationals and regional compounders, concentrating procurement leverage among Dutch and German dairy cooperatives with volume-scale negotiation power.
Pricing Analysis
Price spreads between Netherlands and Polish procurement markets reflect divergent automation infrastructure and batch consistency requirements. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-registered live culture formulations from commodity mineral-vitamin matrices and uncoated generic blends. Pricing pressure stems from F-Gas Regulation compliance costs in thermal-stabilized coating processes. Polish and Baltic cooperatives exhibit highest price sensitivity due to scaling compound feed operations with thinner margin profiles.
Supply Chain Analysis
Contract manufacturing concentrates among Cargill's Poznań milling complex, Nutreco's Selko blending facilities, and Koninklijke DSM's enzyme modification platforms. Raw material sourcing draws from Chinese vitamin precursor production, Brazilian trace mineral extraction, and domestic European probiotic strain cultivation. Single-source vulnerability in vitamin E and selenium concentrates threatens formulation continuity. Distribution runs through integrated compound feed manufacturers in the Netherlands and Germany, with spot-market bagged sales serving Polish farm-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA dossier capabilities and multi-stage micro-pulverization infrastructure represent scarce assets that concentrate competitive advantage among four to six dominant players. Premix innovators without thermal coating capacity or validated probiotic strains face structural exclusion from premium dairy supply chains.
For Market Incumbents: Insulate margin pools by accelerating backward integration into probiotic strain development and expanding Poznań-region capacity to capture Baltic cooperative consolidation. Defensive positioning requires pre-emptive REACH authorization for next-generation preservative chemistries before regulatory lag windows close to competitors. For New Entrants and Emerging Players: Build out precision-delivery vitamin matrix capabilities targeting mid-scale French dairy cooperatives underserved by automated feeding infrastructure. White-space opportunity concentrates in goat farm selenium formulations and research institution pre-authorization validation services. Go-to-market traction hinges on partnering with Polish compound feed scalers seeking cross-border mineral premix supply. For Investors and Strategic Acquirers: The EU Green Deal's Farm to Fork antimicrobial reduction targets reshape the acquisition landscape toward enzyme-modified nutrient platforms and EFSA-registered live culture pipelines. Long-term viability favors targets with dossier-ready microbial strains and existing thermal-stabilized coating infrastructure. Watch EMA-EFSA parallel review timeline compression as inflection signal for first-mover premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Dossier Investment | Validates novel probiotic strains under Farm to Fork antimicrobial reduction mandates. |
| Central European Capacity Expansion | Captures Polish and Baltic dairy cooperative procurement consolidation. |
| Enzyme-Modified Nutrient Platform Development | Sustains rumen bypass efficiency claims under EFSA-reviewed health protocols. |
| Integrated Feed Supply Chain Partnership | Locks in Dutch automated feeding system operators through captive sourcing. |
| Alternative Preservative Chemistry Reformulation | Preempts REACH discontinuity risks in vitamin synthesis operations. |
Research Methodology
Initial hypotheses were tested against primary input from premix manufacturing plant managers, dairy cooperative procurement leads, compound feed technical directors, and EFSA regulatory affairs specialists and refined through secondary validation. Sources included EFSA scientific opinion databases, EU Green Deal implementation tracking, customs trade flows for vitamin precursors, and SEC filings of listed agribusiness conglomerates. Bottom-up volume triangulation across formulation types reconciled with top-down value estimates from industry association data.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions spanning product type, formulation category, end-user scale tier, and regional regulatory cluster. CAGRs derived from fitted growth curves calibrated to historical premix adoption patterns and antimicrobial reduction policy implementation trajectories. Forecast inputs incorporated dairy herd productivity targets and automated feeding infrastructure penetration rates.
Stress conditions across REACH authorization delays, probiotic strain validation failures, and Baltic cooperative procurement consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of EMA-EFSA parallel review timelines and Polish compound feed production capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Cattle Head Catch Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Bird Feeder Market
Livestock Management
Poultry Health Market
Livestock Management
Wagyu Beef Market
Livestock Management
South America Ruminant Feed Market
Livestock Management
Cattle Management Software Market
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
North America Swine Feed Market
Livestock Management
North America Ruminant Feed Premix Market
Livestock Management
Europe Swine Feed Market
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
China Swine Feed Market
Livestock Management
Animal Feed Protease Market