
 Herd Management Software Market | 2026-2036
Herd Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Herd Management Software Market Insights
A capital-intensity divergence between hardware-integrated incumbents and lean software-only entrants is unwinding traditional competitive boundaries in livestock technology. GEA Group Aktiengesellschaft leverages its milking equipment installed base to bundle subscription-based analytics, while Nedap N.V. anchors its position through proprietary sensor hardware that locks in recurring software revenue. Afimilk Ltd. differentiates by specializing in parlor-integrated milk meters that feed real-time data into breeding and health algorithms.
Herd management software denotes digital platforms that aggregate biometric, reproductive, nutritional, and environmental data from individual animals or groups to optimize livestock productivity and welfare decisions. These systems typically process inputs from RFID ear tags, pedometers, rumination monitors, and milk composition sensors, translating raw signals into actionable alerts for estrus detection, mastitis early warning, and feed ration adjustment. Cloud-based solutions now lead deployment preferences among mid-scale operators seeking lower upfront infrastructure costs, while data analytics features command the fastest growth trajectory as artificial intelligence models improve predictive accuracy for disease onset and reproductive timing. On-premise solutions retain durable share among privacy-sensitive agricultural cooperatives managing multi-farm data estates under strict member control protocols.
USDA's Animal Disease Traceability rules and the FDA's Veterinary Feed Directive collectively mandate granular record-keeping that software platforms increasingly automate, while EU Green Deal livestock emissions reporting requirements through ECHA-aligned national agencies are extending compliance obligations to methane monitoring and feed additive documentation. Stakeholders must evaluate whether to build proprietary data lakes or federate across cooperative platforms as regulatory granularity intensifies and insurer premium models begin weighting digitized health records.
Market Dynamics
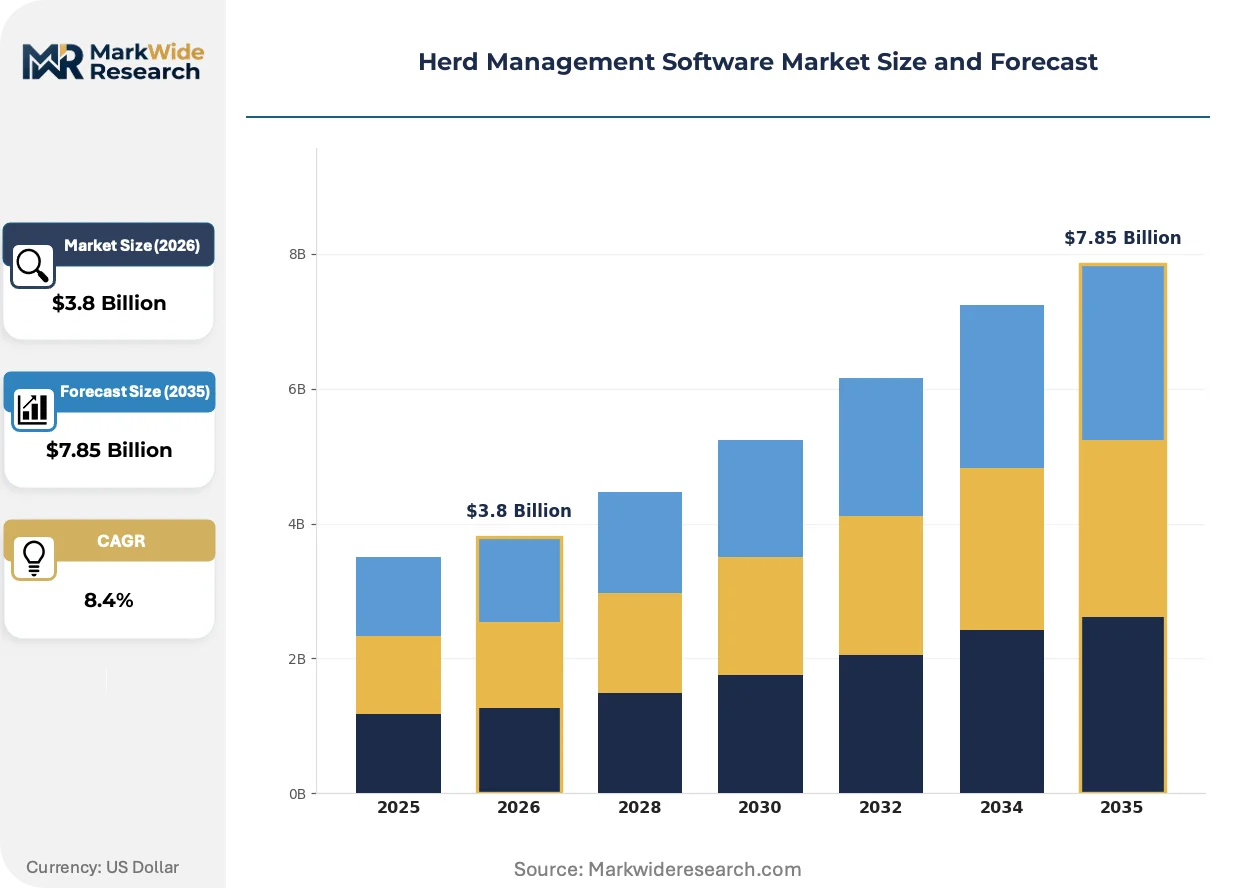
Cloud-native architectures are displacing on-premise deployments among mid-scale dairy operations, compressing vendor margins while expanding addressable market reach through lower upfront capital barriers.
Growth Catalysts
- USDA Animal Disease Traceability mandates:Federal rules requiring electronic identification and movement documentation accelerate digitization among cattle producers seeking compliance automation.
- RFID sensor convergence:Integration of biometric ear tags with rumination monitors enables real-time health alerts that reduce veterinary intervention costs.
- Netherlands precision agriculture clusters:Dense dairy farming regions with government-funded technology adoption programs concentrate procurement of integrated herd platforms.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication bottlenecks in East Asia delay sensor hardware deliveries and inflate component costs for integrated system vendors.
- FDA Veterinary Feed Directive complexity:Granular antibiotic usage documentation requirements create compliance friction for small-scale producers lacking technical staff.
- Legacy data silos:Proprietary formats from incumbent equipment manufacturers obstruct seamless data migration to modern cloud platforms.
Strategic Opportunities
- India dairy cooperative digitization:National livestock mission incentives target 100 million cattle under electronic traceability, opening greenfield software deployments.
- AI-driven predictive breeding:Machine learning models processing genomic and phenotypic data converge to optimize genetic selection decisions.
- EU Green Deal methane monitoring:Emissions reporting obligations create demand for feed additive tracking and enteric fermentation measurement modules.
Industry Challenges
- Veterinary data science talent scarcity:Shortage of professionals combining livestock health expertise with statistical modeling slows algorithm deployment.
- Multi-farm integration complexity:Agricultural cooperatives managing member data estates face technical obstacles unifying disparate legacy systems under unified governance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herd Management Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Solutions, Mobile Applications, Standalone Software End User: Dairy Farmers, Beef Cattle Producers, Agricultural Cooperatives, Livestock Management Businesses Feature: Health Monitoring, Breeding Management, Feed Management, Data Analytics Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Local Server |
| Companies Covered | BouMatic LLC, Antelliq France SAS, GEA Group Aktiengesellschaft, Agriwebb, Nedap N.V., DeLaval International Aktiebolag, Afimilk Ltd., Vytelle, Lely Holding S.C.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herd Management Software Market Trends and Innovations
Artificial intelligence architectures are bifurcating competitive positioning between hardware-integrated incumbents and lean software-native entrants, reshaping how value capture distributes across the technology stack.
Edge computing deployments for real-time estrus detection are bifurcating processing architectures between cloud-dependent analytics and on-device inference. Large-scale confinement dairies in the US Midwest adopt localized computing to minimize latency for time-sensitive breeding decisions. This technical split is bifurcating vendor roadmaps and forcing strategic bets on where intelligence should reside.
EU Green Deal livestock emissions frameworks through ECHA-aligned national agencies mandate methane quantification and feed additive documentation. Dairy processors purchasing milk under sustainability-linked contracts now require supplier software integration for emissions verification. Dutch and Danish producers face the most immediate compliance deadlines, accelerating procurement of monitoring modules.
Subscription pricing for predictive health analytics is displacing perpetual license models among mid-scale operators. Vendors bundle algorithmic disease early-warning with hardware leases, capturing recurring revenue while lowering customer capital barriers. This commercial shift concentrates most visibly in US dairy regions where cooperative financing structures favor operational expenditure treatment.
Herd Management Software Market Segmentation
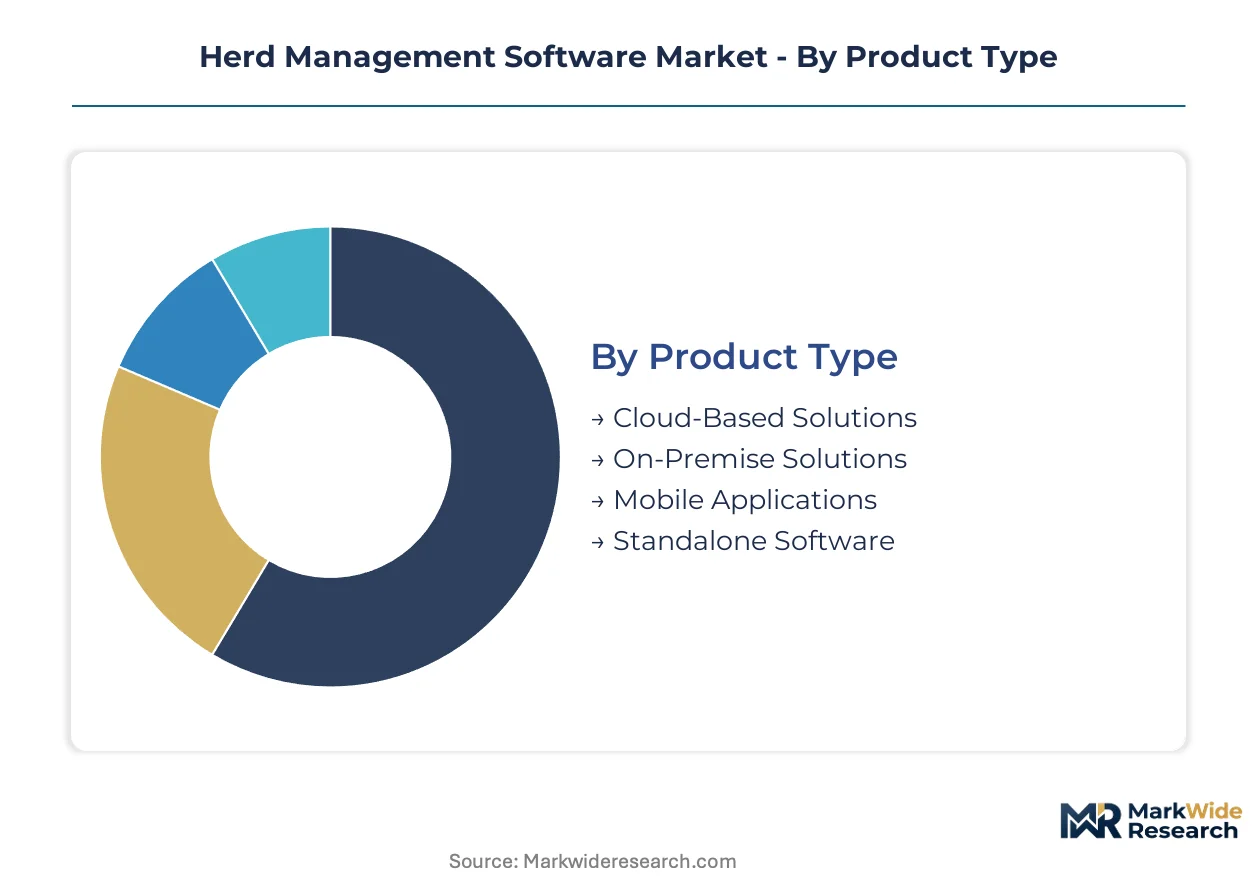
Herd management software segments reflect divergent technology maturity and customer capital constraints. Deployment architecture and feature depth determine vendor margin capture across dairy, beef, and cooperative end users.
Product Type:
Margin pools concentrate in recurring-revenue cloud platforms that reduce customer churn through embedded data gravity.
- Cloud-Based Solutions:Multi-tenant SaaS architectures process sensor telemetry through centralized analytics engines. Dairy cooperatives in Wisconsin and California favor these platforms for multi-farm data federation without infrastructure overhead. USDA traceability mandates accelerate procurement among mid-scale operators lacking IT staff.
- On-Premise Solutions:Single-tenant installations run on customer-controlled servers with offline operational capability. Privacy-sensitive agricultural cooperatives in the Netherlands and Denmark retain this model to maintain strict member data governance under cooperative bylaws. Higher upfront license fees compress addressable market but preserve premium pricing power.
- Mobile Applications:Lightweight iOS and Android clients extend field access to breeding and health records.
- Standalone Software:Perpetual-license desktop applications serve small producers with minimal integration requirements.
The dominant share belongs to Cloud-Based Solutions, while Mobile Applications are closing the gap fastest through bring-your-own-device adoption among younger farm operators.
End User:
Customer type dictates integration complexity and willingness to pay for predictive capabilities.
- Dairy Farmers:Milk yield optimization drives demand for estrus detection algorithms and mastitis early-warning systems. Dutch dairy clusters under EU Green Deal emissions frameworks procure methane monitoring modules alongside core herd management functions. Per-cow data granularity justifies premium subscription tiers.
- Beef Cattle Producers:Pasture-based operations prioritize RFID-based movement tracking and electronic identification for USDA Animal Disease Traceability compliance. Feedlot operators in Texas and Nebraska adopt health monitoring to reduce antibiotic usage documentation friction under FDA Veterinary Feed Directive rules.
- Agricultural Cooperatives:Multi-member governance structures require federated data architectures with strict access controls.
- Livestock Management Businesses:Contracted herd management services seek white-label platform capabilities for client differentiation.
Dairy Farmers command the largest revenue pool, though Beef Cattle Producers are expanding fastest as traceability mandates tighten.
Feature:
Functional modules stratify by algorithmic sophistication and sensor hardware dependency.
- Data Analytics:Machine learning models process genomic, phenotypic, and environmental signals to optimize breeding decisions and predict disease onset. Large confinement dairies in the US Midwest deploy these capabilities for real-time intervention timing. Vendor roadmaps bifurcate between cloud-dependent training and edge inference architectures.
- Health Monitoring:Integration of rumination sensors, pedometers, and milk composition analyzers enables automated welfare alerts. Netherlands producers face immediate compliance deadlines for emissions-linked health documentation under ECHA-aligned national agencies.
- Breeding Management:Estrus detection and artificial insemination scheduling tools leverage behavioral biometrics.
- Feed Management:Ration optimization modules track intake and connect to feed additive compliance workflows.
Data Analytics captures the steepest expansion trajectory, while Health Monitoring retains the largest installed base through sensor hardware bundling.
Deployment:
Infrastructure location determines latency, sovereignty, and total cost of ownership tradeoffs.
- Public Cloud:Shared infrastructure delivers lowest per-seat economics and automatic software updates. Mid-scale dairy operators across Iowa and Minnesota prefer this model for zero capital expenditure and rapid scaling during expansion phases.
- Hybrid Cloud:Sensitive data remains on-premises while analytics workloads burst to public infrastructure. Danish agricultural cooperatives deploy this architecture to satisfy member privacy requirements while accessing advanced AI training resources.
- Private Cloud:Dedicated single-tenant environments serve regulated enterprises with audit requirements.
- Local Server:Air-gapped installations support operations with unreliable connectivity or extreme data sovereignty needs.
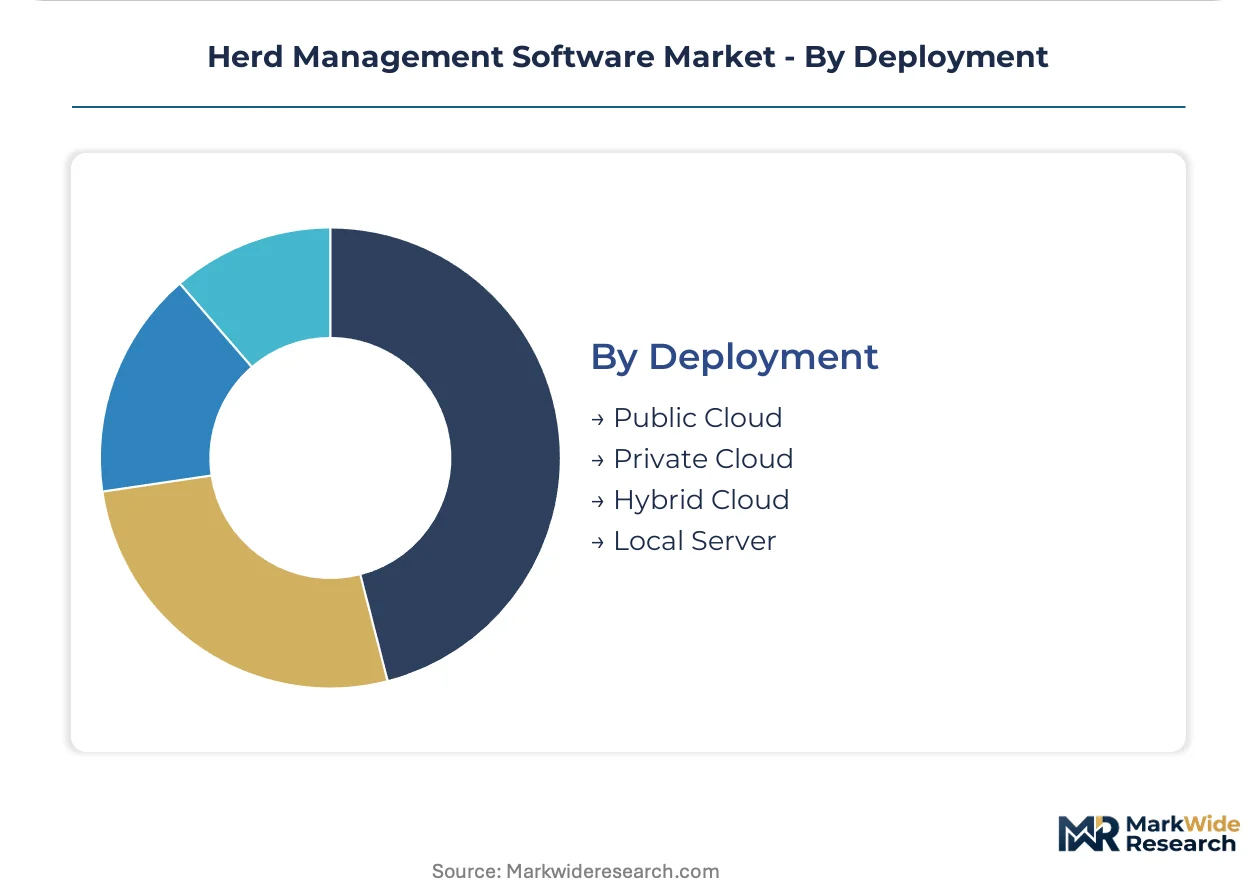
Public Cloud holds the dominant position, yet Hybrid Cloud is gaining share fastest among privacy-conscious cooperative structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies, with smallholder-dominated regions resisting subscription models while capital-intensive dairy clusters in Western Europe absorb premium sensor-integrated platforms without margin compression.
United States
Large confinement dairies in Wisconsin and California drive cloud-native procurement for multi-farm data federation. USDA Animal Disease Traceability mandates accelerate electronic identification adoption among mid-scale operators lacking dedicated IT staff. The Midwest dairy belt concentrates sensor hardware deployments for real-time estrus detection.
Netherlands
Dense dairy farming clusters under government-funded precision agriculture programs generate concentrated demand for integrated herd platforms. EU Green Deal emissions frameworks through ECHA-aligned national agencies mandate methane monitoring and feed additive documentation. The Gelderland and Friesland provinces anchor procurement of sustainability-linked software modules.
India
National livestock mission incentives target electronic traceability for 100 million cattle across dairy cooperatives. The country's central agricultural regulator pushes digitization through subsidized RFID deployments. Gujarat and Maharashtra lead greenfield software adoption among organized cooperative structures.
Germany
Privacy-sensitive agricultural cooperatives in Lower Saxony and Bavaria favor on-premise installations with strict member data governance. The country's federal agricultural ministry enforces granular antibiotic usage documentation under EU veterinary regulations. The northern dairy regions concentrate hybrid cloud deployments balancing sovereignty with AI access.
Australia
Pastoral beef operations prioritize RFID-based movement tracking for biosecurity compliance across vast station holdings. The national agricultural department mandates electronic identification for cattle exports under trade protocols. Queensland and New South Wales concentrate procurement of mobile-first health monitoring solutions.
Herd Management Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where hardware-integrated incumbents compete against lean software-native entrants. The vendor base splits between milking equipment manufacturers bundling analytics subscriptions and pure-play cloud platforms attacking mid-scale price points. Two dominant strategic archetypes have emerged: sensor-hardware bundlers capturing recurring revenue through installed base lock-in, and API-first SaaS vendors federating data across heterogeneous equipment estates. Competitive moves concentrate on M&A for sensor technology access and strategic partnerships with dairy processors for sustainability-linked contract compliance.
Within the hardware-integrated tier, GEA Group Aktiengesellschaft and Nedap N.V. exemplify divergent approaches to value capture—one leveraging milking equipment installed base for subscription bundling, the other anchoring position through proprietary sensor hardware. Afimilk Ltd. occupies a specialist position representing parlor-integrated milk meter vendors feeding real-time data into breeding algorithms. These three entities collectively illustrate how capital-intensity divergence unwinds traditional competitive boundaries across livestock technology.
| Leading Market Players |
|---|
| BouMatic LLC |
| Antelliq France SAS |
| GEA Group Aktiengesellschaft |
| Agriwebb |
| Nedap N.V. |
| DeLaval International Aktiebolag |
| Afimilk Ltd. |
| Vytelle |
| Lely Holding S.C.A. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day semiconductor lead times for RFID sensor modules tether vendor pricing power directly to East Asian foundry capacity allocation, compressing margins for hardware-integrated platforms while software-native entrants exploit component-light architectures. This inventory-to-pricing linkage concentrates cost pressure among Dutch and US dairy technology suppliers dependent on biometric sensor supply chains.
Pricing Analysis
After-sales revenue from predictive health analytics subscriptions drives lifetime value capture across vendor portfolios. Three-tier pricing structure across premium sensor-integrated, standard cloud-native, and economy standalone software levels stratifies by hardware bundling intensity and algorithmic sophistication. Cost compression in the premium tier is intensifying because semiconductor fabrication bottlenecks inflate BOM costs for integrated system vendors. Small-scale beef producers in Texas and Nebraska exhibit highest price sensitivity due to FDA Veterinary Feed Directive compliance friction, while Dutch dairy cooperatives under EU Green Deal mandates absorb premium tiers without negotiation.
Supply Chain Analysis
Strategic stockpile preferences dominate among hardware-integrated vendors buffering against East Asian semiconductor fabrication volatility, while software-native competitors maintain just-in-time cloud infrastructure scaling. Sensor hardware supply concentrates in Taiwan, South Korea, and Japan for RFID chip fabrication and MEMS accelerometer production. Raw material dependencies span silicon wafers, rare earth magnets for pedometer assemblies, and specialized polymers for ruggedized ear tag housings. Single-source vulnerability around TSMC-adjacent foundry capacity for low-power biometric processors creates systemic delivery risk. Distribution runs through dairy equipment OEM dealer networks and direct SaaS sales teams to cooperative procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as USDA traceability mandates and EU methane monitoring rules splinter demand across compliance-heavy and analytics-prioritized buyer archetypes, creating defendable niches for specialized entrants.
For Market Incumbents: Fortify sensor-hardware installed base lock-in through extended service contracts bundling predictive analytics, while accelerating backward integration into proprietary RFID chip design to escape East Asian semiconductor supply volatility. Threat from lean software-native entrants attacking mid-scale price points demands channel control investment through dairy cooperative financing partnerships. For New Entrants and Emerging Players: Anchor in India's national livestock mission digitization wave targeting 100 million cattle traceability, the most penetrable greenfield geography with subsidized RFID deployment tailwinds. White-label platform capabilities for contracted livestock management services in Gujarat and Maharashtra offer fastest revenue ramp, with mobile-first deployment as the critical go-to-market angle against infrastructure-constrained competitors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because USDA and EU Green Deal mandates permanently embed software into livestock operations, transforming cyclical equipment sales into durable recurring revenue streams. Acquisition target archetype: sensor-hardware specialists with parlor-integrated data feeds and established dairy processor sustainability-linked contract relationships. Signal to watch: insurer premium models weighting digitized health records crossing threshold adoption rates in Wisconsin and California cooperative structures.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Hardware Backward Integration | Proprietary RFID chip design escapes TSMC-adjacent foundry bottlenecks inflating competitor BOM costs. |
| Predictive Analytics Subscription Bundling | Algorithmic disease early-warning locked to hardware leases captures recurring revenue from dairy cooperatives. |
| EU Green Deal Compliance Module Development | Methane monitoring and feed additive tracking satisfy ECHA-aligned national agency reporting deadlines for Dutch processors. |
| India Dairy Cooperative White-Label Platform | Subsidized national livestock mission deployments open greenfield software revenue without direct sales infrastructure. |
| Edge Computing Architecture Investment | On-device inference for real-time estrus detection minimizes latency for Midwest confinement dairy breeding decisions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dairy technology procurement officers, cooperative data governance committees, and livestock health algorithm developers; and secondary validation through USDA Animal Disease Traceability rulemakings, FDA Veterinary Feed Directive guidance documents, EU Green Deal livestock emissions frameworks, and SEC filings from publicly traded agricultural equipment manufacturers. Bottom-up triangulation across deployment architecture adoption rates and top-down reconciliation against national cattle inventory databases anchored volume estimates.
Across the projection horizon, the analytical framework modeled deployment architecture, end-user operational scale, feature module sophistication, and regional regulatory compliance intensity as core segmentation dimensions. CAGRs derived from curve-fitting historical digitization penetration patterns against mandate-driven procurement acceleration curves, with sensor hardware cost trajectories and cloud infrastructure price elasticity as key industry-specific forecast inputs.
Material uncertainties — East Asian semiconductor supply disruption, EU methane quantification methodology revisions, and Indian cooperative subsidy allocation shifts — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement timelines and hardware cost normalization trajectories. Revision becomes warranted when USDA traceability compliance thresholds or insurer premium weighting for digitized health records cross adoption inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Cattle Squeeze Market
Livestock Management
China Swine Feed Market
Livestock Management
Global Smart Ear Tags Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Layer Feed Market
Livestock Management
North America Feed Binders Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Animal Identification Market
Livestock Management
Hominy Feed Market
Livestock Management
Wild Birds Products Market
Livestock Management
Livestock Dewormers Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
Cattle Head Catch Market
Livestock Management
North America Swine Feed Market