
 North America Feed Binders Market | 2026-2036
North America Feed Binders Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Binders Market Analytics
A shift from single-source lignin supply toward multi-source carbohydrate and protein-based procurement is recalibrating raw material strategies across the North American feed binder value chain. Archer Daniels Midland leverages its corn processing infrastructure to supply dextrin and modified starch binders at scale across the Midwest. Darling Ingredients sustains a distinct position through rendered protein and fat co-products that serve dual binding and energy functions in ruminant formulations. Borregaard anchors the lignosulfonate segment with Scandinavian-sourced wood chemistry expertise adapted to U.S. pelletizing specifications.
Feed binders are adhesive additives, typically comprising lignosulfonates, gelatinized starches, or molasses solids, that agglomerate feed ingredients into durable pellets resistant to friability during transport and automated delivery. These materials function through hydration, thermal gelatinization, or surface tension reduction to achieve pellet durability indices exceeding 90% in commercial broiler and layer operations. Lignosulfonates and molasses dominate volume due to established supply chains from pulp milling and sugar refining, while starch variants command premium positioning in aquaculture and specialty ruminant diets where water stability requirements are stringent. Powder and granule forms lead current consumption patterns, though liquid application systems are gaining traction in integrated poultry operations seeking continuous mixer integration.
The FDA veterinary feed directive and EPA nutrient management requirements shape formulation choices by restricting certain medicated additives and mandating manure phosphorus controls that indirectly affect binder selection for nutrient precision. The Canadian Food Inspection Agency and USDA-APHIS maintain parallel import and safety standards that influence cross-border ingredient flows and manufacturing location decisions. Stakeholders must monitor pending state-level antibiotic reduction mandates and their downstream effects on binder functionality specifications in medicated feed transitions.
Market Dynamics
The FDA veterinary feed directive compresses formulation timelines across North American feed operations, forcing manufacturers to requalify binding agents under stricter medicated feed protocols while maintaining pellet durability standards.
Growth Catalysts
- GRAS-certified binding agents:The FDA's veterinary feed directive accelerates substitution of legacy binders with generally recognized as safe alternatives in swine and poultry integrator operations.
- Poultry integrators in the southeastern United States:Bulk handling efficiency mandates drive binder adoption to reduce feed waste during automated delivery and transport.
- Lignosulfonate supply chains:Established pulp milling infrastructure from Scandinavian wood chemistry operations secures cost-competitive raw material flows into U.S. pelletizing facilities.
Market Restraints
- Carbohydrate feedstock volatility:Corn and wheat starch prices fluctuate with Midwest grain harvest cycles, compressing margins for modified starch binder producers.
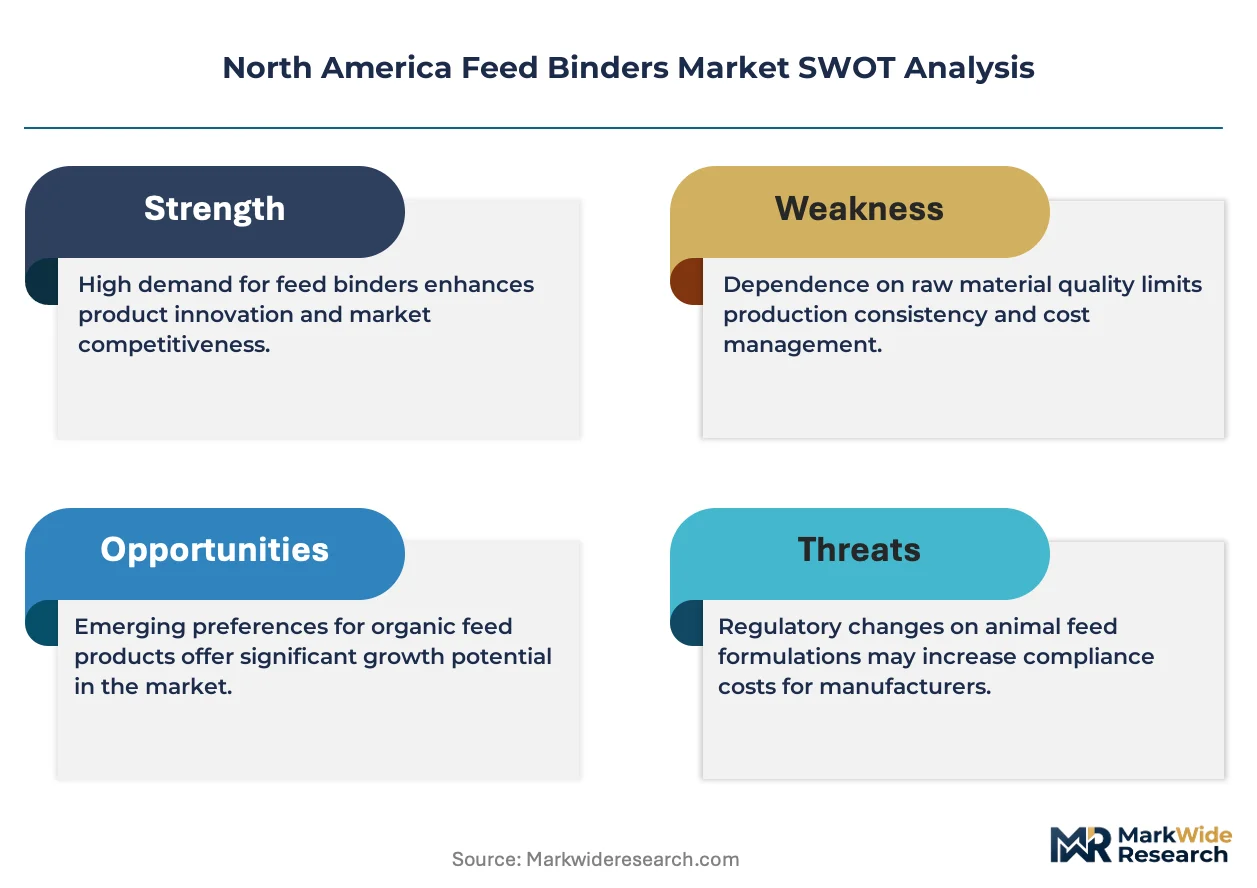
- Scandinavian lignin concentration:Borregaard's dominance in wood chemistry expertise creates single-source dependency risk for lignosulfonate specifications.
- Aquaculture water stability requirements:Starch variants face technical ceiling effects in high-moisture environments where gelatinization thresholds limit binding efficacy.
Strategic Opportunities
- Canadian ruminant operations:Underpenetrated demand for rendered protein-fat co-products in Alberta and Saskatchewan cattle feeding presents white space for dual-function binder-energy additives.
- Continuous mixer integration:Liquid application systems enable new channel entry into integrated poultry operations seeking automated binder dosing.
- EPA nutrient management alignment:Phosphorus control mandates create tailwind for precision-formulated binders that reduce manure nutrient loading.
Industry Challenges
- GRAS requalification timelines:FDA documentation requirements for novel binding agents extend product development cycles by 18-24 months.
- Legacy feed mill retrofit costs:Powder-to-liquid system conversions demand capital outlays that mid-scale operations defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Binders Market |
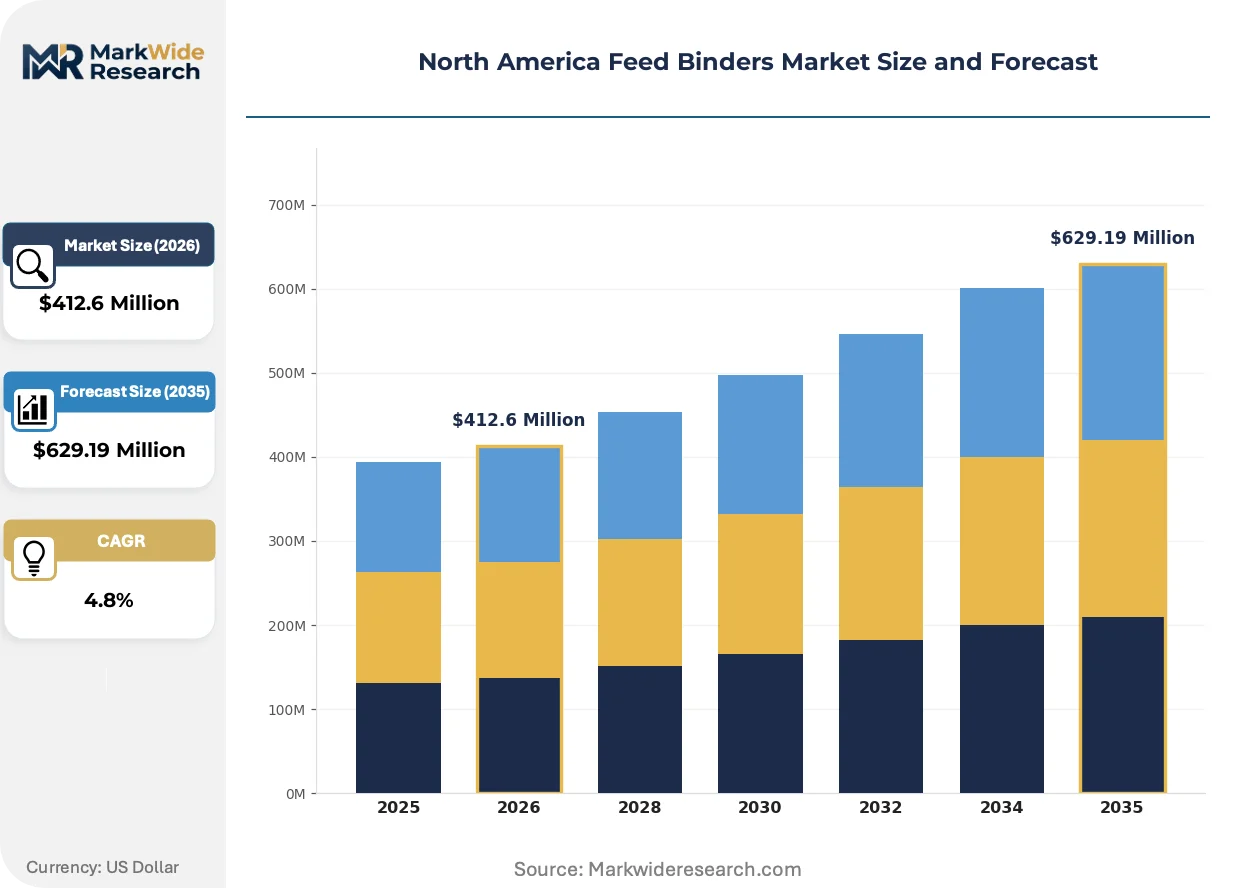
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Starch, Lignosulfonates, Molasses End User: Poultry, Swine, Ruminants, Aquaculture Functionality: Binding, Pelletizing, Coating, Nutrient Delivery Form: Powder, Granule, Liquid, Tablet |
| Companies Covered | Archer Daniels Midland, Darling Ingredients, Borregaard, Nouryon, Cra-Vac Industries, Kemin Industries, DuPont, Alltech, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Binders Market Evolving Landscape
Binding technology is fragmenting across hydration chemistry, thermal processing, and surface-active formulations as end-users demand application-specific performance rather than commodity pelletizing solutions.
Modified starch chemistry is converging with enzymatic pre-treatment protocols to enhance water stability in aquaculture feeds. Pacific Northwest salmon and trout operations pilot these systems at commercial scale. The convergence is compressing demand for traditional molasses-lignosulfonate blends in marine applications.
EPA nutrient management requirements tighten phosphorus discharge thresholds for concentrated animal feeding operations. Large-scale swine integrators in Iowa and North Carolina reformulate binders to enable precise nutrient density control. The regulation accelerates substitution of high-ash lignosulfonates with low-residue carbohydrate alternatives.
Specification-driven procurement now dominates volume contracting for feed binders. Midwest grain cooperatives consolidate purchasing through centralized ingredient sourcing platforms, displacing direct mill-supplier relationships. The pattern concentrates most visibly in U.S. Corn Belt cattle and swine operations where procurement teams negotiate multi-year binder supply agreements.
North America Feed Binders Market Segmentation
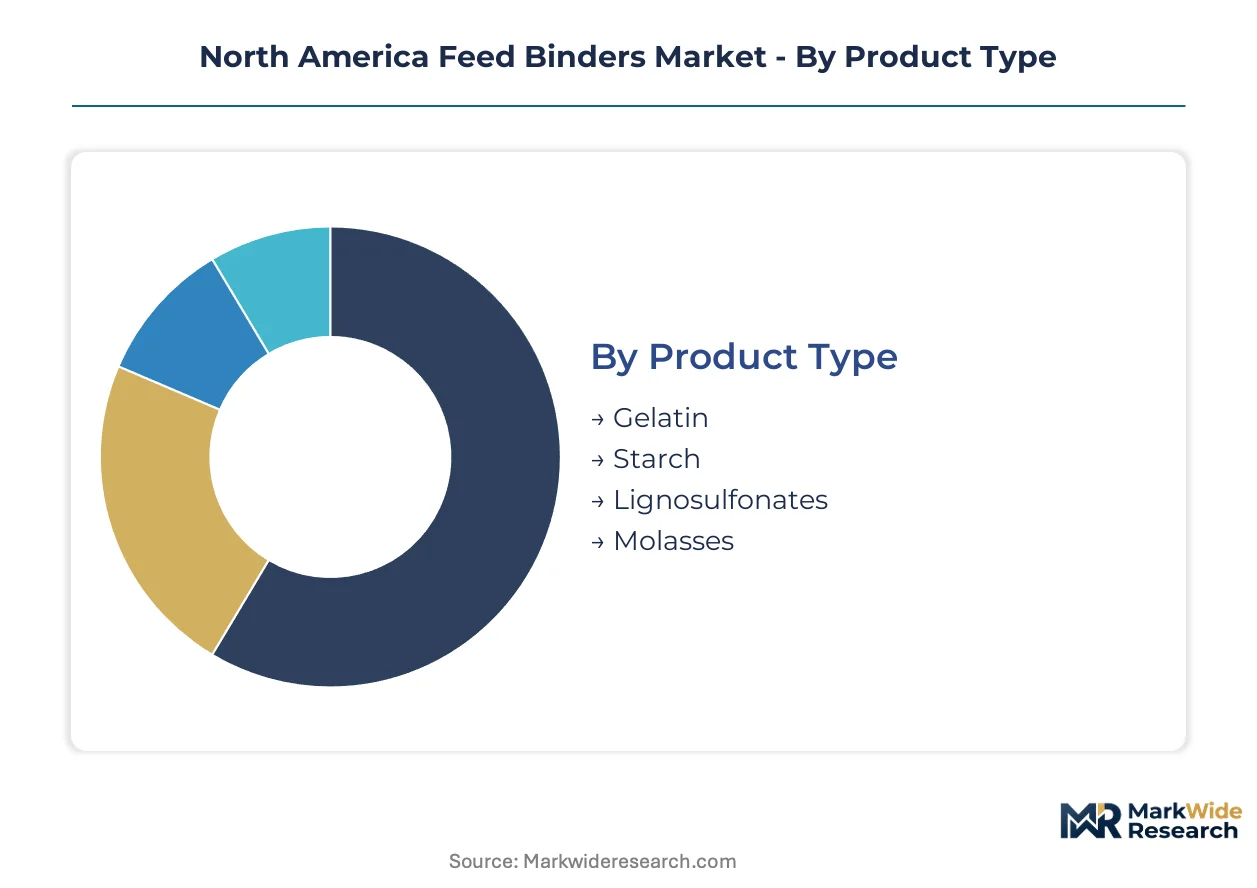
Feed binder procurement in North America stratifies sharply across product chemistry, animal species requirements, and application systems. Understanding these divisions reveals where formulation investments concentrate and where specification gaps create entry opportunities for alternative suppliers.
Product Type:
Standalone commodity binders dominate bulk procurement, while modified and blended variants embed into precision-formulation systems for specialized end-uses.
- Lignosulfonates:Derived from sulfite pulping of softwood lignin, these anionic polymers achieve pellet durability indices above 90% through surface tension reduction and electrostatic binding. Demand concentrates in Iowa and North Carolina swine operations where bulk handling efficiency mandates drive volume procurement. The EPA's phosphorus discharge thresholds are accelerating substitution toward lower-ash carbohydrate alternatives in these same facilities.
- Starch:Corn and wheat derivatives undergo thermal gelatinization to form irreversible gels that bind feed particles under mechanical pressure. Modified starch variants command premium positioning in Pacific Northwest aquaculture operations where water stability requirements exceed 24 hours. Corn processing infrastructure across the Midwest secures cost-competitive supply chains for dextrin and pre-gelatinized grades.
- Molasses:Cane and beet refining co-products provide hygroscopic binding through viscous adhesion and palatability enhancement.
- Gelatin:Collagen-derived hydrocolloids serve niche applications requiring thermo-reversible binding and controlled release properties.
Lignosulfonates lead volumes today; starch variants are gaining share fastest.
End User:
Species-specific digestive physiology and feeding infrastructure dictate binder selection, with ruminant and monogastric requirements diverging on nutrient density and pellet durability specifications.
- Poultry:Broiler and layer integrators across the southeastern United States prioritize pellet friability resistance for automated delivery systems. The FDA's veterinary feed directive compresses formulation timelines, forcing requalification of binding agents under stricter medicated feed protocols while maintaining durability standards above 85%.
- Swine:Large-scale operations in the U.S. Corn Belt drive procurement of lignosulfonate and starch-based solutions for nursery and finishing diets. Nutrient precision requirements under EPA manure management rules favor low-residue binders that enable exact phosphorus dosing.
- Ruminants:Cattle feeding operations in Alberta and Saskatchewan present underpenetrated demand for rendered protein-fat co-products serving dual binding and energy functions.
- Aquaculture:Salmon and trout facilities in the Pacific Northwest pilot enzymatically pre-treated starch systems for extended water stability.
Poultry operations anchor current procurement volumes; aquaculture applications are expanding most quickly.
Functionality:
Core binding applications absorb the majority of volume, while value-added functions command pricing premiums through nutrient delivery and protective coating capabilities.
- Binding:Primary agglomeration function achieving mechanical durability through hydration chemistry, thermal gelatinization, or surface-active mechanisms. Powder and granule forms dominate this application in commercial broiler and layer operations.
- Pelletizing:Process-specific optimization for extrusion and compression systems, with lignosulfonates and molasses serving as established workhorses in high-throughput facilities.
- Coating:Surface application for dust suppression, palatability enhancement, and controlled nutrient release in specialty diets.
- Nutrient Delivery:Functional integration of binding with vitamin, mineral, or medication incorporation, subject to FDA veterinary feed directive compliance requirements.
Binding functions capture the largest share; nutrient delivery applications show the steepest expansion trajectory.
Form:
Physical presentation determines equipment compatibility, with powder and granule formats entrenched in legacy mill infrastructure while liquid systems enable continuous processing integration.
- Powder:Dry-flowing particles suit batch mixing operations across Midwest grain cooperatives and independent feed mills. Established handling infrastructure and dosing equipment sustain this format's dominance in cattle and swine operations.
- Granule:Agglomerated particles reduce dust generation and improve flowability in automated handling systems. Poultry integrators favor this format for bulk transport efficiency.
- Liquid:Pumpable concentrates enable continuous mixer integration and precise dosing control. Integrated poultry operations in the southeastern United States are retrofitting facilities to accommodate liquid application systems.
- Tablet:Compressed units serve niche applications requiring exact unit dosing or slow-release functionality.
Powder and granule forms dominate procurement today; liquid systems are penetrating fastest among new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Corn Belt anchors North American feed binder procurement through concentrated swine and cattle feeding infrastructure that drives volume demand for lignosulfonate and starch-based pelletizing solutions.
United States
Poultry integrators across Georgia and Alabama are retrofitting facilities for liquid binder application systems to reduce feed waste in automated bulk handling operations. The FDA's veterinary feed directive forces requalification of binding agents under stricter medicated feed protocols. Iowa and North Carolina swine operations are substituting high-ash lignosulfonates with low-residue carbohydrate alternatives to meet EPA phosphorus discharge thresholds.
Canada
Alberta and Saskatchewan cattle feeding operations present underpenetrated demand for rendered protein-fat co-products serving dual binding and energy functions. The Canadian Food Inspection Agency maintains parallel import and safety standards that influence cross-border manufacturing location decisions. Prairie Provinces grain cooperatives are consolidating binder procurement through centralized ingredient sourcing platforms.
Mexico
Poultry production clusters in Querétaro and Jalisco are expanding integrated operations that require pellet durability standards exceeding 85% for automated delivery systems. The country's national agricultural regulator enforces feed safety standards aligned with USDA-APHIS protocols for cross-border ingredient flows. Bajío Region feed mills are sourcing modified starch binders from U.S. Midwest suppliers to bypass domestic corn price volatility.
North America Feed Binders Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty aquaculture and precision-formulation niches. The market structure concentrates around three archetypes: diversified agricultural processors with captive corn processing infrastructure, rendered protein specialists leveraging co-product streams, and Scandinavian lignin chemistry providers with pulp milling supply chains. Competitive moves center on backward integration into carbohydrate feedstock supply and geographic expansion into underpenetrated Canadian ruminant markets.
Within the diversified processor tier, Archer Daniels Midland exemplifies scale-driven positioning through Midwest corn processing infrastructure. Darling Ingredients occupies a distinct position among rendered protein specialists. Borregaard anchors the lignosulfonate segment with Scandinavian-sourced wood chemistry expertise adapted to U.S. pelletizing specifications.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Darling Ingredients |
| Borregaard |
| Nouryon |
| Cra-Vac Industries |
| Kemin Industries |
| DuPont |
| Alltech |
| Cargill |
| Others |
Value Network & Pricing Analysis
EPA phosphorus discharge mandates gate both qualified supply and premium-tier pricing access for feed binder manufacturers serving large-scale swine integrators in Iowa and North Carolina. Low-residue carbohydrate alternatives command 15-20% price premiums over high-ash lignosulfonates as operators reformulate to meet nutrient precision requirements.
Pricing Analysis
Input-cost pass-through from Midwest grain harvest cycles dominates modified starch binder pricing, with corn and wheat starch producers adjusting contract rates quarterly to preserve margins. Three-tier pricing structure across premium, standard, and economy levels separates enzymatically pre-treated aquaculture grades from commodity lignosulfonates and molasses workhorses. Cost compression in standard-tier lignosulfonates is intensifying because Scandinavian pulp milling capacity constraints limit supply elasticity. Mid-scale independent feed mills exhibit highest price sensitivity, while integrated poultry operators prioritize durability performance over unit cost.
Supply Chain Analysis
Direct-to-feed-mill channels handle volume demand from Midwest grain cooperatives and southeastern poultry integrators, bypassing distributor markups for multi-year contract holders. Raw material flows draw from Scandinavian pulp mills for lignosulfonates, U.S. Corn Belt processing facilities for dextrin and modified starches, and Gulf Coast sugar refineries for molasses solids. Single-source vulnerability concentrates in Borregaard's Scandinavian wood chemistry operations, creating specification risk for U.S. pelletizing facilities dependent on imported lignin. Distribution runs through centralized ingredient sourcing platforms that displace legacy direct mill-supplier relationships across Prairie Provinces grain cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Feed Binders Market functions as a stable compounder anchored by persistent regulatory pressure on medicated feed formulations and nutrient discharge compliance that sustains steady demand for qualified binding agents.
For Market Incumbents: Deploy backward integration into corn processing infrastructure to secure cost-competitive dextrin supply and defend margin position against carbohydrate feedstock volatility. Incumbents must accelerate GRAS requalification documentation for novel binding agents to compress 18-24 month FDA timelines and preempt emerging entrants from capturing aquaculture water stability niches. Capacity addition in Alberta and Saskatchewan addresses underpenetrated Canadian ruminant demand for rendered protein-fat co-products.
For New Entrants and Emerging Players: Aquaculture integrators in the Pacific Northwest represent the most penetrable entry point, where enzymatically pre-treated starch systems displace traditional molasses-lignosulfonate blends. White space exists in liquid application system manufacturing for southeastern U.S. poultry retrofit projects. New entrants should pursue co-development partnerships with continuous mixer equipment suppliers to embed binding chemistry into automated dosing architectures.
For Investors and Strategic Acquirers: Roll-up economics work for regional rendered protein specialists because Prairie Provinces cattle feeding operations lack integrated binder-energy additive suppliers and procurement consolidation creates scale advantages. Long-term viability over a 5-10 year window rests on EPA nutrient management rule expansion and state-level antibiotic reduction mandate proliferation. Acquisition targets should exhibit captive co-product streams and FDA GRAS certification infrastructure. The signal to watch is Iowa and North Carolina swine integrator adoption rates for low-residue carbohydrate alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Archer Daniels Midland's captive supply of dextrin and modified starches secures cost advantage against volatile Midwest grain cycles. |
| GRAS Certification Investment | FDA documentation acceleration compresses novel binder development timelines and opens medicated feed formulation channels. |
| Liquid Application System Manufacturing | Continuous mixer integration enables new channel entry into Georgia and Alabama poultry integrator retrofit projects. |
| Canadian Ruminant Market Expansion | Alberta and Saskatchewan cattle feeding operations present underpenetrated demand for dual-function protein-fat co-products. |
| Enzymatic Pre-treatment Development | Pacific Northwest salmon and trout operations pilot enhanced water stability systems that displace legacy marine binder blends. |
Research Methodology
Direct dialogue with feed mill operations managers, poultry integrator procurement directors, rendered protein supplier technical leads, and FDA regulatory affairs specialists grounded this analysis in operational reality. Primary interview insights combined with secondary validation from USDA-APHIS import records, EPA nutrient management enforcement data, Canadian Food Inspection Agency feed safety standards, and SEC 10-K filings from diversified agricultural processors. Bottom-up volume estimates from species-specific feed production statistics and top-down market sizing from binder consumption intensity metrics underwent cross-triangulation to reconcile discrepancies.
Bottom-up modeling tracked lignosulfonate, starch, molasses, and gelatin consumption across poultry, swine, ruminant, and aquaculture end-uses, with form-specific intensity factors applied to powder, granule, liquid, and tablet presentations. Top-down analysis calibrated aggregate market evolution against macro drivers including FDA veterinary feed directive implementation phases and EPA concentrated animal feeding operation permit expansions. CAGRs derived from segmented growth rate assumptions weighted by base-year procurement volumes across the analysis window. Industry-specific forecast inputs incorporated pulp milling capacity utilization from Scandinavian suppliers and Midwest corn processing infrastructure expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA phosphorus threshold revisions and state-level antibiotic mandate proliferation that could accelerate or compress binder reformulation cycles. Forecasts reflect documented assumptions regarding GRAS requalification timeline stability and Scandinavian lignin supply chain continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Poultry Feed Market
Livestock Management
Cattle Head Catch Market
Livestock Management
Roughage Feed Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Animal Identification Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Cattle Squeeze Market
Livestock Management
Pig Feed Market
Livestock Management
Feed Management Software Market
Livestock Management
Animal Feed Protease Market
Livestock Management
Europe Swine Feed Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Hominy Feed Market
Livestock Management
South America Ruminant Feed Market