
 Hominy Feed Market | 2026-2036
Hominy Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Hominy Feed Market Foresight
Soybean meal is pivoting away from certain dairy rations as hominy feed offers comparable energy density at lower input cost. Cargill leverages its integrated corn milling network to secure consistent hominy feed supply across the Upper Midwest. Archer Daniels Midland anchors its position through wet milling co-product optimization that streams hominy feed directly into regional distribution. Bunge competes by extending its Gulf Coast export infrastructure to move surplus hominy feed into Mexican livestock markets.
Hominy feed comprises the germ, bran, and residual endosperm fractions separated during corn alkaline processing, typically containing 10-12% crude protein and 65-70% total digestible nutrients on a dry matter basis. Dairy farms dominate end-user consumption due to hominy feed's palatability and fiber content in high-production lactation diets. Wet hominy feed retains moisture from the milling process and commands logistical advantages near processing plants, while dry hominy feed supports longer-haul distribution to deficit regions. Direct sales channels capture the largest volume flow by linking processors to integrated livestock operations, though agricultural cooperatives are gaining share among mid-size independent farms seeking collective bargaining power.
The FDA enforces mycotoxin action levels under the Food Safety Modernization Act that constrain hominy feed inclusion rates when corn quality deteriorates. The USDA's Agricultural Marketing Service monitors corn co-product grading consistency to maintain trade fluidity between processors and end users. State-level Department of Agriculture inspections in Iowa, Nebraska, and Illinois enforce moisture and foreign material standards at loading points. Stakeholders must monitor drought-induced corn quality volatility and corresponding regulatory tolerance adjustments to optimize inventory timing and formulation flexibility.
Market Dynamics
The Hominy Feed Market is absorbing structural pressure from USDA mycotoxin threshold tightening under the Food Safety Modernization Act, which forces processors to reconfigure sourcing protocols and inventory management while dairy operations seek formulation flexibility.
Growth Catalysts
- Dairy Ration Optimization:Large-scale lactation operations in Iowa and Nebraska are expanding hominy feed inclusion rates as a cost-effective energy alternative to soybean meal, driven by comparable total digestible nutrient profiles at reduced input cost.
- FSMA Compliance Infrastructure:The FDA's updated mycotoxin action levels are accelerating investment in testing and segregation systems that differentiate compliant feed streams and create quality-tiered supply channels.
- Corn Processing Cluster Proximity:Wet milling concentration in Illinois and Indiana generates logistical efficiencies for wet hominy feed distribution, reducing spoilage risk and transport cost for regional livestock operations.
Market Restraints
- Corn Quality Volatility:Drought-induced aflatoxin and fumonisin spikes in the Midwestern grain belt constrain inclusion rates and trigger regulatory rejection, forcing processors to maintain costly buffer inventories.
- Moisture Degradation Risk:Wet hominy feed's 60-70% moisture content limits distribution radius to approximately 150 miles from processing plants, creating supply gaps in deficit regions lacking dry processing capacity.
- Soybean Meal Substitution Elasticity:Protein price arbitrage periodically reverses, causing dairy nutritionists to revert to soybean meal when crush margins compress vegetable protein costs below hominy feed equivalence.
Strategic Opportunities
- Mexican Livestock Export Corridor:Bunge's Gulf Coast infrastructure extension demonstrates viability for surplus Midwest hominy feed movement into Sonora and Chihuahua cattle finishing operations, accessing price-premium deficit markets.
- Cooperative Procurement Platforms:Mid-size independent dairy farms in Wisconsin and Minnesota are aggregating through agricultural cooperatives to secure collective bargaining power and direct processor contracts previously reserved for integrated operations.
- Dry Fractionation Investment:Capital deployment into regional drying facilities would extend distribution reach to Southeastern poultry markets currently dependent on local corn byproducts with inferior fiber profiles.
Industry Challenges
- Mycotoxin Testing Skill Gap:State Department of Agriculture inspection protocols in Iowa, Nebraska, and Illinois require certified sampling technicians that rural elevators struggle to recruit and retain, creating compliance bottlenecks at loading points.
- Moisture Standardization Complexity:Wet hominy feed's variable moisture content complicates total mixed ration formulation precision, forcing nutritionists to implement real-time dry matter correction protocols that increase labor intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hominy Feed Market |
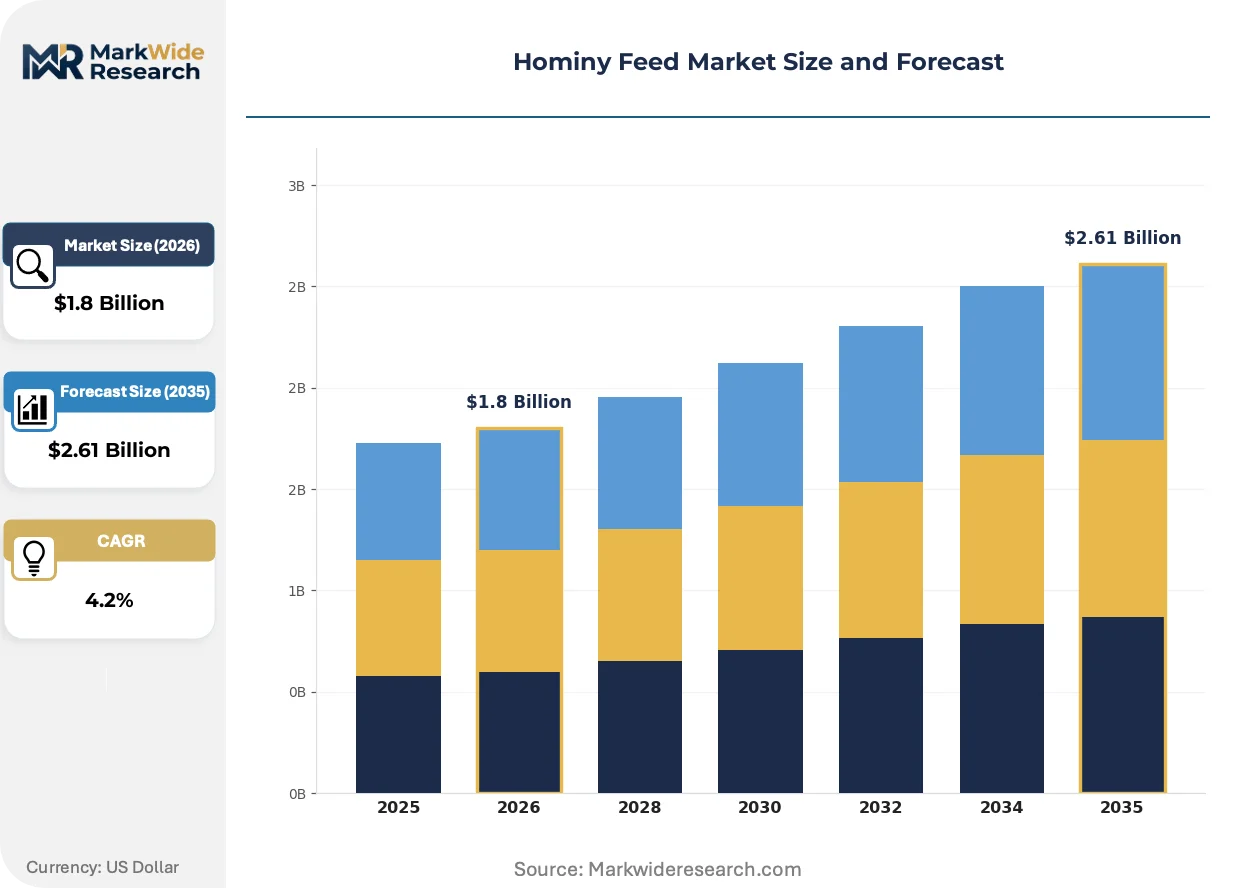
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Hominy Feed, Wet Hominy Feed, Hominy Pellets, Coarse Hominy Feed End User: Dairy Farms, Poultry Farms, Swine Farms, Aquaculture Distribution Channel: Direct Sales, Wholesalers, Online Retailers, Agricultural Cooperatives Manufacturing Stage: Processing, Packaging, Distribution, Quality Control |
| Companies Covered | Cargill, Archer Daniels Midland, Bunge, Louis Dreyfus, CHS Inc., Associated British Foods, Ingredion, Tate & Lyle, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hominy Feed Market Shifts & Advancements
Near-infrared spectroscopy deployment and cooperative procurement platform proliferation are compressing traditional supply chain intermediaries while regulatory testing protocols reshape quality differentiation mechanisms across the value chain.
NIR-based mycotoxin screening technology is absorbing quality assurance functions previously performed by centralized laboratory analysis. Dairy cooperatives in Wisconsin and Minnesota are adopting handheld units for load-by-load verification at receiving bays. This capability compression is enabling real-time rejection decisions that protect herd health and reduce regulatory exposure.
The USDA Agricultural Marketing Service is tightening corn co-product grading consistency protocols to maintain trade fluidity between wet millers and end users. Industrial consequence includes mandatory moisture and foreign material documentation at transfer points. Dairy operations in Illinois face the most acute adjustment burden as they retrofit receiving infrastructure to capture required data fields.
Direct sales channel expansion is displacing traditional agricultural cooperative intermediaries among large integrated livestock operations. Cargill's processor-to-farm contracting model demonstrates this displacement, offering price transparency and volume commitments that collective bargaining structures struggle to match. This pattern concentrates most visibly across Upper Midwest states where corn processing density supports dedicated logistics arrangements.
Hominy Feed Market Segmentation
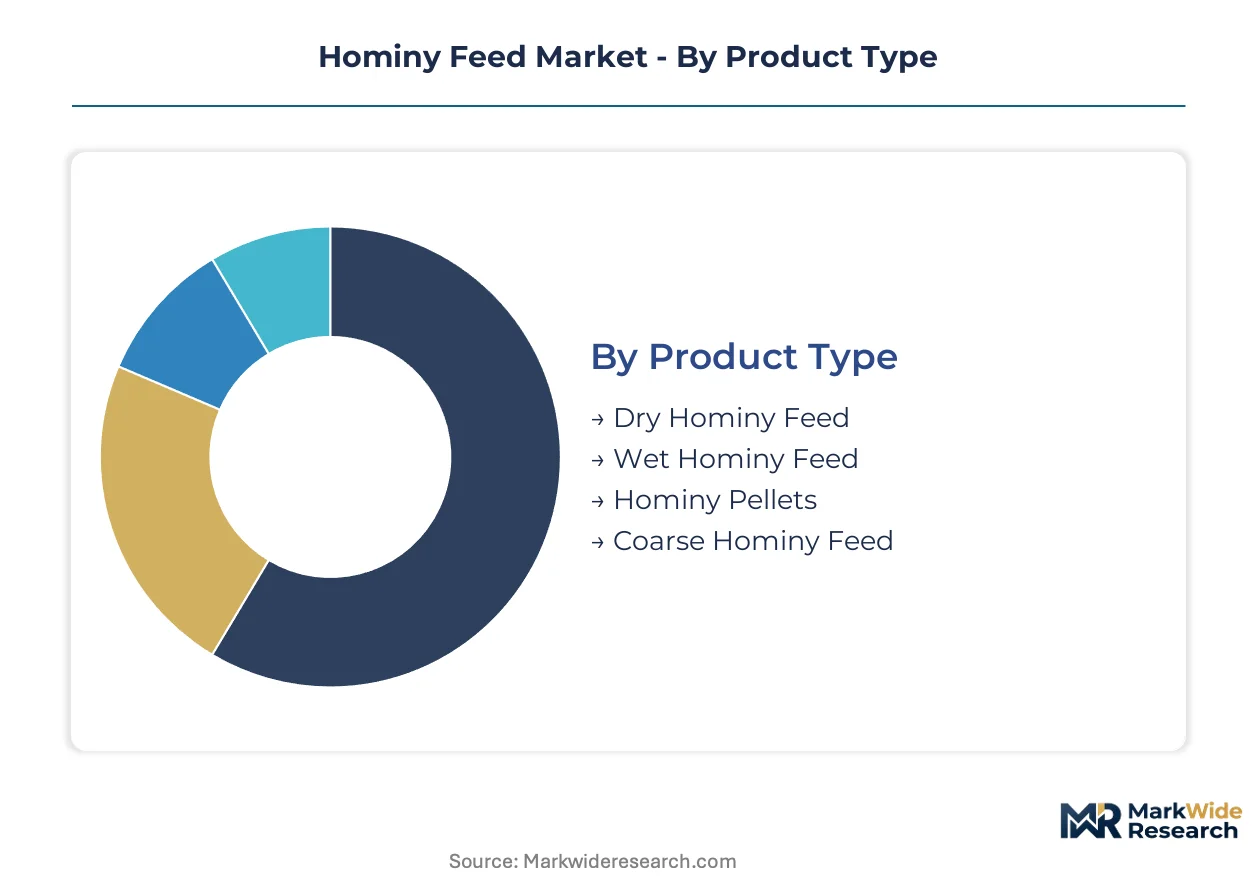
Hominy feed segmentation reflects the tension between perishability and distribution economics. Product form determines logistical radius, end-use dictates formulation precision, and channel structure shapes price transparency across integrated versus independent livestock operations.
Product Type:
Corn milling concentration in Illinois and Indiana creates distinct supply zones for each moisture variant.
- Dry Hominy Feed:Reduced to 10-12% moisture through mechanical dehydration, enabling 500-mile distribution radius to deficit poultry markets. Southeastern broiler operations source this form despite fiber profile limitations relative to local corn byproducts.
- Wet Hominy Feed:Retains 60-70% moisture from alkaline processing, limiting viable transport to 150 miles. Iowa and Nebraska dairy farms capture cost advantages through proximity to wet milling clusters while bearing spoilage risk.
- Hominy Pellets:Compacted form reduces dust and improves handling characteristics for automated feeding systems. Mid-size Wisconsin operations favor this format for total mixed ration consistency.
- Coarse Hominy Feed:Larger particle size supports rumen fiber requirements in high-production lactation diets. Minnesota nutritionists specify this grade for fresh cow transition protocols.
Today's leader: Wet Hominy Feed. Tomorrow's challenger: Dry Hominy Feed.
End User:
Formulation flexibility varies sharply across species-specific digestive physiology and regulatory tolerance.
- Dairy Farms:Palatability and fiber content align with high-production lactation diet requirements. Iowa operations lead inclusion rate expansion as soybean meal price arbitrage periodically favors energy substitution.
- Poultry Farms:Lower fiber tolerance constrains inclusion rates compared to ruminant applications. Southeastern broiler integrators source dry forms where local corn byproduct supply falls short.
- Swine Farms:Monogastric sensitivity to mycotoxins limits deployment during drought-induced corn quality deterioration. Nebraska farrow-to-finish operations maintain buffer inventories for formulation continuity.
- Aquaculture:Emerging demand segment with unproven digestibility coefficients. Channel catfish producers in the Mississippi Delta trial limited inclusion for cost reduction.
Dairy Farms command current volume. Poultry Farms show the steepest expansion trajectory if drying capacity regionalizes.
Distribution Channel:
Channel selection tracks operation scale and bargaining power concentration.
- Direct Sales:Processor-to-farm contracting captures largest volume flow through dedicated logistics arrangements. Cargill's integrated network exemplifies this structure across Upper Midwest states.
- Wholesalers:Aggregate fragmented demand for regional redistribution. Rural elevators in Nebraska serve as consolidation nodes for independent livestock producers.
- Online Retailers:Digital platforms penetrate small hobby farm segments with bagged product offerings. Limited traction in commercial operations due to bulk handling requirements.
- Agricultural Cooperatives:Wisconsin and Minnesota dairy farms aggregate procurement for collective bargaining power. Direct processor contracts previously reserved for integrated operations now accessible through cooperative structures.
Direct Sales dominate transaction value. Agricultural Cooperatives are gaining share fastest among mid-size independents.
Manufacturing Stage:
FSMA compliance pressure reshapes investment allocation across production stages.
- Processing:Germ, bran, and residual endosperm separation during alkaline cooking determines final nutrient profile. Wet millers in Illinois optimize throughput for co-product stream consistency.
- Packaging:Moisture-barrier specifications critical for dry form shelf stability. Bulk tote systems reduce labor at receiving bays for large dairy operations.
- Distribution:Temperature-controlled logistics for wet forms constrain seasonal availability. Bunge's Gulf Coast infrastructure extension demonstrates surplus movement into Mexican livestock markets.
- Quality Control:Near-infrared spectroscopy deployment accelerates load-by-load mycotoxin verification. FDA action levels force segregation systems that differentiate compliant feed streams.
Processing commands capital deployment. Quality Control is climbing the fastest as regulatory tolerance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Upper Midwest wet milling corridor spanning Iowa, Illinois, and Nebraska concentrates North American hominy feed processing capacity within a 300-mile radius of major corn processing clusters.
United States
Dairy farms in Iowa and Wisconsin drive wet hominy feed consumption through proximity to alkaline processing plants. The FDA enforces mycotoxin action levels under FSMA that constrain inclusion rates during drought years. Cargill's integrated corn milling network in Illinois streams hominy feed directly into regional distribution channels serving large-scale lactation operations.
Mexico
Cattle finishing operations in Sonora and Chihuahua import surplus Midwest hominy feed through Gulf Coast export infrastructure. The country's national agricultural health authority monitors import documentation for moisture and foreign material compliance. Bunge's port facilities in Veracruz anchor cross-border movement of dry forms into northern livestock deficit zones.
Canada
Ontario dairy cooperatives source dry hominy feed from U.S. Midwest processors when local corn byproduct supply tightens during harvest delays. Health Canada/CFIA enforces feed safety standards aligned with FSMA thresholds for aflatoxin and fumonisin. Toronto-area feed mills maintain blending capacity for hominy feed inclusion in total mixed rations serving the province's concentrated lactation sector.
Brazil
ANVISA regulates mycotoxin limits in corn-derived feed ingredients for the country's expanding poultry export sector. São Paulo state feed compounders trial limited hominy feed inclusion in broiler diets where local corn byproduct fiber profiles prove inferior. Processing technology transfer from North American wet millers remains limited by capital constraints in the Center-West corn belt.
Argentina
The Rosario grain hub concentrates corn export flow that leaves limited wet milling co-product availability for domestic livestock feed. The country's national food safety authority applies EU-aligned mycotoxin standards that restrict hominy feed deployment during humid harvest conditions. Buenos Aires province dairy operations rely primarily on soybean meal and local corn silage for energy formulation.
Hominy Feed Market Competitive Landscape
Global majors compete with regional champions across procurement radius and FSMA compliance infrastructure. The market structure consolidates around integrated agribusiness conglomerates with captive corn processing capacity, while mid-size regional millers occupy niche positions in cooperative supply channels. Three archetypes dominate: wet milling specialists with co-product optimization systems, diversified grain traders extending into feed ingredient distribution, and agricultural cooperatives aggregating independent farm demand. Capacity expansion and direct processor-to-farm contracting represent the dominant competitive moves reshaping channel access.
Within the integrated agribusiness tier, Cargill, Archer Daniels Midland, and Bunge exemplify divergent strategic positioning. Cargill anchors the Upper Midwest through dedicated logistics arrangements linking wet milling clusters to large dairy operations. Archer Daniels Midland occupies a position emphasizing wet milling co-product stream consistency and regional distribution density. Bunge extends procurement reach through Gulf Coast infrastructure accessing Mexican livestock markets. Each represents a distinct archetype: captive supply chain control, processing throughput optimization, and export corridor development respectively.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Bunge |
| Louis Dreyfus |
| CHS Inc. |
| Associated British Foods |
| Ingredion |
| Tate & Lyle |
| Roquette Frères |
| Others |
Supply & Pricing Matrix
Captive integration into corn wet milling operations anchors both supply security and pricing power for hominy feed processors across the Upper Midwest. Cargill's processor-to-farm contracting model demonstrates how in-house corn processing capacity insulates margin structures from commodity volatility while enabling volume commitments that independent aggregators struggle to match.
Pricing Analysis
Input-cost pass-through from corn futures and energy inputs dominates pricing formation across wet and dry hominy feed variants. Three-tier pricing structure across premium FSMA-compliant, standard grade, and economy non-certified levels differentiates value capture. Pricing pressure stems from soybean meal price arbitrage that periodically compresses energy feed margins. Large integrated dairy operations exhibit lowest price sensitivity due to formulation lock-in, while mid-size independent farms drive collective bargaining through cooperative structures.
Supply Chain Analysis
Dual-sourcing requirements among major dairy cooperatives mandate qualification of at least two wet millers to mitigate single-plant disruption risk. Supply concentrates in the United States, with secondary flows into Mexico and Canada. Raw material dependencies center on No. 2 yellow corn, caustic soda for alkaline processing, and natural gas for drying operations. Tariff exposure on cross-border movements into Mexican livestock markets creates supply chain risk. Distribution runs through direct processor-to-farm contracting for integrated operations and agricultural cooperative aggregation for independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in hominy feed rests on FSMA compliance infrastructure investment that commands premium pricing from quality-sensitive dairy operations.
For Market Incumbents: Cement supply chain control through captive wet milling capacity additions in Iowa and Illinois to defend against Bunge's export corridor expansion. Prioritize near-infrared spectroscopy deployment at loading points to differentiate FSMA-compliant streams and capture quality-tiered pricing. Regulatory tolerance tightening on mycotoxins threatens non-compliant inventory positions. For New Entrants and Emerging Players: Launch via cooperative procurement platforms serving mid-size Wisconsin and Minnesota dairy farms seeking direct processor contracts. Target dry fractionation investment in the Southeast to access poultry deficit markets currently dependent on inferior local corn byproducts. White-space exists in automated moisture correction services that reduce nutritionist labor intensity. For Investors and Strategic Acquirers: Roll-up economics work for regional drying facility operators because wet-to-dry conversion capacity scarcity constrains distribution reach to deficit poultry markets. Five-to-ten year viability hinges on FSMA compliance infrastructure as a moat against commodity substitution. Monitor FDA mycotoxin action level adjustments as the key inflection signal for inventory valuation and capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| FSMA Compliance Infrastructure Investment | Near-infrared spectroscopy deployment at Iowa and Nebraska loading points enables real-time rejection decisions protecting herd health. |
| Dry Fractionation Capacity Buildout | Southeastern facility investment extends distribution radius to poultry markets dependent on inferior local corn byproducts. |
| Cooperative Procurement Platform Expansion | Wisconsin and Minnesota dairy aggregation secures direct processor contracts previously reserved for integrated livestock operations. |
| Mexican Export Corridor Development | Gulf Coast infrastructure extension moves surplus Midwest supply into Sonora and Chihuahua cattle finishing deficit zones. |
| Wet Milling Co-product Stream Optimization | Illinois and Indiana throughput adjustments improve hominy feed consistency for total mixed ration formulation precision. |
Research Methodology
Coverage spans the United States, Mexico, Canada, and Brazil, with primary inputs from each market's stakeholder base. The analysis combines interviews with wet milling operations managers, dairy nutritionists, agricultural cooperative procurement leads, and FDA compliance officers with secondary validation from USDA Agricultural Marketing Service reports, FDA FSMA guidance documents, EPA energy input disclosures, and customs trade flow data. Bottom-up volume estimates from processor capacity utilization triangulate against top-down feed ingredient demand models.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions modeled include product moisture form, end-user species application, distribution channel structure, and FSMA compliance tier. CAGRs derive from regression analysis against corn processing throughput, dairy herd expansion patterns, and regulatory tolerance adjustment scenarios. Industry-specific inputs incorporate mycotoxin testing technology adoption curves and cooperative membership growth rates.
Several conditions sit outside the modeled scope, including extreme drought frequency beyond historical baselines and biotechnology breakthroughs in corn co-product digestibility. Forecasts reflect assumptions about regulatory stability and feed safety protocol harmonization. Deviation in FDA mycotoxin action level stringency or Midwestern corn quality volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Dairy Herd Management Market
Livestock Management
Hog Production and Pork Market
Livestock Management
Layer Feed Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Wild Birds Products Market
Livestock Management
Poultry Health Market
Livestock Management
Wagyu Beef Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Poultry Feed Market
Livestock Management
Global Smart Ear Tags Market
Livestock Management
Roughage Feed Market
Livestock Management
Animal Identification Market
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Cattle Feeder Market