
 South America Ruminant Feed Market | 2026-2036
South America Ruminant Feed Market Size, Share, and Industry Trends Forecast 2026-2036
South America Ruminant Feed Market Analytics
Aftermarket nutritional consulting revenue is tilting toward formulation services as ranchers seek precision feeding programs. Cargill, Incorporated leverages its Pan-American laboratory network to deliver customized mineral premixes for Brazilian Nelore operations. ADM sustains crushing-integrated feed economics through its soy processing footprint in Mato Grosso. Nutreco NV anchors premium positioning via Trouw Nutrition's technical service teams deployed across Argentina's Pampas.
South America ruminant feed encompasses complete, supplementary, and premix formulations designed to meet metabolizable energy and crude protein specifications for cattle, sheep, goats, and bison, typically incorporating corn, soybean meal, and regionally sourced sugarcane pulp as primary substrates. The primary purpose centers on optimizing feed conversion ratios and average daily gain in confined and semi-confined production systems. Complete feed occupies the dominant value share where Brazilian feedlots scale operations, while additives represent the fastest-expanding margin pool as beta-agonist and ionophore regulations tighten. Premixes concentrate technical value as veterinarians and nutritionists assume greater prescribing authority over mineral and vitamin supplementation protocols.
Brazil's MAPA and Argentina's SENASA enforce mycotoxin maximum limits and feed mill registration requirements that elevate compliance costs for smaller regional blenders. ANVISA oversight of veterinary drug residues in meat exports directly shapes additive approval pathways and withdrawal period labeling. Stakeholders must monitor evolving Mercosur harmonization talks on feed safety standards, as regulatory misalignment between Brazil and Argentina threatens cross-border formulation portability and procurement planning.
Market Dynamics
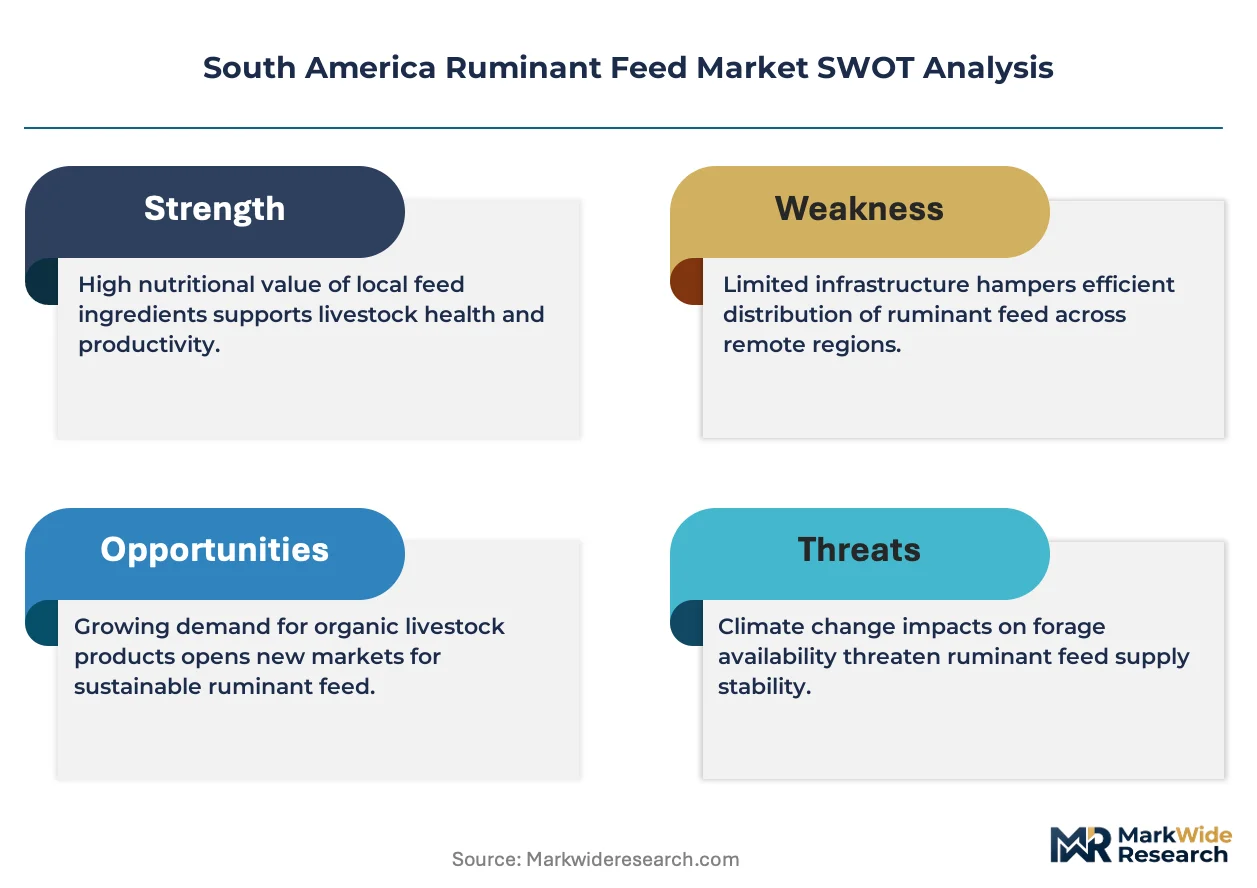
Pasture-to-feedlot transitions across Brazil's Central-West cattle belt concentrate demand for complete feed formulations, while MAPA's stricter mycotoxin enforcement redirects procurement toward certified premix suppliers with laboratory-verified quality systems.
Growth Catalysts
- MAPA Mycotoxin Enforcement:Brazil's tighter maximum limits for aflatoxin and fumonisin in ruminant feed compel mills to source certified premixes, expanding the addressable market for quality-assured suppliers.
- Pasture-to-Feedlot Conversion:Central-West Brazilian ranchers finishing Nelore and crossbred cattle in confined systems generate sustained demand for energy-dense complete feeds with optimized metabolizable protein ratios.
- Dairy Cooperative Consolidation:Bulk procurement by Argentine and Brazilian dairy cooperatives drives volume commitments for customized mineral formulations, reducing per-unit formulation costs for large-scale operators.
Market Restraints
- Input Cost Volatility:Corn and soybean meal price swings in Mato Grosso and Rio Grande do Sul squeeze feed mill margins, forcing formula adjustments that disrupt customer pricing agreements.
- Regulatory Friction:Divergent ANVISA and SENASA approval pathways for beta-agonist and ionophore additives complicate cross-border formulation portability between Brazilian and Argentine operations.
- Supply Concentration Risk:Crushing-integrated multinationals controlling Mato Grosso soy processing capacity limit independent feed blenders' access to competitively priced soybean meal.
Strategic Opportunities
- Precision Nutrition Services:Ranchers in Argentina's Pampas seek veterinarian-prescribed mineral programs, creating white space for technical service teams delivering customized supplementation protocols.
- Mercosur Harmonization Tailwind:Pending alignment of feed safety standards between Brazil and Argentina would enable single-formulation products across the customs union, reducing compliance duplication.
- Sugarcane Pulp Integration:Co-product valorization from São Paulo ethanol mills offers fiber-rich, cost-competitive substrate alternatives for semi-confined dairy and beef operations.
Industry Challenges
- Nutritionist Talent Scarcity:Qualified feed formulation specialists capable of balancing metabolizable energy and crude protein specifications remain concentrated in São Paulo and Buenos Aires, limiting regional mill technical capabilities.
- Certification Timeline Compression:ANVISA's extended review periods for novel additive registrations delay product commercialization, forcing suppliers to maintain legacy portfolios longer than planned.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Ruminant Feed Market |
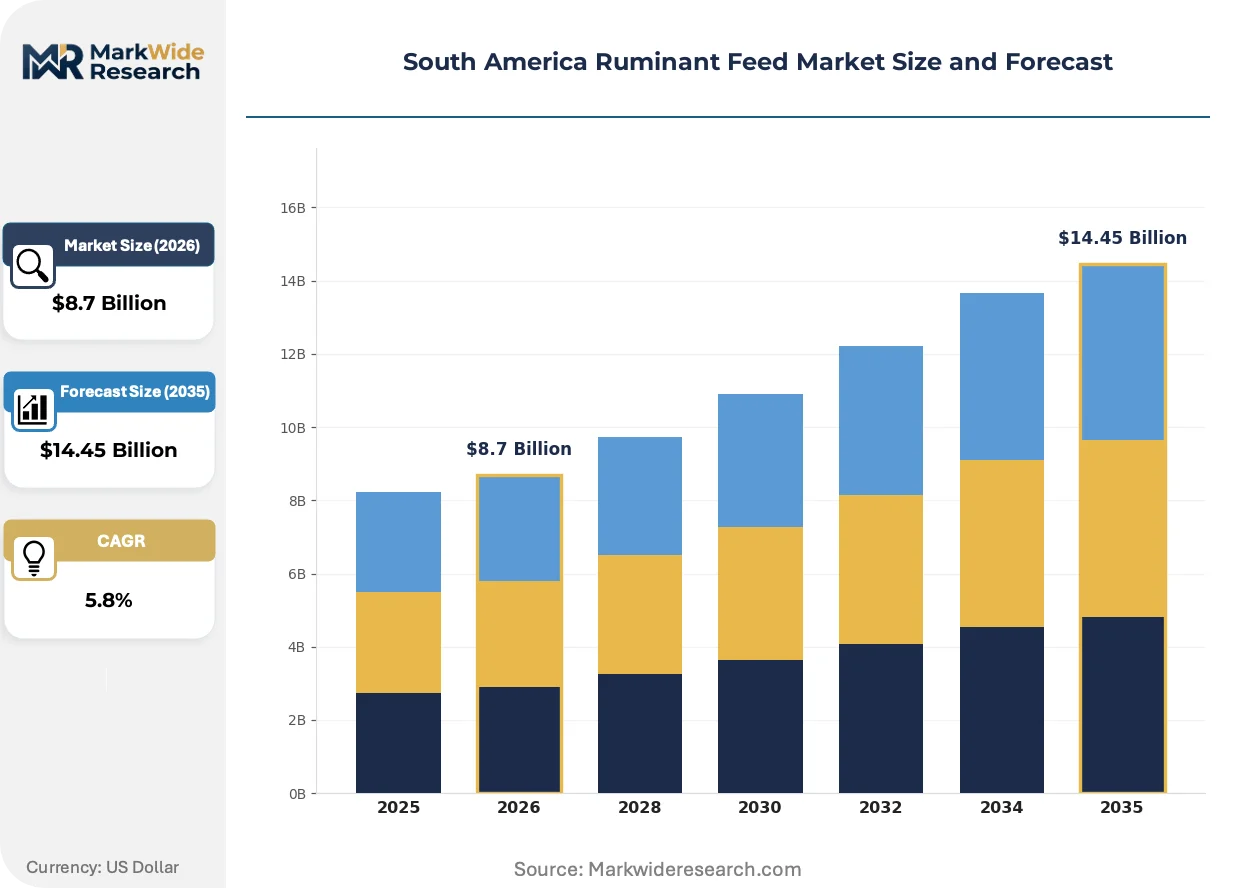
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Supplementary Feed, Additives, Premixes Ingredient Type: Corn, Soybean Meal, Wheat, Sugarcane Pulp Animal Type: Cattle, Sheep, Goats, Bison Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Cargill, Incorporated, ADM, Kemin Industries, Alltech, DSM-Firmenich, BASF SE, CCPA GROUP, Nutreco NV, JBS S.A, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Ruminant Feed Market Evolving Landscape
Digital feed formulation platforms and remote nutritional consulting are compressing the traditional veterinarian-nutritionist-rancher advisory chain, while regulatory tightening on veterinary drug residues reshapes additive portfolios.
NIR-based real-time ingredient analysis is virtualizing laboratory-dependent quality control workflows. Large Brazilian feedlots deploying portable spectrometers at receiving bays verify corn and soybean meal moisture and protein content within minutes rather than hours. This technology is virtualizing the centralized lab model, enabling decentralized decision-making at procurement points and reducing formulation adjustment delays.
ANVISA's residue monitoring protocols for meat exports now mandate extended withdrawal period documentation on all beta-agonist and ionophore labels. Brazilian premix suppliers reformulate additive packages to exclude restricted compounds from export-bound cattle programs. Feedlots supplying EU and Middle Eastern markets maintain separate additive inventories, complicating inventory management but preserving market access.
Aftermarket nutritional consulting revenue migrates from product sales toward subscription-based formulation services. Argentine dairy cooperatives engage technical teams on retainer for seasonal ration adjustments rather than per-ton premix purchases. This shift concentrates advisory relationships with suppliers possessing in-house metabolizable energy modeling capabilities, disadvantaging commodity traders lacking technical service infrastructure.
South America Ruminant Feed Market Segmentation
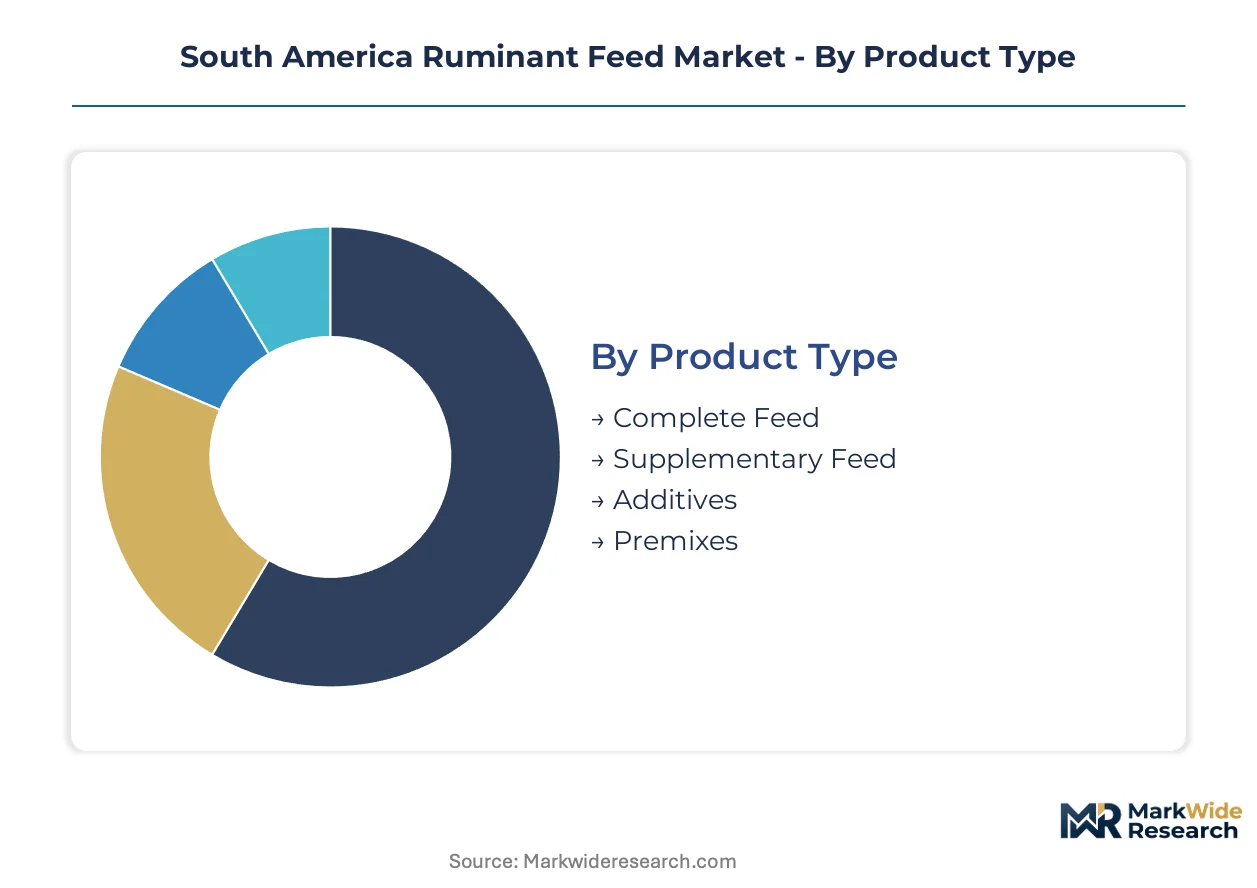
South America ruminant feed segmentation reflects divergent technical service intensities across product tiers. Formulation complexity and regulatory compliance burdens concentrate margin capture in segments requiring ongoing nutritional consulting rather than commodity trading.
Product Type:
After-sales service intensity peaks in premix and additive categories where veterinarians and nutritionists prescribe mineral protocols and monitor withdrawal periods for export-bound cattle.
- Complete Feed:Energy-dense formulations combining corn, soybean meal, and roughage sources to meet metabolizable energy specifications for confined Nelore and dairy operations. Brazilian Central-West feedlots scaling pasture-to-feedlot transitions drive procurement concentration here, though margin compression from input cost volatility limits supplier profitability.
- Premixes:Concentrated mineral and vitamin blends requiring laboratory-verified quality systems to meet MAPA mycotoxin enforcement standards. Argentina's Pampas dairy cooperatives and Brazilian beef operations generate sustained demand for customized formulations with technical service retainers.
- Supplementary Feed:Protein and mineral supplements designed for semi-confined grazing systems.
- Additives:Beta-agonist and ionophore compounds subject to ANVISA residue monitoring protocols.
By volume, Complete Feed leads. By growth pace, Premixes is ahead.
Ingredient Type:
Cost tier differentiation separates commodity grains from regional co-products with valorization potential.
- Corn:Primary energy substrate sourced from Mato Grosso and Rio Grande do Sul production belts, with moisture and protein content verified through NIR-based receiving bay analysis. Brazilian feedlot operators in Goiás and Mato Grosso do Sul concentrate procurement here, though price swings force formula adjustments that disrupt customer agreements.
- Soybean Meal:Standardized protein ingredient crushing-integrated multinationals control through Mato Grosso processing capacity. Independent blenders face supply concentration risk as ADM and Cargill leverage captive soy economics.
- Wheat:Secondary energy source in southern Brazilian and Argentine formulations.
- Sugarcane Pulp:Fiber-rich co-product from São Paulo ethanol mills offering cost-competitive roughage alternatives.
By procurement scale, Corn dominates. By margin expansion potential, Sugarcane Pulp is climbing the fastest.
Animal Type:
Application-specific formulation requirements vary sharply across species metabolism and production endpoints.
- Cattle:Beef and dairy segments requiring distinct metabolizable protein ratios, with Nelore genetics in Brazil and Holstein crosses in Argentina driving divergent energy density specifications. Central-West Brazilian feedlots and Argentine dairy cooperatives concentrate demand here, supported by precision nutrition consulting services.
- Sheep:Smaller-volume segment concentrated in Patagonian Argentina and southern Brazilian states.
- Goats:Niche dairy and meat production systems with localized formulation requirements.
- Bison:Emerging commercial segment with limited regional scale.
By revenue concentration, Cattle leads. By technical service penetration, Sheep is gaining share fastest.
Distribution Channel:
Customer type and procurement scale dictate channel selection across cooperative bulk purchasing and independent rancher transactions.
- Direct Sales:Volume contracts between premix suppliers and consolidated dairy cooperatives or large feedlot operators, embedding technical service teams for seasonal ration adjustments. Argentine dairy cooperatives in Santa Fe and Córdoba drive this channel's expansion through retainer-based advisory relationships.
- Distributors:Regional blenders and independent mills accessing certified premixes through authorized networks.
- Retail:Local agricultural supply stores serving smaller rancher operations.
- Online:Emerging platform for standardized product procurement with limited technical service attachment.
By transaction value, Direct Sales leads. By channel expansion, Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crushing-integrated multinationals concentrate soybean meal supply in Mato Grosso, while pasture-to-feedlot transitions concentrate demand in Brazil's Central-West cattle belt. Argentine dairy cooperatives in the Pampas and Chilean salmon byproduct valorization create secondary feed formulation clusters. Regulatory divergence between ANVISA and SENASA complicates cross-border procurement planning.
Brazil
Central-West feedlots in Mato Grosso do Sul and Goiás drive complete feed procurement as Nelore finishing intensifies. MAPA enforces stricter aflatoxin and fumonisin maximum limits, redirecting mills toward certified premix suppliers. São Paulo's ethanol mills supply sugarcane pulp fiber to semi-confined dairy operations, creating co-product valorization networks.
Argentina
Pampas dairy cooperatives in Santa Fe and Córdoba consolidate bulk procurement of customized mineral formulations. SENASA maintains feed mill registration requirements and mycotoxin standards that elevate compliance costs for regional blenders. Buenos Aires anchors nutritionist talent concentration, limiting technical service deployment to peripheral provinces.
Chile
Salmon processing byproduct meal enters ruminant feed formulations as a protein alternative in southern livestock regions. The country's agricultural regulator enforces residue monitoring protocols aligned with EU export requirements. Metropolitan Santiago houses formulation laboratories serving both domestic cattle operations and cross-border technical consulting.
Uruguay
Grass-fed beef export certification programs limit compound feed penetration, though supplementary mineral blocks gain traction in drought periods. Mercosur harmonization talks on feed safety standards would reduce compliance duplication for Brazilian suppliers operating here. Montevideo's port infrastructure handles premix imports for the domestic dairy sector.
Colombia
Andean dairy clusters in Antioquia and Cundinamarca import premix formulations from Ecuador and Peru due to limited domestic crushing capacity. The national agricultural institute maintains veterinary drug residue protocols for beef export markets. Bogotá-based distributors coordinate cross-border supply chains for Andean ranching operations.
South America Ruminant Feed Market Competitive Landscape
Agribusiness conglomerates and specialty nutrition houses split the market between crushing-integrated volume plays and technical service-driven premix positioning. The structure concentrates in two tiers: multinational traders controlling soybean meal supply economics, and premix specialists capturing margin through formulation consulting. Three archetypes dominate—crushing-integrated feed manufacturers, mineral premix technical service providers, and cooperative-aligned regional blenders. Competitive moves center on laboratory network expansion for real-time quality verification and retainer-based nutritional consulting contracts with large dairy cooperatives.
Within the crushing-integrated tier, Cargill, Incorporated and ADM exemplify supply chain control through Mato Grosso soy processing capacity. Nutreco NV anchors the technical service archetype through Trouw Nutrition's deployment across Argentine Pampas operations. These three occupy positions spanning commodity supply and precision nutrition advisory, representing the strategic spectrum from volume-driven crushing economics to veterinarian-prescribed mineral protocol customization.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| ADM |
| Kemin Industries |
| Alltech |
| DSM-Firmenich |
| BASF SE |
| CCPA GROUP |
| Nutreco NV |
| JBS S.A |
| Others |
Value Network & Pricing Analysis
Mato Grosso crushing-integrated multinationals controlling soybean meal supply anchor feed economics downstream, compressing independent blender margins while concentrating value capture in premix and technical service tiers where laboratory-verified quality commands premium positioning.
Pricing Analysis
Aftermarket nutritional consulting revenue drives lifetime value through retainer-based formulation services rather than per-ton product sales. Three-tier pricing structure across certified-premium, standard-compliant, and economy-generic levels separates MAPA-verified premix suppliers from commodity traders. Cost compression in complete feed formulations is intensifying because corn and soybean meal price volatility in Central-West Brazil disrupts customer pricing agreements. Argentine dairy cooperatives show least price sensitivity due to bulk procurement scale, while independent ranchers in peripheral Brazilian states face acute margin pressure.
Supply Chain Analysis
Upstream corn and soybean meal feedstock concentrates in Brazil's Mato Grosso and Rio Grande do Sul production belts, with crushing-integrated multinationals ADM and Cargill anchoring soy processing capacity. The supply chain draws from regional sugarcane pulp co-products in São Paulo and Patagonian wheat in southern Argentina. Single-source vulnerability in soybean meal access limits independent blender procurement flexibility. Distribution runs through direct sales contracts with consolidated dairy cooperatives and authorized distributor networks serving regional mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as pasture-to-feedlot transitions across Brazil's Central-West cattle belt accelerate demand for precision nutrition services and certified premix formulations.
For Market Incumbents: Insulate crushing-integrated economics by securing captive soy processing capacity in Mato Grosso while building laboratory networks for real-time mycotoxin verification that independent blenders cannot replicate. Defend against technical service specialists by embedding nutritionist teams within Argentine dairy cooperatives on multi-year retainers. For New Entrants and Emerging Players: Build out precision nutrition consulting capabilities targeting sheep and goat segments in Patagonian Argentina where technical service penetration remains shallow relative to cattle operations. Capture white space in online distribution of standardized mineral blocks for drought-period supplementary feeding. Lead with NIR-based ingredient verification as a differentiated procurement service. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed premix specialists possessing Trouw Nutrition-style technical service infrastructure deployable across Mercosur harmonization scenarios. Long-term viability centers on formulation IP and veterinarian advisory relationships rather than commodity trading scale. Watch for ANVISA-SENASA regulatory alignment talks as inflection signal for cross-border formulation portability plays.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Network Expansion | MAPA mycotoxin enforcement elevates demand for certified quality verification at receiving bays. |
| Retainer-Based Consulting Contracts | Argentine dairy cooperatives shift procurement from product sales to seasonal ration advisory services. |
| Sugarcane Pulp Integration Partnerships | São Paulo ethanol mill co-product valorization offers fiber-rich cost alternatives for semi-confined operations. |
| Mercosur Harmonization Positioning | Single-formulation products across Brazil-Argentina border reduce compliance duplication for premix suppliers. |
| NIR Spectrometer Deployment | Portable receiving bay analysis virtualizes centralized lab models for decentralized procurement decisions. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with feed mill procurement managers, veterinarian nutritionists, dairy cooperative technical directors, and MAPA compliance officers; and secondary validation through ANVISA additive registration databases, SENASA feed mill certification records, Brazilian customs trade statistics, and South American agricultural ministry production reports. Bottom-up volume estimates from state-level feed production data triangulated against top-down value projections from crushing-integrated multinational disclosures.
Forecast inputs span product type segmentation across complete feed, premix, and additive categories; ingredient type tiers from commodity grains to regional co-products; and animal type applications distinguishing cattle, sheep, goat, and bison metabolism requirements. CAGRs were derived from elasticity modeling against pasture-to-feedlot conversion rates and dairy cooperative consolidation trajectories. Industry-specific inputs include MAPA mycotoxin limit enforcement timelines and ANVISA novel additive review period assumptions.
Stress conditions across corn-soybean meal price volatility bands, Mercosur regulatory harmonization scenarios, and nutritionist talent availability constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about pasture conversion acceleration and cooperative procurement consolidation. Cross-checking against Brazilian Feed Industry Association production statistics and Argentine Rural Society dairy sector surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Poultry Feed Market
Livestock Management
Hominy Feed Market
Livestock Management
United States Swine Feed Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
Herd Management Software Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Swine Feed Market
Livestock Management
Global Smart Ear Tags Market
Livestock Management
North America Swine Feed Market
Livestock Management
Animal Identification Market
Livestock Management
Bird Feeder Market
Livestock Management
Hog Production and Pork Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Digital Livestock Farming Market