
 Italy Automotive Airfilters Market | 2026-2036
Italy Automotive Airfilters Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Airfilters Market Foresight
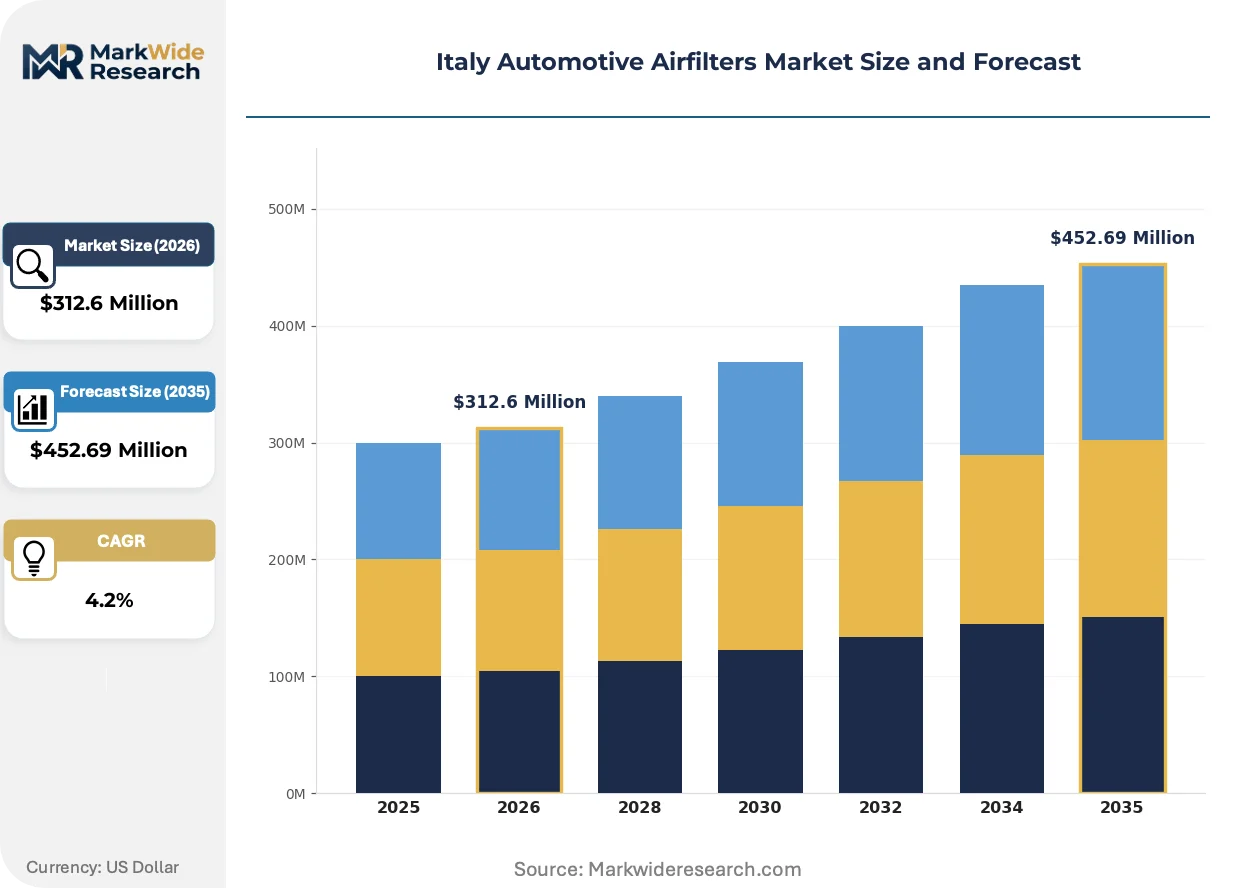
Capital-intensity divergence between automated pleating lines and manual assembly operations is collapsing as mid-tier suppliers retool. Mann+Hummel leverages its captive nonwoven media production to defend margin pools in cabin filter supply. Sogefi S.p.A. anchors its position through direct OEM relationships with Stellantis and domestic vehicle assemblers. Robert Bosch GmbH competes via integrated sensor-enabled filter systems that extend replacement interval visibility to fleet operators.
Automotive airfilters for the Italian market comprise pleated fibrous media—paper, synthetic, or composite substrates—engineered to capture particulate matter down to micron-scale thresholds while maintaining calibrated airflow resistance for combustion efficiency or cabin air quality. Cabin filters incorporating activated carbon layers adsorb VOCs and NOx from urban traffic environments, a functional priority given Italy's dense metropolitan vehicle concentrations. Engine air filters using synthetic media are gaining share from traditional cellulose as thermal durability requirements intensify under turbocharged downsized engines. The aftermarket channel dominates volume throughput, though OEM specifications increasingly dictate material grade and pleat geometry standards that shape supplier qualification barriers.
Italy's Ministry of Infrastructure and Transport enforces EU-wide type-approval frameworks while ANFIA coordinates domestic automotive supplier compliance with evolving emission protocols. Euro 7 standards from Brussels will mandate finer particulate filtration across both intake and cabin circuits, forcing media upgrades and testing protocol investments. Stakeholders must monitor how Turin-based OEM sourcing committees reconcile cost targets with incoming filtration performance floors.
Market Dynamics
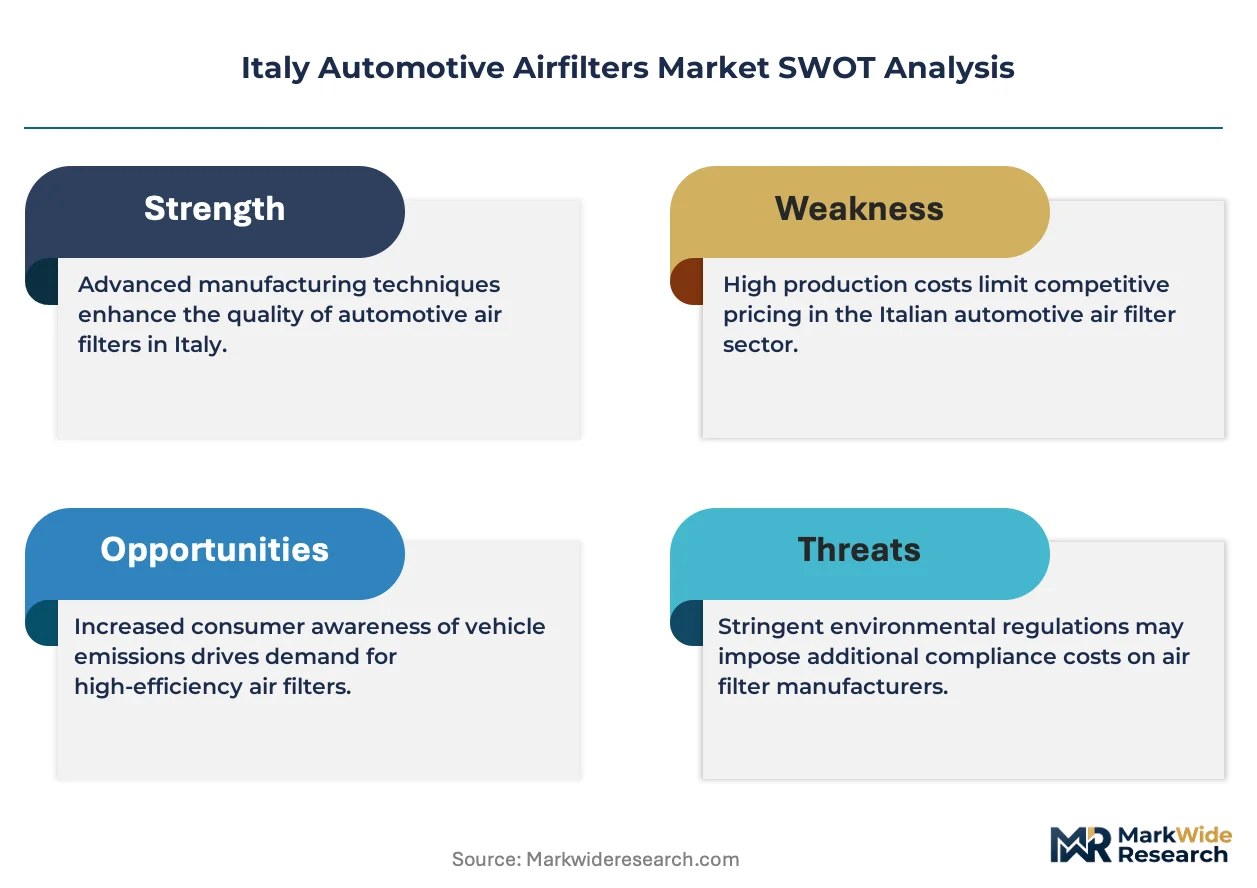
Euro 7 emission standards are compressing pleat geometry tolerances and forcing media substrate upgrades across Italian supplier operations, restructuring competitive qualification barriers before the 2026 implementation window.
Growth Catalysts
- Turin-Milan corridor fleet density:Vehicle concentration in this industrial corridor sustains elevated filter replacement velocity. Commercial fleets and aging passenger stock drive aftermarket throughput.
- Synthetic media thermal durability:Turbocharged downsized engines require filtration substrates that withstand higher operating temperatures. Engine air filter specifications are migrating from cellulose toward engineered synthetics.
- Euro 7 particulate thresholds:Brussels-mandated finer filtration standards across intake and cabin circuits force media upgrade investments. Testing protocol expansions create compliance-driven equipment refresh cycles.
Market Restraints
- Nonwoven media input cost volatility:Polypropylene and polyester fiber prices fluctuate with petrochemical feedstock markets. Captive production capabilities at large suppliers widen margin pressure on non-integrated competitors.
- Emilia-Romagna supplier concentration:Filter housing and pleating equipment manufacturing clusters in this region create geographic supply risk. Disruption at specialized tooling providers propagates through domestic production networks.
- Cellulose substrate technical ceiling:Traditional paper media cannot achieve Euro 7 filtration efficiency without unacceptable airflow restriction. R&D timelines to bridge this performance gap strain mid-tier engineering resources.
Strategic Opportunities
- Southern Italy aftermarket underpenetration:Campania and Sicily maintain lower service chain density than northern regions. Mobile service units and regional distribution hubs can capture latent replacement demand.
- Sensor-enabled filter monitoring:Integration of pressure differential sensors with telematics platforms enables predictive replacement scheduling. Fleet operators gain visibility into actual filter condition versus calendar-based intervals.
- Activated carbon cabin filter expansion:Urban traffic density in Rome, Naples, and Milan elevates VOC and NOx exposure concerns. Premium cabin filter specifications with adsorption layers command pricing differentiation.
Industry Challenges
- Automated pleating technician scarcity:Operation of servo-controlled pleating lines requires mechatronics competencies scarce in traditional filter manufacturing labor pools. Training pipelines lag equipment deployment schedules.
- Euro 7 certification timeline compression:ANFIA-coordinated type-approval processes must validate new media formulations before regulatory deadlines. Testing queue congestion risks market access delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Airfilters Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $452.69 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabin Filters, Engine Air Filters, Fuel Filters, Oil Filters Technology: HEPA, Electrostatic, Activated Carbon, Foam End User: OEMs, Aftermarket, Vehicle Assemblers, Retailers Material: Paper, Synthetic, Textile, Composite |
| Companies Covered | Mann+Hummel, Purolator Filters LLC, K&N Engineering, A.L. Group, Hengst SE, MAHLE GmbH, Donaldson Company, Sogefi S.p.A., Robert Bosch GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Airfilters Market Shifts & Advancements
Filter media engineering is converging with sensor integration and predictive maintenance platforms, shifting value capture from commodity replacement parts toward condition-monitored service systems.
Electrospun nanofiber surface layers are enhancing sub-micron particle capture without sacrificing airflow permeability. Italian OEM sourcing committees are specifying this technology for premium engine air intake applications. The manufacturing footprint for nanofiber deposition is miniaturizing, enabling distributed production nodes closer to assembly plants.
ANFIA-coordinated domestic compliance with Euro 7 protocols is mandating expanded laboratory testing capacity for filtration efficiency validation. Equipment suppliers in the Emilia-Romagna tooling cluster are backlogged with orders for automated test stands. Small and mid-tier filter producers face capital allocation decisions between testing infrastructure and media production expansion.
Fleet operators are unbundling filter replacement from bundled maintenance contracts, seeking direct procurement relationships with filter suppliers. Large commercial vehicle lessors in the Turin-Milan corridor are piloting usage-based billing models tied to actual particulate loading rather than fixed intervals. This procurement evolution is most visible in long-haul logistics segments where telematics penetration enables accurate duty-cycle tracking.
Italy Automotive Airfilters Market Segmentation
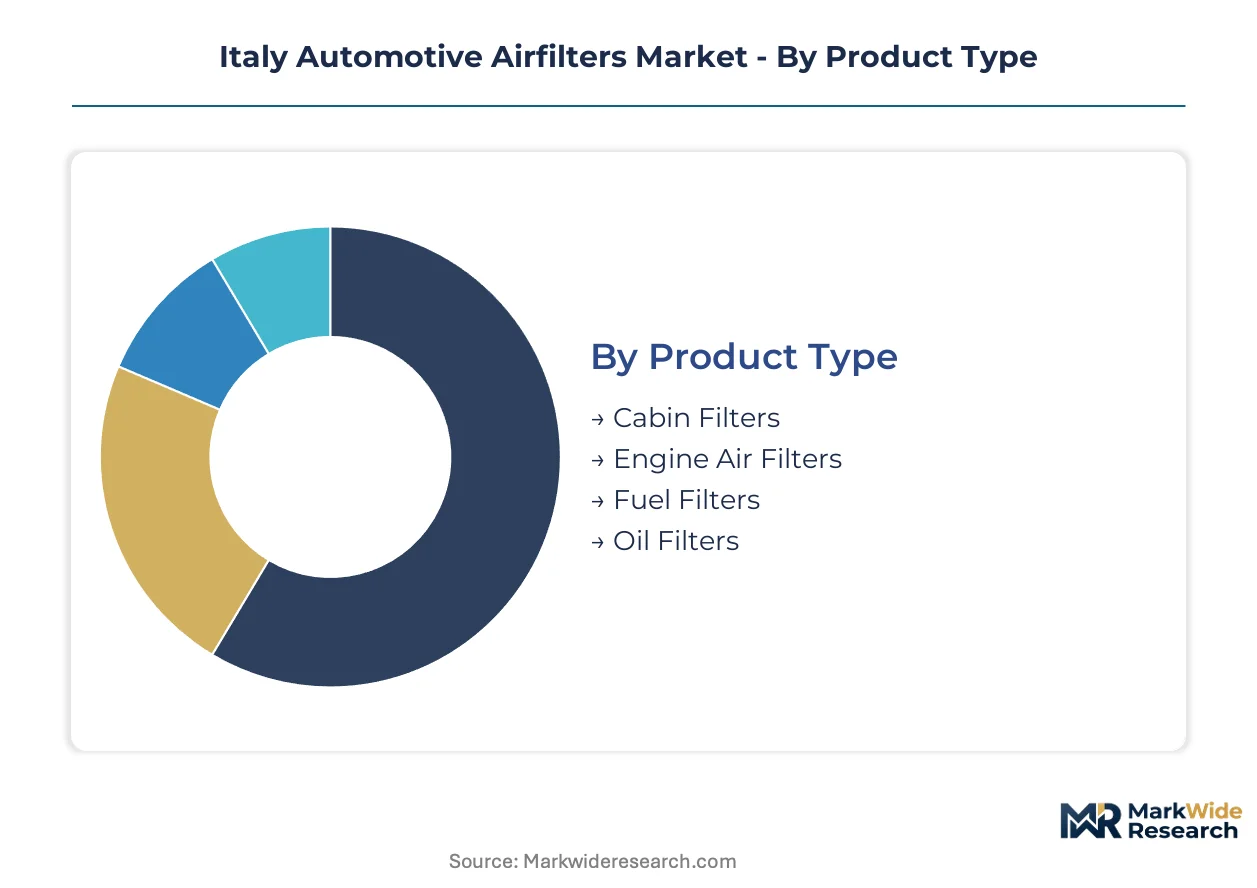
Segmentation in the Italian automotive airfilters market reveals how Euro 7 compliance investments and thermal durability requirements are redistributing value capture across product architectures and material grades. Supplier positioning depends on matching the right technology-material combination to specific end-user procurement patterns.
Product Type:
Margin pools concentrate in cabin filter supply where activated carbon specifications command pricing premiums, while engine air filters face commoditization pressure from synthetic media standardization.
- Cabin Filters:Multi-layer constructions combining particulate filtration with activated carbon adsorption layers address VOC and NOx exposure in Rome, Naples, and Milan traffic corridors. Premium specifications with electrostatic enhancement are displacing standard cellulose configurations in fleet renewal programs across the Turin-Milan industrial corridor.
- Engine Air Filters:Pleated synthetic media withstands elevated intake temperatures from turbocharged downsized engines common in Stellantis powertrain configurations. ANFIA-coordinated type-approval processes are compressing qualification timelines for new media formulations ahead of regulatory deadlines.
- Fuel Filters:Water separation and particulate capture functions protect common-rail injection systems from biodiesel contamination prevalent in Italian commercial fleets.
- Oil Filters:Spin-on and cartridge configurations serve divergent service interval strategies between passenger vehicles and heavy-duty logistics operators.
Cabin filters hold installed capacity. Engine air filters is rotating up the share rankings.
Technology:
Technology selection tracks the divergence between compliance-driven efficiency floors and comfort-driven air quality specifications in dense metropolitan environments.
- HEPA:Sub-micron particle capture efficiency meets Euro 7 cabin air quality mandates without excessive pressure drop. Turin-based OEM sourcing committees are specifying HEPA-grade specifications for premium vehicle segments.
- Activated Carbon:Adsorption layers target NOx and VOC loads from urban traffic congestion. Demand concentrates in aftermarket upgrade cycles across northern Italian metropolitan zones.
- Electrostatic:Charge-enhanced fiber matrices boost particle capture with reduced media density. This technology is expanding most quickly in engine intake applications where packaging constraints limit pleat count.
- Foam:Reticulated polyurethane structures serve coarse pre-filtration and specialty off-road equipment where washability extends service intervals.
Activated carbon dominates value capture. Electrostatic is climbing the fastest.
End User:
Procurement concentration shapes competitive access, with aftermarket service chains consolidating purchasing power while OEM specifications dictate material qualification barriers.
- OEMs:Direct supply relationships with Stellantis and domestic vehicle assemblers require validated media formulations and pleat geometry tolerances. Mann+Hummel and Sogefi S.p.A. anchor their positions through these captive channels.
- Aftermarket:Service chain expansion across northern Italy sustains replacement velocity for aging fleet stock. Mobile service units are penetrating Campania and Sicily where chain density lags.
- Vehicle Assemblers:Contract manufacturing arrangements for niche and specialty vehicle producers demand flexible production lot sizes.
- Retailers:Independent parts distributors serve the long tail of owner-operated maintenance in southern regions.
OEMs hold specification control. Aftermarket is gaining share fastest.
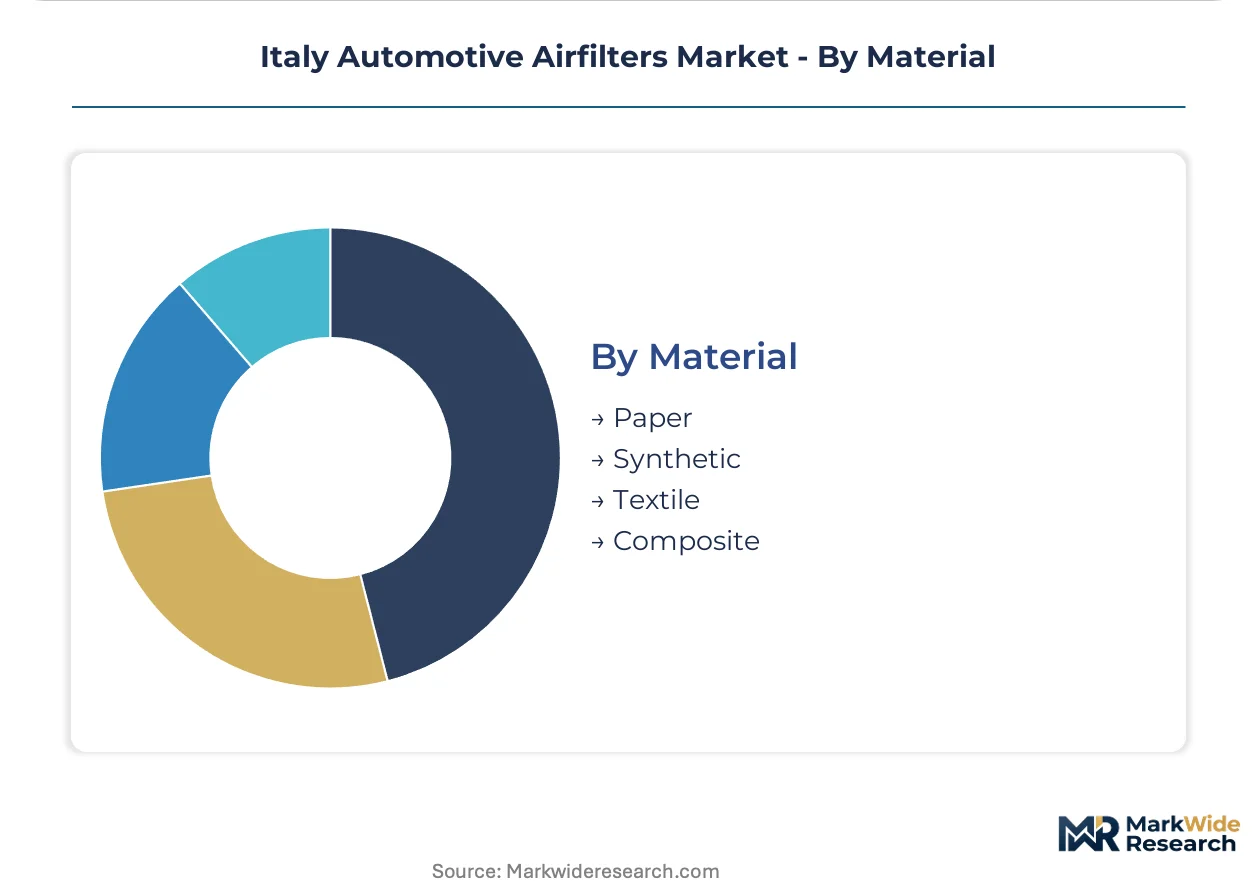
Material:
Substrate selection determines thermal performance ceilings and compliance pathway costs as cellulose technical limits force migration toward engineered alternatives.
- Synthetic:Polypropylene and polyester nonwoven matrices withstand elevated operating temperatures and enable electrostatic charging. Captive production at integrated suppliers widens margin pressure on non-integrated competitors.
- Paper:Traditional cellulose substrates face technical ceilings for Euro 7 efficiency requirements without unacceptable airflow restriction. Demand is concentrating in cost-sensitive aftermarket segments.
- Textile:Woven and nonwoven fabric structures serve specialty applications requiring washability or chemical resistance.
- Composite:Multi-substrate laminates combine particulate capture layers with adsorption media in unified pleat geometries.
Synthetics hold capacity expansion. Composite is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aftermarket buyers in southern Italy exhibit acute price sensitivity, while fleet operators in the industrial north prioritize performance specifications and sensor-enabled monitoring capabilities over unit cost.
Lombardy
Milan's dense commercial fleet concentration sustains elevated replacement velocity for cabin and engine air filters. The Ministry of Infrastructure and Transport enforces EU type-approval frameworks that filter suppliers must satisfy for aftermarket distribution rights. Bergamo-based tooling manufacturers supply automated pleating equipment to domestic producers upgrading for Euro 7 compliance timelines.
Piedmont
Turin anchors OEM sourcing committees for Stellantis and domestic vehicle assemblers demanding validated media formulations. ANFIA coordinates supplier compliance with evolving emission protocols including incoming Euro 7 particulate thresholds. The metropolitan manufacturing belt concentrates filter housing production and testing laboratory capacity for northern Italian supply networks.
Emilia-Romagna
Modena and Bologna host specialized pleating equipment manufacturers currently backlogged with orders for automated test stands. Regional suppliers face capital allocation pressures between testing infrastructure investments and media production expansion. The tooling cluster's output propagates through domestic filter production networks, creating geographic concentration risk.
Lazio
Rome's urban traffic density elevates VOC and NOx exposure concerns, driving aftermarket upgrade cycles toward activated carbon cabin specifications. The metropolitan aftermarket channel serves owner-operated maintenance demand with lower service chain density than northern counterparts. Mobile service units are penetrating this underpenetrated region to capture latent replacement velocity.
Campania
Naples maintains lower aftermarket service chain density than northern industrial corridors, constraining filter replacement throughput despite comparable vehicle stock age. Regional distribution infrastructure gaps limit supplier access to price-sensitive independent repair channels. Emerging mobile service platforms are testing direct-to-fleet procurement models in this southern market.
Italy Automotive Airfilters Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Italy's automotive airfilter supply base. Mann+Hummel and Robert Bosch GmbH anchor the upper tier through captive media production and sensor integration capabilities respectively. Mid-tier specialists compete on OEM qualification speed and aftermarket distribution reach. Dominant competitive moves include backward integration into nonwoven media production and strategic partnerships with telematics platforms for predictive replacement scheduling.
Among Germany-based diversified suppliers, Mann+Hummel and Robert Bosch GmbH exemplify the integrated archetype through upstream control over filtration media and sensor-enabled systems respectively. Sogefi S.p.A. represents the domestic specialist tier, occupying a position anchored by direct OEM relationships with Stellantis. These three entities collectively illustrate how competitive positioning in this market depends on matching material qualification capabilities with specific channel access patterns.
| Leading Market Players |
|---|
| Mann+Hummel |
| Purolator Filters LLC |
| K&N Engineering |
| A.L. Group |
| Hengst SE |
| MAHLE GmbH |
| Donaldson Company |
| Sogefi S.p.A. |
| Robert Bosch GmbH |
| Others |
Supply & Pricing Matrix
Capacity utilization at automated pleating lines in Emilia-Romagna shapes margin structures across Italian filter supply, concentrating pricing power among integrated producers while compressing floors for non-captive competitors. This scale dynamic feeds directly into procurement negotiations with Turin-based OEM sourcing committees and aftermarket service chains.
Pricing Analysis
Aftermarket service revenue drives lifetime value capture, with filter replacement cycles generating recurring throughput that exceeds initial equipment margins. Three-tier pricing structure across premium, standard, and economy levels separates activated carbon cabin specifications from basic cellulose configurations. Cost compression in synthetic media tiers is intensifying because Mann+Hummel's captive polypropylene production widens cost advantages. Fleet operators in the Turin-Milan corridor show lowest price sensitivity, prioritizing sensor-enabled monitoring over unit cost.
Supply Chain Analysis
Inventory lead times for specialized pleating equipment from Bergamo and Modena manufacturers currently extend twelve to sixteen weeks, constraining capacity expansion timelines for Euro 7 compliance upgrades. Raw material supply draws from Germany, China, and domestic Emilia-Romagna tooling clusters for nonwoven media inputs. Polypropylene fiber and polyester substrate dependencies rest on petrochemical feedstock markets. Single-source vulnerability concentrates at specialized servo-controlled pleating equipment providers. Distribution runs through ANFIA-coordinated OEM qualification channels and independent aftermarket service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's automotive airfilter sector represents an early-cycle expansion story, with Euro 7 regulatory mandates forcing media upgrade investments that penetrate supplier operations ahead of implementation deadlines.
For Market Incumbents: Consolidate backward integration into nonwoven media production to defend margin pools against petrochemical input volatility. Acquire specialized pleating equipment manufacturers in Emilia-Romagna to secure capacity access for compliance-driven production ramps. Synthetic media thermal durability requirements and captive supply advantages at Mann+Hummel constitute the primary competitive threat. For New Entrants and Emerging Players: ANFIA-coordinated Euro 7 certification fast-tracks offer qualification pathway acceleration for validated media formulations. Southern Italy aftermarket underpenetration in Campania and Sicily presents the most accessible white-space target, with mobile service units enabling direct fleet procurement relationships without established chain density. Partner with telematics platforms for predictive replacement scheduling to differentiate from calendar-based competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-enabled filter monitoring providers with fleet operator relationships. Long-term viability across a five-to-ten-year window favors suppliers with dual OEM-aftermarket channel access and captive media production. Acquisition targets should demonstrate ANFIA qualification track records and Emilia-Romagna equipment relationships. Monitor Euro 7 testing queue congestion as inflection indicator for market access delays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nonwoven Media | Mann+Hummel's captive polypropylene production widens cost advantages over non-integrated competitors. |
| Sensor-Enabled Filter Monitoring | Robert Bosch GmbH's integrated pressure differential systems extend replacement interval visibility to fleet operators. |
| Euro 7 Certification Investment | ANFIA-coordinated type-approval processes compress qualification timelines for new media formulations. |
| Southern Italy Distribution Expansion | Mobile service units penetrate Campania and Sicily where aftermarket chain density lags northern corridors. |
| Automated Pleating Equipment Acquisition | Emilia-Romagna tooling manufacturers face backlogs, creating captive capacity advantages for acquirers. |
Research Methodology
The analysis maps cabin filter, engine air filter, fuel filter, and oil filter sub-sectors, each validated through procurement directors at aftermarket service chains, OEM platform engineers at Stellantis, and ANFIA regulatory affairs leads. Primary interviews with Tier 1 supplier sourcing teams and aftermarket distributors combined with secondary validation from EU type-approval filings, vehicle production databases, and customs records. Bottom-up segmentation sizing and top-down market triangulation cross-checked projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, technology grade, material substrate, and end-user procurement channel dimensions throughout the forecast period. CAGRs derived from segment-level growth trajectory analysis incorporating Euro 7 compliance investment cycles and synthetic media thermal durability adoption curves.
Decision-makers should treat outputs as directional under base assumptions of Euro 7 implementation timelines and petrochemical feedstock stability; material deviation would warrant model refresh. Forecasts reflect assumptions about regulatory enforcement intensity and fleet renewal velocity. Supply disruption at Emilia-Romagna tooling clusters or testing queue congestion could revise projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Global Automotive Nitrous Oxide System Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Odometer Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market