
 India Automotive Coolant Market | 2026-2036
India Automotive Coolant Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Coolant Market Foresight
Bharat Stage VI emission norms is recalibrating coolant formulation requirements across India's automotive value chain. Indian Oil Corp. Ltd leverages its nationwide fuel-station network to push packaged coolant into tier-two and tier-three cities. Castrol Limited anchors premium positioning through OEM tie-ups with domestic passenger-vehicle manufacturers. Gulf Oil International competes aggressively on commercial-vehicle fleet contracts, sustaining volume throughput in logistics corridors.
India automotive coolant comprises a heat-transfer fluid—typically ethylene glycol or propylene glycol blended with corrosion inhibitors, antifoam agents, and pH buffers—engineered to maintain engine thermal equilibrium between minus 37 degrees Celsius and 129 degrees Celsius while preventing cavitation erosion in aluminum cylinder heads. Ethylene glycol formulations still dominate installed-base refills across the aftermarket, though organic acid technology is displacing conventional silicate chemistry in OEM first fills because extended service intervals reduce total cost of ownership for fleet buyers. Passenger vehicles generate the largest absolute volume, yet commercial vehicles yield higher per-unit consumption and more predictable workshop-driven replenishment cycles.
BIS certification mandates and the Automotive Research Association of India's test protocols shape product entry thresholds, while Central Pollution Control Board water-toxidity rules are forcing reformulation of heavy-metal-containing corrosion packages. The Ministry of Road Transport and Highways' extended warranty regulations indirectly pressure OEMs to specify longer-life chemistries. Stakeholders must monitor how state-level scrapage policies in Delhi-NCR and Maharashtra accelerate coolant demand from replacement-vehicle production.
Market Dynamics
Bharat Stage VI emission norms are compressing coolant drain intervals while simultaneously mandating aluminum-compatible chemistries, forcing reformulation across India's entire automotive supply chain. Fleet operators now demand extended-life organic acid technology to minimize total cost of ownership amid tighter particulate-matter regulations.
Growth Catalysts
- BIS certification mandates:Mandatory Bureau of Indian Standards testing protocols are elevating product entry barriers, filtering out unorganized suppliers and consolidating market share among certified manufacturers serving OEM first-fill contracts.
- Commercial-vehicle fleet expansion:Logistics corridors across Maharashtra and Gujarat are generating predictable workshop-driven replenishment cycles, with higher per-unit consumption than passenger-vehicle segments.
- Organic acid technology:Extended service intervals of this silicate-free chemistry are reducing maintenance downtime for fleet buyers, accelerating displacement of conventional inorganic additive packages in Tamil Nadu's manufacturing belt.
Market Restraints
- Ethylene glycol price volatility:Petrochemical feedstock fluctuations compress blender margins, particularly for aftermarket refill producers lacking long-term supply contracts with integrated refiners.
- Heavy-metal reformulation costs:Central Pollution Control Board water-toxicity rules are forcing costly redevelopment of corrosion-inhibitor packages containing borates and phosphates, straining mid-tier suppliers.
- Propylene glycol substitution ceiling:Higher unit costs and inferior thermal-transfer coefficients limit bio-based alternatives to niche electric-vehicle thermal-management applications despite toxicity advantages.
Strategic Opportunities
- Electric-vehicle thermal management:Battery-electric platforms require dielectric coolants for power-electronics cooling, opening white-space demand unrelated to internal-combustion engine formulations.
- Tier-three city penetration:Indian Oil Corp.'s fuel-station network enables packaged coolant distribution into underserved Rajasthan and Madhya Pradesh markets currently reliant on loose bulk supply.
- Scrapage policy tailwinds:Delhi-NCR and Maharashtra vehicle-retirement schemes are accelerating replacement-vehicle production, boosting OEM first-fill demand for long-life chemistries.
Industry Challenges
- Automotive Research Association of India certification timelines:Extended test-protocol durations delay product launches, compressing revenue recognition windows for seasonal formulation cycles.
- Aluminum-wet sleeve cavitation expertise:Specialized tribology knowledge for heavy-duty diesel compatibility remains concentrated among legacy formulators, constraining new entrant technical credibility.
- Legacy fleet compatibility:Mixed-age commercial-vehicle parc requires inventory complexity, as pre-BSIV assets demand conventional silicated chemistries incompatible with newer organic acid formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Coolant Market |
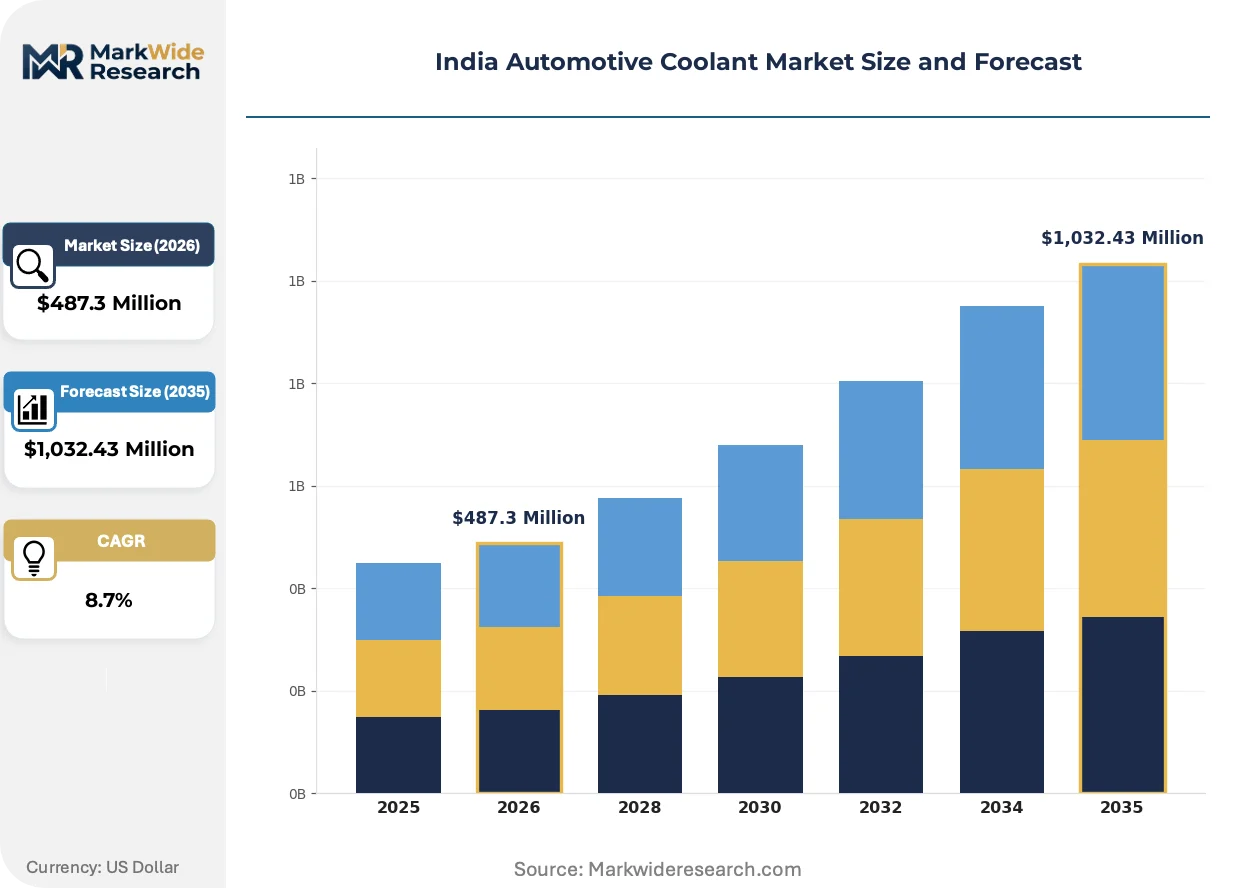
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Glycol, Propylene Glycol, Organic Acid Technology, Hybrid Use Case: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Motorcycles End User: OEMs, Aftermarket Providers, Retail Customers, Workshops Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Valvoline LLC, Bharat Petroleum Corporation Limited, Indian Oil Corp. Ltd, Shell Lubricants, Gulf Oil International, Castrol Limited, Motul, IFTEX Oil & Chemicals Ltd., ExxonMobil Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Coolant Market Shifts & Advancements
Formulation chemistry, regulatory compliance architecture, and procurement modalities are undergoing simultaneous transformation across India's automotive coolant value chain. Three distinct vectors are compressing legacy operating models while opening new competitive terrain.
Organic acid technology is rewriting thermal-fluid specifications across India's commercial-vehicle segment. This silicate-free, phosphate-free chemistry extends service intervals beyond 500,000 kilometers while eliminating gelation risks in aluminum cooling systems. Fleet operators in Gujarat's logistics corridors are adopting it aggressively to minimize workshop downtime. The technology is compressing demand for conventional inorganic additive packages and consolidating procurement around single-supplier long-life contracts.
Central Pollution Control Board water-toxicity regulations are forcing heavy-metal elimination from corrosion-inhibitor packages. Borate and phosphate limits are compelling blenders to reformulate around carboxylate and azole chemistries at 15-20% higher raw-material cost. Aftermarket refill producers serving unorganized workshops face the steepest compliance burden, while OEM-certified suppliers capture migrating volume through pre-approved first-fill positions.
Workshop procurement is consolidating around annual maintenance contracts rather than spot purchases. Fleet managers in Maharashtra are unbundling coolant supply from general lubricant procurement, negotiating direct agreements with certified blenders for predictable replenishment schedules. This behavioral shift is disintermediating traditional distributor networks in Mumbai-Pune industrial clusters, compressing margin pools for regional stockists dependent on fragmented retail demand.
India Automotive Coolant Market Segmentation
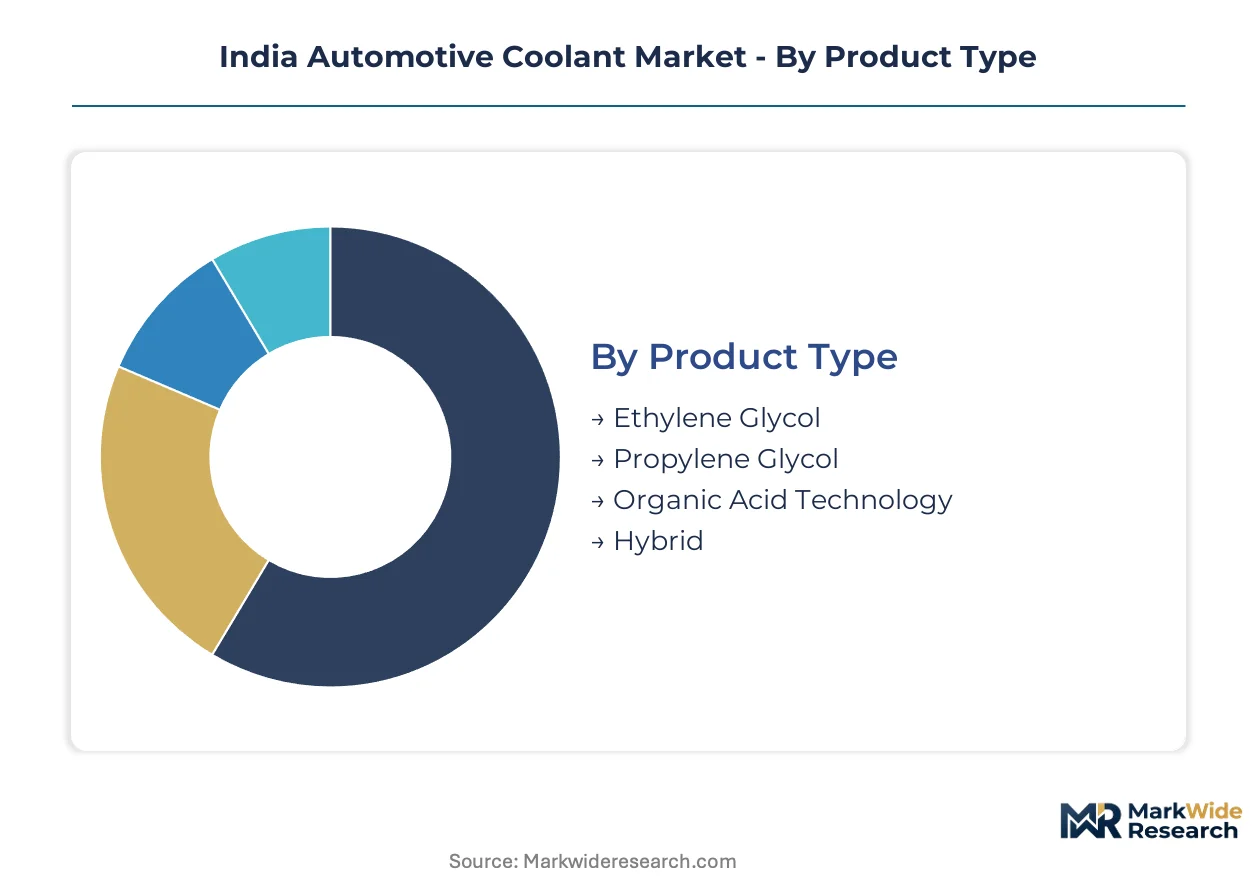
Coolant procurement patterns in India diverge sharply across vehicle parc age, fleet ownership structure, and regulatory compliance tier. Formulation chemistry and channel economics create distinct margin profiles that reward suppliers with OEM certification or direct fleet relationships.
Product Type:
Ethylene glycol formulations command volume dominance while organic acid technology captures premium expansion.
- Ethylene Glycol:Petroleum-derived base fluid blended with silicate corrosion inhibitors dominates aftermarket refills across India's legacy commercial-vehicle parc. Maharashtra and Gujarat fleet operators specify this chemistry for pre-BSIV assets where compatibility constraints block organic acid migration.
- Organic Acid Technology:Carboxylate-based silicate-free formulations extend drain intervals beyond 500,000 kilometers in aluminum-compatible cooling systems. Tamil Nadu's automotive manufacturing belt is displacing conventional chemistry fastest as OEM first-fill specifications harden around extended service intervals.
- Propylene Glycol:Bio-based alternative with toxicity advantages limited to niche electric-vehicle thermal management applications by inferior thermal-transfer coefficients and 40% higher unit costs.
- Hybrid:Intermediate chemistry blending organic acid longevity with conventional inhibitor compatibility serves mixed-age fleet operators seeking inventory simplification.
Today's leader: Ethylene Glycol. Tomorrow's challenger: Organic Acid Technology.
Use Case:
Passenger vehicles generate absolute volume while commercial vehicles yield predictable replenishment economics.
- Passenger Vehicles:India's largest coolant consumption segment by unit volume, with aluminum-intensive engine architectures mandating low-silicate formulations. Delhi-NCR replacement-vehicle production is accelerating OEM first-fill demand for long-life chemistries.
- Commercial Vehicles:Higher per-unit consumption and workshop-driven replenishment cycles generate superior margin stability. Fleet operators across Mumbai-Pune logistics corridors negotiate annual maintenance contracts directly with certified blenders.
- Heavy Machinery:Construction and mining equipment in Rajasthan's extractive zones demands extreme-duty formulations with supplemental cavitation protection for wet-sleeve diesel architectures.
- Motorcycles:Air-cooled dominance limits coolant penetration to premium liquid-cooled models; aftermarket refill volumes concentrate in urban service centers.
Commercial Vehicles anchor supplier profitability. Passenger Vehicles scale manufacturing throughput.
End User:
OEM procurement consolidates around certified first-fill positions while aftermarket fragments across channel tiers.
- OEMs:Domestic passenger-vehicle manufacturers specify extended-life organic acid formulations to satisfy Ministry of Road Transport and Highways warranty regulations. BIS certification mandates filter supplier pools to pre-approved blenders with ARAI test-protocol completion.
- Aftermarket Providers:Regional distributors serving tier-two cities face margin compression from Indian Oil Corp.'s fuel-station network expansion into packaged coolant retail.
- Retail Customers:Individual vehicle owners in unorganized sectors rely on loose bulk supply from local workshops, though Central Pollution Control Board water-toxicity rules are forcing packaged product migration.
- Workshops:Fleet-aligned service centers in Gujarat's logistics corridors are unbundling coolant procurement from general lubricant supply, negotiating direct blender agreements.
OEMs concentrate technical validation power. Workshops are disintermediating traditional distribution.
Distribution Channel:
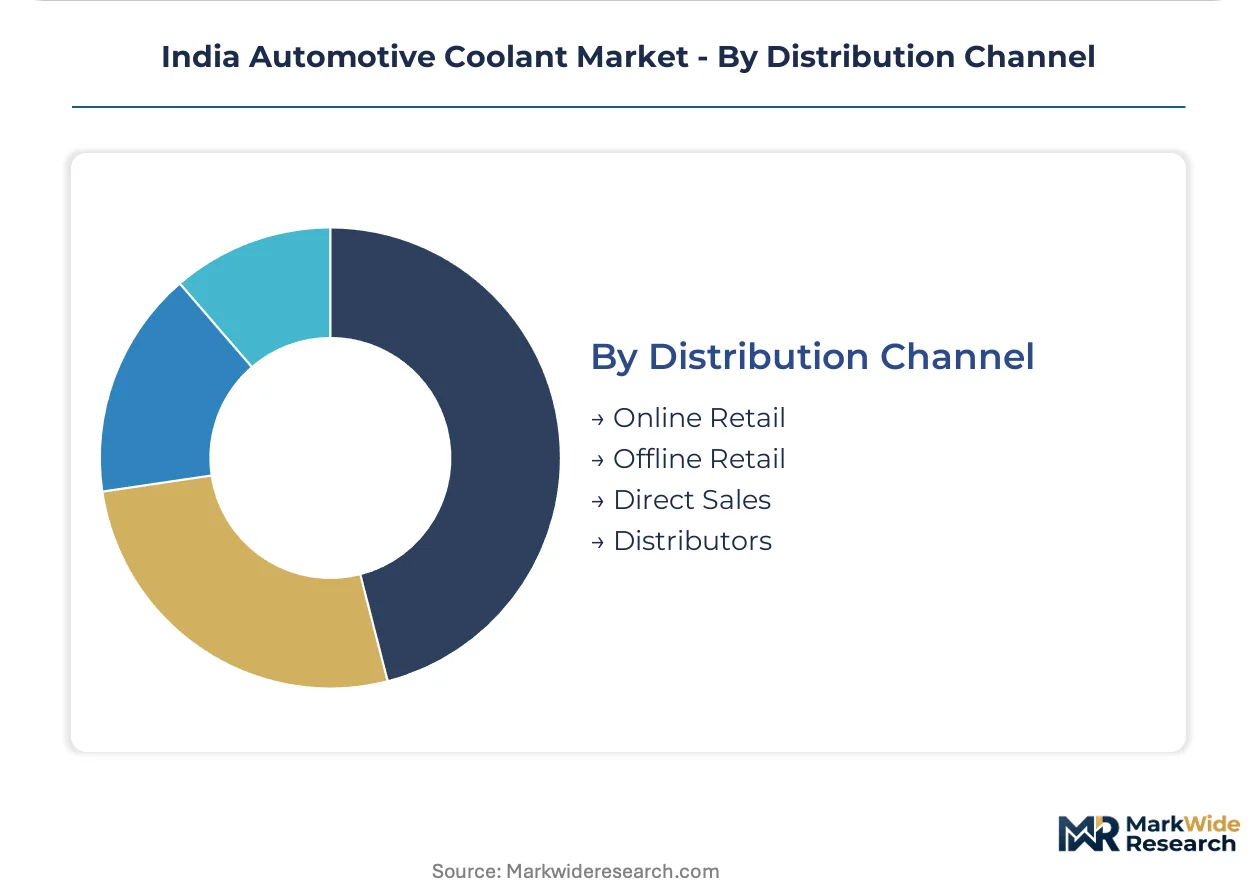
Offline infrastructure retains coolant's physical handling requirements while digital penetration advances in standardized formulations.
- Offline Retail:Kirana automotive stores and spare-part markets in Madhya Pradesh remain dependent on loose bulk supply, though BIS enforcement is accelerating packaged product adoption.
- Direct Sales:Fleet operators in Maharashtra bypass distributor networks for annual volume contracts with certified blenders, compressing margin pools for regional stockists.
- Distributors:Legacy regional networks face structural pressure from integrated refiner retail expansion and workshop procurement consolidation.
- Online Retail:E-commerce platforms capture standardized passenger-vehicle refill volumes in tier-one cities where specification clarity reduces physical inspection requirements.
Direct Sales capture fleet value. Online Retail is climbing fastest in urban replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled formulation chemists and tribology specialists cluster around India's automotive manufacturing corridors, concentrating technical capability in states with dense OEM presence and fleet operator networks.
Maharashtra
Mumbai-Pune logistics corridors generate dense commercial-vehicle fleet activity with predictable coolant replenishment cycles. BIS certification mandates elevate entry barriers for aftermarket suppliers serving this industrial belt. Fleet operators in Nashik and Aurangabad negotiate direct annual maintenance contracts with certified blenders, bypassing traditional distributor networks.
Gujarat
Sanand and Halol automotive clusters anchor passenger-vehicle production with aluminum-intensive engine architectures demanding low-silicate formulations. The state's central pollution control enforcement accelerates heavy-metal elimination from corrosion-inhibitor packages. Port-connected logistics hubs in Mundra and Hazira sustain commercial-vehicle throughput with workshop-driven coolant demand.
Tamil Nadu
Oragadam and Sriperumbudur manufacturing belts displace conventional silicate chemistry fastest as OEM first-fill specifications harden around extended service intervals. Organic acid technology adoption concentrates here due to proximity to domestic passenger-vehicle assembly plants. Automotive Research Association of India test-protocol completion requirements filter supplier pools to pre-approved blenders.
Delhi-NCR
Vehicle retirement schemes under state scrapage policies accelerate replacement-vehicle production, boosting OEM first-fill demand for long-life chemistries. Gurugram and Manesar automotive clusters face stringent National Capital Region air quality regulations that tighten particulate-matter compliance across coolant specifications. Ministry of Road Transport and Highways warranty regulations indirectly pressure manufacturers to specify extended-drain formulations.
Haryana
Faridabad and Panipat industrial zones concentrate aftermarket coolant blending capacity serving northern India's fragmented workshop network. Central Pollution Control Board water-toxicity rules force packaged product migration away from loose bulk supply in unorganized retail channels. Indian Oil Corp.'s fuel-station network expansion penetrates tier-two cities previously dependent on regional stockists.
India Automotive Coolant Market Competitive Landscape
Integrated refiners with captive petrochemical feedstock compete with standalone blenders dependent on merchant glycol supply, creating a tiered structure where scale advantages concentrate in national oil companies. The market consolidates around three strategic archetypes: state-owned energy majors leveraging distribution infrastructure, multinational lubricant specialists with OEM certification relationships, and regional chemical blenders serving fleet direct contracts. Dominant competitive moves include backward integration into ethylene glycol production and exclusive long-term supply agreements with commercial-vehicle manufacturers.
Among state-owned energy majors, Bharat Petroleum Corporation Limited and Indian Oil Corp. Ltd occupy positions defined by fuel-station network reach into tier-three cities. Castrol Limited exemplifies the multinational lubricant specialist archetype through premium positioning and domestic OEM tie-ups. Gulf Oil International represents the fleet-focused competitor segment competing aggressively on commercial-vehicle contracts in logistics corridors.
| Leading Market Players |
|---|
| Valvoline LLC |
| Bharat Petroleum Corporation Limited |
| Indian Oil Corp. Ltd |
| Shell Lubricants |
| Gulf Oil International |
| Castrol Limited |
| Motul |
| IFTEX Oil & Chemicals Ltd. |
| ExxonMobil Corp. |
| Others |
Supply & Pricing Matrix
Organic acid technology migration across India's automotive coolant value chain simultaneously elevates formulation costs and consolidates procurement around certified blenders with ARAI test-protocol completion. This chemistry transition compresses margin pools for aftermarket refill producers while rewarding integrated refiners with captive ethylene glycol supply and established BIS certification infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale. Price differentiation separates ARAI-approved organic acid formulations for OEM first-fill from conventional silicate chemistry serving legacy fleet compatibility needs. Cost compression in economy-tier aftermarket refills is intensifying because Central Pollution Control Board water-toxicity rules force heavy-metal reformulation. Fleet operators negotiating annual maintenance contracts demonstrate lowest price sensitivity, while unorganized retail customers in tier-three cities exhibit highest elasticity.
Supply Chain Analysis
BIS certification and ARAI test-protocol completion gate supplier participation in OEM first-fill contracts, filtering the vendor base to pre-approved blenders. Manufacturing concentration centers on Maharashtra, Gujarat, and Tamil Nadu automotive clusters, with ethylene glycol feedstock drawing from domestic petrochemical refiners and merchant importers. Single-source vulnerability runs through concentrated organic acid additive supply from multinational chemical specialists. Distribution runs through Indian Oil Corp.'s fuel-station network expansion, direct fleet contracts, and legacy regional distributor networks serving fragmented workshop demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
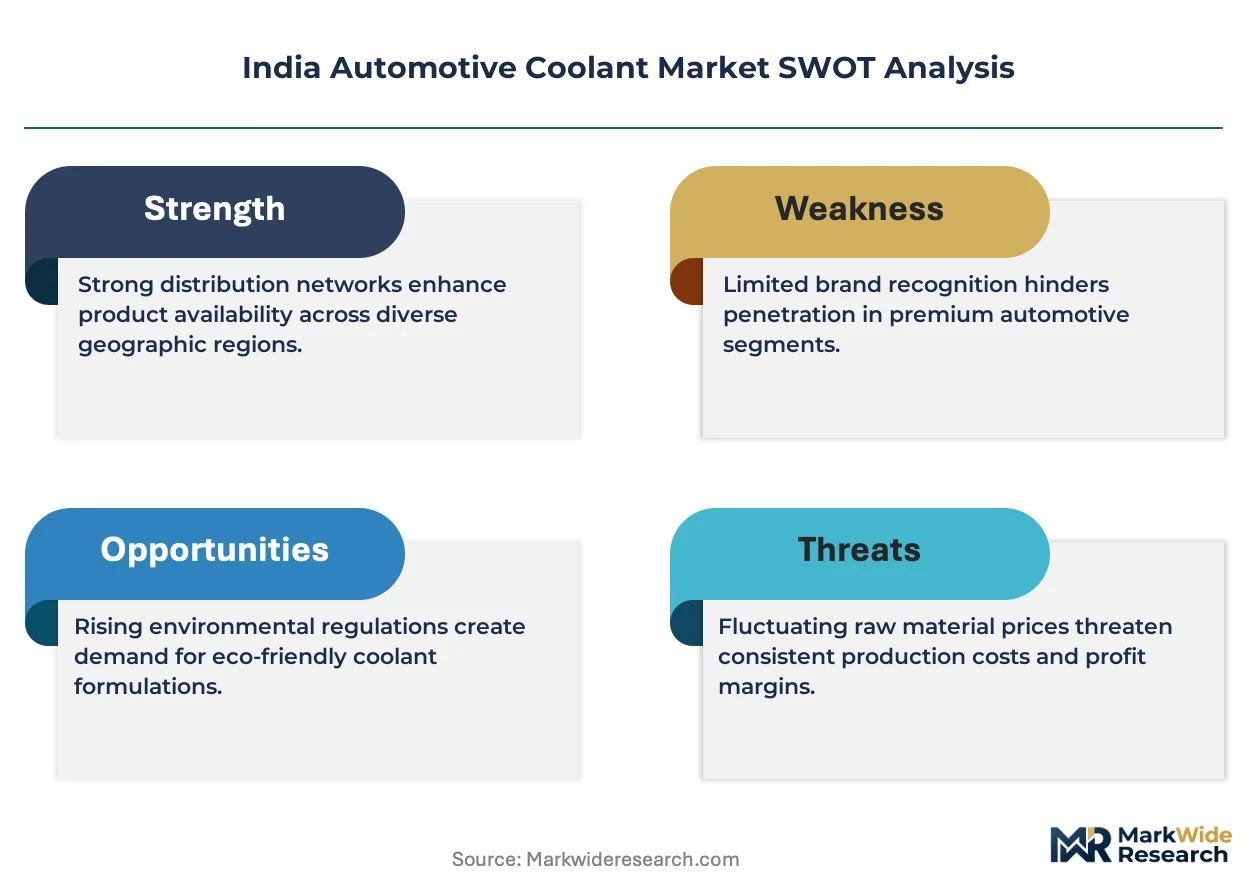
India's automotive coolant market functions as a geographic-arbitrage play where BIS certification costs and ARAI testing timelines in India run substantially lower than equivalent EU REACH compliance burdens, attracting formulation investment toward domestic supply.
For Market Incumbents: To counter margin compression from ethylene glycol price volatility, secure long-term supply contracts with integrated refiners and deepen backward integration into corrosion-inhibitor precursor manufacturing. Prioritize certification maintenance investments to defend OEM first-fill positions against emerging blenders seeking ARAI approval. For New Entrants and Emerging Players: BIS emission norm tightening in Maharashtra and Gujarat opens a window for organic acid technology specialists to capture fleet direct contracts bypassing traditional distributor networks. Target tier-three city penetration through Indian Oil Corp. fuel-station partnerships, and pursue white-space positioning in electric-vehicle dielectric coolant formulations. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier blenders with ARAI certification completion but lacking integrated refiner feedstock access. Long-term viability hinges on chemistry transition execution capability across the projection horizon. Acquisition target archetype: certified regional blenders with established fleet relationships in logistics corridors. Monitor organic acid technology adoption rates in Tamil Nadu manufacturing belts as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Glycol | Captive petrochemical feedstock secures margin stability against merchant price volatility. |
| ARAI Certification Investment | Test-protocol completion unlocks OEM first-fill contracts with domestic passenger-vehicle manufacturers. |
| Fuel-Station Network Expansion | Indian Oil Corp. retail penetration captures tier-three city demand from loose bulk supply. |
| Organic Acid Technology Capacity Buildout | Extended-drain formulation capability aligns with BS VI emission norm requirements. |
| Electric-Vehicle Coolant Development | Dielectric thermal-fluid positioning opens battery-electric platform white-space demand. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Tamil Nadu, Delhi-NCR, and Haryana, with primary inputs from each automotive manufacturing cluster. The approach combines primary interviews with OEM procurement managers, fleet maintenance directors, aftermarket distributor operators, and formulation chemists at blending facilities with secondary validation from BIS certification records, ARAI test-protocol documentation, Central Pollution Control Board regulatory filings, and vehicle production databases. Bottom-up triangulation across channel volume estimates and top-down cross-checks against petrochemical feedstock consumption data anchor analytical rigor.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window. Segmentation dimensions modeled include formulation chemistry tier, vehicle class architecture, end-user procurement modality, and regional production cluster concentration. CAGRs derive from trend extrapolation of fleet expansion rates, emission norm implementation timelines, and chemistry transition adoption curves. Industry-specific forecast inputs incorporate BS VI compliance penetration rates and scrapage policy implementation intensity in Delhi-NCR and Maharashtra.
Revisions become necessary when BIS certification requirement changes, ethylene glycol feedstock price dislocations, or electric-vehicle platform thermal-management specification shifts materialize beyond modeled assumptions. Forecasts reflect documented assumptions about regulatory enforcement consistency and fleet operator procurement behavior stability. A model refresh is warranted upon material change in organic acid technology cost parity timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
South Africa Passenger Vehicles Lubricants Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Rammer Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
Automotive Performance Parts Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Automatic Bus Door System Market