
 Saudi Arabia Last Mile Delivery Market | 2026-2036
Saudi Arabia Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Last Mile Delivery Market Analysis
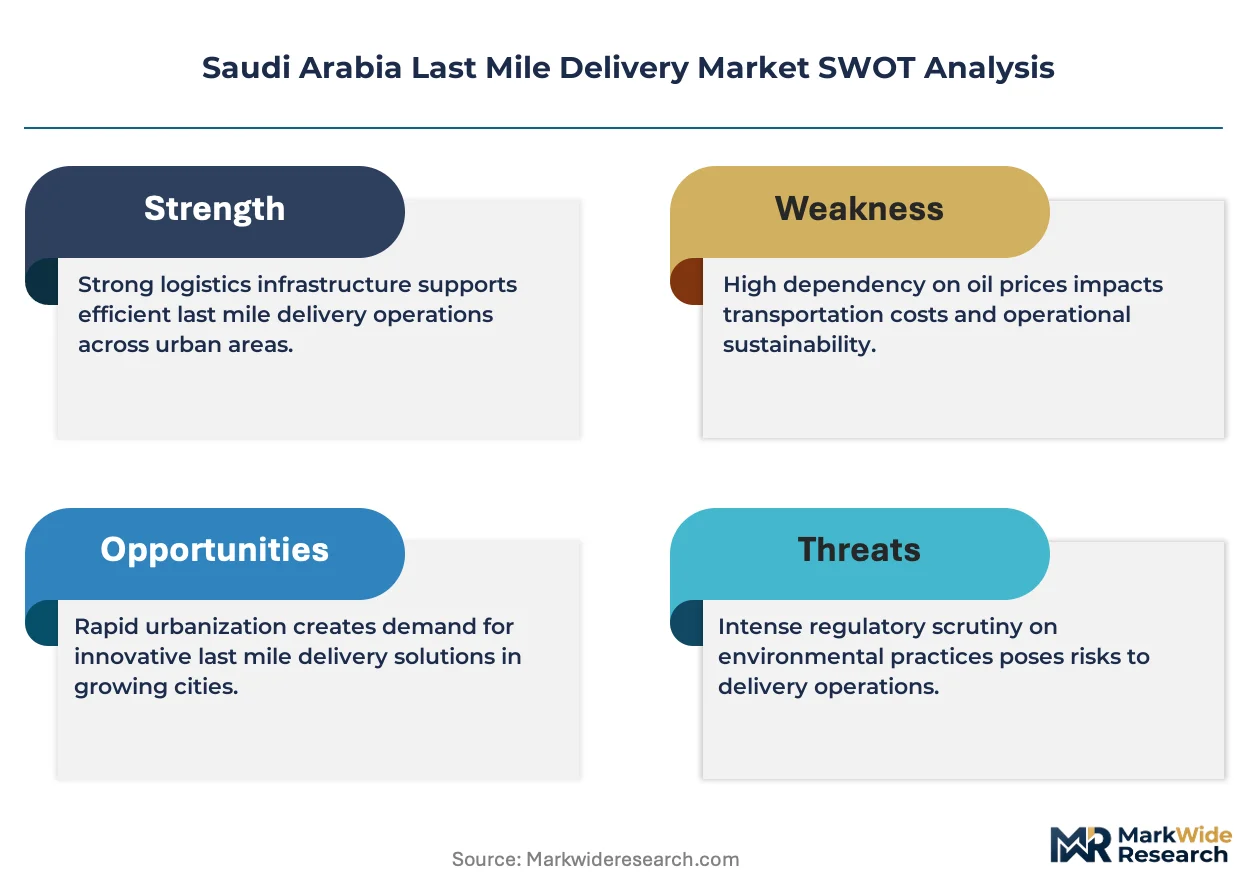
Expatriate logistics labor availability is reorganizing how Saudi last-mile operators staff peak seasons and expand geographic coverage. Aramex leverages its regional hub infrastructure to maintain cross-border parcel flows into the Kingdom. Naqel Express anchors domestic coverage through its extensive depot network across secondary cities. SMSA Express competes on enterprise contract density, particularly with healthcare and retail clients requiring temperature-controlled handling.
Last mile delivery constitutes the final leg of supply chain execution where parcels move from distribution hubs to end recipients, typically spanning distances under fifty kilometers and requiring real-time route optimization and proof-of-delivery capture. The segment serves as the critical customer touchpoint where delivery speed, accuracy, and communication quality directly determine repurchase behavior and platform loyalty. Express delivery and same-day delivery command premium positioning as e-commerce platforms and quick-commerce operators prioritize speed as a competitive weapon. Standard delivery retains volume leadership in non-urban zones where density economics resist acceleration. Mobile applications and GPS tracking dominate technology investment as fleet visibility and customer notification systems become baseline expectations rather than differentiators.
SFDA oversight of pharmaceutical and temperature-sensitive shipments shapes cold-chain packaging and vehicle specifications for healthcare last-mile services. The Saudi Standards, Metrology and Quality Organization governs vehicle safety and emissions profiles for delivery fleets operating under commercial licenses. MOHAP guidelines for medical product distribution add compliance layers that specialized operators must navigate to serve hospital and pharmacy networks. Stakeholders must weigh whether to build captive delivery infrastructure or partner with third-party platforms as Riyadh and Jeddah approach saturation and expansion shifts toward Dammam and emerging economic zones.
Market Dynamics
Data localization mandates from the Saudi Communications, Space and Technology Commission are forcing logistics platforms to rebuild their IT infrastructure on domestic servers, raising compliance costs while creating competitive moats for operators with established local data centers.
Growth Catalysts
- E-commerce fulfillment acceleration:Same-day delivery expectations from Saudi consumers are pulling investment into micro-fulfillment centers across Riyadh and Jeddah, compressing delivery radii below fifteen kilometers.
- SFDA cold-chain mandates:Pharmaceutical distribution regulations require temperature-validated vehicles and real-time monitoring, creating specialized service tiers with premium pricing power.
- Quick-commerce proliferation:Fifteen-minute grocery and pharmacy delivery apps are normalizing hyperlocal hub networks that legacy parcel operators must replicate to retain volume.
Market Restraints
- Expatriate labor dependency:Visa quota fluctuations and Saudization targets create staffing volatility during Ramadan and year-end peak seasons.
- Fleet electrification costs:Commercial EV procurement and charging infrastructure deployment strain operator balance sheets before fuel savings materialize.
- Secondary city density gaps:Low order concentration in Tabuk, Hail, and Baha provinces prevents route optimization algorithms from achieving viable unit economics.
Strategic Opportunities
- NEOM logistics corridor:The linear city's planned autonomous vehicle networks and drone delivery zones offer greenfield infrastructure without legacy system integration burdens.
- Healthcare last-mile specialization:Hospital-at-home programs and chronic disease management are expanding addressable demand for temperature-controlled, time-definite pharmaceutical delivery.
- Cross-border GCC integration:Unified customs protocols under the Gulf Cooperation Council enable consolidated hub-and-spoke networks serving Bahrain, Kuwait, and UAE from Saudi distribution centers.
Industry Challenges
- Route optimization talent scarcity:Data scientists capable of integrating real-time traffic, customer availability windows, and vehicle capacity constraints command compensation premiums that mid-size operators struggle to match.
- Legacy WMS integration friction:Warehouse management systems designed for bulk distribution require expensive middleware development to synchronize with last-mile dispatch platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Last Mile Delivery Market |
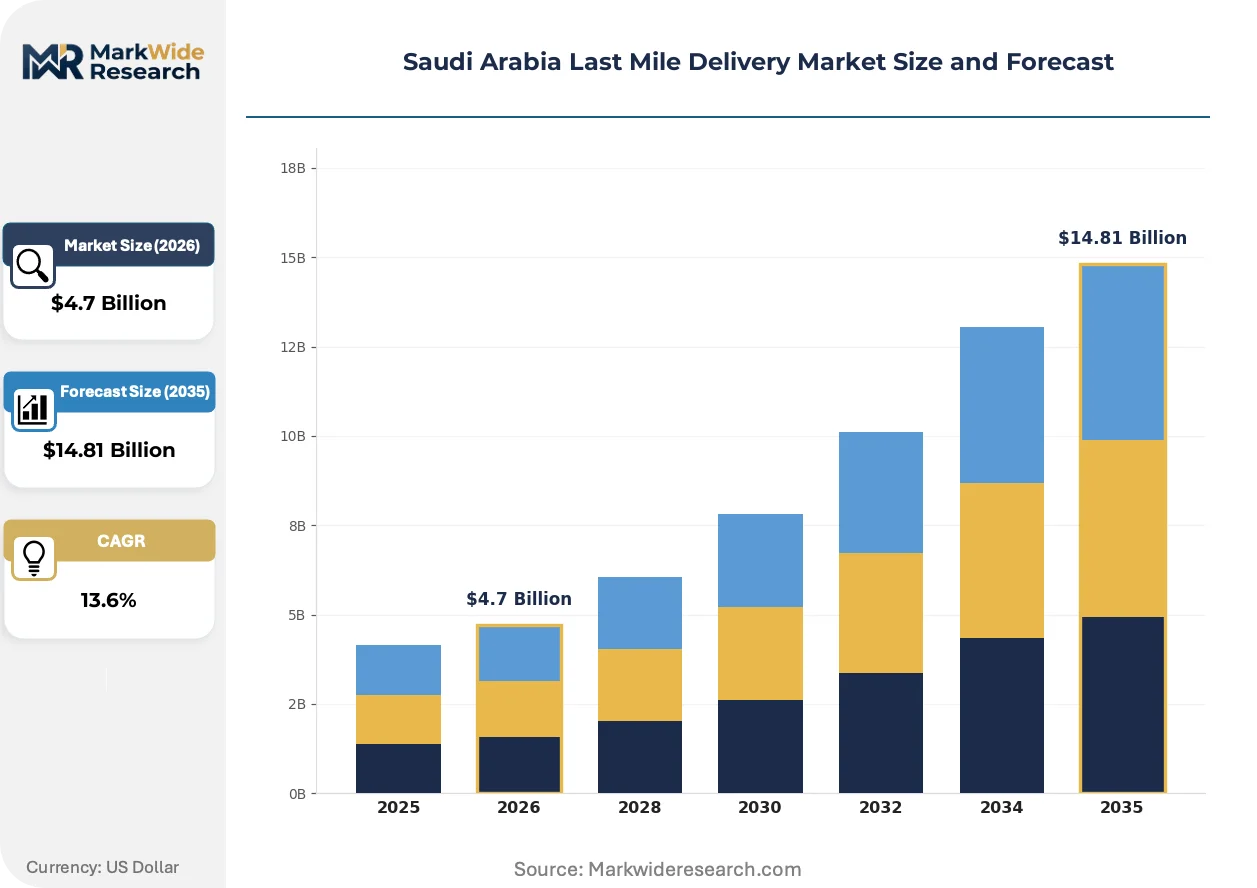
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Standard Delivery, Same-Day Delivery, Scheduled Delivery Technology: Mobile Applications, GPS Tracking, Automated Sorting, Drones End User: E-Commerce, Retail, Food & Beverage, Healthcare Distribution Channel: Online, Offline, Partnered Solutions, Last-Mile Partnerships |
| Companies Covered | Aramex, Naqel Express, SMSA Express, Zajil Express, AJEX, DHL Express, FedEx, Fetchr, Diggipacks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Last Mile Delivery Market Emerging Trajectories
Artificial intelligence and autonomous systems are compressing delivery timelines while regulatory pressure on data sovereignty and emissions is reshaping capital allocation across the sector.
Electric cargo bikes and three-wheelers are displacing small vans in Riyadh's congested commercial districts, cutting parking violation costs and enabling sidewalk-level handoffs. Quick-commerce operators including grocery and pharmacy platforms have adopted these vehicles for sub-five-kilometer routes. This shift is displacing traditional four-wheel fleet procurement plans and forcing vehicle leasing companies to expand micromobility offerings.
SFDA serialization requirements for pharmaceutical shipments mandate unit-level tracking from manufacturer to patient, creating compliance layers that favor operators with integrated warehouse-to-doorstep visibility systems. Cold-chain validation documentation must now accompany every temperature-sensitive parcel. Specialized healthcare logistics providers are responding by certifying drivers in GDP (Good Distribution Practice) protocols and equipping vehicles with redundant temperature logging.
Subscription-based delivery memberships are consolidating consumer loyalty around platforms offering predictable monthly fees for unlimited same-day service. Retailers and pure-play logistics marketplaces are competing to bundle delivery with streaming, grocery, and pharmacy benefits. This model is most visible in Riyadh and Jeddah, where household penetration of e-commerce subscriptions has crossed thirty percent and is compressing per-order profitability for pay-per-delivery competitors.
Saudi Arabia Last Mile Delivery Market Segmentation
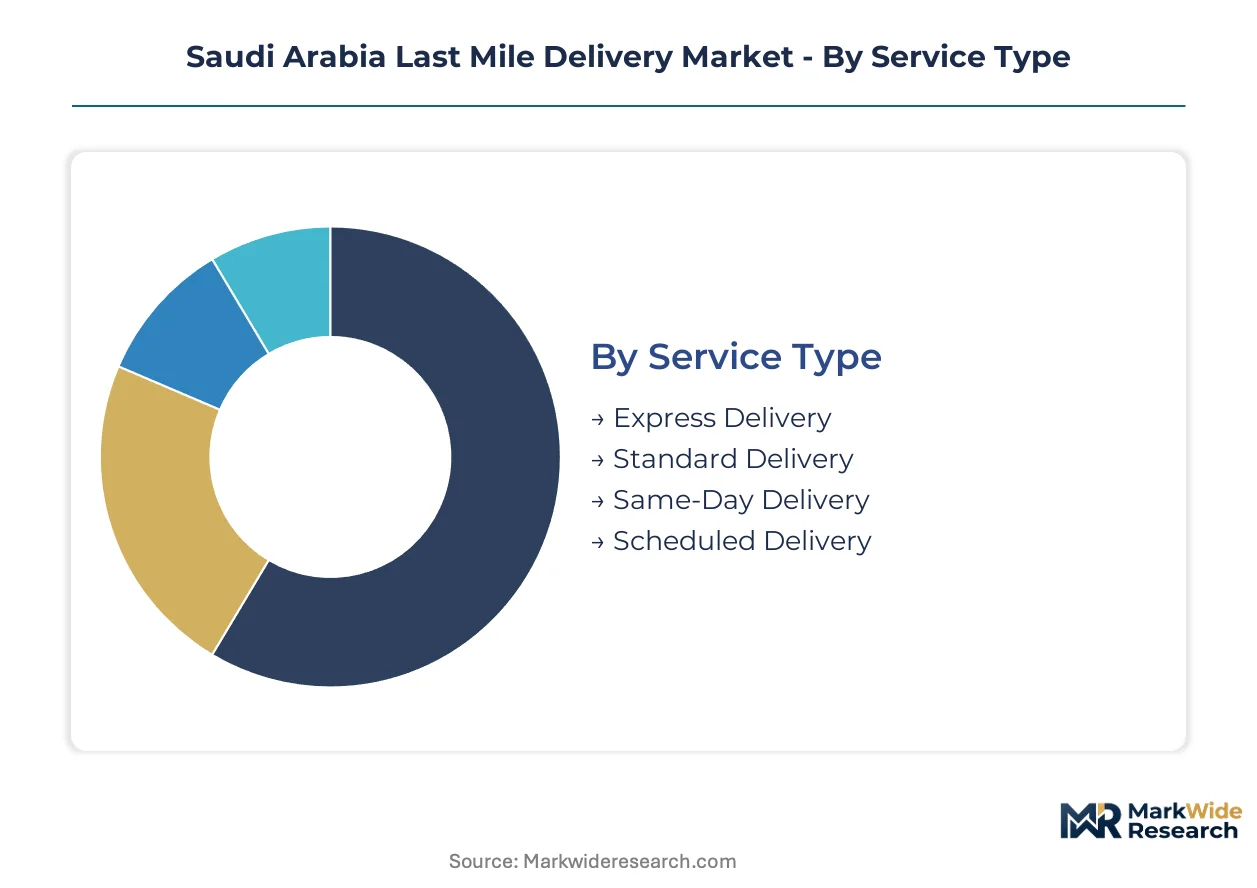
Segmentation in Saudi Arabia's last mile delivery market reveals how regulatory pressure and urban density reshape operator investment priorities. Service tiers diverge sharply between premium corridors in Riyadh and Jeddah versus cost-constrained secondary cities. Technology deployment and end-use specialization further stratify competitive positioning across the Kingdom.
Service Type:
SFDA cold-chain mandates and CST data localization rules create compliance moats that favor operators with capital to segment service tiers vertically.
- Express Delivery:Time-definite parcels moving through dedicated fleet lanes with real-time tracking and signature capture. Riyadh's financial district and Jeddah's King Abdullah Economic Zone generate concentrated demand from legal documents and high-value retail shipments subject to Saudization staffing quotas.
- Standard Delivery:Non-urgent parcels consolidated through hub-and-spoke networks with next-day or two-day service windows. Tabuk, Hail, and Baha provinces rely on this tier exclusively where route density economics resist faster service investment.
- Same-Day Delivery:Micro-fulfillment center networks compressing delivery radii below fifteen kilometers for e-commerce platforms competing on speed.
- Scheduled Delivery:Appointment-based windows for large-format goods and B2B procurement requiring recipient presence.
Standard Delivery handles the majority of throughput; Same-Day Delivery is gaining share fastest as quick-commerce apps normalize sub-hour expectations.
Technology:
Capital deployment across technology layers tracks directly to CST compliance deadlines and fleet electrification timelines under SASMO vehicle emissions standards.
- Mobile Applications:Customer-facing platforms integrating order placement, real-time tracking, and digital proof-of-delivery. Riyadh and Jeddah households now treat app-based scheduling and live GPS visibility as baseline expectations rather than premium features.
- GPS Tracking:Fleet telematics systems providing dispatch centers with vehicle location, route deviation alerts, and driver behavior analytics required for insurance underwriting and fuel efficiency reporting.
- Automated Sorting:Hub conveyor systems and parcel dimensioning equipment reducing manual handling at distribution centers serving high-volume e-commerce clients.
- Drones:Pilot programs in NEOM and remote coastal zones testing autonomous aerial delivery for medical supplies and documents beyond road network reach.
GPS Tracking anchors current infrastructure spending; Drones show the steepest expansion trajectory as NEOM's linear city eliminates legacy integration burdens.
End User:
End-use demand concentrates where disposable income, regulatory specialization requirements, and platform penetration overlap.
- E-Commerce:Pure-play online retailers and marketplace platforms driving volume through micro-fulfillment centers. Cross-border parcel flows from GCC neighbors consolidate in Saudi hubs before final-mile dispersion.
- Retail:Omnichannel merchants blending store inventory with home delivery, particularly in Riyadh's luxury mall corridors where click-and-collect transitions to same-day dispatch.
- Food & Beverage:Quick-commerce grocery and prepared meal platforms deploying electric cargo bikes for sub-five-kilometer routes in congested commercial districts.
- Healthcare:Pharmaceutical distributors requiring GDP-certified drivers, redundant temperature logging, and SFDA serialization compliance from manufacturer to patient.
E-Commerce captures the dominant revenue share; Healthcare posts the fastest climb as hospital-at-home programs expand chronic disease management logistics.
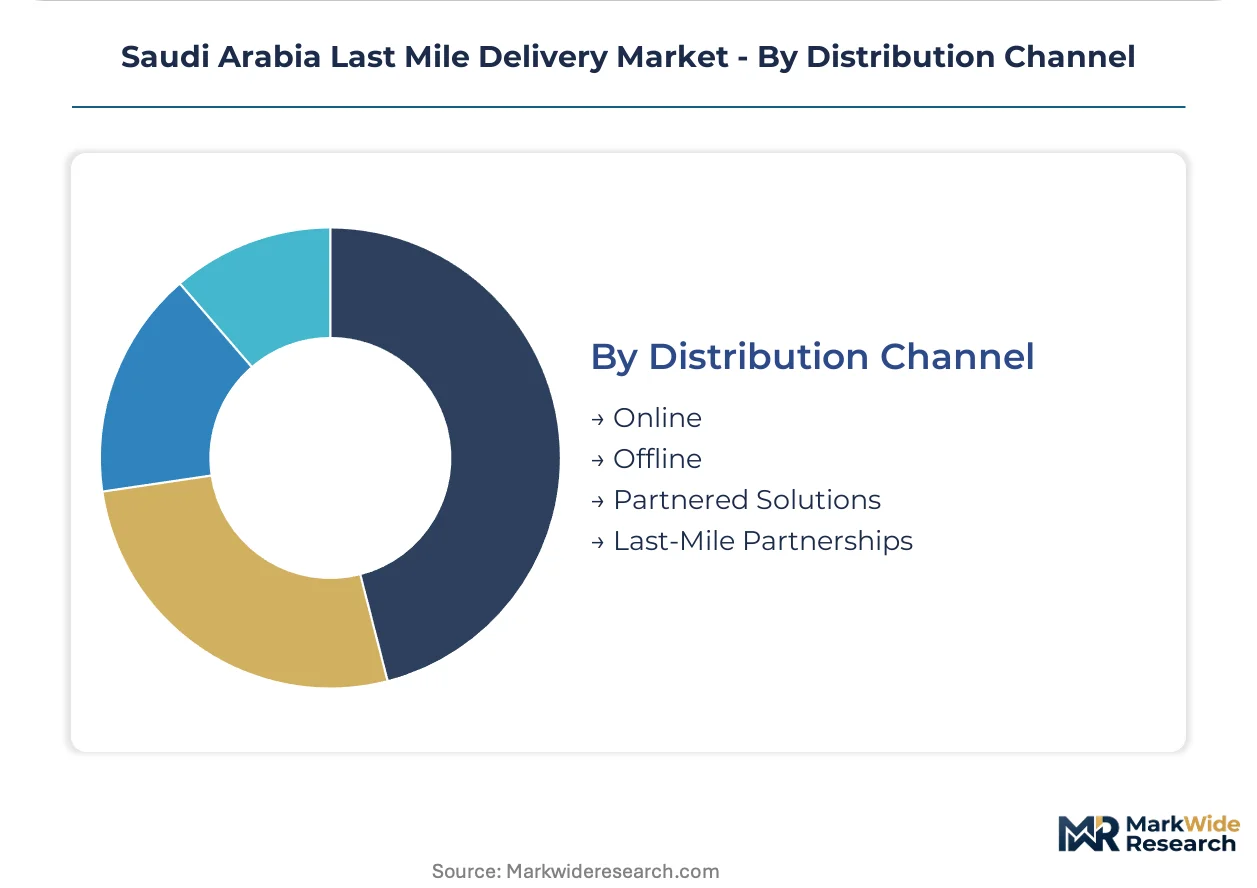
Distribution Channel:
Channel strategy hinges on whether operators build captive infrastructure or leverage third-party platforms as Riyadh and Jeddah approach saturation.
- Online:Direct-to-consumer platforms owning the full technology stack from order capture through delivery confirmation, common among quick-commerce specialists with subscription membership models.
- Offline:Traditional courier counter networks and retail partner locations for parcel drop-off and collection, persisting in secondary cities with lower smartphone penetration.
- Partnered Solutions:White-label delivery services where logistics operators execute fulfillment under retailer branding without consumer-facing platform ownership.
- Last-Mile Partnerships:Shared fleet arrangements between parcel carriers and quick-commerce platforms to improve vehicle utilization during off-peak hours.
Online channels command the greatest investment intensity; Last-Mile Partnerships are expanding most quickly as operators seek density economics through asset sharing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh commands premium pricing power for same-day delivery corridors while secondary provinces operate on thinner margins due to density gaps. This asymmetry drives capital concentration in the Central and Western regions. Expansion into emerging zones depends on regulatory harmonization and infrastructure commitments.
Riyadh
E-commerce platform headquarters and micro-fulfillment center networks generate concentrated demand for sub-hour delivery windows. The Saudi Communications, Space and Technology Commission enforces data localization rules that raise IT infrastructure costs for operators serving the capital. King Abdullah Financial District and Diriyah Gate anchor logistics investment as quick-commerce apps normalize subscription-based delivery memberships.
Eastern Province
Industrial zone procurement and petrochemical supply chains create specialized B2B last-mile requirements distinct from consumer parcel flows. SASMO vehicle emissions standards push fleet operators toward commercial EV procurement despite charging infrastructure gaps. Dammam and Khobar form the core logistics cluster where cross-border GCC integration enables consolidated hub operations serving Bahrain and Kuwait.
Western Region
Jeddah's Red Sea port dominance and religious tourism flows generate seasonal volume spikes requiring flexible staffing models. SFDA cold-chain mandates shape pharmaceutical distribution networks serving hospital and pharmacy corridors along the Mecca-Jeddah axis. King Abdullah Economic Zone attracts fulfillment center investment as operators seek alternatives to Riyadh's rising real estate costs.
NEOM Northwest
The linear city's autonomous vehicle and drone delivery pilot programs offer greenfield infrastructure without legacy system integration burdens. NEOM's regulatory sandbox allows testing of aerial delivery corridors for medical supplies beyond road network reach. THE LINE and Oxagon industrial city anchor planned logistics zones where density economics are engineered rather than inherited.
Saudi Arabia Last Mile Delivery Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Saudi last-mile market. Regional hub operators with integrated cross-border networks compete against domestic specialists with dense depot coverage in secondary cities. Three archetypes dominate: GCC-integrated regional carriers, Saudi-focused domestic operators, and global express networks with premium positioning. Competitive moves concentrate on fleet electrification partnerships and micro-fulfillment center joint ventures with quick-commerce platforms.
Within the domestic specialist tier, Naqel Express anchors extensive depot networks across secondary cities while SMSA Express occupies a position serving enterprise healthcare and retail contracts. Aramex represents the GCC-integrated archetype with regional hub infrastructure maintaining cross-border parcel flows. These three exemplify how operator strategy diverges between geographic coverage depth and service specialization.
| Leading Market Players |
|---|
| Aramex |
| Naqel Express |
| SMSA Express |
| Zajil Express |
| AJEX |
| DHL Express |
| FedEx |
| Fetchr |
| Diggipacks |
| Others |
Supply Flow & Price Mechanics
Micro-fulfillment center density in Riyadh and Jeddah compresses delivery radii below fifteen kilometers, creating scale economies that concentrate pricing power among operators with hub networks while establishing cost floors that exclude undercapitalized entrants from same-day service tiers.
Pricing Analysis
Configured-to-order pricing for temperature-controlled pharmaceutical deliveries commands spreads of forty to sixty percent above standard parcel rates, reflecting SFDA compliance costs and GDP-certified driver premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies around delivery velocity, with same-day subscriptions capturing household loyalty through predictable monthly fees. Cost compression in standard delivery is intensifying because electric fleet depreciation and CST data localization infrastructure amortization weigh on mid-size operators. Quick-commerce platforms exhibit lowest price sensitivity due to bundled membership economics, while secondary city SMEs face acute margin pressure from density gaps.
Supply Chain Analysis
Inventory lead times for commercial electric vehicles and cold-chain packaging materials stretch sixteen to twenty-four weeks, tethering fleet expansion plans to supplier capacity in China, South Korea, and Germany. Battery cell and telematics hardware dependencies expose operators to semiconductor allocation volatility and rare earth price swings. Single-source vulnerability concentrates in lithium-ion procurement from Chinese cell manufacturers. Distribution runs through hub-and-spoke networks anchored at Riyadh's King Abdullah Financial District and Jeddah's King Abdullah Economic Zone, with spoke extensions into Dammam and emerging secondary corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Route optimization algorithm development and real-time traffic data integration constitute the binding capability constraint, with fewer than two hundred qualified data scientists available domestically to serve a market expanding toward fourteen billion dollars.
For Market Incumbents: Consolidate depot networks in Tabuk, Hail, and Baha provinces through acquisition of regional specialists before greenfield buildout economics improve. Lock in exclusive micro-fulfillment center joint ventures with quick-commerce platforms to defend density advantages against emerging asset-light competitors. Prioritize backward integration into electric cargo bike leasing to capture vehicle utilization premiums currently flowing to third-party fleet providers. For New Entrants and Emerging Players: Lead with healthcare last-mile specialization targeting hospital-at-home programs and chronic disease management logistics, where SFDA compliance moats deter generalist competitors. NEOM's autonomous vehicle regulatory sandbox offers the most penetrable geography for drone delivery pilots without legacy system integration burdens. Position through GDP-certified driver networks and redundant temperature logging capabilities rather than competing on delivery velocity alone. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based quick-commerce platforms with household penetration above thirty percent in Riyadh and Jeddah, suggesting superior cash flow quality relative to transactional parcel operators. Long-term viability hinges on electrification fleet scale and data localization compliance infrastructure. Target acquisition candidates with established CST-certified IT stacks and secondary city depot licenses. Monitor Saudization staffing quota enforcement as the critical inflection signal for labor cost trajectory and competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Center Joint Venture | Compresses delivery radii below fifteen kilometers for same-day service competitiveness in Riyadh and Jeddah corridors. |
| Electric Fleet Procurement Partnership | Locks in commercial EV allocation priority ahead of SASMO emissions compliance deadlines and charging infrastructure buildout. |
| GDP Certification Investment | Enables SFDA-compliant pharmaceutical distribution contracts with premium pricing power in hospital-at-home expansion. |
| Data Localization Infrastructure Build | Satisfies CST mandates while creating competitive moats through domestic server deployment costs that exclude undercapitalized rivals. |
| Secondary City Depot Acquisition | Captures geographic licenses and established customer relationships in Tabuk, Hail, and Baha before density economics improve. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and fleet operator disclosures. Interviews with logistics platform CTOs, SFDA compliance officers, quick-commerce supply chain directors, and electric vehicle procurement managers informed operational cost structures and technology deployment timelines. Secondary validation drew from CST regulatory bulletins, SASMO vehicle emissions standards, SFDA pharmaceutical distribution guidelines, and GCC customs integration protocols. Bottom-up service tier volume estimates triangulated against top-down e-commerce platform fulfillment expenditure analysis.
Segmentation dimensions modeled span service type, technology deployment, end-use vertical, and distribution channel across the analysis window. CAGRs derive from logistic curve fitting to e-commerce penetration rates and quick-commerce subscription adoption patterns. Industry-specific forecast inputs incorporate Saudization staffing quota enforcement trajectories and NEOM infrastructure commissioning schedules.
Underlying assumptions cover regulatory compliance cost stability and electric vehicle procurement lead time normalization, with deviation risk concentrated in visa quota volatility and lithium-ion cell supply allocation. Revision becomes warranted when CST data localization enforcement intensity or GCC customs harmonization progress crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
US Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Singapore 3PL Market
Logistics and Shipping
Middle East and Africa Freight & Logistics Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Germany Same Day Delivery Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
Apparel Logistics Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Spain Freight and Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
South Korea International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Russia Freight and Logistics Market