
 Malaysia Road Freight Transport Market | 2026-2036
Malaysia Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Road Freight Transport Market Foresight
Telematics integration with AI-powered route optimization is rewriting operational economics for Malaysian fleet operators. Tiong Nam Logistics Holdings Bhd leverages its cold-chain infrastructure to dominate temperature-sensitive cargo across Peninsular Malaysia. CJ Logistics Corporation anchors its competitive position through integrated warehousing and last-mile capabilities in Johor Bahru. Swift Haulage Berhad specializes in container haulage between Port Klang and the Klang Valley industrial belt.
Malaysia road freight transport encompasses the movement of goods via commercial motor vehicles across federal and state highway networks, typically operating vehicles with gross vehicle weights exceeding 3.5 tonnes and utilizing diesel or biodiesel blends compliant with national emissions schedules. The sector functions as the primary logistics artery for manufacturing supply chains, agricultural distribution, and retail replenishment throughout the peninsula and East Malaysia. Full Truckload services command the largest revenue share due to manufacturing hub concentration in Selangor and Penang, while Less Than Truckload segments attract growing interest from small and medium enterprises seeking flexible shipment consolidation. Express delivery modes exhibit the fastest structural expansion, driven by e-commerce platform requirements for next-day fulfillment across urban corridors.
The Commercial Vehicles Licensing Board regulates fleet entry and route authority, while the Department of Environment enforces Euro 4 and impending Euro 5 emissions standards that compel engine upgrades or fleet renewal. BIS-equivalent Malaysian Standards and the Road Transport Department's mandatory periodic inspections shape vehicle specifications and maintenance protocols. Stakeholders must monitor biodiesel blend mandate escalations and cross-border ASEAN logistics agreements that could reconfigure fleet deployment strategies between Peninsular Malaysia and Thailand's southern economic corridor.
Market Dynamics
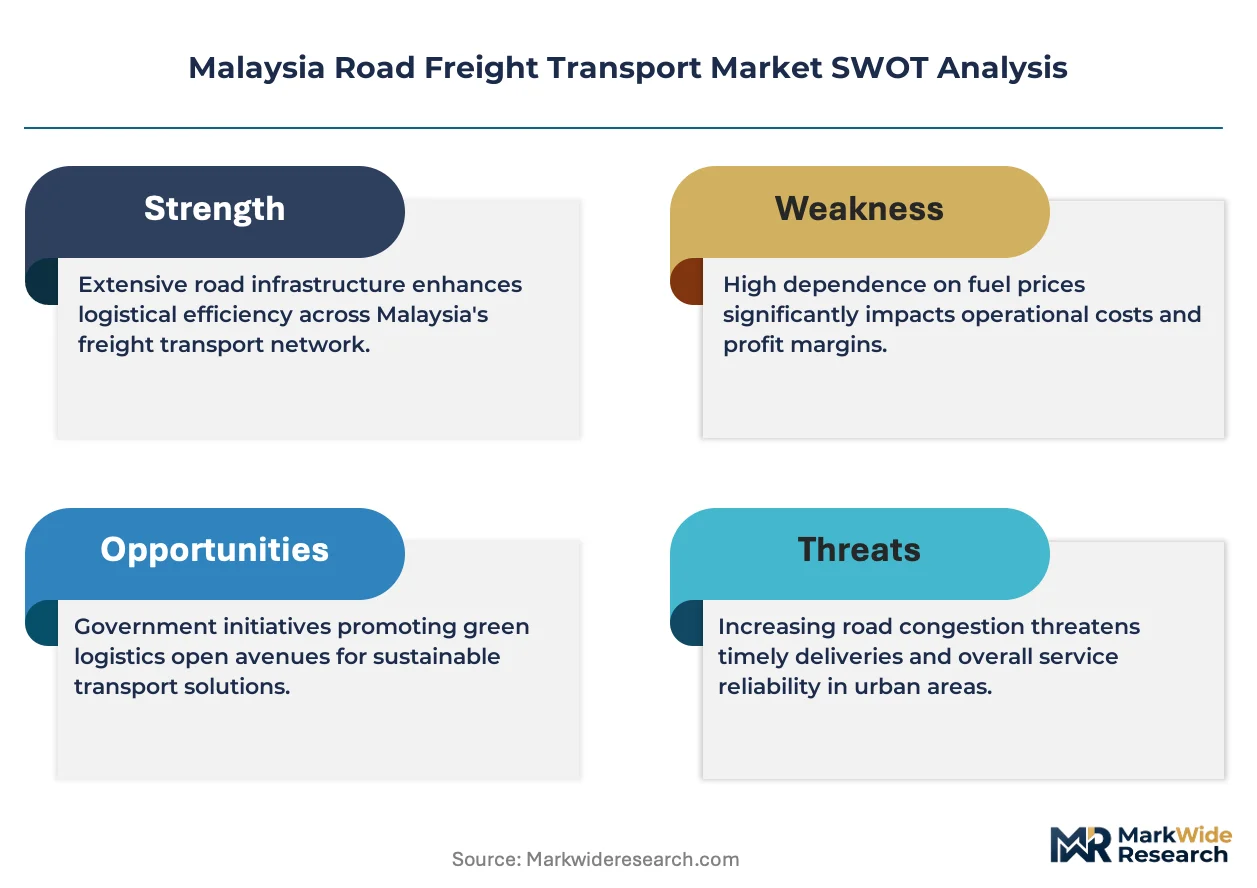
Malaysia's B20 biodiesel mandate for heavy vehicles is forcing fleet operators to reconfigure fuel procurement and engine maintenance protocols across Peninsular Malaysia's logistics corridors.
Growth Catalysts
- E-commerce fulfillment expansion:Selangor-based distribution centers are scaling last-mile capacity to meet next-day delivery commitments from major retail platforms. Cold-chain infrastructure investments in Shah Alam support temperature-sensitive cargo growth.
- Port Klang logistics corridor concentration:Manufacturing zones in the Klang Valley generate consistent full-truckload demand connecting to maritime terminals. Container haulage volumes between industrial belts and Port Klang anchor revenue stability for fleet operators.
- Euro 5 emissions preparation:The Department of Environment's impending standard is accelerating fleet renewal cycles. Engine upgrades and newer vehicle acquisitions are creating equipment demand across diesel and biodiesel-compatible platforms.
Market Restraints
- Biodiesel blend cost volatility:Palm oil price fluctuations directly impact B20 procurement economics for heavy vehicle operators. Fuel cost uncertainty compresses margin visibility for long-haul contracts.
- Driver shortage concentration:Peninsular Malaysia faces acute skilled commercial driver deficits. Recruitment friction limits fleet expansion velocity despite equipment availability.
- Cross-border ASEAN fragmentation:Inconsistent customs protocols between Malaysia and Thailand's southern economic corridor create scheduling unpredictability. Documentation delays erode just-in-time delivery reliability.
Strategic Opportunities
- Johor Bahru-Singapore corridor specialization:Integrated warehousing and cross-border last-mile capabilities position operators for electronics and pharmaceutical cargo flows. CJ Logistics Corporation's infrastructure investments demonstrate viable scaling models.
- Telematics-AI convergence:Route optimization platforms combined with real-time fleet monitoring are reducing empty-mile ratios. Technology adopters capture efficiency premiums in contract negotiations.
- East Malaysia connectivity gaps:Sabah and Sarawak exhibit underdeveloped road freight density relative to manufacturing growth. Fleet deployment into Kuching and Kota Kinabalu corridors offers first-mover positioning.
Industry Challenges
- Euro 4-to-Euro 5 certification timelines:The Road Transport Department's inspection protocols create compliance backlogs. Fleet operators face operational disruption during mandatory vehicle upgrade windows.
- Legacy dispatch system integration:Paper-based consignment documentation persists among small and medium enterprise shippers. Digital platform adoption requires training investment that delays efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Road Freight Transport Market |
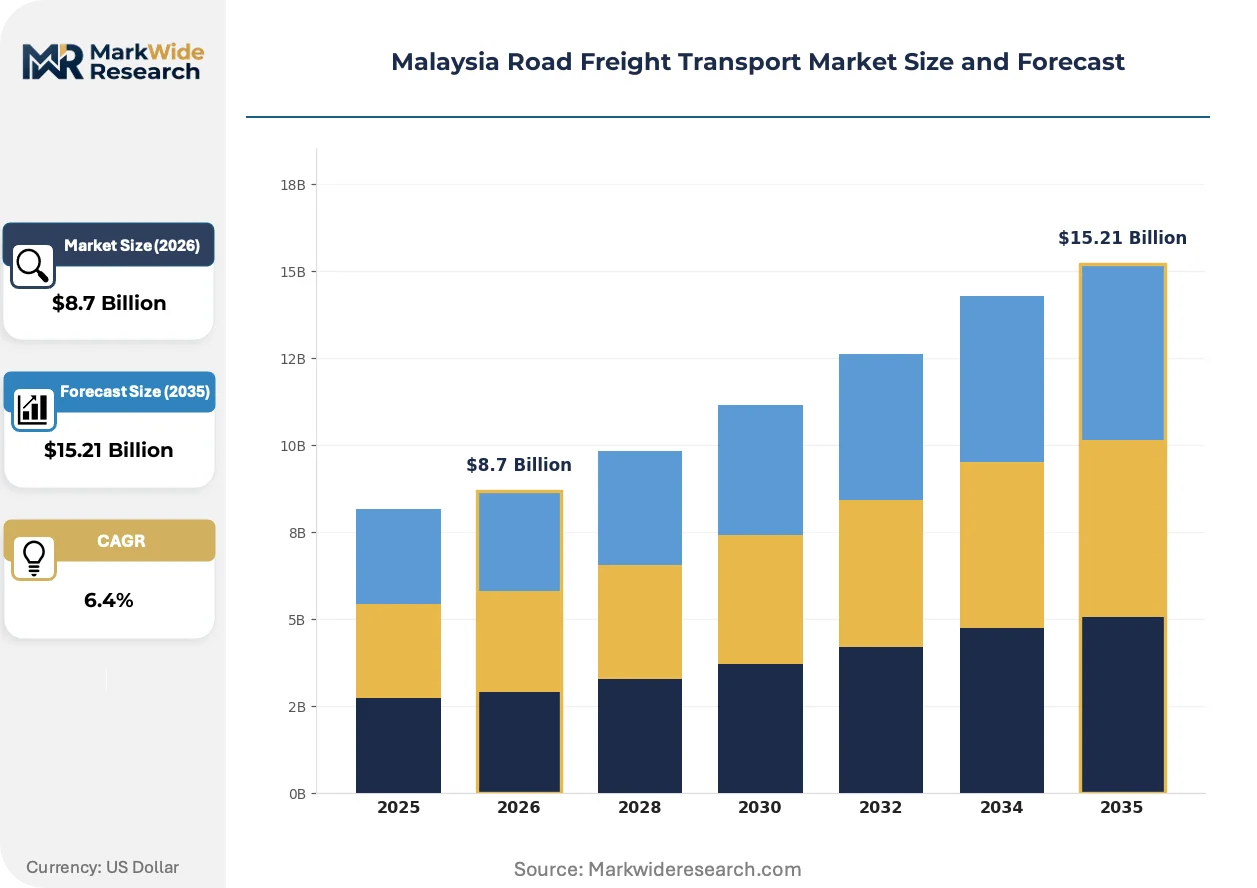
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trucks, Vans, Lorries, Buses Service Type: Full Truckload, Less Than Truckload, Express, Bulk Transport End User: Retail, Manufacturing, Agriculture, Construction Delivery Mode: Same Day, Next Day, Standard Ground, Scheduled |
| Companies Covered | Tiong Nam Logistics Holdings Bhd, CJ Logistics Corporation, DHL Group, Swift Haulage Berhad, Pos Logistics Bhd, DSV, Kuehne + Nagel, DB Schenker, NYK Line, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Road Freight Transport Market Shifts & Advancements
Digital infrastructure is compressing operational decision cycles across Malaysian fleet management. Technology deployment patterns reveal three distinct vectors reshaping competitive economics.
Telematics platforms combining GPS tracking with predictive maintenance algorithms are virtualizing fleet oversight functions. Large operators in the Klang Valley are deploying these systems across container haulage divisions. Real-time visibility into vehicle health and location is virtualizing traditional dispatch center operations and reducing manual intervention requirements.
The Department of Environment's Euro 5 emissions roadmap is mandating particulate filter retrofits and engine management upgrades. Heavy vehicle fleets face capital deployment decisions between retrofit compliance and full vehicle replacement. Diesel-powered units serving Port Klang corridors are prioritizing upgrade paths that maintain biodiesel blend compatibility.
Consolidation platforms are aggregating Less Than Truckload shipments from small and medium enterprises into optimized full-truckload rotations. Digital freight matching services displace traditional broker relationships in Selangor and Penang manufacturing belts. Electronics component suppliers exhibit the fastest adoption velocity, driven by inventory velocity requirements from contract manufacturers.
Malaysia Road Freight Transport Market Segmentation
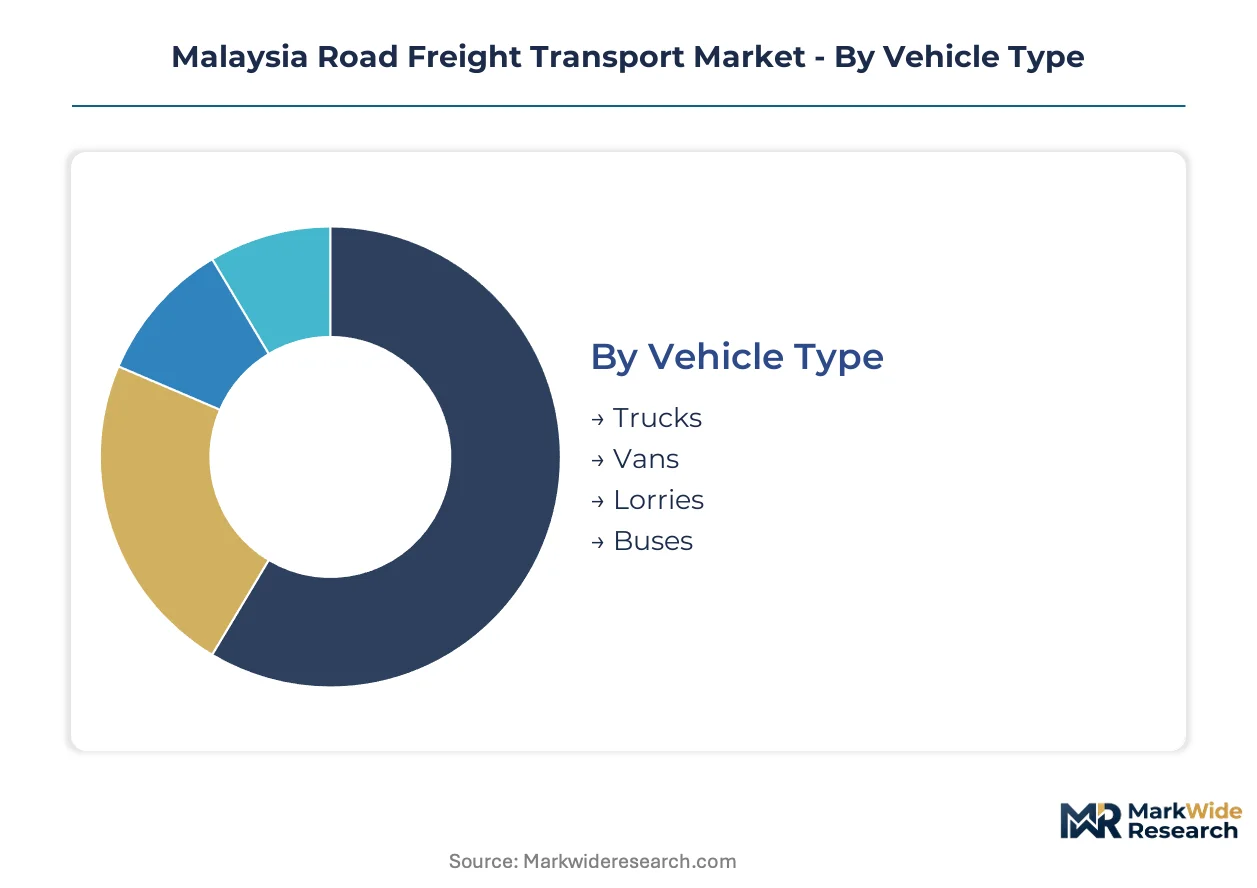
Malaysian fleet operators configure asset portfolios around cargo density patterns and service-level commitments. Segment boundaries determine maintenance scheduling intensity, fuel procurement strategies, and driver certification requirements across Peninsular Malaysia's logistics corridors.
Vehicle Type:
After-sales service intensity varies sharply across vehicle classes, with heavy diesel platforms demanding specialized biodiesel-compatible maintenance protocols.
- Trucks:Gross vehicle weights exceeding 12 tonnes dominate Port Klang container haulage and Klang Valley manufacturing belt operations. These units face the steepest compliance burden under the Department of Environment's Euro 5 transition timeline, accelerating replacement cycles in Selangor-based fleets.
- Vans:Light commercial vehicles below 3.5 tonnes handle last-mile e-commerce fulfillment from Shah Alam distribution centers. Cold-chain variants support temperature-sensitive pharmaceutical delivery across Johor Bahru-Singapore corridors, where CJ Logistics Corporation maintains dedicated van fleets for cross-border express services.
- Lorries:Medium-duty rigid trucks serve agricultural distribution networks connecting Pahang and Johor plantation zones to processing facilities. Palm oil cargo flows require corrosion-resistant chassis specifications and frequent undercarriage inspections due to acidic residue exposure.
- Buses:Converted or dedicated cargo buses support worker transport and light freight consolidation in East Malaysia's underdeveloped road networks. Sabah and Sarawak operators repurpose intercity bus chassis for mixed passenger-cargo services on Kota Kinabalu-Kuching corridors.
By volume, Trucks lead. By growth pace, Vans are expanding most quickly.
Service Type:
Cost tier differentiation separates asset-heavy full-fleet commitments from variable-cost brokerage arrangements favored by small and medium enterprises.
- Full Truckload:Dedicated vehicle allocation for single-shipper cargo dominates electronics component flows from Penang manufacturing zones to Port Klang. Contract manufacturers demand locked capacity during quarterly production ramps, penalizing carriers who fail bidirectional load optimization.
- Less Than Truckload:Shipment consolidation platforms aggregate fractional loads from multiple small and medium enterprise shippers into optimized rotations. Digital freight matching services displace traditional broker relationships in Selangor and Penang industrial belts.
- Express:Time-definite delivery with guaranteed windows commands premium pricing from pharmaceutical and electronics sectors. Next-day commitments require dedicated fleet segments with bypass authority at Port Klang customs checkpoints.
- Bulk Transport:Open-bed and tanker configurations handle construction aggregates, palm oil, and petroleum derivatives. B20 biodiesel mandate compliance adds fuel stability monitoring requirements for long-haul bulk operators.
Full Truckload captures the highest revenue concentration. Express delivery shows the steepest expansion trajectory.
End User:
Application-specific requirements dictate fleet specialization, with temperature control and security protocols varying by cargo category.
- Retail:E-commerce fulfillment centers in Selangor scale last-mile capacity to meet next-day delivery commitments from major retail platforms. Peak season volume surges require surge fleet partnerships with independent owner-operators.
- Manufacturing:Just-in-time component delivery from Penang and Johor Bahru industrial zones demands precise scheduling adherence. Electronics suppliers impose financial penalties for delivery window violations affecting production line continuity.
- Agriculture:Seasonal harvest peaks in Pahang and Kelantan create acute capacity shortages during palm oil and rubber collection windows. Perishable cargo requires rapid turnaround at collection points to prevent quality degradation.
- Construction:Heavy equipment and materials transport operates on project-based contracts with irregular demand patterns. Cement and steel movements from Port Klang to Greater Kuala Lumpur development sites anchor baseline revenue for specialized flatbed operators.
Manufacturing generates the most consistent year-round demand. Retail exhibits the most volatile seasonal spikes.
Delivery Mode:
Customer type stratification separates premium service tiers from economy ground options, with pricing power concentrated in time-definite segments.
- Same Day:Emergency and high-value cargo movements within Klang Valley metropolitan boundaries. Medical supplies and critical manufacturing components justify dispatch premiums for dedicated vehicle allocation.
- Next Day:Standard e-commerce fulfillment commitment across Peninsular Malaysia urban corridors. Shah Alam distribution centers position inventory to achieve morning delivery windows for afternoon customer availability.
- Standard Ground:Economical non-urgent freight with flexible delivery windows spanning two to five days. Small and medium enterprise shippers accept longer transit times for reduced per-kilometer rates.
- Scheduled:Recurring fixed-route services for manufacturing supply chains with predictable replenishment cycles. Electronics component suppliers utilize scheduled milk runs between contract manufacturers and assembly facilities.
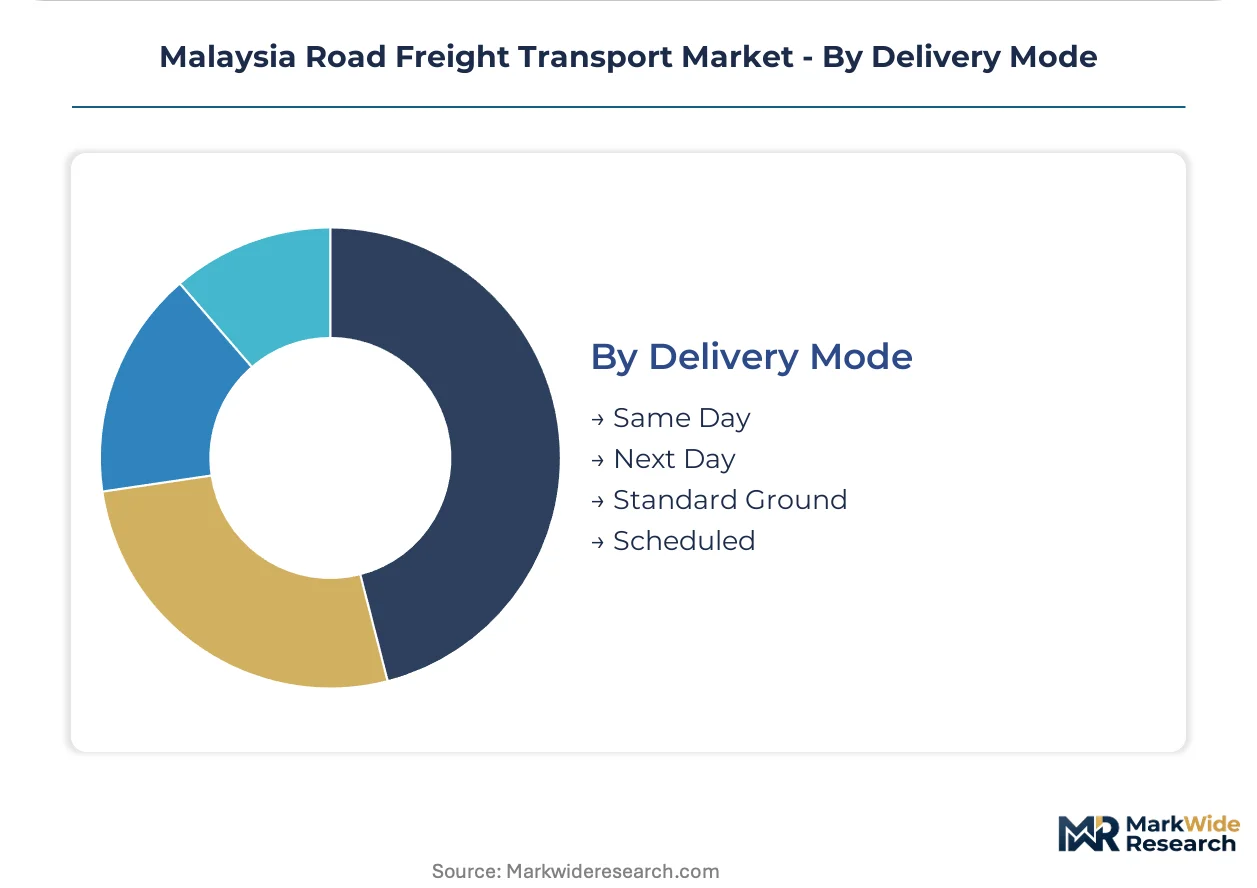
Standard Ground moves the highest cargo volume. Same Day commands the fastest adoption rate among premium service tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian road freight demand concentrates around manufacturing exporters in Peninsular Malaysia and resource extraction zones in East Malaysia, with logistics buyers prioritizing Port Klang connectivity and cross-border ASEAN access.
Selangor
Electronics contract manufacturers and e-commerce fulfillment centers drive fleet utilization across the Klang Valley. The Commercial Vehicles Licensing Board enforces route authority caps that limit new entrant expansion. Shah Alam distribution clusters anchor cold-chain investments for pharmaceutical and perishable cargo flows.
Johor
Cross-border electronics and pharmaceutical cargo to Singapore generate premium express demand. The Iskandar Malaysia development corridor attracts integrated warehousing investments from regional logistics operators. Johor Bahru industrial zones concentrate container haulage activity connecting to Tanjung Pelepas Port.
Penang
Semiconductor and medical device exporters require just-in-time delivery precision to Port Klang and Penang Port. The Department of Environment's Euro 5 timeline accelerates fleet renewal among electronics-focused carriers. Bayan Lepas and Kulim manufacturing belts generate consistent full-truckload contract volumes.
Pahang
Seasonal palm oil harvest peaks create acute capacity shortages across plantation-to-port corridors. The B20 biodiesel mandate shapes fuel procurement for agricultural haulage operators. Kuantan Port connections to the East Coast Rail Link project stimulate construction materials transport demand.
Sabah
Underdeveloped road density relative to manufacturing growth creates first-mover opportunities for fleet deployment. The federal government's Pan Borneo Highway upgrades improve Kota Kinabalu-Kuching corridor connectivity. Mixed passenger-cargo services persist on intercity routes where dedicated freight infrastructure remains limited.
Malaysia Road Freight Transport Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Malaysia's road freight sector, yielding a tiered structure where integrated logistics groups command premium contract terms while independent operators fill spot-market gaps. Consolidation pressure intensifies as telematics investments raise minimum efficient scale thresholds. Three archetypes dominate: asset-heavy fleet operators with owned warehousing, digital freight platforms aggregating fragmented capacity, and cross-border specialists leveraging ASEAN customs expertise. Competitive moves center on biodiesel-compatible fleet renewal and strategic partnerships with e-commerce fulfillment platforms.
Among Malaysia-based integrated operators, Tiong Nam Logistics Holdings Bhd and Swift Haulage Berhad occupy positions exemplifying cold-chain specialization and container haulage concentration respectively. CJ Logistics Corporation represents the multinational archetype, anchoring competitive positioning through Johor Bahru infrastructure investments. These three entities illustrate the strategic divergence between domestic fleet scale and cross-border network integration.
| Leading Market Players |
|---|
| Tiong Nam Logistics Holdings Bhd |
| CJ Logistics Corporation |
| DHL Group |
| Swift Haulage Berhad |
| Pos Logistics Bhd |
| DSV |
| Kuehne + Nagel |
| DB Schenker |
| NYK Line |
| Others |
Supply & Pricing Matrix
Overcapacity in Selangor-based container haulage fleets is compressing spot-market rates while reinforcing contract-rate premiums for dedicated capacity. Fleet operators respond by segmenting pricing tiers around fuel-indexed surcharges and biodiesel blend volatility, forcing buyers to choose between price certainty and operational flexibility.
Pricing Analysis
Cost-plus contracts with diesel price indexation dominate long-haul agreements between Port Klang and Klang Valley manufacturing zones. Three-tier pricing structure across premium express, standard scheduled, and economy deferred tiers separates time-definite commitments from flexible-window alternatives. Pricing pressure stems from palm oil cost volatility affecting B20 procurement economics, with small and medium enterprise shippers exhibiting highest price sensitivity due to thin inventory margins.
Supply Chain Analysis
Extended payment terms from electronics contract manufacturers in Penang and Selangor are straining working capital for mid-tier fleet operators, accelerating supply-chain finance facility adoption. Vehicle manufacturing draws from Japan, China, and Thailand for chassis and engine platforms, while biodiesel feedstock rests on domestic palm oil production. Single-source vulnerability concentrates in Euro 5-compliant engine management systems from European suppliers. Distribution runs through manufacturer-authorized service networks anchored in Shah Alam and Johor Bahru.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's road freight sector presents a defensive-moat opportunity anchored in regulatory entrenchment. The Commercial Vehicles Licensing Board's route authority caps create artificial scarcity that protects incumbent fleet utilization rates.
For Market Incumbents: Insulate contract renewal rates by embedding telematics-AI platforms that raise switching costs for manufacturing shippers. Deepen backward integration into cold-chain warehousing in Shah Alam to capture pharmaceutical margin pools. The Euro 5 transition timeline threatens smaller competitors with compliance capital burdens, favoring scale-driven fleet renewal programs. For New Entrants and Emerging Players: Establish a beachhead in East Malaysia's Kota Kinabalu-Kuching corridor where road freight density lags manufacturing growth. Target agricultural haulage in Pahang and Kelantan plantation zones with corrosion-resistant lorry specifications. A digital freight-matching platform aggregating independent owner-operators offers the most penetrable entry vector against asset-heavy incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated logistics operators with dedicated warehousing and cross-border ASEAN capabilities. Long-term viability favors asset-heavy models with biodiesel-compatible fleet scale and Johor Bahru-Singapore corridor positioning. Watch for B20 mandate escalation as an inflection signal that would compress margins for non-compliant operators and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-AI Platform Deployment | Route optimization algorithms reduce empty-mile ratios for Port Klang container haulage operators. |
| Cold-Chain Infrastructure Expansion | Shah Alam pharmaceutical distribution clusters capture temperature-sensitive cargo premiums from medical device exporters. |
| Euro 5 Fleet Renewal Program | Engine upgrade cycles displace smaller competitors lacking capital access for compliance investments. |
| Cross-Border ASEAN Partnership | Johor Bahru-Singapore corridor integration secures electronics and pharmaceutical express delivery contracts. |
| Digital Freight Matching Launch | Aggregation platforms displace traditional brokers in Selangor and Penang manufacturing belts. |
Research Methodology
The analysis maps full-truckload, less-than-truckload, and express delivery segments, each validated through fleet operations directors, logistics procurement managers at electronics manufacturers, cold-chain facility operators, and Commercial Vehicles Licensing Board officials. Primary interviews combined with secondary validation from Road Transport Department inspection records, Department of Environment emissions compliance filings, Port Klang container throughput statistics, and customs trade data. Bottom-up fleet capacity estimates triangulated against top-down manufacturing output projections.
Assumptions held fixed include B20 biodiesel mandate adherence and Euro 5 transition timelines, while palm oil price trajectories and cross-border ASEAN customs efficiency were varied across scenarios. Segmentation dimensions modeled encompass vehicle type, service tier, end-use industry, and delivery mode across the projection horizon. CAGRs derived from equipment replacement cycles, e-commerce fulfillment growth curves, and manufacturing export velocity trends. Forecast inputs included fleet utilization rates by corridor and driver shortage severity indices.
Sensitivities concentrate around palm oil price volatility affecting fuel procurement economics and cross-border customs protocol harmonization between Malaysia and Thailand. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and infrastructure investment continuity. Macroeconomic contraction, emissions standard acceleration, or telematics disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Empty Container Repositioning Optimization Platforms Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Renewable Resources Logistics Market
Logistics and Shipping
Japan Logistics Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market