
 Global Courier Market | 2026-2036
Global Courier Market Size, Share, and Industry Trends Forecast 2026-2036
Global Courier Market Analysis
EU Green Deal emissions benchmarks is rebalancing the cost-of-entry calculus for fleet operators across Europe, forcing capital reallocation toward electric vans and carbon accounting infrastructure. DHL Express anchors its European network with dedicated electric vehicle hubs in Germany and the Netherlands. FedEx Corporation navigates these compliance layers by integrating renewable energy into its sortation facilities. SF Express dominates intra-Asia express corridors with proprietary freighter capacity and automated mega-hubs in Shenzhen and Hangzhou.
A courier operation encompasses the collection, sortation, line-haul transport, and last-mile delivery of parcels and documents, typically governed by service-level agreements specifying transit-time windows, tracking granularity, and liability limits for loss or damage. Its commercial purpose centers on enabling time-definite exchange of goods between businesses and consumers across distributed geographies. Express delivery commands premium pricing and captures the dominant share of profit pools, while same-day delivery represents the fastest-expanding service tier as urban density and micro-fulfillment networks mature. The B2C delivery model now generates the highest volume growth, though B2B contracts still sustain superior margin stability through contracted lanes and predictable freight profiles.
FAA regulations in the United States restrict beyond-visual-line-of-sight drone operations, constraining autonomous last-mile deployment until type certification pathways mature for commercial unmanned aircraft. EASA's U-space framework in Europe creates a more structured airspace integration model, enabling earlier regulatory clarity for drone corridor networks. China's CAAC has granted operational licenses for drone delivery in designated low-altitude zones, accelerating real-world deployment data. Stakeholders must monitor which regulator moves first on scalable autonomous certification, as this will determine where capital for next-generation delivery infrastructure concentrates.
Market Dynamics
E-commerce merchants are compressing delivery windows from 48-hour to same-day service, forcing fleet operators to reconfigure hub-and-spoke networks into distributed micro-fulfillment architectures with electrified last-mile assets.
Growth Catalysts
- EU Green Deal emissions mandates:Fleet operators across Germany, the Netherlands, and France must electrify delivery vans and install carbon accounting infrastructure, accelerating capital deployment into zero-emission vehicles.
- Cross-border e-commerce corridors:Chinese export merchants are scaling automated sortation and dedicated freighter capacity to serve Southeast Asian and European consumer markets with time-definite delivery.
- Drone corridor licensing:China's CAAC has designated low-altitude zones for commercial unmanned aircraft operations, generating real-world deployment data that refines autonomous delivery economics.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing and cell manufacturing cluster in China, exposing European and North American fleet electrification timelines to geopolitical supply risk.
- FAA beyond-visual-line-of-sight restrictions:United States regulators have not certified commercial unmanned aircraft for autonomous last-mile deployment, constraining drone network scaling until type certification pathways mature.
- Urban real estate scarcity:Micro-fulfillment hubs require last-touch warehouse space in dense metropolitan cores where industrial zoning and land costs limit network expansion.
Strategic Opportunities
- Rural drone penetration:India's Ministry of Civil Aviation is liberalizing low-altitude airspace for cargo drones, opening last-mile networks where road infrastructure remains underdeveloped.
- Carbon accounting software integration:The EU's CSRD mandates granular emissions disclosure across supply chains, creating demand for route optimization platforms that calculate per-shipment carbon intensity.
- Autonomous vehicle-roadside infrastructure convergence:Fleet operators partnering with smart city authorities in Singapore and Dubai are testing curb management systems that reserve dedicated loading zones for electric delivery robots.
Industry Challenges
- Electrical technician shortage:Fleet maintenance operations lack personnel certified on high-voltage van powertrains, extending vehicle downtime and compressing asset utilization rates.
- Legacy warehouse management system integration:Automated sortation hardware from Chinese and European vendors requires custom API development to synchronize with incumbent software platforms, delaying hub modernization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Courier Market |
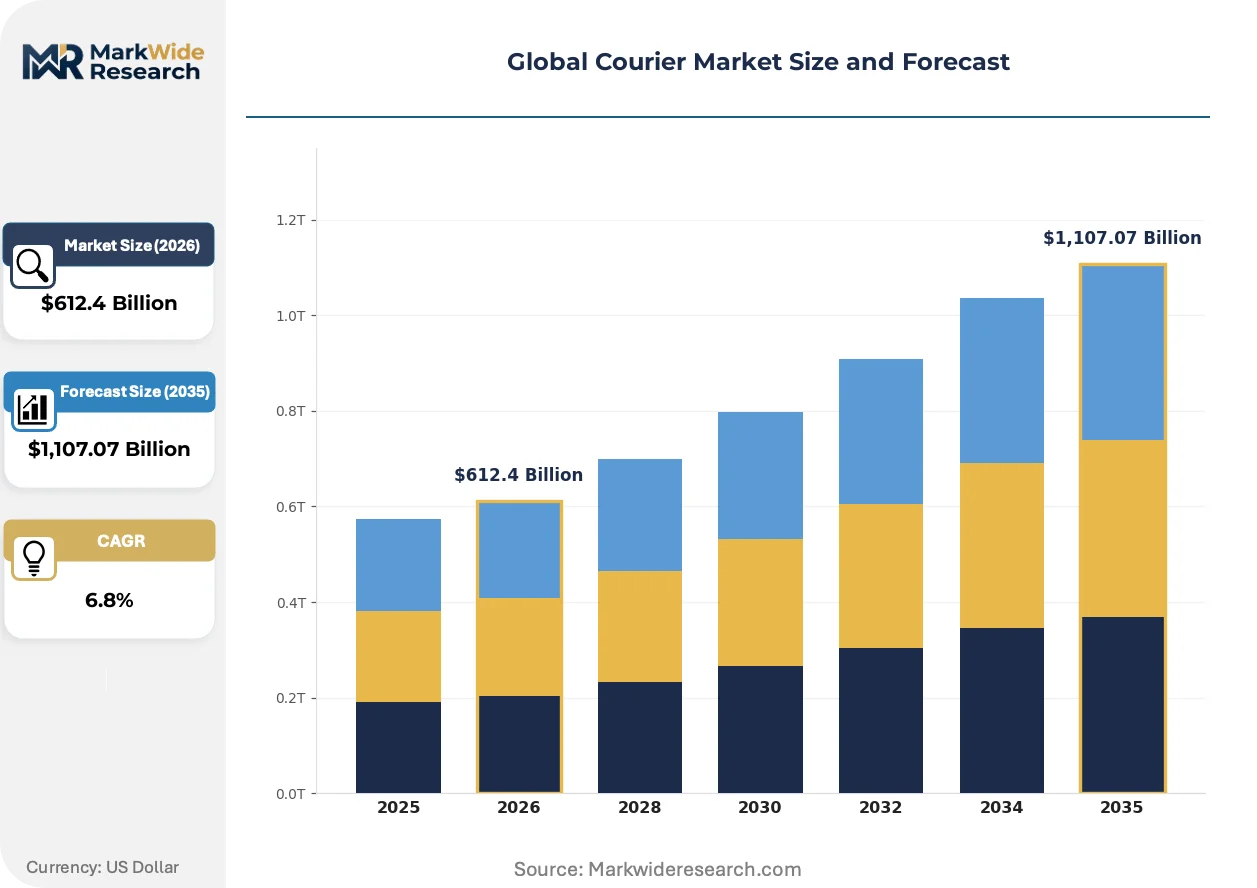
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,107.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Standard Delivery, Same-Day Delivery, International Shipping Vehicle Type: Motorcycle, Van, Truck, Drone Delivery Model: B2B, B2C, C2C, Hybrid Packaging Type: Boxes, Envelopes, Pallets, Crates |
| Companies Covered | SF Express, DB Schenker, DHL Express, Japan Post Group, Yamato Holdings, FedEx Corporation, Aramex, Blue Dart Express, United Parcel Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Courier Market Emerging Trajectories
Autonomous sorting robotics, electrified last-mile fleets, and regulatory frameworks for unmanned aerial delivery are converging to redefine operational economics and service-level capabilities across express networks.
Autonomous mobile robots equipped with computer vision and pneumatic grasping systems are expanding into high-throughput parcel sortation facilities. E-commerce fulfillment centers in Shenzhen and Rotterdam are deploying these units to handle irregular package dimensions without mechanical reconfiguration. This technology is expanding into mid-sized regional hubs previously constrained by labor availability and shift-based throughput ceilings.
The EU Green Deal's F-Gas Regulation is phasing down hydrofluorocarbon use in refrigerated transport units, compelling cold-chain courier operators to adopt CO2-based cooling systems or electric refrigeration. Pharmaceutical and fresh-food delivery segments face the steepest compliance costs due to temperature-validated service requirements. German and Dutch fleet operators are responding by consolidating refrigerated loads onto dedicated electric routes with solar-powered depot charging.
Urban consumers are consolidating purchases into fewer, larger orders to qualify for free shipping thresholds, compressing delivery density and forcing route optimization algorithms to prioritize drop-size over drop-frequency. Grocery and general merchandise e-commerce platforms in London and Tokyo are absorbing the margin impact through membership subscription models. This behavioral shift is most visible in dense Asian metropolitan markets where apartment building concierge systems enable centralized reception of consolidated shipments.
Global Courier Market Segmentation
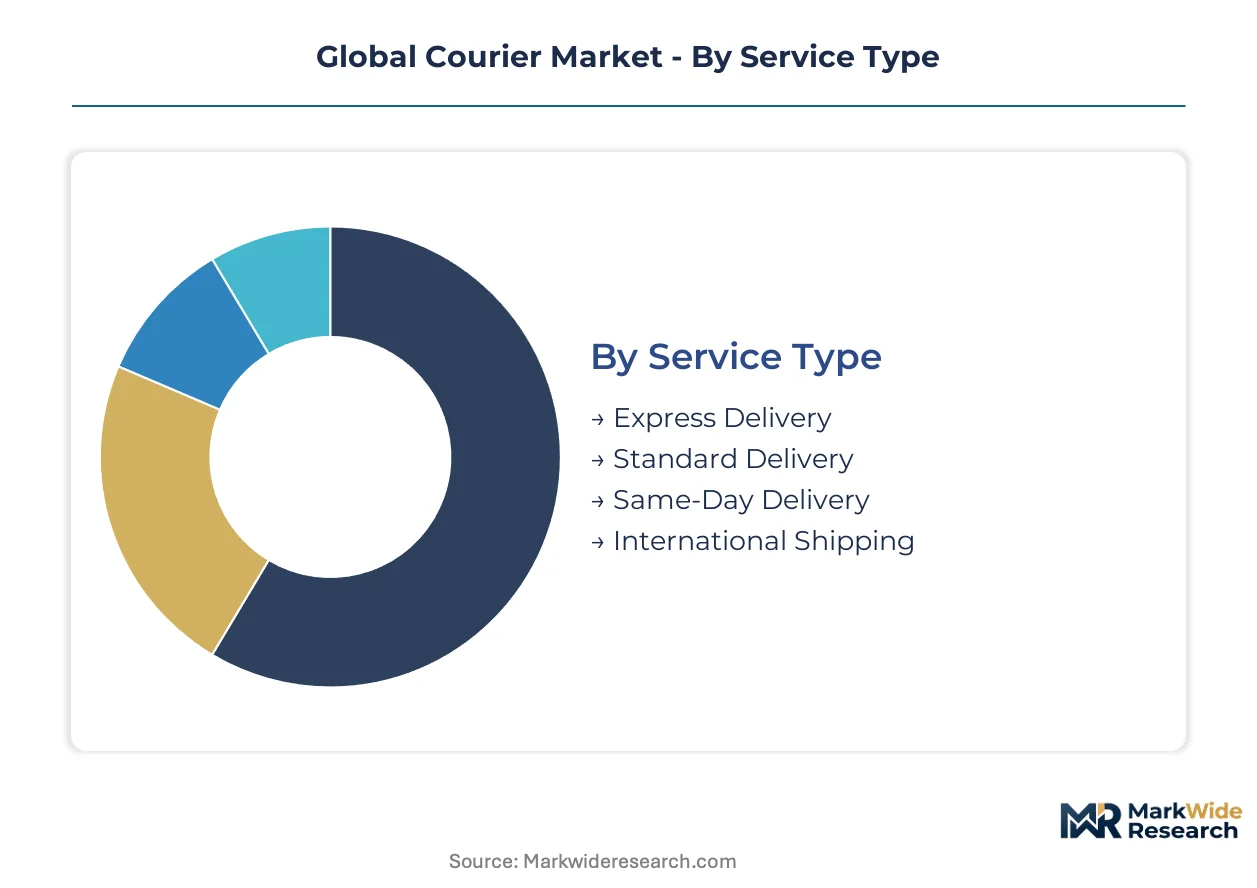
Courier market segmentation reveals how capital allocation and operational complexity concentrate across service tiers and vehicle platforms. Understanding these divisions exposes where margin compression and technology substitution are reshaping competitive economics.
Service Type:
Supply concentration in premium express networks has created asymmetric infrastructure investment, with automated hubs and dedicated freighter capacity clustering around time-definite service guarantees.
- Express Delivery:Time-definite transit with guaranteed delivery windows and end-to-end tracking granularity. Pharmaceutical distributors and high-value electronics manufacturers in Germany and the Netherlands anchor demand for temperature-validated express corridors.
- Standard Delivery:Non-guaranteed transit typically spanning 48-72 hours with basic tracking. E-commerce fulfillment platforms absorb volume here, though margin pressure from free-shipping thresholds compresses per-unit economics.
- Same-Day Delivery:Micro-fulfillment networks with urban dark stores and electrified last-mile fleets. Grocery and quick-commerce operators in London and Tokyo are scaling this tier through membership subscription models.
- International Shipping:Cross-border customs brokerage with harmonized tariff classification and duty-deferred clearance. Chinese export merchants leverage dedicated freighter capacity into Southeast Asian consumer markets.
Today's leader: Express Delivery. Tomorrow's challenger: Same-Day Delivery.
Vehicle Type:
Cost tier stratification across vehicle platforms determines fleet electrification sequencing, with battery economics and regulatory mandates driving divergent replacement timelines.
- Van:Last-mile workhorse for parcel densities above 50 stops per route. EU Green Deal emissions benchmarks are accelerating electric van deployment across German and Dutch depot networks.
- Drone:Autonomous aerial platforms for low-altitude cargo corridors. China's CAAC has designated operational zones generating real-world deployment data that refines autonomous delivery economics.
- Motorcycle:Two-wheel platforms navigating dense urban cores with minimal parking constraints. Southeast Asian courier networks rely on motorcycle fleets for informal address penetration.
- Truck:Line-haul and palletized freight for B2B contract logistics. Refrigerated truck fleets face F-Gas Regulation compliance costs as CO2-based cooling systems replace hydrofluorocarbon units.
Van platforms dominate capital deployment today. Drone networks represent the steepest expansion trajectory as airspace integration frameworks mature.
Delivery Model:
Customer type concentration determines contract structure stability, with predictable freight profiles commanding superior margin protection against spot-market volatility.
- B2B:Contracted lanes with scheduled pickups and dedicated account management. Manufacturing supply chains and pharmaceutical distributors sustain this segment through multi-year service agreements.
- B2C:On-demand parcel collection with residential address variability. E-commerce volume growth concentrates here, though last-mile density challenges erode per-stop profitability.
- C2C:Peer-to-peer shipment facilitation through digital marketplace integration. Informal sellers on cross-border platforms drive intermittent volume without predictable routing patterns.
- Hybrid:Integrated models serving both commercial and residential endpoints from shared sortation infrastructure. Retailers with omnichannel fulfillment requirements favor this flexibility.
B2B contracts anchor margin stability. B2C volume is climbing the fastest as consumer delivery expectations compress toward same-day service.
Packaging Type:
Application-driven packaging specifications determine sortation automation compatibility and damage liability allocation across the handling chain.
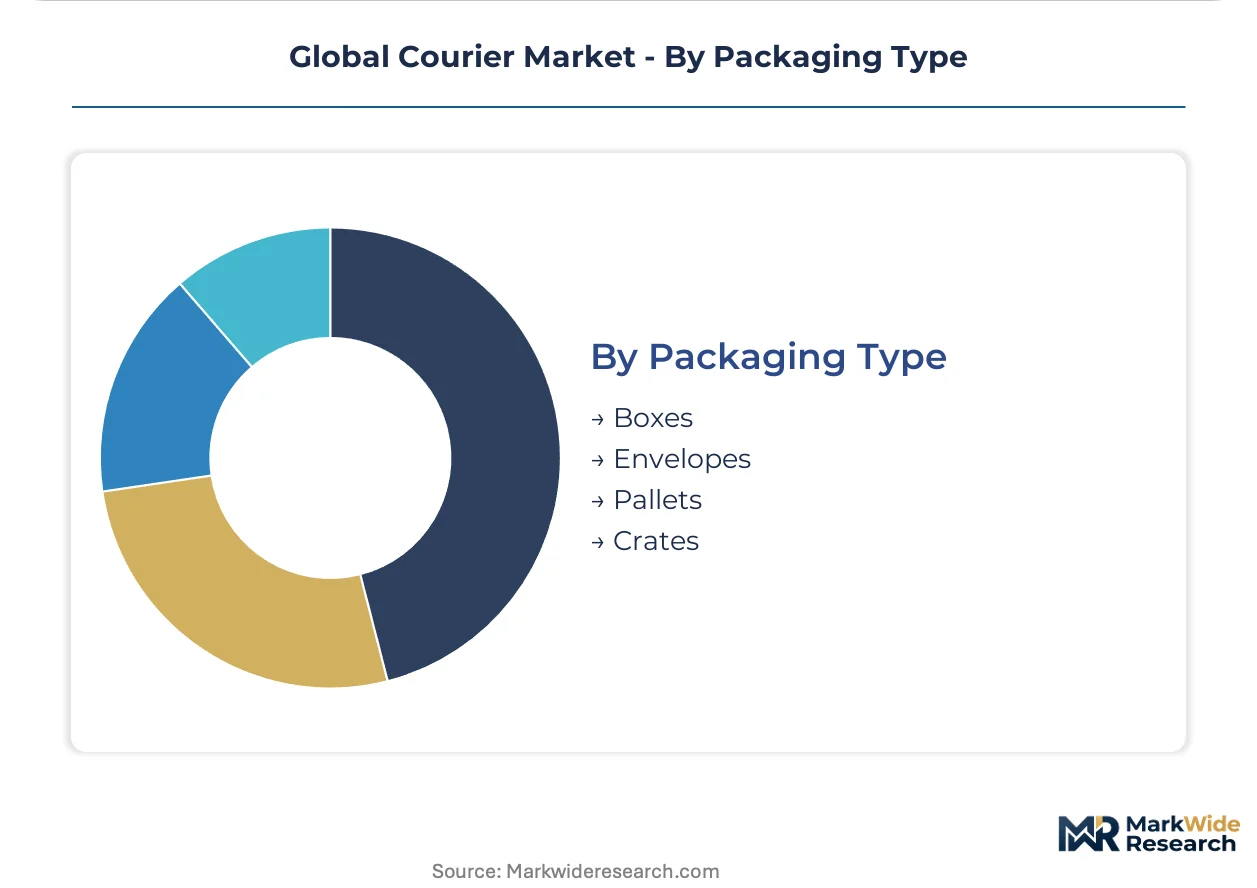
- Boxes:Corrugated containers protecting general merchandise through automated sortation systems. E-commerce fulfillment centers in Shenzhen deploy computer-vision-guided robotics for irregular dimension handling.
- Envelopes:Document and small-item pouches with minimal dimensional weight penalties. Financial services and legal sectors sustain demand for tamper-evident envelope tracking.
- Pallets:Unitized freight for B2B contract logistics with forklift-compatible handling. Manufacturing inbound supply chains require palletized consolidation for warehouse receiving efficiency.
- Crates:Reusable rigid containers for high-value or temperature-sensitive shipments. Pharmaceutical cold-chain operators utilize insulated crates with validated thermal mass properties.
Boxes capture the dominant volume share. Envelopes face structural displacement as document digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Courier workforce concentration clusters around three distinct talent pools: European electric vehicle technicians, Chinese automation engineers, and American logistics data scientists. These specialized labor markets anchor regional competitive positioning. Regulatory divergence across aviation authorities and emissions frameworks is fragmenting deployment timelines for next-generation delivery infrastructure.
United States
E-commerce fulfillment demand from Amazon, Walmart, and Target compresses delivery windows toward same-day service. FAA beyond-visual-line-of-sight restrictions constrain drone network scaling until commercial unmanned aircraft certification pathways mature. FedEx Corporation anchors its Memphis super-hub with automated sortation and dedicated freighter capacity serving domestic express corridors.
China
Cross-border e-commerce exports to Southeast Asia and Europe drive volume concentration in automated mega-hubs. CAAC drone corridor licensing in designated low-altitude zones generates real-world autonomous deployment data. Shenzhen and Hangzhou host SF Express proprietary freighter operations and computer-vision-guided robotics facilities.
Germany
EU Green Deal emissions mandates force fleet electrification and carbon accounting infrastructure deployment. DHL Express operates dedicated electric vehicle hubs with solar-powered depot charging networks. The Rhine-Ruhr industrial corridor concentrates refrigerated pharmaceutical logistics requiring F-Gas Regulation compliance.
India
Blue Dart Express and domestic competitors scale last-mile networks where road infrastructure remains underdeveloped in rural hinterlands. Ministry of Civil Aviation liberalization of low-altitude airspace for cargo drones opens penetration pathways. Mumbai and Delhi-NCR anchor B2C volume growth from quick-commerce and grocery platforms.
Japan
Yamato Holdings and Japan Post Group sustain aging-population logistics through contracted B2B lanes with predictable freight profiles. METI standards for autonomous vehicle-roadside infrastructure convergence guide smart city pilot programs. Tokyo-Osaka corridor concentrates same-day delivery density through membership subscription models.
Global Courier Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across service tiers and geographic footprints. The vendor base stratifies into three tiers: integrated global networks with dedicated air cargo capacity, regional specialists with dense last-mile coverage, and technology-forward disruptors deploying autonomous assets. Strategic moves concentrate on electrification partnerships with vehicle OEMs and API integration with e-commerce platforms. M&A activity targets last-mile density in urban cores and cross-border customs brokerage capabilities.
Within the integrated global network tier, DHL Express, FedEx Corporation, and United Parcel Service anchor competitive positioning through dedicated freighter fleets and automated hub infrastructure. These Germany-based and US-based entities exemplify scale-driven consolidation across express, standard, and international shipping segments. Their archetype represents capital-intensive network economics where route density and aircraft utilization rates determine margin sustainability against regional specialists.
| Leading Market Players |
|---|
| SF Express |
| DB Schenker |
| DHL Express |
| Japan Post Group |
| Yamato Holdings |
| FedEx Corporation |
| Aramex |
| Blue Dart Express |
| United Parcel Service |
| Others |
Supply Flow & Price Mechanics
Cross-border e-commerce merchants in China and Southeast Asia anchor demand for time-definite express services, driving a pricing model that bundles guaranteed transit windows with carbon accounting disclosure. This buyer concentration forces tiered service structures where premium express corridors command sustained margins while standard delivery faces compression from free-shipping thresholds.
Pricing Analysis
Bundled service packages combining express transit, tracking granularity, and liability coverage dominate enterprise contracts, while unbundled per-shipment pricing persists in spot-market B2C transactions. Three-tier pricing structure across premium express, standard parcel, and economy deferred tiers separates pharmaceutical distributors from e-commerce fulfillment platforms. Cost compression in standard delivery is intensifying because merchants absorb shipping fees to meet consumer expectations, eroding per-unit economics. Quick-commerce operators show least price sensitivity due to membership subscription models, while informal C2C sellers on cross-border platforms resist any premium above economy rates.
Supply Chain Analysis
Dual-sourcing requirements for lithium-ion battery cells and cathode materials now feature in European fleet operator procurement mandates, reducing exposure to single-origin supply disruption. Cell manufacturing concentrates in China, South Korea, and Japan, while automated sortation hardware production clusters in China and Germany. Supply chains draw from rare earth processing facilities for electric motor magnets and semiconductor fabs for autonomous vehicle compute modules. Single-source vulnerability in Chinese cathode material refining poses structural risk to electrification timelines. Distribution runs through dedicated electric vehicle hubs with solar-powered depot charging in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
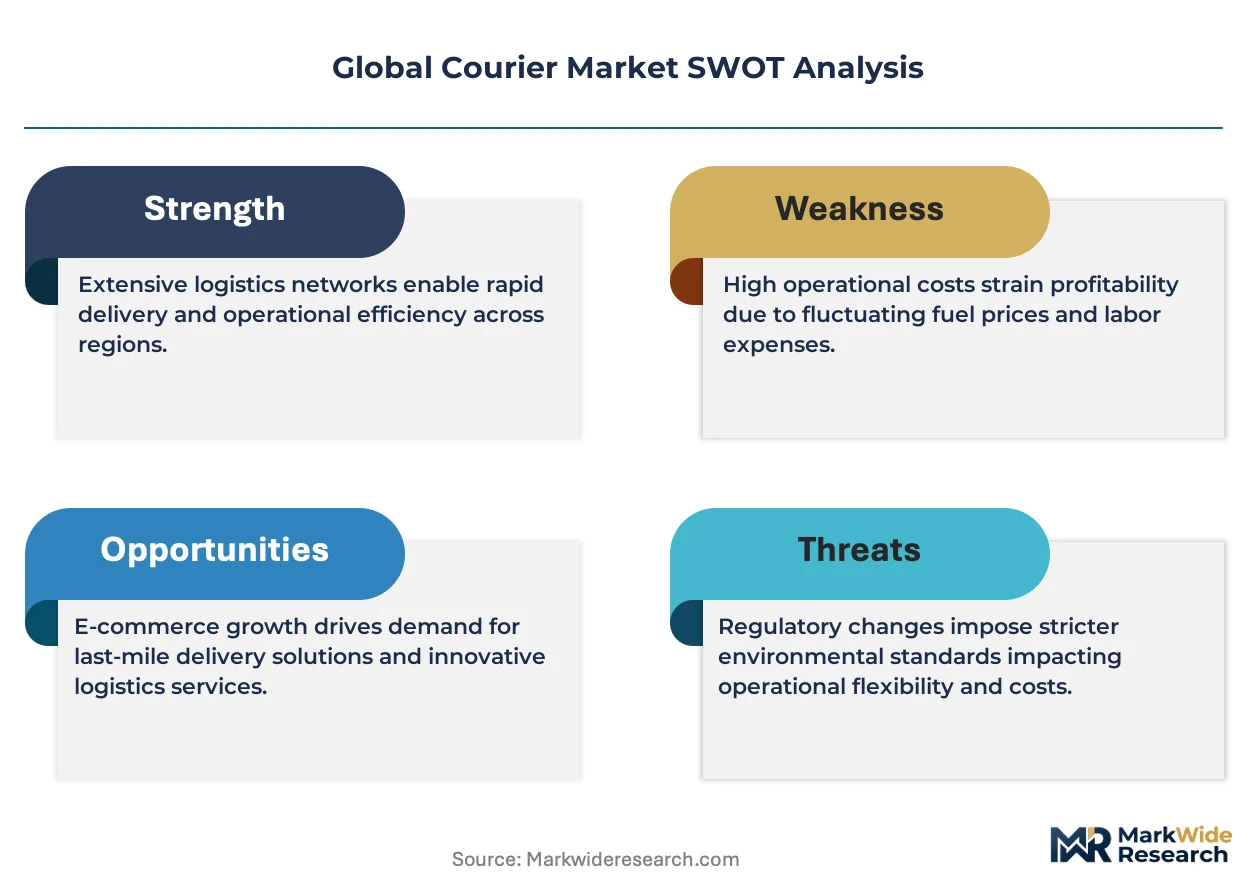
Fleet electrification and automated sortation deployment represent parallel margin-expansion vectors, with EU Green Deal compliance costs already capitalized by integrated operators while regional specialists absorb ongoing retrofit burdens.
For Market Incumbents: Lock in dedicated freighter capacity and automated hub infrastructure to defend against technology-forward disruptors deploying autonomous aerial assets. Prioritize backward integration into electric vehicle maintenance networks to address certified electrical technician scarcity. Secure long-term battery supply agreements with dual-source qualification to mitigate lithium-ion cell concentration risk. For New Entrants and Emerging Players: Enter via rural drone penetration in India where Ministry of Civil Aviation liberalization opens low-altitude cargo corridors underserved by road infrastructure. Target quick-commerce same-day delivery in dense Asian metropolitan markets where micro-fulfillment density remains below saturation. Pursue carbon accounting software integration as a service layer atop existing fleet operator relationships. For Investors and Strategic Acquirers: E-commerce platform operators are the most active acquirer in this space, seeking captive last-mile capacity to control delivery experience and data. Long-term viability favors operators with integrated air cargo networks and regulatory clarity on autonomous certification. Acquisition target archetype: regional specialists with dense urban last-mile coverage and pending drone corridor licenses. Watch FAA beyond-visual-line-of-sight rulemaking as the inflection signal for North American autonomous deployment scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | DHL Express anchors German network with dedicated EV hubs meeting EU Green Deal benchmarks. |
| Autonomous Sortation Deployment | SF Express deploys computer-vision robotics in Shenzhen facilities handling irregular package dimensions. |
| Drone Corridor Licensing | CAAC-designated low-altitude zones in China generate real-world autonomous delivery economics data. |
| Carbon Accounting Integration | CSRD-mandated emissions disclosure creates demand for route optimization platforms calculating per-shipment intensity. |
| Micro-Fulfillment Network Expansion | Quick-commerce operators in Tokyo and London scale dark-store density through membership subscription models. |
Methodological Framework
Bottom-up e-commerce merchant modeling reconciled against top-down fleet operator capacity tracking forms the analytical core of this study. Primary interviews with express network planners, electric vehicle procurement leads, aviation regulatory affairs specialists, and last-mile operations directors combined with secondary validation from customs trade databases, SEC filings of listed logistics operators, EU emissions registry disclosures, and CAAC regulatory bulletins. Triangulation across shipment volume data, fleet composition reports, and air cargo capacity filings ensures cross-source consistency.
Historical trendline analysis of express parcel volumes, fleet electrification capex cycles, and autonomous technology deployment timelines informed the projection framework. Segmentation modeling spans service tier, vehicle platform, delivery model, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to bottom-up volume build-ups and top-down market sizing reconciliation. Industry-specific inputs include EU Green Deal compliance cost curves, lithium-ion battery price trajectories, and drone certification pathway maturity assessments.
Inputs from aviation regulators, fleet operators, and e-commerce platforms were available through the study window; gaps in real-world autonomous deployment cost data introduce uncertainty bands around drone network scaling assumptions. Forecasts reflect documented assumptions on regulatory timeline acceleration, battery chemistry cost reduction, and urban real estate availability for micro-fulfillment siting. Deviation in FAA or EASA unmanned aircraft certification schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
Iraq Air Freight Transport Market
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Shipping Supplies Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Freight and Logistics Market