
 Kuwait Used Car Market | 2026-2036
Kuwait Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Used Car Market Insights
The gap between certified pre-owned vehicles and unverified private-sale units is shifting transaction flows toward structured channels. Alghanim Automotive leverages its multi-brand service infrastructure to anchor buyer confidence in higher-mileage inventory. Al-Mulla Group competes through geographic dominance across Jahra and Farwaniya showroom clusters. YallaMotor.com controls digital discovery, capturing search-to-visit conversion through integrated financing pre-qualification tools.
A used car is a previously registered vehicle sold through secondary channels, typically evaluated by age, odometer reading, structural integrity, and maintenance traceability before re-entry into circulation. Its commercial purpose centers on value recovery for original owners and affordable mobility access for subsequent buyers. SUV inventory under five years commands the strongest margin pools due to family-size utility preferences and residual value stability. Petrol powertrains still dominate transaction volume, though hybrid entries are gaining fastest in certified channels where battery health verification protocols exist. Age categories between five and ten years represent the most liquid segment, balancing depreciation absorption against remaining service life.
Kuwait's Ministry of Interior traffic department enforces mandatory technical inspection certificates, filtering unsafe units from formal resale pathways. The Central Agency for Information Technology oversees digital marketplace compliance, including identity verification and transaction record retention. Kuwait's Consumer Protection Authority monitors warranty claim disputes on certified pre-owned sales, pressuring dealers to standardize condition grading. Stakeholders must monitor how battery health certification protocols evolve as electrified used inventory expands beyond negligible share.
Market Dynamics
Certified pre-owned channels are consolidating transaction flows as Kuwait's Ministry of Commerce and Industry enforces stricter odometer disclosure mandates, compressing private-sale volume toward structured dealership networks.
Growth Catalysts
- Financing accessibility expansion:Banking partnerships now extend installment coverage to five-year-old SUVs, pulling first-time buyers from cash-only segments into formal credit channels.
- Kuwait Consumer Protection Authority warranty standardization:Mandatory condition grading for certified inventory elevates price transparency, reducing buyer hesitation on higher-mileage units.
- Hybrid battery health protocols:Technical verification frameworks for electrified powertrains unlock certified-channel acceptance of Toyota and Honda hybrid SUVs previously relegated to informal sales.
Market Restraints
- Petrol price volatility:Subsidy adjustments at Kuwait Petroleum Corporation alter total-cost-of-ownership calculations, compressing demand for V6 and V8 SUV segments during price spikes.
- Inspection certificate bottlenecks:Ministry of Interior traffic department capacity constraints create two-week processing delays, freezing inventory turnover during peak registration periods.
- Substitution from ride-hailing:Careem and Uber fleet expansion in Kuwait City reduces necessity-driven vehicle ownership among young professionals in Salmiya corridors.
Strategic Opportunities
- Jahra governorate penetration:Al-Mulla Group showroom clusters demonstrate unmet demand density; digital platforms lack last-mile service infrastructure in this corridor.
- Integrated financing pre-qualification:Search-to-visit conversion tools on automotive portals compress decision cycles, capturing buyers before dealership contact.
- Battery health certification tailwind:Central Agency for Information Technology marketplace compliance rules create first-mover advantage for dealers verifying electrified powertrain condition.
Industry Challenges
- Technical inspection talent scarcity:Ministry of Interior-certified assessor training programs lag vehicle volume growth, creating inspection-quality variance across governorates.
- Legacy DMS integration friction:Dealership management systems from the 2010s resist API connectivity with YallaMotor.com and competing digital platforms, fragmenting inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Used Car Market |
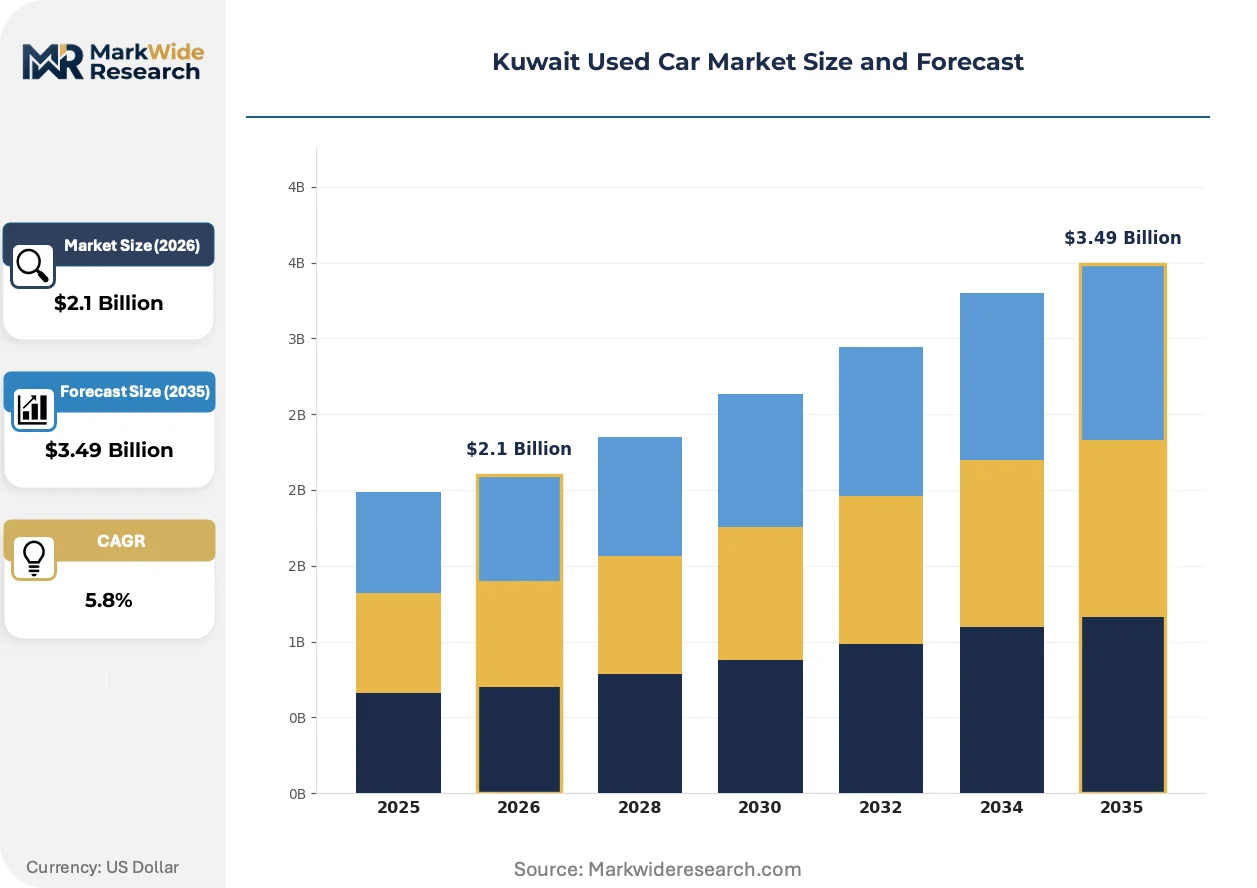
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Age Category: Less than 5 years, 5 to 10 years, 10 to 15 years, More than 15 years Condition: Certified Pre-Owned, Good, Fair, Needs Repair |
| Companies Covered | Alghanim Automotive, Al-Mulla Group, Al-Sayer Group, Al-Futtaim Motors, Al-Mansour Automotive, Al-Jazeera Automotive, Al Babtain Group, YallaMotor.com, Dubizzle Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Used Car Market Trends and Innovations
Digital discovery layers are fusing with financing infrastructure, reshaping how Kuwaiti buyers locate, validate, and fund pre-owned vehicle acquisitions without physical showroom visitation.
Artificial intelligence-driven condition scoring is integrating into certified pre-owned workflows. Computer vision systems assess exterior damage and tire wear from uploaded imagery, compressing initial valuation from days to hours. Young professionals in Salmiya leverage these tools to pre-screen inventory before scheduling inspections, reducing unproductive dealership visits by half.
Kuwait's Ministry of Commerce and Industry tightened odometer disclosure requirements through amended commercial agency regulations, criminalizing rollback documentation. Dealers now face license suspension for verified violations, forcing investment in blockchain-verified service history integration. SUV inventory under three years experiences the steepest compliance cost escalation.
Certification-driven preference shifts concentrate transaction gravity in structured channels. Buyers increasingly filter search results by warranty availability, excluding private sellers from consideration sets regardless of price advantage. This behavior compresses price discovery efficiency in Jahra and Farwaniya, where informal sales previously dominated volume.
Kuwait Used Car Market Segmentation
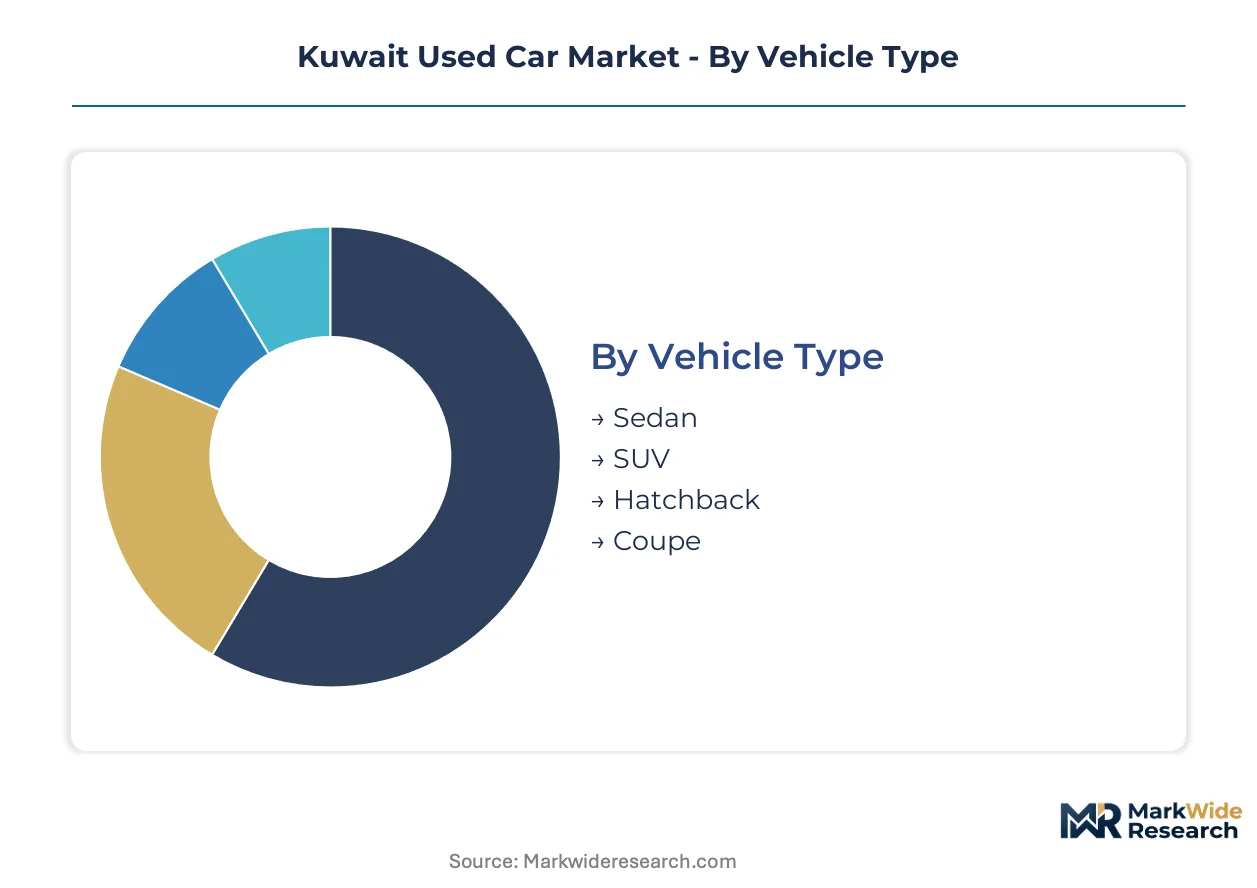
Segmentation in Kuwait's used car market determines financing eligibility, inspection intensity, and residual value stability. Certified channels price inventory by condition tier while age brackets govern warranty coverage duration. Fuel type and vehicle category together shape buyer access to bank installment plans.
Vehicle Type:
Standalone utility vehicles dominate certified channels, while embedded passenger configurations concentrate in informal resale pathways. Integration depth varies by family size requirements and commercial registration status.
- SUV:Three-row and two-row configurations anchor certified pre-owned volume, with chassis-on-frame designs preferred for desert terrain durability. Demand clusters in Jahra and Farwaniya where family-size utility outweighs fuel cost sensitivity. Kuwait's Ministry of Commerce and Industry odometer disclosure rules elevate trust in higher-mileage SUV transactions.
- Sedan:Four-door passenger cars with unibody construction serve corporate fleet rotation and individual commuter needs. Salmiya corridors absorb mid-size sedans under five years as young professionals exit ride-hailing dependency. Financing accessibility expansion pulls first-time buyers toward this segment.
- Hatchback:Compact two-box designs with rear liftgate access target single-occupant urban mobility. Kuwait City parking constraints favor shorter wheelbases in secondary ownership cycles.
- Coupe:Two-door fixed-roof configurations with sport-tuned suspension appeal to discretionary purchasers. Low volume relegates most units to private-sale channels outside certified networks.
Volume placements concentrate in SUV; the faster expansion belongs to Sedan.
Fuel Type:
Cost tier differentiation separates subsidy-dependent petrol from emerging electrified alternatives. Battery health verification protocols create margin stratification between certified and informal channels.
- Petrol:Internal combustion engines with port or direct fuel injection constitute the dominant transaction volume. V6 and V8 configurations face demand compression during Kuwait Petroleum Corporation subsidy adjustments. Dealer networks maintain dense service infrastructure for these powertrains.
- Hybrid:Dual-mode powertrains combining petrol engines with electric motor assistance gain certified-channel acceptance. Toyota and Honda SUV hybrids previously relegated to informal sales now qualify for warranty-backed transactions. Central Agency for Information Technology marketplace compliance rules reward early battery health certifiers.
- Diesel:Compression-ignition engines with higher torque output serve commercial hauling applications. Limited passenger car availability restricts volume in Kuwait's consumer-focused market.
- Electric:Battery-electric vehicles with zero tailpipe emissions occupy negligible secondary market share. Charging infrastructure gaps and battery degradation uncertainty suppress resale liquidity.
Petrol maintains absolute volume leadership; hybrid configurations are climbing the fastest.
Age Category:
Application maturity determines inspection certificate requirements and financing term availability. Newer segments embed warranty transferability; older brackets demand cash-only settlement.
- Less than 5 years:Recent model-year inventory with manufacturer warranty remnants commands premium certified-channel placement. SUV units in this bracket generate the strongest margin pools due to residual value stability. Banking partnerships extend maximum installment coverage here.
- 5 to 10 years:Mid-life vehicles balancing depreciation absorption against remaining service life represent the most liquid segment. Ministry of Interior technical inspection certificates filter unsafe units while preserving transaction velocity. This bracket absorbs the highest search-to-visit conversion rates on digital platforms.
- 10 to 15 years:Higher-mileage units with diminished warranty prospects concentrate in Farwaniya and Jahra informal markets. Price-sensitive buyers accept elevated maintenance exposure for acquisition cost reduction.
- More than 15 years:Classic and utility-focused configurations face restricted financing access. Collector interest and commercial repurposing sustain minimal volume outside scrap pathways.
Five-to-ten-year inventory dominates transaction velocity; sub-five-year units show the steepest certified-channel price escalation.
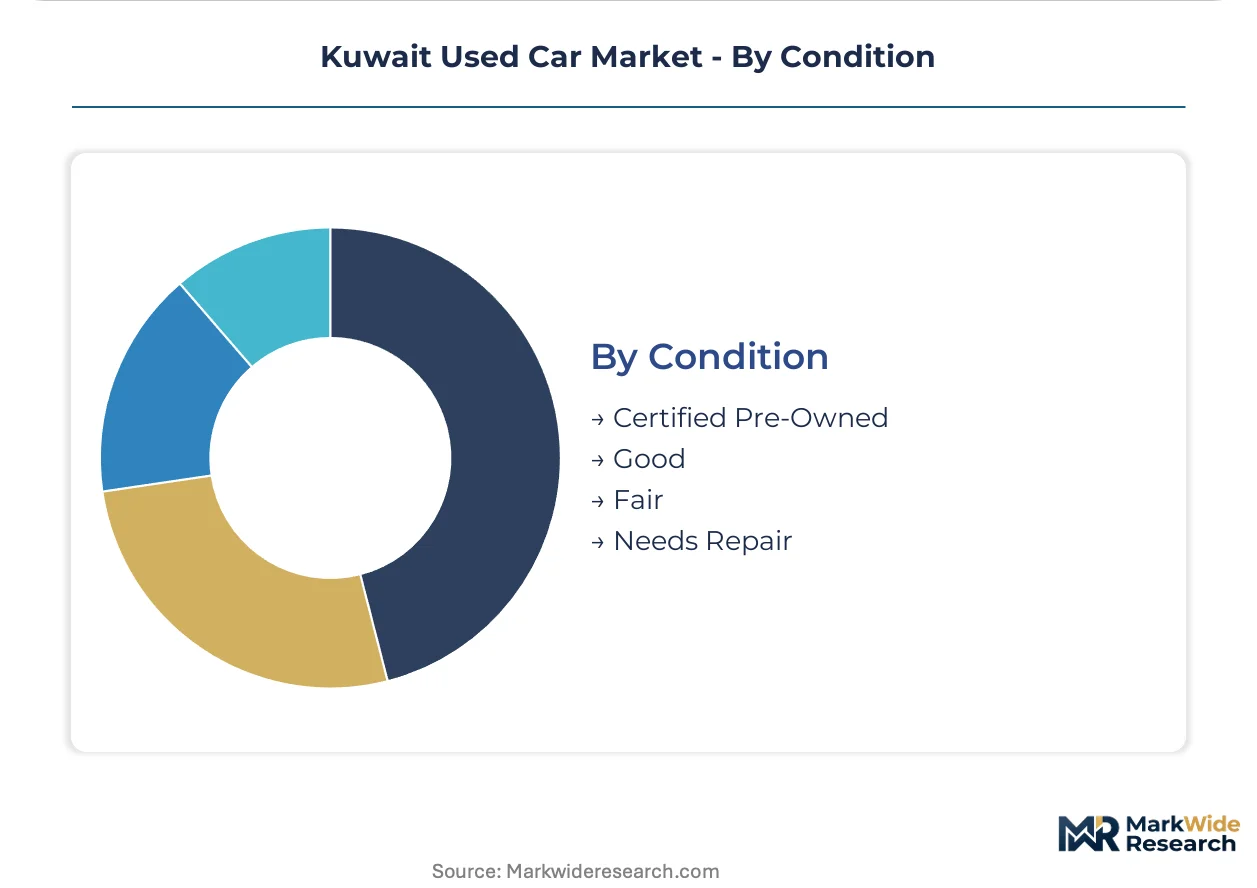
Condition:
Customer type segmentation separates warranty-seeking certified purchasers from risk-tolerant private-sale participants. Margin structure varies directly with documentation depth and recourse availability.
- Certified Pre-Owned:Dealer-verified inventory with standardized condition grading and warranty backing. Kuwait Consumer Protection Authority monitoring pressures consistent quality disclosure. Young professionals in Salmiya filter search results exclusively to this tier.
- Good:Well-maintained units with complete service documentation but no formal certification. Private sellers achieve price premiums approaching certified levels through blockchain-verified history integration.
- Fair:Functionally operational vehicles with cosmetic defects or partial maintenance records. Ministry of Commerce and Industry disclosure mandates reduce information asymmetry in this tier.
- Needs Repair:Mechanically compromised inventory requiring immediate component replacement. Cash-only transactions predominate; inspection certificate bottlenecks delay formal registration.
Certified Pre-Owned captures the fastest share gain; Good condition sustains the largest absolute volume in private channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kuwait City anchors transaction density through overlapping digital platforms and dealership networks, with Salmiya corridors absorbing the highest certified pre-owned SUV volume as young professionals exit cash-only segments.
Kuwait City
Three-row SUV demand concentrates in urban family households seeking desert terrain capability. Kuwait's Ministry of Commerce and Industry enforces stricter odometer disclosure mandates through amended commercial agency regulations. The capital's showroom clusters integrate blockchain-verified service history systems to elevate buyer confidence in higher-mileage inventory.
Salmiya
Young professionals filter search results exclusively by warranty availability, excluding private sellers from consideration sets. The Consumer Protection Authority monitors warranty claim disputes on certified pre-owned sales, pressuring dealers toward standardized condition grading. Digital discovery layers fuse with financing infrastructure here, compressing decision cycles through pre-qualification tools.
Jahra
Family-size utility preferences outweigh fuel cost sensitivity in this governorate. Ministry of Interior technical inspection certificates filter unsafe units from formal resale pathways. Al-Mulla Group showroom clusters demonstrate unmet demand density where digital platforms lack last-mile service infrastructure.
Farwaniya
Mid-life vehicles between five and ten years represent the most liquid segment in this corridor. Inspection certificate bottlenecks at the traffic department create two-week processing delays during peak registration periods. Price-sensitive buyers accept elevated maintenance exposure for acquisition cost reduction in informal markets here.
Kuwait Used Car Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and warranty backing. The vendor base stratifies into three tiers: multi-brand service infrastructure operators, geographic cluster dominators, and digital discovery platforms with integrated financing tools. Consolidation pressure intensifies as disclosure mandates compress private-sale volume toward structured channels. Dominant competitive moves include geographic showroom expansion and API connectivity investments linking inventory management systems to automotive portals.
Within the multi-brand infrastructure tier, Alghanim Automotive leverages service network density to anchor buyer confidence, while Al-Mulla Group exemplifies geographic dominance across Jahra and Farwaniya clusters. YallaMotor.com occupies the digital discovery vector, capturing search-to-visit conversion through financing pre-qualification integration.
| Leading Market Players |
|---|
| Alghanim Automotive |
| Al-Mulla Group |
| Al-Sayer Group |
| Al-Futtaim Motors |
| Al-Mansour Automotive |
| Al-Jazeera Automotive |
| Al Babtain Group |
| YallaMotor.com |
| Dubizzle Group |
| Others |
Pricing and Supply Chain Analysis
Kuwait's Ministry of Commerce and Industry odometer disclosure mandates gate access to certified pre-owned premiums, compressing private-sale volume toward structured channels while elevating compliance costs for inventory under three years. Dealers absorbing blockchain-verified service history integration pass through certification premiums to warranty-seeking buyers in Salmiya corridors.
Pricing Analysis
Certification-grade anchoring determines transaction premiums, with dealer-verified inventory commanding spreads over private-sale units based on standardized condition grading and Kuwait Consumer Protection Authority warranty backing. Price differentiation rests on battery health verification protocols for hybrid SUVs and blockchain-verified maintenance documentation for petrol-powered units. Cost compression in higher-mileage brackets intensifies as inspection certificate bottlenecks at the Ministry of Interior delay registration velocity. Young professionals in Kuwait City exhibit lowest price sensitivity when filtering exclusively by warranty availability, while Farwaniya informal market participants accept elevated maintenance exposure for acquisition cost reduction.
Supply Chain Analysis
Freight consolidation from Japan, South Korea, and the United Arab Emirates feeds Kuwait's certified pre-owned pipeline, with chassis-on-frame SUV platforms dominating import volume for desert terrain durability. Inventory sourcing draws from OEM lease returns, corporate fleet rotations, and regional trade-in cascades from GCC markets. Single-source vulnerability concentrates in hybrid battery health certification equipment, where technical assessor training programs lag vehicle volume growth. Distribution runs through Alghanim Automotive's multi-brand service infrastructure and Al-Mulla Group's Jahra-Farwaniya showroom clusters, with YallaMotor.com capturing digital discovery layers through financing pre-qualification integration.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inspection certificate processing capacity at the Ministry of Interior traffic department constrains inventory velocity, propping pricing power for dealers with established technical assessor relationships and fast-track registration protocols.
For Market Incumbents: Lock in battery health certification capabilities ahead of electrified used inventory expansion beyond negligible share, while deepening API connectivity with YallaMotor.com and competing digital platforms to fragment competing inventory visibility. Al-Mulla Group's geographic dominance across Jahra and Farwaniya showroom clusters demonstrates defensible positioning against ride-hailing substitution from Careem and Uber fleet expansion. For New Entrants and Emerging Players: Kuwait Consumer Protection Authority warranty standardization opens a window for digital-native platforms offering integrated financing pre-qualification tools that compress search-to-visit conversion cycles before incumbent dealership contact. Jahra governorate penetration presents the most penetrable white-space target, where last-mile service infrastructure gaps persist beneath Al-Mulla Group's showroom density. A mobile-first condition assessment service targeting five-to-ten-year inventory brackets unlocks certified-channel acceptance without fixed asset overhead. For Investors and Strategic Acquirers: Hybrid battery health protocol adoption rates at Toyota and Honda certified channels are the leading indicator that electrified powertrain margins will sustain premium-tier pricing against petrol volatility at Kuwait Petroleum Corporation. Long-term viability across the analysis window favors dealers with backward integration into technical assessor training programs and blockchain-verified service history systems. Target acquisition archetypes combine multi-brand service infrastructure with dense showroom clustering in supply-constrained corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Health Certification Investment | Central Agency for Information Technology compliance rules reward early hybrid powertrain verifiers with certified-channel placement. |
| API Integration with Digital Platforms | Connectivity with YallaMotor.com compresses inventory visibility gaps against legacy DMS resistance from 2010s systems. |
| Technical Assessor Training Program | Ministry of Interior certification capacity builds defensible registration velocity during peak processing periods. |
| Blockchain Service History Integration | Kuwait Ministry of Commerce and Industry disclosure mandates elevate trust premiums for documented maintenance traceability. |
| Jahra Showroom Cluster Expansion | Geographic density captures unmet family-size utility demand where digital platforms lack last-mile infrastructure. |
Research Methodology
Document review covered vehicle registration databases, Ministry of Interior technical inspection filings, and Central Agency for Information Technology marketplace compliance records, complemented by interviews with dealership operations managers, certified pre-owned program directors, digital platform product leads, and banking partnership executives at installment providers. Secondary validation drew from customs import data, automotive OEM fleet rotation disclosures, and consumer protection authority warranty dispute filings. Bottom-up transaction volume triangulation across age brackets, fuel types, and condition tiers was cross-referenced against top-down market value estimates from financing penetration rates and average transaction values.
Segment-level outputs across vehicle type, fuel category, age bracket, and geographic governorate were generated through the projection horizon using elasticity-adjusted demand curves and supply-constrained inventory turnover assumptions. CAGRs were derived from regression-weighted historical velocity patterns and policy-impact scenario modeling. Key forecast inputs incorporated Ministry of Commerce and Industry regulatory phase-in schedules and Kuwait Petroleum Corporation subsidy adjustment probabilities.
The model assumes a particular technology adoption path for hybrid powertrain certification; alternative pathways for battery-electric vehicle secondary market liquidity would alter the outlook if charging infrastructure gaps narrow faster than baseline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
New Zealand Used Car Market
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
China Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
Portugal Used Car Market
Used Vehicles
Used Cars Market
Used Vehicles
UAE Used Cars Industry Market
Used Vehicles
United States Used Car Market
Used Vehicles
Canada Used Car Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
North America Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Indonesia Used Car Financing Market