
 Apparel Logistics Market | 2026-2036
Apparel Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Apparel Logistics Market Analysis
Multi-source apparel procurement is recalibrating how brands balance speed against inventory risk. Deutsche Post DHL Group leverages its Asia-Europe air freight corridors to serve fast-fashion replenishment cycles. Kuehne + Nagel anchors trans-Pacific volumes through controlled ocean-air intermodal solutions. DSV competes on project logistics for seasonal collection launches requiring compressed delivery windows.
Apparel logistics encompasses the specialized movement, storage, and fulfillment of garments from manufacturing nodes through retail channels, requiring temperature-controlled environments, hanging-garment conveyance systems, and barcode-level SKU granularity to prevent shrinkage and obsolescence. Sourcing services dominate value capture as brands fragment production across multiple low-cost countries to mitigate tariff exposure. Fulfillment under the delivery model segment registers the fastest structural expansion, driven by e-commerce platforms demanding parcel-level final-mile precision. RFID tracking within the technology dimension is displacing manual inventory counts in high-velocity distribution centers.
The EU Green Deal and CSRD compel logistics providers to document Scope 3 emissions across apparel supply chains, while REACH restricts chemical treatments in textile finishing that affect warehousing protocols. The US EPA and OSHA regulate warehouse air quality and worker safety standards in garment distribution facilities. Stakeholders must monitor how emissions disclosure mandates reshape carrier selection criteria and warehouse location decisions.
Market Dynamics
E-commerce fulfillment velocity is compressing delivery windows from weeks to hours, forcing apparel logistics providers to reconfigure warehouse networks around urban micro-fulfillment nodes and automated sortation systems.
Growth Catalysts
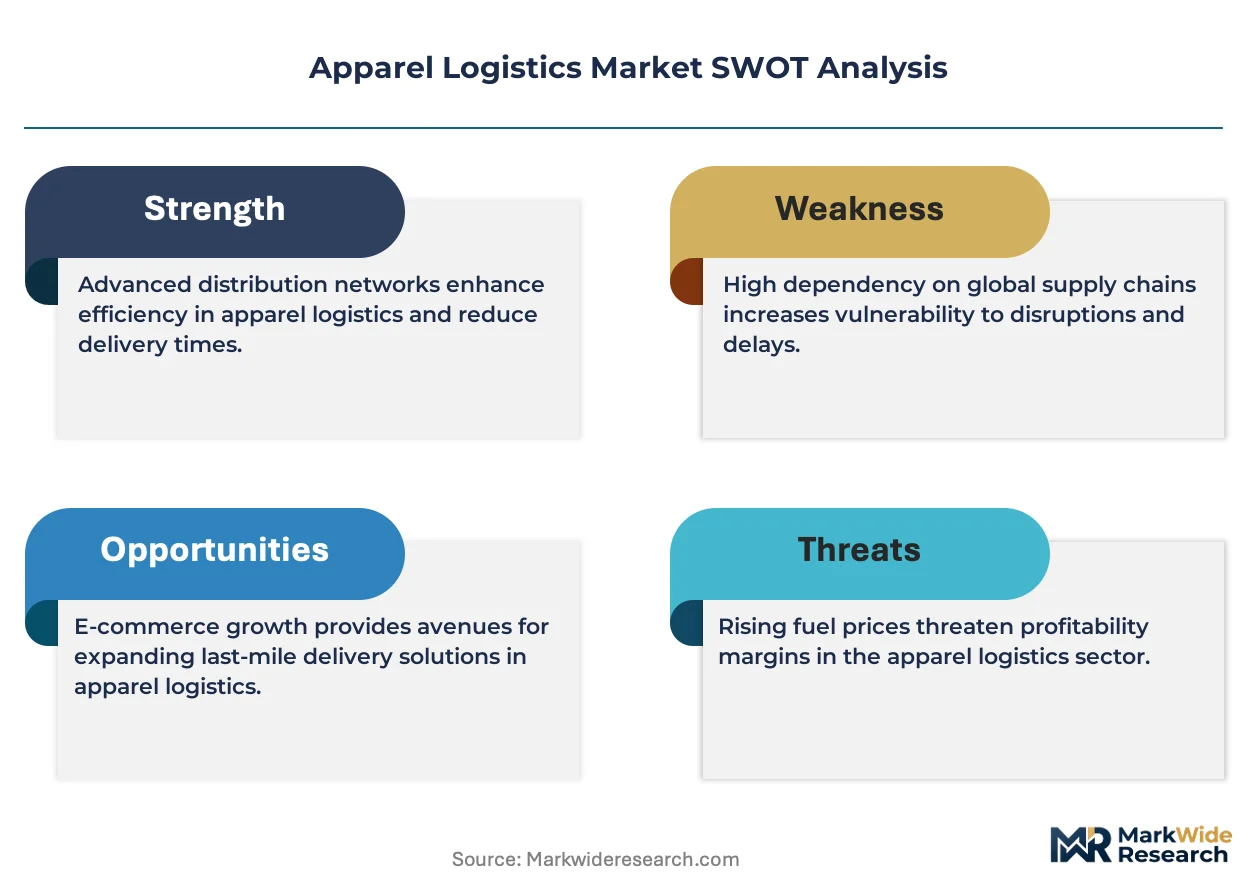
- EU Green Deal compliance mandates:The EU Green Deal and CSRD require Scope 3 emissions documentation across apparel supply chains, creating demand for carbon-accounting logistics services and low-emission last-mile fleets.
- Fast-fashion replenishment cycles:Direct-to-consumer brands now require same-day and next-day fulfillment capabilities, driving investment in automated hanging-garment conveyance and real-time inventory visibility systems.
- Pearl River Delta manufacturing concentration:Apparel production clusters in Guangdong and Shenzhen feed high-volume outbound logistics lanes, anchoring air freight and ocean-air intermodal demand.
Market Restraints
- Fuel price volatility:Diesel and sustainable aviation fuel cost swings directly compress margins in temperature-controlled garment transport and express delivery segments.
- Vietnam corridor concentration risk:Heavy reliance on manufacturing corridors from Ho Chi Minh City to Hai Phong creates vulnerability to port congestion, labor disruptions, and single-source dependency.
- REACH chemical restrictions:ECHA's REACH regulation limits textile finishing chemicals, forcing warehouse operators to segregate inventory and extend quarantine protocols for treated garments.
Strategic Opportunities
- Circular economy logistics:The EU Green Deal's circular economy compliance requirements create white space for reverse logistics services handling garment returns, resale authentication, and textile recycling collection.
- RFID-barcode convergence:Integration of RFID tracking with legacy barcode systems enables item-level granularity in high-velocity distribution centers without full infrastructure replacement.
- India manufacturing diversification:Brands fragmenting production to mitigate tariff exposure are activating logistics corridors from Tirupur and Bangalore, creating demand for bonded warehousing and export consolidation.
Industry Challenges
- Warehouse automation talent scarcity:Deployment of robotic pick systems and automated storage/retrieval requires technicians skilled in mechatronics and warehouse management system integration, a capability gap in traditional garment logistics labor pools.
- Legacy WMS integration friction:Real-time inventory visibility demands API connectivity between enterprise resource planning platforms and third-party logistics provider systems, often requiring expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apparel Logistics Market |
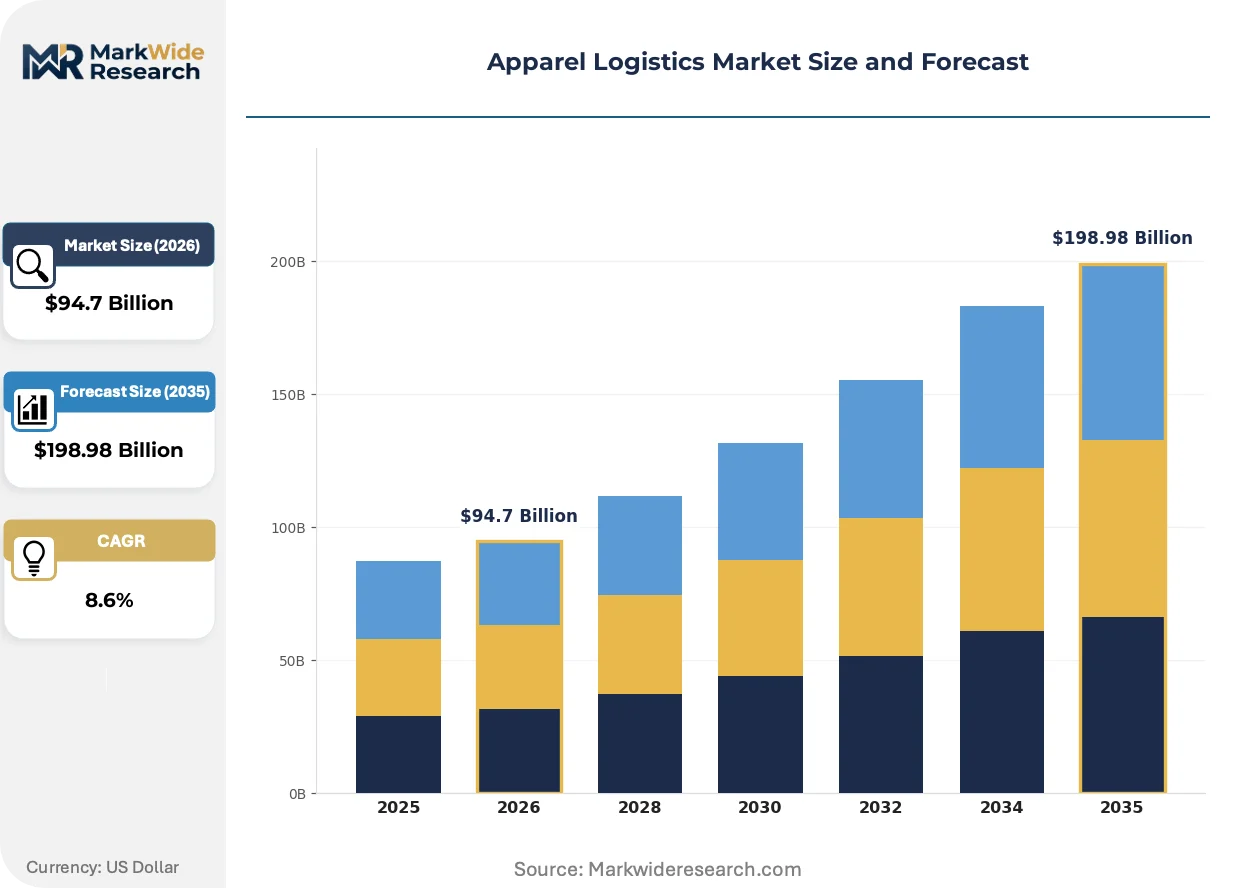
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $198.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Sourcing, Warehousing, Transportation, Distribution Delivery Model: Direct Shipping, Drop Shipping, Cross-Docking, Fulfillment Customer Type: Retailers, Wholesalers, E-commerce Platforms, Brands Technology: Inventory Management, RFID Tracking, Data Analytics, Automation |
| Companies Covered | Deutsche Post DHL Group, Kuehne + Nagel, DSV, Hellmann Worldwide Logistics, Ceva Logistics, XPO Logistics, DB Schenker, Bolloré Logistics, Nippon Express, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apparel Logistics Market Emerging Trajectories
Digital inventory transparency and automated material handling are converging to collapse fulfillment cycle times, while regulatory disclosure mandates reshape carrier selection criteria across apparel supply chains.
RFID-enabled garment tracking is overtaking manual barcode scanning in high-velocity distribution centers. Fast-fashion retailers and luxury consignment platforms are deploying item-level RFID to eliminate cycle-count labor and enable real-time shrinkage detection. This technology is overtaking legacy inventory methods by compressing receiving and put-away timelines from hours to minutes, enabling same-day fulfillment promises.
The EU Green Deal's CSRD disclosure requirements are mandating granular Scope 3 emissions reporting across European logistics networks. Apparel brands must now document transportation and warehousing carbon footprints, forcing logistics providers to invest in telematics and fuel-monitoring infrastructure. Third-party logistics operators serving EU markets are responding by electrifying last-mile fleets and securing renewable energy contracts for distribution centers.
Direct-to-consumer channel expansion is fragmenting order profiles from bulk retail shipments to individual parcel fulfillment. E-commerce platforms are disintermediating traditional wholesale distribution, requiring logistics providers to reconfigure warehouse layouts for piece-pick automation and polybag packaging. This shift is most visible in Vietnam-to-EU and China-to-US lanes, where parcel-level customs clearance and final-mile precision now determine competitive positioning.
Apparel Logistics Market Segmentation
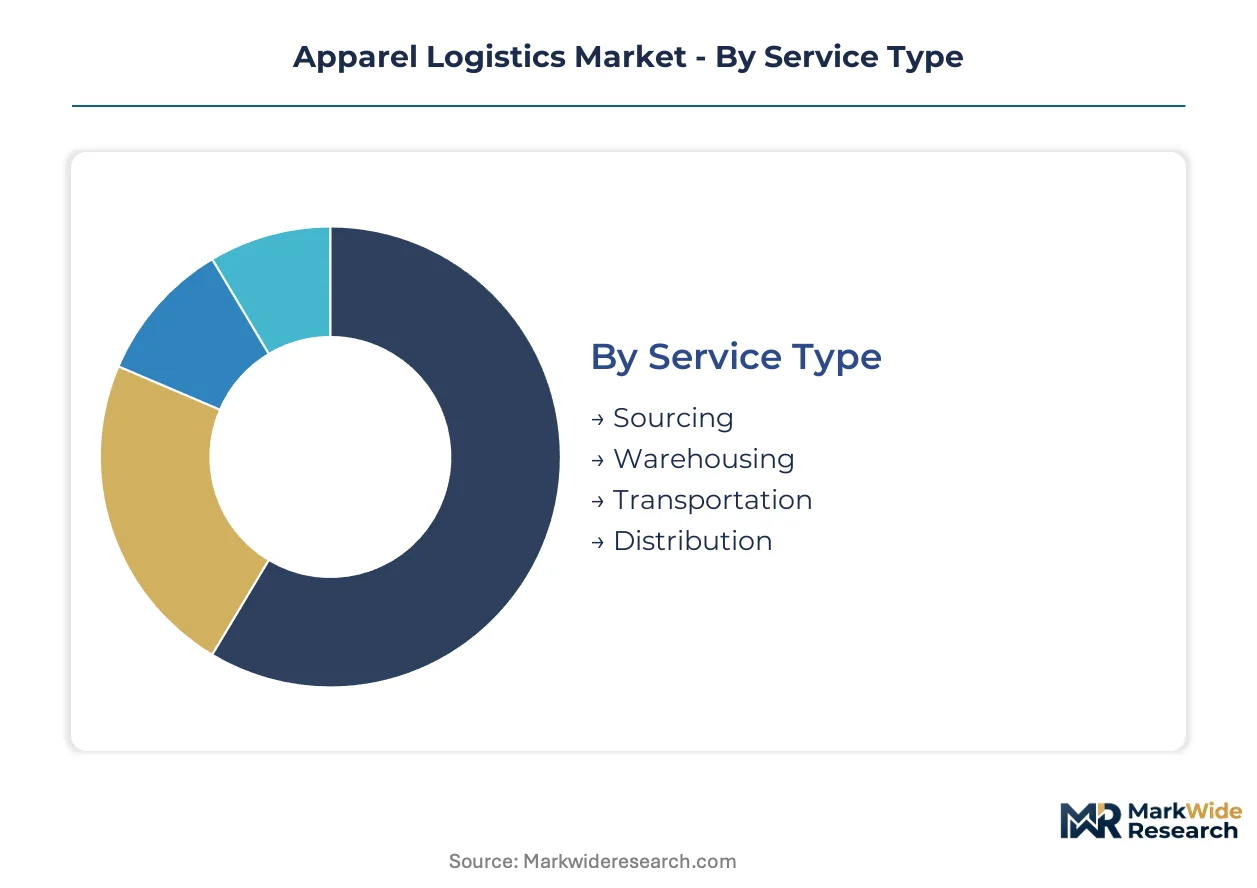
Apparel logistics segmentation reveals how service specialization, delivery velocity, and technology integration determine competitive positioning across garment supply chains. Each dimension carries distinct regulatory burdens and capital intensity requirements that shape provider profitability.
Service Type:
Sourcing services face REACH chemical documentation requirements for textile treatments entering EU markets, while warehousing operations must satisfy OSHA warehouse safety standards in US distribution nodes.
- Sourcing:Procurement coordination across Vietnam's manufacturing corridors and Guangdong production clusters requires bonded warehouse management and export consolidation expertise. Brands fragmenting production across multiple low-cost countries drive demand for multi-origin shipment consolidation and tariff engineering services.
- Warehousing:Temperature-controlled environments with hanging-garment conveyance systems preserve garment integrity during seasonal inventory peaks. Automated storage and retrieval systems in Pearl River Delta facilities compress put-away timelines to enable same-day fulfillment promises.
- Transportation:Air freight corridors from Ho Chi Minh City to Rotterdam and ocean-air intermodal solutions from Shenzhen anchor trans-Pacific and Asia-Europe volume.
- Distribution:Final-mile precision in urban micro-fulfillment networks determines e-commerce platform retention rates.
Sourcing sits at the top of the volume ranking, with fulfillment climbing the fastest.
Delivery Model:
Cost tiers separate asset-heavy models requiring dedicated infrastructure from variable-cost arrangements leveraging third-party networks.
- Direct Shipping:Bulk container movements from manufacturing nodes to retail distribution centers minimize handling costs for predictable seasonal collections. Fast-fashion replenishment cycles in Zara-style operations demand compressed ocean transit times with expedited customs clearance.
- Fulfillment:Parcel-level processing with polybag packaging and piece-pick automation serves direct-to-consumer order profiles. E-commerce platforms in US and EU markets require real-time inventory visibility and same-day dispatch capabilities from urban micro-fulfillment nodes.
- Drop Shipping:Supplier-direct dispatch eliminates intermediate inventory holding for long-tail SKU assortments.
- Cross-Docking:Minimal dwell-time transfer between inbound and outbound vehicles reduces working capital requirements for high-velocity fashion items.
Direct Shipping captures the highest shipment volume, with Fulfillment expanding most quickly.
Customer Type:
Application intensity varies by inventory risk tolerance and channel complexity, with e-commerce platforms demanding the highest fulfillment precision.
- E-commerce Platforms:Individual parcel processing with real-time tracking and flexible return logistics dominates service requirements. Shein and Temu operations from Guangdong to EU and US markets require customs pre-clearance and last-mile electrification to meet CSRD emissions disclosure mandates.
- Brands:Omnichannel coordination across wholesale, retail, and direct-to-consumer channels demands unified inventory visibility. Nike and Adidas operations require RFID-enabled item-level tracking to prevent shrinkage across global distribution networks.
- Retailers:Seasonal collection launches with compressed delivery windows drive project logistics demand.
- Wholesalers:Bulk consolidation and break-bulk services support traditional multi-brand distribution.
E-commerce Platforms sit at the top of the volume ranking, with Brands climbing the fastest.
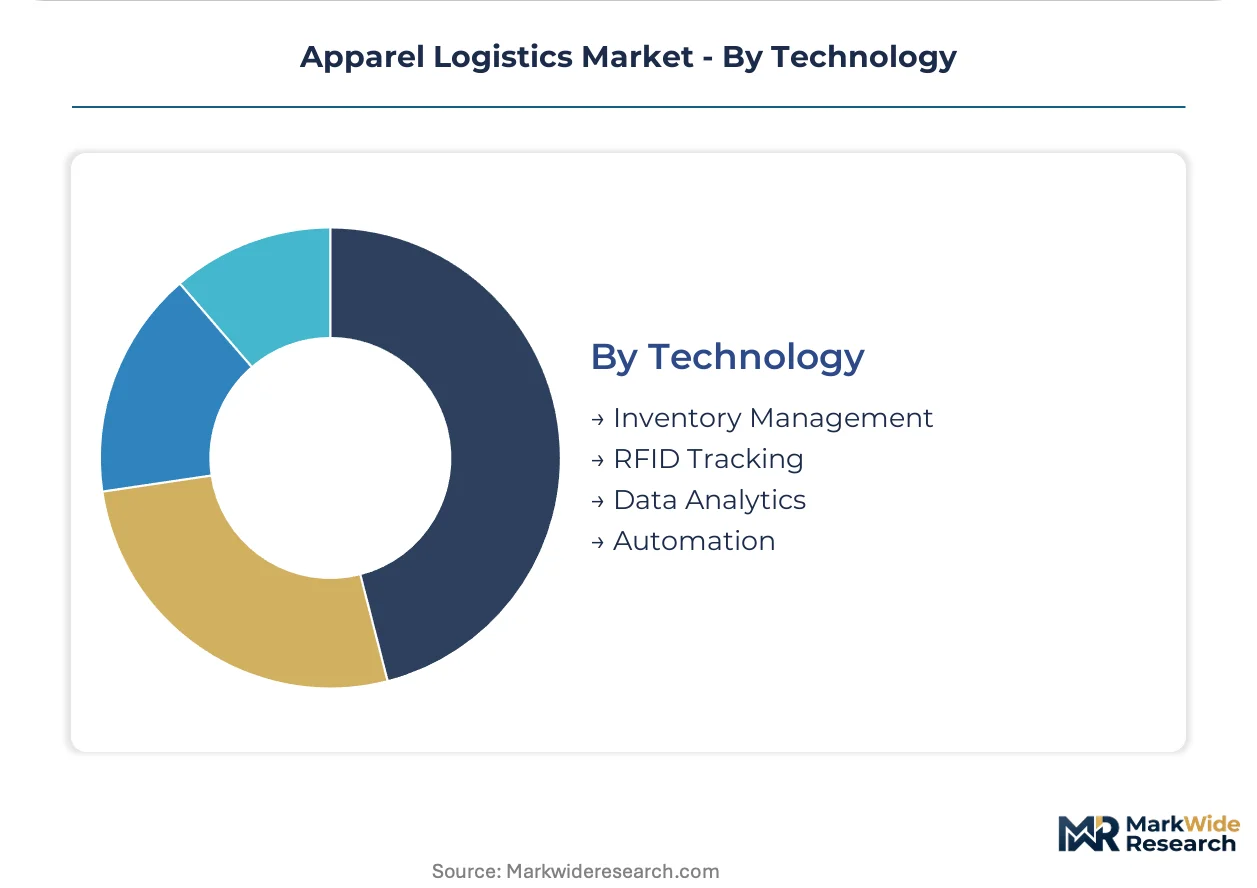
Technology:
Maturity stages separate legacy barcode systems from emerging RFID and automation deployments requiring significant capital reconfiguration.
- RFID Tracking:Item-level garment identification eliminates manual cycle counts and enables real-time shrinkage detection in high-velocity distribution centers. Zara and H&M deployments across European facilities compress receiving timelines from hours to minutes.
- Automation:Robotic pick systems and automated storage/retrieval infrastructure address warehouse labor scarcity in Vietnam and China manufacturing corridors. DHL and Kuehne + Nagel investments in mechatronics capabilities support fast-fashion replenishment cycles.
- Inventory Management:API connectivity between enterprise resource planning and third-party logistics systems enables unified stock visibility.
- Data Analytics:Demand forecasting and route optimization algorithms reduce empty miles and inventory obsolescence risk.
Inventory Management sits at the top of the volume ranking, with RFID Tracking climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is accelerating production migration toward jurisdictions with narrower emissions disclosure obligations and lower labor compliance costs. Vietnam and Bangladesh capture garment manufacturing volume as brands seek alternatives to China's tightening environmental enforcement. The Pearl River Delta retains dominance in fast-fashion fulfillment infrastructure despite rising operational costs.
China
Guangdong and Shenzhen manufacturing clusters anchor Asia-Europe air freight corridors for fast-fashion replenishment cycles. MEE enforcement of dual carbon goals is tightening warehouse energy standards and forcing logistics providers to electrify last-mile fleets. The Pearl River Delta concentration feeds high-volume outbound lanes, though rising labor costs are pushing some brands toward Southeast Asian alternatives.
Vietnam
Ho Chi Minh City to Hai Phong manufacturing corridors attract brands diversifying beyond China to mitigate tariff exposure and labor cost inflation. REACH documentation requirements for EU-bound textile exports are forcing logistics operators to invest in chemical traceability systems. The northern Red River Delta corridor is expanding bonded warehousing capacity to serve export consolidation demand.
Germany
Ruhr Valley and Rhine-Main distribution hubs serve as EU entry points for Asia-sourced apparel volumes. CSRD mandates under the EU Green Deal compel logistics providers to document Scope 3 emissions across warehousing and transportation operations. KBA regulations on commercial fleet emissions are accelerating electrification of last-mile delivery networks serving e-commerce platforms.
United States
Los Angeles and Savannah port complexes handle trans-Pacific apparel imports for domestic distribution networks. EPA warehouse air quality standards and OSHA worker safety regulations govern garment handling facilities in California and Georgia. The Inland Empire logistics corridor is expanding automated sortation capacity to meet same-day fulfillment demands from direct-to-consumer brands.
India
Tirupur and Bangalore manufacturing clusters are activating as brands fragment production to reduce China dependency and capture duty-free EU access under trade agreements. BIS textile quality standards and DGFT export documentation requirements shape logistics protocols for outbound shipments. The Delhi-Mumbai Industrial Corridor is developing dedicated apparel logistics parks with temperature-controlled warehousing infrastructure.
Apparel Logistics Market Vendor Landscape
Established logistics providers occupy the standard tier with integrated air-ocean networks; emerging entrants pursue niche specialization in circular economy reverse logistics and carbon-accounting services. The market structure consolidates around three to five global operators controlling trans-Pacific and Asia-Europe lane capacity, with regional specialists capturing intra-Asia and final-mile segments. Strategic archetypes divide between asset-heavy integrators owning freighter fleets and warehouses, asset-light forwarders leveraging partner networks, and technology-enabled platforms offering visibility-layer services. Dominant competitive moves include M&A to secure lane density and strategic partnerships with e-commerce platforms for dedicated fulfillment capacity.
Within the integrated logistics tier, Deutsche Post DHL Group and Kuehne + Nagel occupy positions as archetypal network-scale operators, while DSV represents the consolidation-driven expansion model. Deutsche Post DHL Group exemplifies the asset-heavy integrator with controlled Asia-Europe air freight corridors. Kuehne + Nagel anchors trans-Pacific volumes through intermodal solutions spanning ocean and air modes. DSV sits within the project logistics specialization segment, serving seasonal collection launches requiring compressed delivery windows.
| Leading Market Players |
|---|
| Deutsche Post DHL Group |
| Kuehne + Nagel |
| DSV |
| Hellmann Worldwide Logistics |
| Ceva Logistics |
| XPO Logistics |
| DB Schenker |
| Bolloré Logistics |
| Nippon Express |
| Others |
Supply Flow & Price Mechanics
RFID-barcode convergence in warehouse automation simultaneously compresses labor cost economics and concentrates vendor power among systems integrators serving Asia-Europe corridors. This technology shift rewards providers with mechatronics capabilities while squeezing margins for asset-light forwarders dependent on manual inventory handling.
Pricing Analysis
Distributor margin compression runs through the fulfillment tier as e-commerce platforms demand same-day dispatch capabilities without absorbing infrastructure costs. Three-tier pricing structure across premium, standard, and economy levels separates RFID-enabled precision logistics from basic transportation brokerage. Price differentiation hinges on carbon-accounting service bundling for EU Green Deal compliance and volume scale in trans-Pacific lane commitments. Cost compression in standard-tier warehousing is intensifying because automated storage and retrieval systems require capital deployment that asset-light competitors cannot match. Direct-to-consumer brands exhibit highest price sensitivity, while luxury houses prioritize service reliability over rate negotiation.
Supply Chain Analysis
Single-source vulnerability sits with Vietnam's Ho Chi Minh City to Hai Phong manufacturing corridor, where port congestion and labor disruptions threaten replenishment cycles for EU-bound fast fashion. Geographic supply concentration draws from Vietnam, Bangladesh, and China's Pearl River Delta, with raw material dependencies resting on cotton fiber, synthetic textile feedstocks, and sustainable aviation fuel for air freight lanes. Supply chain risk centers on tariff exposure as brands fragment production to mitigate duty engineering complexity. Distribution runs through bonded warehousing nodes in Rotterdam, Los Angeles, and Singapore for customs pre-clearance before final-mile injection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Apparel logistics functions as a late-cycle quality story as direct-to-consumer channel expansion forces premium specifications for real-time inventory visibility and emissions traceability. Brands now treat logistics as a competitive differentiator rather than a cost center.
For Market Incumbents: Lock in lane density through dedicated freighter capacity agreements on Asia-Europe corridors before emerging entrants secure charter alternatives. Defend against technology-enabled visibility platforms by acquiring RFID systems integrators with proven warehouse management system integration capabilities. Prioritize certification investment for CSRD emissions disclosure to capture carbon-accounting service premiums from EU-bound brands.
For New Entrants and Emerging Players: The price-point gap between premium RFID-enabled fulfillment and economy-grade transportation brokerage offers white space for mid-tier automation providers targeting India manufacturing diversification. Target bonded warehousing in Tirupur and Bangalore corridors where incumbent coverage remains thin. Pursue circular economy reverse logistics for garment resale authentication, a segment where established players lack specialized infrastructure.
For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light forwarders without controlled warehouse networks or freighter capacity, as margin compression exposes structural weakness. Long-term viability favors operators with vertical integration into automation technology and renewable energy contracts for distribution center power. Watch for inflection where EU Green Deal enforcement triggers carrier selection criteria shifts that disqualify non-compliant logistics providers from brand tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID Infrastructure Deployment | Item-level tracking eliminates cycle-count labor for Zara-style replenishment cycles. |
| Last-Mile Fleet Electrification | KBA regulations in Germany accelerate zero-emission delivery network investments. |
| Bonded Warehousing Expansion | India's Delhi-Mumbai Industrial Corridor develops temperature-controlled apparel logistics parks. |
| Carbon-Accounting Service Launch | CSRD mandates create revenue streams from Scope 3 emissions documentation. |
| Reverse Logistics Platform Buildout | Circular economy compliance requires specialized handling for textile recycling collection. |
Methodological Framework
Coverage spans Asia-Pacific, Europe, and North America, with primary inputs from each region combined with secondary validation. Primary interviews engaged logistics operations directors, apparel brand supply chain executives, bonded warehouse managers, and sustainability compliance officers across Vietnam, Germany, and the United States. Secondary sources incorporated customs trade data, SEC 10-K filings of listed logistics providers, EU ETS emissions registry records, and port authority throughput statistics. Bottom-up shipment volume modeling and top-down market sizing triangulated against carrier capacity disclosures.
Rate-of-change decomposition structured the analytical framework across the modeling period, segmenting by service type, delivery model, customer channel, and technology adoption stage. CAGRs derived from historical lane volume growth adjusted for e-commerce penetration trajectories and regulatory implementation timelines. Forecast inputs included air freight yield trends, warehouse automation deployment rates, and circular economy policy enforcement intensity.
Caveats apply where fuel price volatility, trade policy shifts, or warehouse automation talent scarcity could materially shift the outlook. Forecasts reflect assumptions about CSRD enforcement consistency and fast-fashion replenishment cycle stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global 3PL in Cold Chain Logistics Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
ASEAN Chemical Logistics Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Freight Transport Management Market