
 Europe less-Than Container Load Market | 2026-2036
Europe less-Than Container Load Market Size, Share, and Industry Trends Forecast 2026-2036
Europe less-Than Container Load Market Foresight
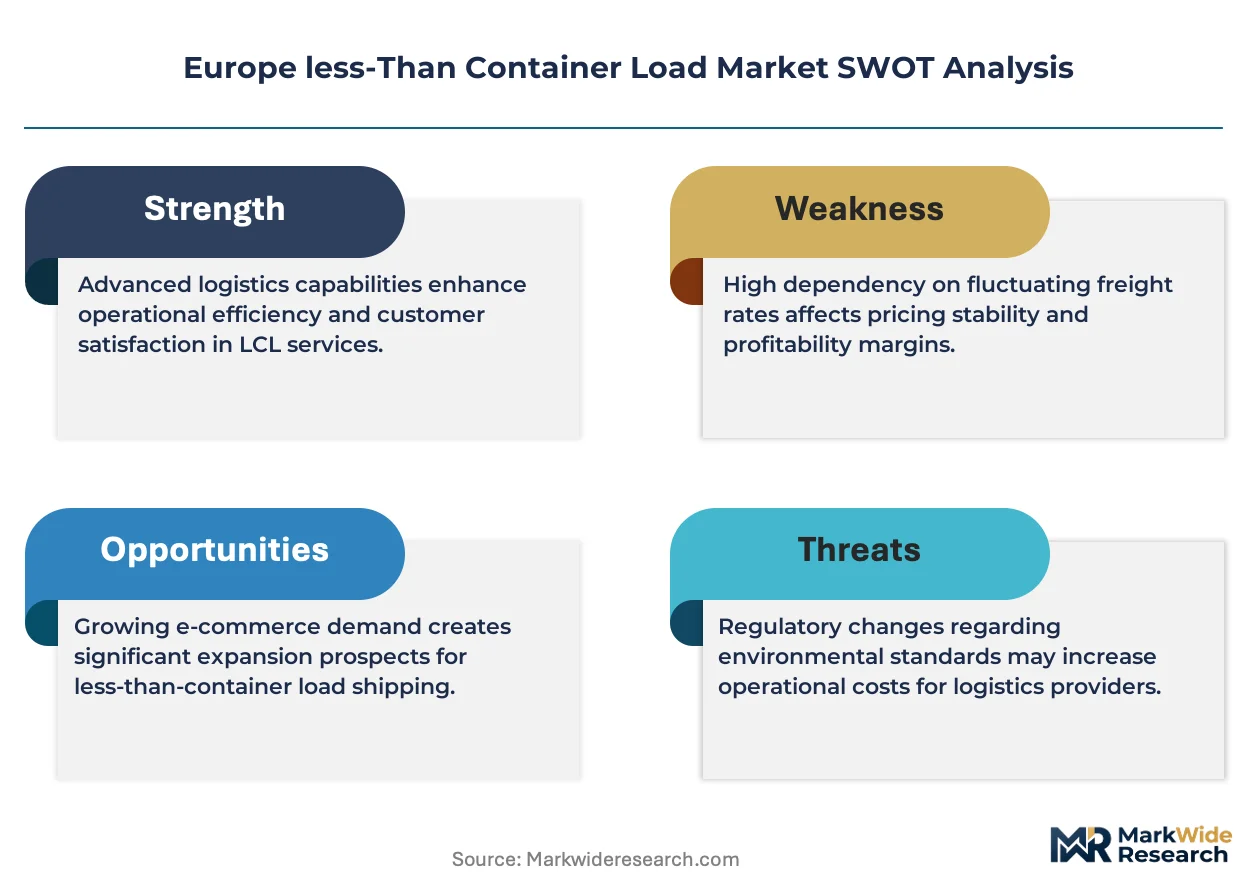
E-commerce fulfillment is restructuring how European shippers procure consolidated freight capacity, pulling inventory closer to consumer clusters and away from traditional port-centric distribution. DSV leverages its Nordic hub network to control cross-border consolidation flows into Scandinavia and the Baltic states. GEODIS anchors its competitiveness through specialized automotive parts consolidation services tied to just-in-sequence manufacturing schedules. Kuehne + Nagel sustains technology leadership through proprietary cargo aggregation platforms that optimize container utilization rates across multiple European gateway ports.
Europe less-than container load denotes maritime and intermodal freight services where multiple shippers share container space for shipments below full container capacity, typically involving cargo weights under twenty metric tons or volumes insufficient for twenty-foot equivalent unit utilization. The primary commercial purpose centers on cost-efficient access to international shipping lanes for small and medium enterprises lacking volume to justify dedicated container charter. Door-to-door service offerings capture premium margin pools by bundling first-mile collection, customs brokerage, and last-mile delivery under single-contract accountability. Rail freight segments gain structural momentum as the EU Green Deal tightens emissions accountability and Rhine corridor congestion elevates landbridge alternatives between North Sea and Mediterranean ports.
The EU Green Deal and its embedded emissions trading system, alongside Germany's KBA truck tolling reforms and the EU's F-Gas Regulation on transport refrigeration units, collectively elevate compliance costs for road-dependent consolidators and redirect investment toward multimodal infrastructure. REACH chemical documentation requirements further shape cargo acceptance protocols and carrier liability frameworks for mixed-load containers. Stakeholders must monitor how the EU AI Act's risk classification rules apply to automated cargo matching platforms, as algorithmic freight allocation becomes central to network density optimization.
Market Dynamics
EU Green Deal emissions trading is compressing road freight margins and accelerating modal shifts toward rail consolidation and short-sea networks across the Rhine corridor.
Growth Catalysts
- Rail freight electrification:The EU Green Deal's carbon border adjustment mechanism is tilting cost structures toward electric rail corridors connecting North Sea and Mediterranean ports.
- E-commerce fulfillment density:Urban consumer clusters in Germany's Rhine-Ruhr region are generating sufficient shipment volumes to sustain daily consolidation cycles.
- REACH documentation automation:Digital chemical compliance platforms are reducing cargo acceptance delays for mixed-load pharmaceutical and specialty chemical shipments.
Market Restraints
- Rhine waterway volatility:Low water episodes on the Rhine River disrupt barge-fed consolidation hubs and force emergency road transfers.
- Refrigerated container equipment scarcity:The EU F-Gas Regulation's phase-down of hydrofluorocarbon refrigerants is constraining reefer container availability for temperature-sensitive cargo.
- Port labor contract fragmentation:Collective bargaining disputes at Hamburg and Rotterdam terminals generate unpredictable dwell time spikes.
Strategic Opportunities
- Baltic rail landbridge expansion:Polish and Lithuanian terminals are capturing Asia-Europe cargo seeking alternatives to congested Suez routing.
- AI Act-compliant matching platforms:The EU AI Act's risk classification framework creates first-mover advantage for freight aggregators with auditable algorithmic cargo allocation.
- Short-sea Mediterranean integration:Spanish and Italian port authorities are subsidizing feeder connections that bypass saturated northern range terminals.
Industry Challenges
- Multimodal data interoperability:Legacy port community systems in Hamburg and Antwerp resist real-time integration with rail and barge operator platforms.
- Customs brokerage talent scarcity:Post-Brexit UK-EU trade documentation complexity has outpaced training pipeline output for certified declarants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe less-Than Container Load Market |
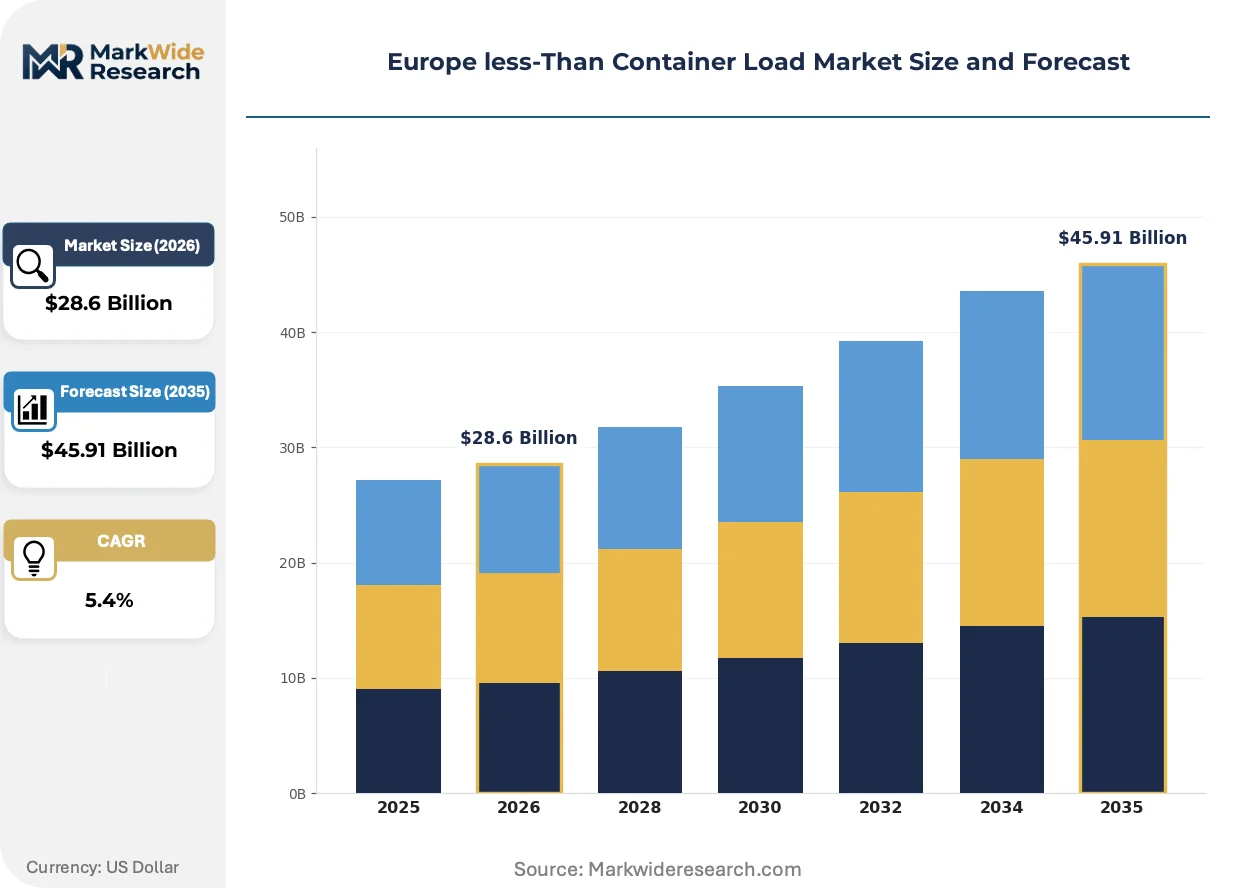
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Door-to-Door, Port-to-Port, Terminal-to-Terminal, Freight Forwarding End User: E-commerce, Retail, Manufacturing, Automotive Delivery Mode: Air Freight, Road Transportation, Rail Freight, Sea Freight Packaging Type: Crates, Pallets, Boxes, Wrapping |
| Companies Covered | DSV, GEODIS, DB Schenker Logistics, Kuehne + Nagel, CEVA Logistics, DHL Group, Vanguard Logistics, ECU Worldwide, Dachser, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe less-Than Container Load Market Shifts & Advancements
Digital freight platforms are compressing transaction cycles and enabling dynamic capacity arbitrage across fragmented European carrier networks.
Proprietary cargo aggregation software is consolidating shipper demand into algorithmically optimized container stowage plans. Third-party logistics providers across Germany and the Netherlands are deploying these systems to raise utilization rates on Asia-Europe backhaul legs. The technology is consolidating mid-tier forwarders into platform-dependent networks rather than standalone service offerings.
The EU AI Act's risk-based governance framework is mandating human oversight protocols for automated freight matching systems. Logistics operators must now maintain audit trails for algorithmic cargo allocation decisions affecting cross-border consolidation. High-risk classification applies to platforms handling hazardous materials documentation, forcing additional compliance layers onto chemical and pharmaceutical freight specialists.
Shippers are unbundling port-centric distribution in favor of inland consolidation hubs positioned near consumer demand clusters. Traditional gateway dependency is yielding to satellite facilities in Poland, Czechia, and Hungary that pre-position inventory for final-mile injection. German automotive manufacturers are driving this pattern through just-in-sequence parts delivery requirements that tolerate minimal inland transit variance.
Europe less-Than Container Load Market Segmentation
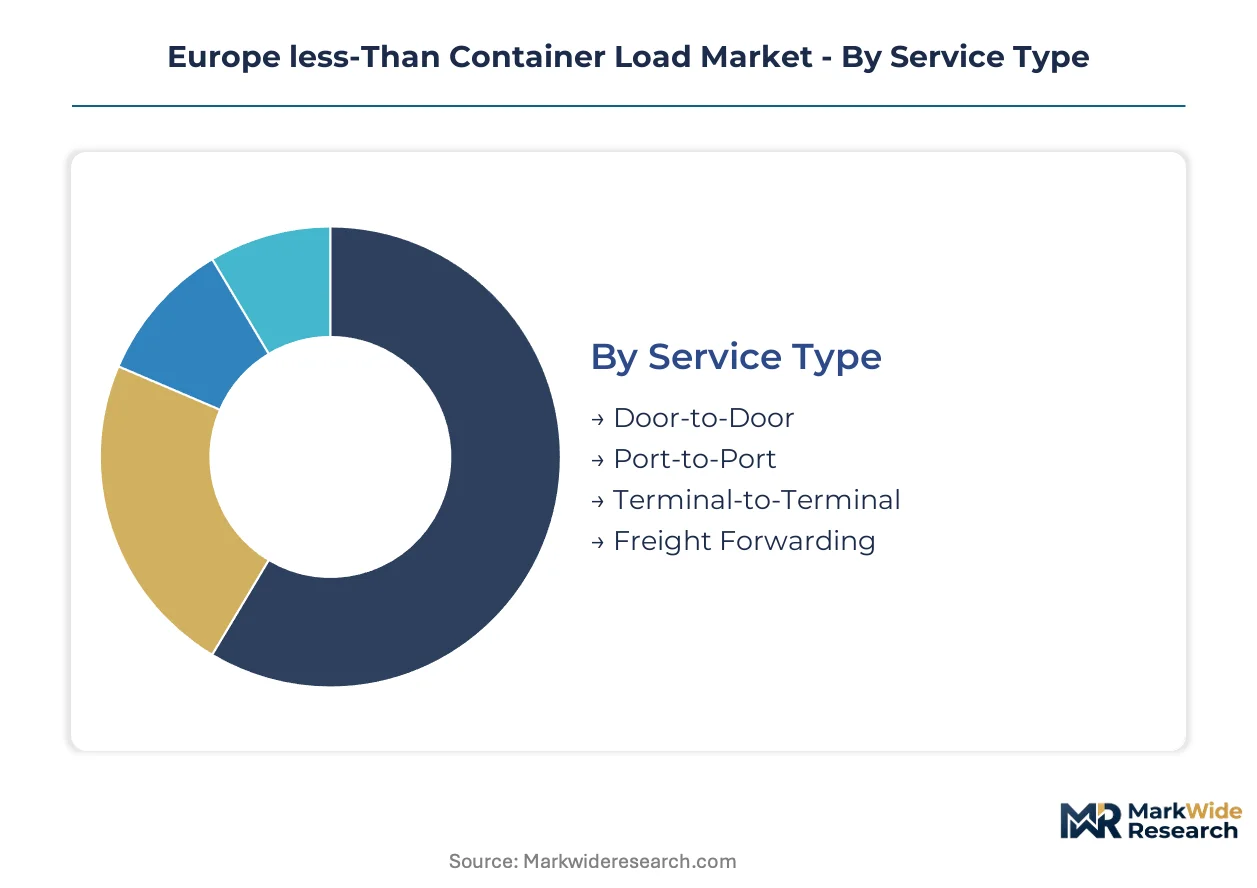
Shippers select service configurations based on inventory velocity requirements, customs complexity tolerance, and modal cost structures. Segment boundaries blur as integrated providers bundle previously discrete offerings under single-contract accountability.
Service Type:
Service tier selection tracks directly with shippers' internal logistics capabilities and tolerance for coordination overhead.
- Door-to-Door:Comprehensive collection-to-delivery coverage bundles first-mile pickup, ocean leg, customs clearance, and final distribution under unified liability. German automotive suppliers and Dutch pharmaceutical distributors favor this tier for REACH documentation continuity and just-in-sequence reliability requirements. Premium pricing captures margin pools from compliance-averse small and medium enterprises lacking in-house brokerage expertise.
- Port-to-Port:Maritime leg-only contracting suits large retailers with established inland distribution networks and captive customs declarants. Rotterdam-Hamburg corridors dominate volume placements, though Polish Baltic port alternatives are capturing Asia-Europe cargo seeking Suez bypass options.
- Terminal-to-Terminal:Handoff at origin and destination container yards appeals to industrial shippers with existing drayage contracts and preferential rail siding access. Cost discipline drives adoption among bulk commodity traders managing their own last-mile injection.
- Freight Forwarding:Non-asset-based coordination aggregates demand across multiple carrier contracts without operational execution. Platform-enabled forwarders are displacing traditional intermediaries through algorithmic capacity matching and real-time visibility.
Volume placements concentrate in Door-to-Door; the faster expansion belongs to Freight Forwarding as digital platforms compress transaction friction.
End User:
End-use concentration shapes capacity planning cycles and equipment specialization requirements across carrier networks.
- E-commerce:Direct-to-consumer fulfillment networks demand daily consolidation cycles, flexible cut-off times, and returns-handling infrastructure. Urban clusters in Germany's Rhine-Ruhr region and the Randstad generate sufficient shipment density to sustain dedicated LCL services with minimal dwell time.
- Retail:Seasonal inventory pre-positioning drives peak-quarter volume spikes requiring surge capacity commitments. Fast-fashion importers prioritize speed-to-shelf over pure transport cost minimization, favoring multimodal combinations with predictable transit variance.
- Manufacturing:Component supply chains tolerate longer transit windows in exchange for cost efficiency on non-critical parts. Czech and Hungarian inland hubs are capturing manufacturing-driven consolidation as production relocates from higher-cost western European locations.
- Automotive:Just-in-sequence parts delivery mandates precise arrival windows measured in hours, not days. Tier suppliers utilize dedicated LCL blocks within shared containers to maintain OEM production schedules without chartering full equipment.
Demand gravity centers on E-commerce fulfillment networks; Automotive commands premium rate structures despite smaller shipment volumes.
Delivery Mode:
Modal selection responds to EU Green Deal emissions accountability and Rhine corridor congestion dynamics.
- Rail Freight:Electric corridor expansion between North Sea and Mediterranean ports is tilting cost structures away from road dependency. Polish terminals at Małaszewicze and Sławków anchor Asia-Europe landbridge alternatives with customs pre-clearance capabilities.
- Sea Freight:Maritime backbone transport retains cost leadership on non-urgent cargo, though northern range port congestion elevates short-sea Mediterranean feeders. Spanish and Italian authorities subsidize bypass connections to Rotterdam and Hamburg saturation.
- Road Transportation:Germany's KBA truck tolling reforms and emissions trading compression are eroding margin viability for long-haul consolidators. Road retains dominance on sub-500km collection and distribution legs where rail siding access remains sparse.
- Air Freight:Velocity premium commands 8-15x maritime rates, restricting deployment to high-value, time-critical pharmaceuticals and electronics. Capacity constraints at Frankfurt and Amsterdam Schiphol limit expansion potential.
Rail Freight is climbing the fastest as electrification and carbon border adjustments restructure intermodal economics.
Packaging Type:
Packaging specification determines container utilization rates, damage liability allocation, and handling equipment requirements.
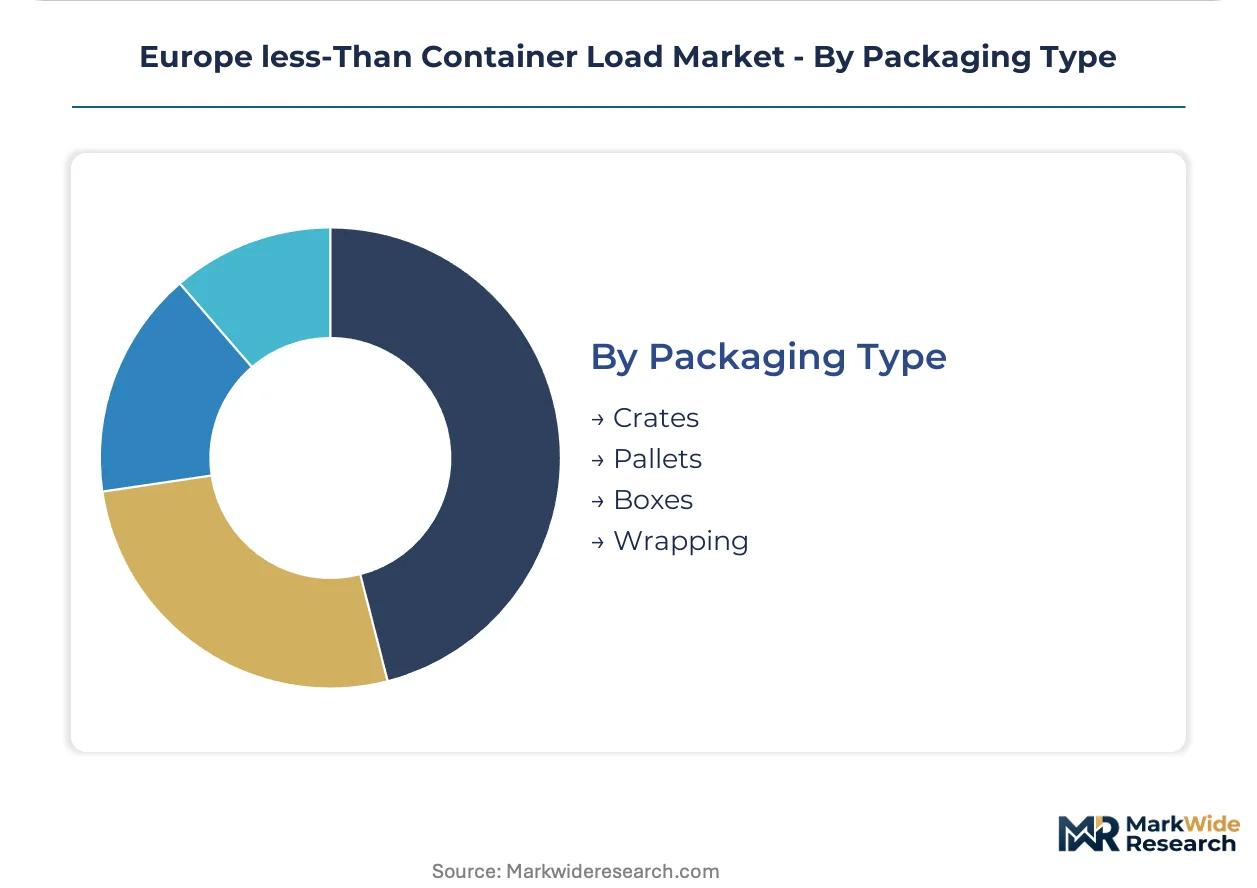
- Pallets:Standardized EUR-pool and CHEP equipment enables forklift handling and maximizes cubic efficiency in consolidated containers. Retail and manufacturing shippers dominate palletized flows through automated warehouse compatibility.
- Boxes:Corrugated fiberboard containers suit e-commerce parcel aggregation and apparel shipments with lower cube density. Modular box dimensions optimize stowage planning in mixed-load consolidations.
- Crates:Rigid wooden or plastic enclosures protect machinery components and high-value industrial equipment from stacking pressure. Automotive and capital goods sectors specify crate construction standards in procurement contracts.
- Wrapping:Stretch film and strapping secure irregularly shaped cargo and unitized bulk commodities without rigid containerization. Cost minimization drives adoption among commodity traders with established damage risk tolerance.
Pallet utilization dominates container volume; Box configurations are gaining share fastest from e-commerce parcel density growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Special Economic Zones and Małaszewicze terminal expansion are concentrating Asia-Europe rail consolidation flows away from congested North Sea ports. German KBA tolling reforms and Dutch carbon border adjustments are redirecting modal investment toward electric corridors and short-sea feeders.
Germany
Rhine-Ruhr automotive clusters and pharmaceutical distribution networks generate sustained LCL density for daily consolidation cycles. The KBA truck tolling reforms and EU Green Deal emissions trading compress road freight margins and elevate rail siding investment at Duisburg and Hamburg. Port congestion at Hamburg terminals pushes shippers toward inland pre-positioning hubs in North Rhine-Westphalia.
Netherlands
Randstad e-commerce fulfillment networks and Rotterdam gateway traffic sustain premium door-to-door service demand. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants and constrains reefer equipment availability for temperature-sensitive cargo flows. Terminal automation disputes at Rotterdam generate unpredictable dwell times that elevate short-sea Mediterranean bypass interest.
Poland
Małaszewicze and Sławków rail terminals capture Asia-Europe cargo seeking Suez alternatives with EU carbon border adjustment compliance. REACH documentation requirements for chemical shipments shape cargo acceptance protocols at Polish consolidation hubs. Silesian manufacturing relocation from western Europe generates component supply chain LCL demand with just-in-sequence tolerance windows.
Italy
Milan-Turin industrial corridors and Adriatic port feeders subsidized by regional authorities bypass saturated northern range terminals. The EU AI Act's risk classification framework applies to automated freight matching platforms handling hazardous materials documentation. Venice and Trieste terminals are capturing Balkan manufacturing consolidation with customs pre-clearance capabilities.
Spain
Barcelona and Valencia port authorities subsidize Mediterranean feeder connections that divert volume from Rotterdam-Hamburg congestion. The EU Green Deal's carbon border adjustment mechanism tilts cost structures toward electric rail corridors connecting to French distribution networks. Madrid logistics clusters are pre-positioning inventory for Iberian e-commerce final-mile injection.
Europe less-Than Container Load Market Competitive Landscape
Top-tier vendors anchor integrated multimodal networks, while mid-tier forwarders compete on digital platform efficiency and specialized vertical expertise. The market exhibits tiered concentration where asset-light technology platforms displace traditional brokerage through algorithmic cargo matching. Three archetypes dominate: integrated 3PLs with captive rail and terminal assets, digital-native freight aggregators, and automotive-focused specialists with just-in-sequence certification. Competitive moves center on multimodal infrastructure partnerships and AI Act-compliant audit trail development for automated allocation systems.
Among Nordic-integrated operators, DSV anchors cross-border consolidation flows into Scandinavia and the Baltic states through its hub network architecture. GEODIS occupies a position within automotive-specialist tiering, exemplifying just-in-sequence parts consolidation tied to OEM manufacturing schedules. Kuehne + Nagel represents technology-forward platform integration, with proprietary cargo aggregation systems optimizing container utilization across multiple European gateway ports.
| Leading Market Players |
|---|
| DSV |
| GEODIS |
| DB Schenker Logistics |
| Kuehne + Nagel |
| CEVA Logistics |
| DHL Group |
| Vanguard Logistics |
| ECU Worldwide |
| Dachser |
| Others |
Supply & Pricing Matrix
Certified customs declarants concentrated in Rotterdam and Hamburg command wage premiums that widen spreads between door-to-door and port-to-port service tiers. The EU Green Deal's carbon border adjustment mechanism feeds compliance cost differentials back into modal selection, with rail-dependent consolidators capturing margin relief unavailable to road-reliant competitors.
Pricing Analysis
Lead-time compression commands premium positioning, with just-in-sequence automotive blocks priced at multiples of standard consolidation slots. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed capacity commitments from spot-market availability and deferred sailings. Price differentiation tracks container utilization rates and customs complexity, with REACH documentation bundling lifting pharmaceutical tiers above commodity cargo. Cost compression in road-dependent segments is intensifying because Germany's KBA tolling reforms and emissions trading obligations erode long-haul viability. Small and medium enterprises lacking in-house brokerage expertise exhibit highest price sensitivity, while automotive OEMs prioritize reliability over rate minimization.
Supply Chain Analysis
Reefer container equipment rests on Chinese and South Korean manufacturing clusters constrained by the EU F-Gas Regulation's hydrofluorocarbon phase-down. Electric locomotive procurement draws from German and Polish rail technology suppliers, while chassis and intermodal assets source from Czech and Romanian fabrication hubs. Single-source vulnerability concentrates in refrigerated container availability, where regulatory-mandated equipment retrofitting outpaces manufacturing throughput. Distribution runs through Rotterdam and Hamburg gateway terminals, with Polish Baltic rail terminals capturing volume seeking Suez bypass routing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic cargo matching platforms are displacing legacy brokerage workflows across European LCL networks. This technology transition rewards operators with compliant audit trails under the EU AI Act's risk classification framework.
For Market Incumbents: Deploy multimodal infrastructure partnerships to counter digital-native freight aggregators eroding mid-tier market share. Backward integration into Polish and Baltic rail terminals secures capacity access as Asia-Europe landbridge volumes accelerate. Investment in AI Act-compliant algorithmic allocation systems defends against regulatory displacement of automated matching platforms.
For New Entrants and Emerging Players: Proprietary cargo aggregation software offers entry leverage against asset-heavy incumbents with legacy system debt. White-space concentration sits in short-sea Mediterranean feeders subsidized by Spanish and Italian port authorities, and in REACH-automated chemical compliance for pharmaceutical consolidations. Direct platform integration with e-commerce fulfillment networks provides the strongest go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with rail-terminal-integrated operators given EU Green Deal modal shift catalysts and carbon border adjustment compliance premiums. Long-term viability favors asset-light technology platforms with captive shipper networks over pure brokerage plays. Monitor Rhine waterway volatility episodes as inflection indicators for emergency modal shift demand and corresponding rate spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Rail Corridor Electrification | EU Green Deal carbon border adjustments tilt cost structures toward electric North Sea-Mediterranean connections. |
| AI Act Compliance Investment | Auditable algorithmic cargo allocation systems secure first-mover positioning under risk classification rules. |
| Baltic Landbridge Expansion | Polish terminal capacity captures Asia-Europe volume seeking alternatives to congested Suez routing. |
| Short-Sea Feeder Integration | Spanish and Italian port subsidies divert volume from Rotterdam-Hamburg saturation toward Mediterranean alternatives. |
| REACH Documentation Automation | Digital chemical compliance platforms reduce cargo acceptance delays for mixed-load pharmaceutical shipments. |
Research Methodology
Independent corroboration across freight forwarder operations directors, rail terminal managers, customs brokerage principals, and e-commerce logistics heads underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation against EU customs databases, port authority throughput statistics, ECHA REACH filings, and rail operator electrification disclosures. Bottom-up carrier capacity assessments and top-down trade flow analysis triangulate volume estimates.
Rate-of-change decomposition separates volume growth from modal mix shifts and pricing tier migration across the analysis window. Segmentation dimensions modeled include service type configuration, end-use industry concentration, delivery mode selection, and packaging specification. CAGRs derive from logistic curve fitting to historical throughput data and scenario-weighted regulatory impact assessment. Rhine waterway level variability and EU ETS carbon price trajectories serve as industry-specific forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including abrupt port labor disputes, unilateral trade policy reversals, and accelerated F-Gas Regulation phase-down schedules. Forecasts reflect assumptions about modal infrastructure completion timelines and carbon border adjustment enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Asia-Pacific Logistics Automation Market
Logistics and Shipping
Middle East Freight Forwarding Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
China Third-Party Logistics (3PL) Market
Logistics and Shipping
Spain Pharmaceutical Logistics Market
Logistics and Shipping
Global Automated Container Terminal Market