
 Qatar Freight and Logistics Market | 2026-2036
Qatar Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Freight and Logistics Market Analytics
Buyer concentration among e-commerce platforms and Qatari retailers is repositioning contract structures toward long-term warehousing partnerships and dedicated fleet arrangements. Gulf Warehousing Company sustains dominant coverage of bonded storage and free zone operations near Hamad Port. DHL Group leverages its express air network through Doha to capture time-sensitive pharmaceutical and electronics shipments. Milaha Maritime & Logistics anchors domestic last-mile distribution through its integrated port-to-warehouse pipeline.
Qatar freight and logistics encompasses the physical movement, storage, and customs clearance of goods across air, sea, and road modalities, typically operating within temperature-controlled parameters for pharmaceuticals and hazardous material protocols for hydrocarbon derivatives. Its primary commercial purpose is synchronizing inbound supply chains for construction and consumer goods with outbound LNG and petrochemical export schedules. Sea freight occupies the largest value share due to bulk hydrocarbon and construction material volumes through Hamad and Mesaieed ports. Air freight differentiates on perishables and high-value electronics where Qatar Airways Cargo's belly-hold and freighter capacity creates competitive advantage. Warehousing is concentrating around automated facilities employing RFID and warehouse management systems as customs compliance tightens.
Qatar's General Authority of Customs enforces the WCO SAFE Framework and advance cargo declaration rules that mandate pre-arrival data submission, directly filtering which logistics providers qualify for authorized economic operator status. The Ministry of Transport and Communications oversees road freight weight limits and driver qualification standards that shape fleet investment cycles. MOHAP pharmaceutical storage guidelines impose cold-chain verification requirements on warehouse operators serving the healthcare sector. Stakeholders must monitor how customs automation timelines and port capacity expansions at Ras Laffan Industrial City reshape routing decisions and capital deployment priorities.
Market Dynamics
Qatar's logistics sector is undergoing structural recalibration as FIFA World Cup legacy infrastructure redirects freight flows toward permanent industrial zones and e-commerce fulfillment networks reshape warehousing demand patterns around Doha.
Growth Catalysts
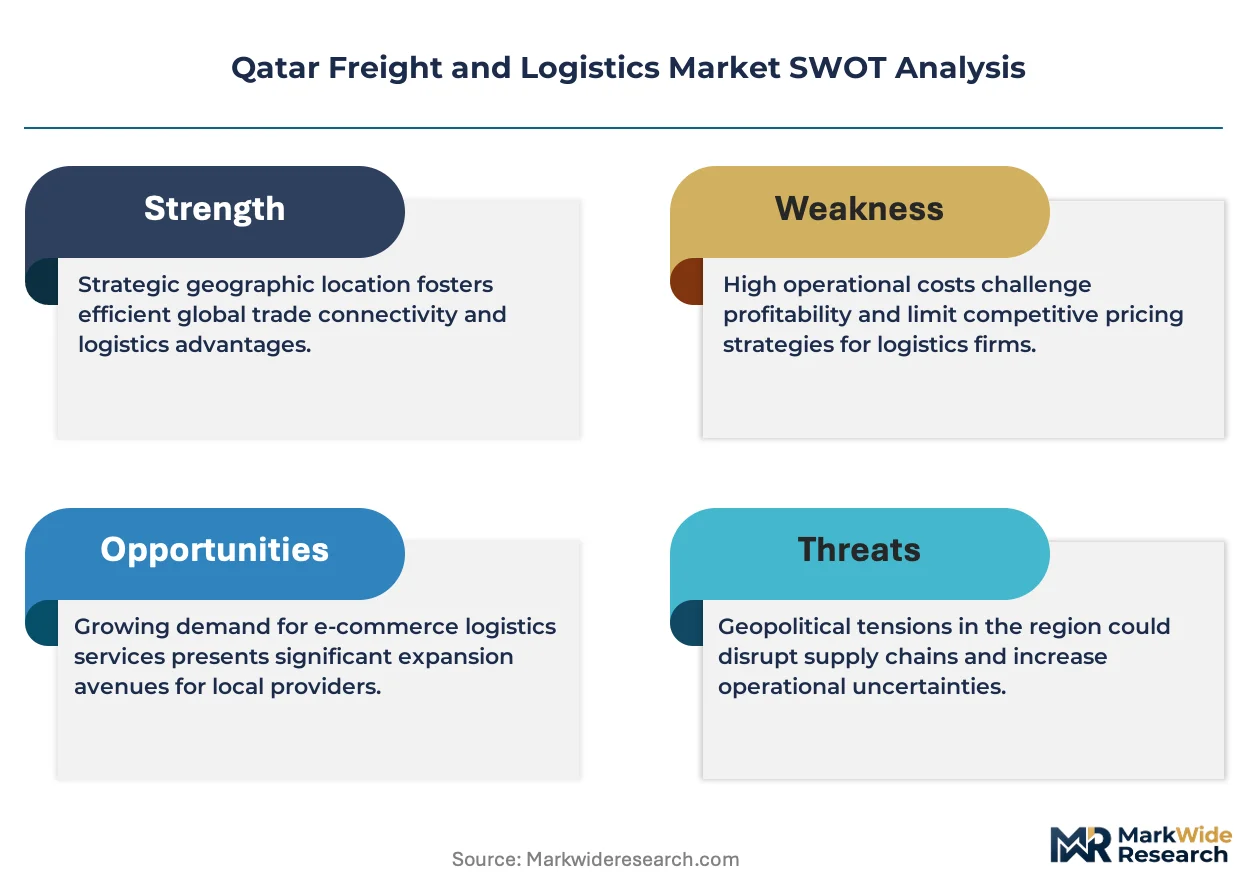
- LNG Export Expansion:Ras Laffan Industrial City's hydrocarbon processing capacity is pulling specialized heavy-lift and hazardous materials handling services into dedicated port corridors.
- General Authority of Customs Automation:The WCO SAFE Framework implementation is accelerating authorized economic operator certifications and reducing cargo dwell times for compliant logistics providers.
- Pharmaceutical Cold-Chain Investment:MOHAP storage guidelines are mandating temperature-verified warehouse infrastructure for healthcare distribution, creating premium service tiers.
Market Restraints
- Driver Qualification Bottlenecks:Ministry of Transport and Communications licensing requirements restrict fleet expansion timelines for road freight operators serving construction materials.
- Port Capacity Concentration:Hamad Port and Mesaieed collectively handle over 90% of containerized volumes, creating single-point vulnerability for import-dependent retailers.
- Land Scarcity Near Free Zones:Bonded warehouse development faces zoning restrictions in industrial areas adjacent to Ras Laffan, elevating real estate costs per pallet position.
Strategic Opportunities
- Al Wakrah Logistics Corridor:Underdeveloped warehousing capacity south of Doha offers first-mover positioning for e-commerce fulfillment centers serving residential expansion zones.
- RFID-WMS Convergence:Warehouse management systems integrating radio-frequency identification are enabling real-time inventory visibility for pharmaceutical distributors under MOHAP audit requirements.
- Long-Term Fleet Contracts:Retailer consolidation is creating demand for dedicated vehicle arrangements with telemetry integration, displacing spot-market trucking relationships.
Industry Challenges
- Cold-Chain Technician Scarcity:Refrigeration systems maintenance expertise lags behind pharmaceutical warehouse deployment, forcing operators into expensive service contracts with equipment vendors.
- Legacy Customs System Integration:Pre-arrival declaration mandates require ERP upgrades that smaller freight forwarders struggle to finance, threatening their authorized economic operator eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Freight and Logistics Market |
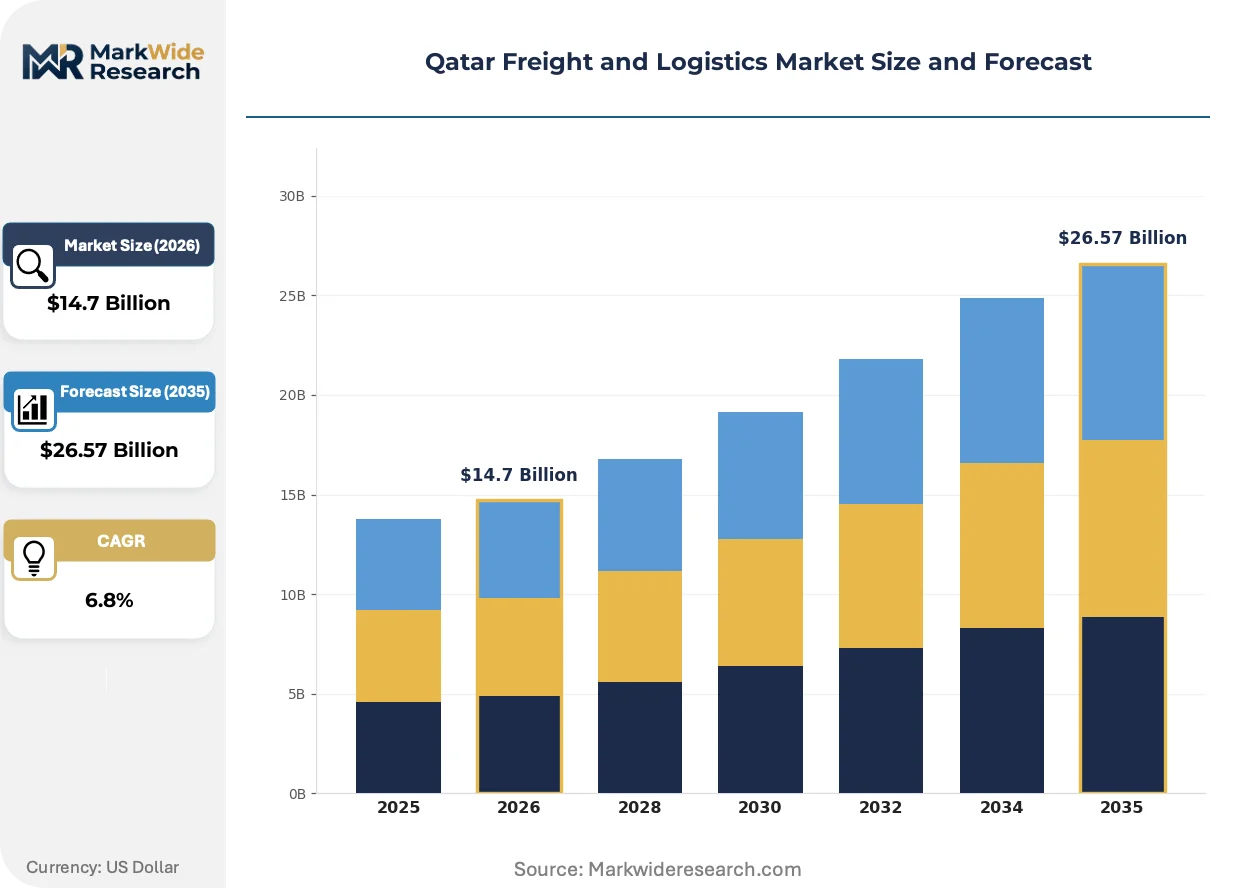
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Sea Freight, Road Freight, Warehousing Customer Type: Retailers, Manufacturers, E-commerce, Importers Technology: GPS Tracking, RFID, Warehouse Management System, Robotics End User: Automotive, Pharmaceuticals, Electronics, Construction |
| Companies Covered | Milaha Maritime & Logistics, A.P. Moller-Maersk, Gulf Warehousing Company (GWC), Aramex, DHL Group, Qatar Airways Group, Gulf Agency Company (GAC), Aero Freight Company, Nakilat, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Freight and Logistics Market Evolving Landscape
Digital infrastructure investments and regulatory compliance automation are reconfiguring how cargo data flows between shippers, customs authorities, and warehouse operators across Qatar's multimodal networks.
Blockchain-enabled documentation is converging with customs pre-clearance platforms to create immutable audit trails for high-value electronics and pharmaceutical shipments. Major retailers and healthcare distributors are piloting these systems to reduce inspection-triggered delays at Hamad Port. The technology is compressing clearance timelines from days to hours for compliant consignments.
Qatar's General Authority of Customs is enforcing advance cargo declaration rules that mandate electronic data interchange 24 hours before vessel arrival. This policy is eliminating paper-based processes for containerized imports and forcing freight forwarders into API-connected workflows. Pharmaceutical and perishable segments are responding fastest due to shelf-life sensitivity.
Retailer procurement teams are consolidating vendor panels around integrated port-to-warehouse service providers capable of bonded storage and last-mile delivery. This behavior is displacing fragmented arrangements with separate customs brokers, haulers, and warehouse operators. E-commerce platforms in Doha and Al Rayyan are driving the shift through volume guarantees and performance penalties.
Qatar Freight and Logistics Market Segmentation
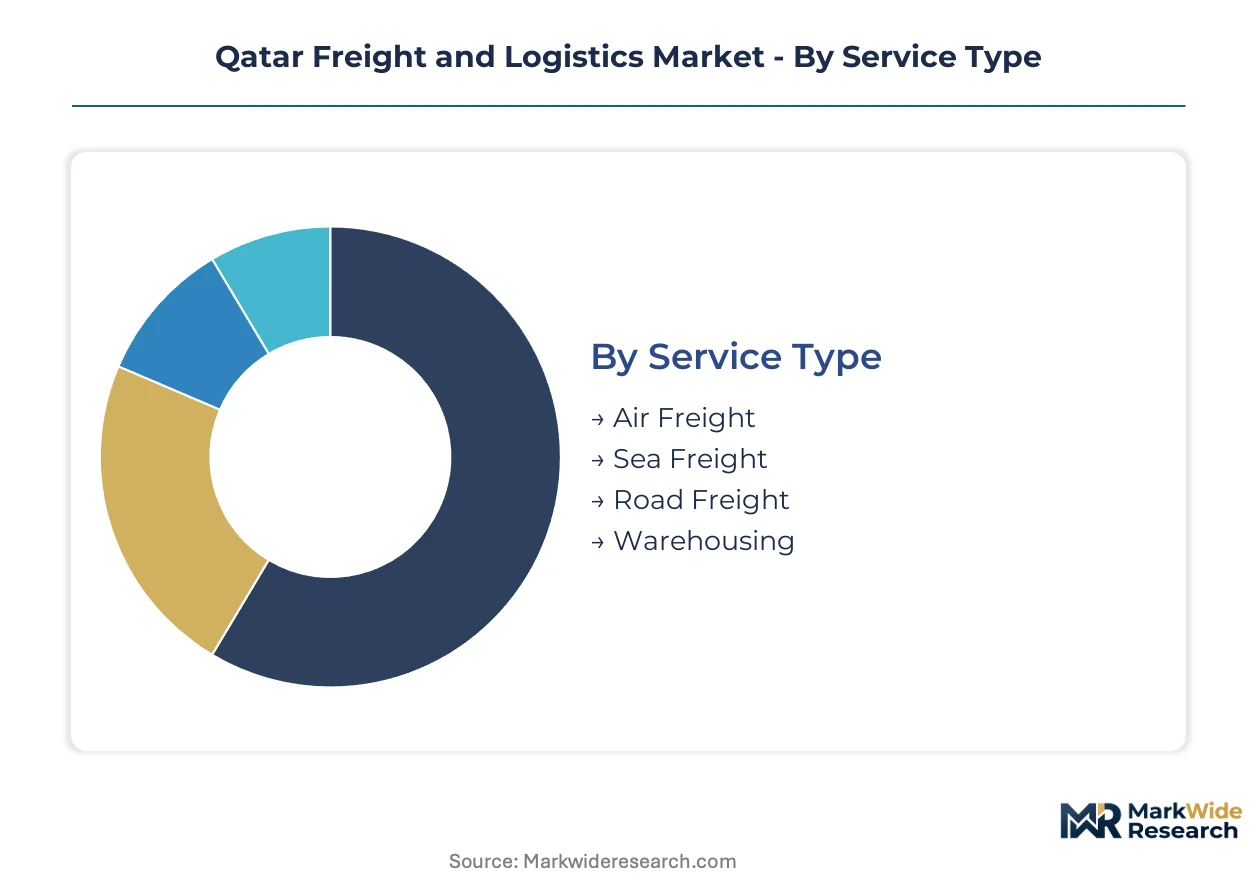
Freight and logistics operators in Qatar configure service portfolios around cargo characteristics, customer scale, and compliance intensity. Segmentation decisions directly determine capital allocation across port infrastructure, fleet composition, and warehouse automation tiers.
Service Type:
Customer choice hinges on speed-cost tradeoffs and cargo value density, with hydrocarbon exports and retail imports pulling divergent modal investments.
- Sea Freight:Containerized and bulk vessel movements through Hamad Port and Mesaieed anchor Qatar's hydrocarbon export economics and construction material imports. Ras Laffan Industrial City's LNG expansion sustains specialized heavy-lift demand for project cargo.
- Air Freight:Qatar Airways Cargo's belly-hold and dedicated freighter capacity targets temperature-sensitive pharmaceuticals and high-value electronics where dwell-time penalties exceed air premium costs. Doha's hub position captures Gulf transshipment flows.
- Road Freight:Last-mile distribution networks connect port terminals to Doha retail clusters and Al Wakrah residential zones under Ministry of Transport weight enforcement.
- Warehousing:Bonded storage and free zone facilities near Hamad Port integrate customs clearance with inventory positioning for importer consolidation programs.
Volume sits with Sea Freight; growth tilts toward Warehousing as e-commerce fulfillment demands automated inventory positioning.
Customer Type:
Contract structures vary by buyer scale, with volume guarantees and dedicated fleet arrangements displacing spot-market relationships among large accounts.
- E-commerce:Platform consolidation around Doha and Al Rayyan is driving demand for integrated port-to-warehouse pipelines with real-time inventory visibility and same-day delivery SLAs.
- Retailers:Qatari retail chains are consolidating vendor panels around long-term warehousing partnerships, forcing logistics providers into bonded storage investments near free zones.
- Manufacturers:Industrial clients serving Ras Laffan and Mesaieed require synchronized inbound parts supply with outbound finished goods scheduling.
- Importers:Fragmented import-dependent businesses rely on freight forwarders for customs brokerage and consolidated container sharing to manage General Authority of Customs compliance costs.
Revenue concentrates with Retailers; E-commerce is climbing the fastest as platform penetration reshapes last-mile infrastructure requirements.
Technology:
Regulatory mandates and customer audit requirements are filtering technology adoption by compliance tier and cargo value.
- Warehouse Management System:MOHAP pharmaceutical storage guidelines and customs automation timelines are mandating ERP-integrated inventory tracking for authorized economic operator eligibility.
- RFID:Radio-frequency identification enables real-time location tracking for high-value electronics and temperature-verified pharmaceutical lots under healthcare distributor audit protocols.
- GPS Tracking:Fleet telemetry integration supports dedicated vehicle contract performance monitoring and Ministry of Transport driver qualification verification.
- Robotics:Automated storage and retrieval systems are penetrating large-format e-commerce fulfillment centers where labor scarcity and throughput velocity justify capital deployment.
Adoption concentrates with Warehouse Management System; Robotics is gaining share fastest as labor costs and throughput demands intensify in Doha logistics zones.
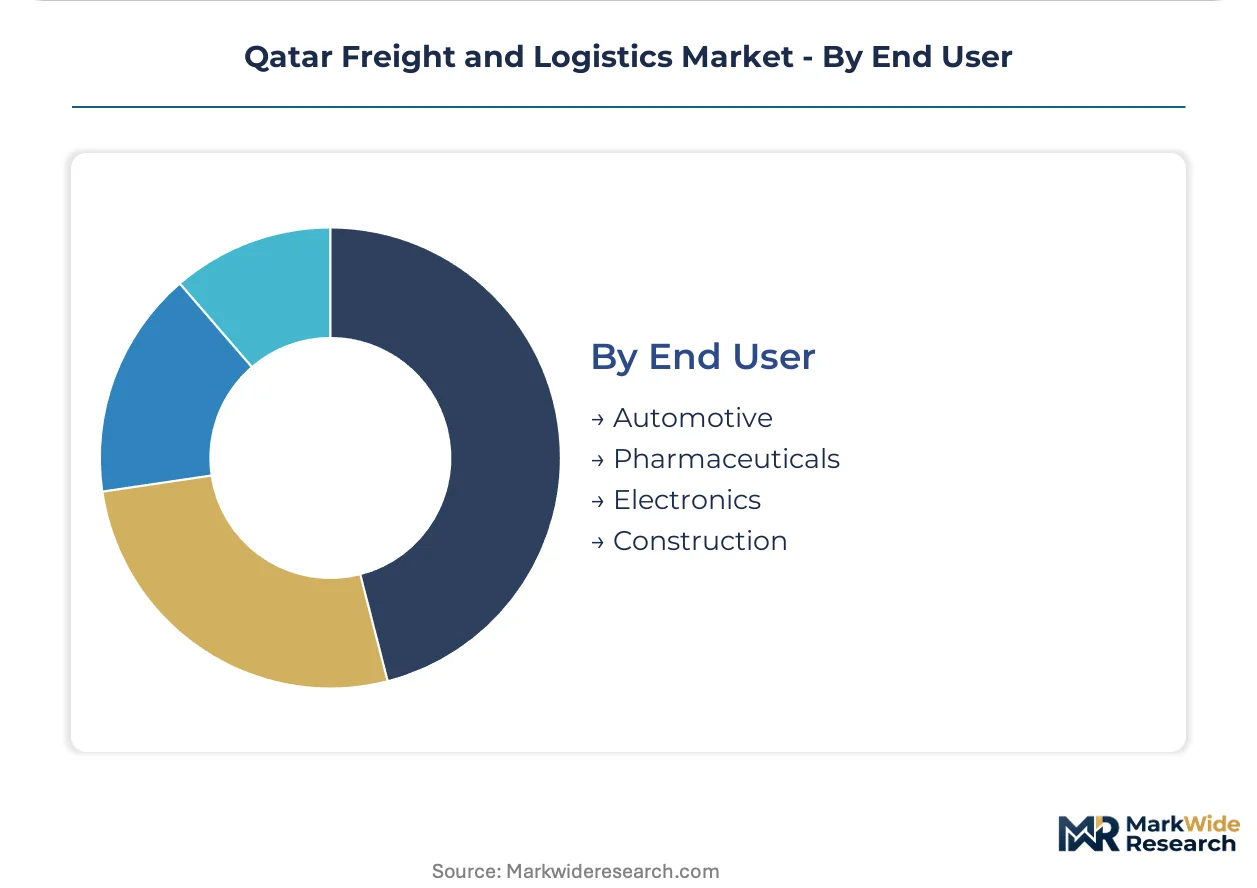
End User:
Cargo characteristics dictate handling protocols, with temperature sensitivity and hazardous material classification driving specialized infrastructure investments.
- Pharmaceuticals:MOHAP cold-chain verification requirements mandate temperature-mapped warehouse zones and continuous monitoring systems for vaccine and biologic distribution.
- Construction:FIFA World Cup legacy infrastructure and ongoing real estate development in Lusail and Al Wakrah sustain bulk cement, steel, and equipment import volumes through Hamad Port.
- Electronics:High-value consumer devices and semiconductor components require bonded storage, anti-static handling, and blockchain-enabled documentation for customs pre-clearance.
- Automotive:Vehicle and parts imports through Mesaieed support dealership networks and Ras Laffan industrial vehicle fleets under specific customs classification protocols.
Tonnage concentrates with Construction; Pharmaceuticals follows the steepest expansion trajectory as healthcare infrastructure investment and import substitution policies advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freight demand concentrates in Qatar's industrial corridor linking Doha to Ras Laffan, where hydrocarbon exports and construction imports generate asymmetric cargo flows. E-commerce fulfillment requirements are redistributing warehousing investment toward Al Wakrah and Lusail residential zones.
Doha Metropolitan Area
Hamad Port and Hamad International Airport anchor containerized imports and high-value air cargo, with Qatar Airways Cargo belly-hold capacity capturing pharmaceutical transshipments. The General Authority of Customs enforces advance cargo declaration rules that filter logistics provider eligibility through authorized economic operator certifications. Lusail's smart city infrastructure is absorbing FIFA World Cup legacy assets into permanent logistics parks.
Al Wakrah
Residential expansion south of Doha is generating underdeveloped warehousing demand for last-mile e-commerce distribution. The Ministry of Transport and Communications regulates road freight weight limits on routes connecting Mesaieed industrial zone to consumer clusters. New fulfillment center development faces land scarcity pressures as zoning prioritizes residential over industrial use.
Ras Laffan Industrial City
LNG export expansion drives specialized heavy-lift and hazardous materials handling through dedicated port corridors. Nakilat's maritime infrastructure supports hydrocarbon logistics requirements. The industrial city's bonded warehouse development confronts zoning restrictions that elevate real estate costs per pallet position.
Mesaieed
Petrochemical processing and bulk construction material imports concentrate containerized volumes alongside Hamad Port. Automotive parts distribution serves dealership networks and industrial vehicle fleets under specific customs classification protocols. Port automation mandates are reshaping compliance requirements for logistics operators serving manufacturing clients.
Qatar Freight and Logistics Market Competitive Landscape
Qatari operators anchor domestic warehousing and port-centric services; international specialists hold express air and maritime segments. Market structure tilts toward integrated providers capable of bonded storage, customs clearance, and last-mile delivery under single contracts. Two archetypes dominate: state-linked industrial conglomerates with captive port infrastructure, and global forwarders leveraging Doha's hub position for Gulf transshipment. Competitive moves concentrate on long-term warehousing partnerships with e-commerce platforms and dedicated fleet arrangements displacing spot-market relationships.
Within the domestic integrated tier, Milaha Maritime & Logistics and Gulf Warehousing Company occupy positions exemplifying port-to-warehouse pipeline control. Among international express specialists, DHL Group represents the archetype of air network leverage through Doha for time-sensitive pharmaceutical and electronics segments. These three anchors illustrate how contract structures are repositioning toward volume guarantees and performance penalties.
| Leading Market Players |
|---|
| Milaha Maritime & Logistics |
| A.P. Moller-Maersk |
| Gulf Warehousing Company (GWC) |
| Aramex |
| DHL Group |
| Qatar Airways Group |
| Gulf Agency Company (GAC) |
| Aero Freight Company |
| Nakilat |
| Others |
Value Network & Pricing Analysis
Refrigeration technician labor costs cascade through pharmaceutical cold-chain warehousing premiums, compressing margins for operators serving MOHAP-compliant facilities while elevating pricing tiers for bonded storage near Hamad Port.
Pricing Analysis
Volume sits with sea freight bulk hydrocarbon movements; margins concentrate in pharmaceutical air freight and temperature-verified warehousing. Three-tier pricing structure across premium cold-chain, standard bonded storage, and economy spot-market trucking reflects certification intensity under General Authority of Customs automation timelines. Pricing pressure stems from driver qualification bottlenecks restricting fleet expansion for construction material haulers. Importers fragmented across small freight forwarders exhibit highest price sensitivity; LNG exporters and integrated e-commerce platforms lock in long-term contracts with performance penalties.
Supply Chain Analysis
Single-source vulnerability sits with Hamad Port and Mesaieed collectively handling over 90% of containerized volumes, creating import-dependent retailer exposure. Equipment and fleet assets draw from Germany, Japan, and South Korea for specialized cold-chain and heavy-lift capabilities. Refrigeration systems maintenance expertise constitutes a critical input gap forcing expensive vendor service contracts. Tariff exposure runs through customs automation mandates requiring ERP upgrades that smaller operators struggle to finance. Distribution runs through integrated port-to-warehouse pipelines displacing fragmented customs-broker-haulage arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Land scarcity near free zones props pricing for bonded warehouse positions, constraining supply response to e-commerce fulfillment demand surges.
For Market Incumbents: Deploy long-term fleet contracts with telemetry integration to capture retailer consolidation demand and displace spot-market relationships. Gulf Warehousing Company and Milaha Maritime & Logistics should expand automated storage capacity in Al Wakrah before zoning restrictions harden. Cold-chain technician training partnerships with equipment vendors defend against service contract margin erosion. For New Entrants and Emerging Players: Launch via underdeveloped warehousing capacity south of Doha targeting e-commerce fulfillment centers for residential expansion zones. RFID-warehouse management system convergence offers entry path for pharmaceutical distributors facing MOHAP audit requirements. First-mover positioning in Al Wakrah logistics corridor avoids direct confrontation with incumbent port-centric networks. For Investors and Strategic Acquirers: General Authority of Customs authorized economic operator certification acceleration is the leading indicator that compliant logistics providers will capture disproportionate volume growth. Target mid-cap operators with existing bonded storage infrastructure and API-connected customs workflows. Cold-chain technician workforce development signals sustainable competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Term Warehousing Partnerships | Retailer consolidation favors integrated port-to-warehouse providers under single contracts with volume guarantees. |
| RFID-WMS Integration | Real-time inventory visibility meets MOHAP pharmaceutical audit requirements and customs automation timelines. |
| Al Wakrah Fulfillment Expansion | Residential zone growth creates first-mover positioning for e-commerce last-mile infrastructure outside Doha congestion. |
| Cold-Chain Technician Training | Refrigeration expertise scarcity forces expensive vendor contracts; in-house capability unlocks margin recovery. |
| Authorized Economic Operator Certification | General Authority of Customs compliance filters eligibility for pre-arrival declaration benefits and reduced dwell times. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Qatar freight and logistics analysis. Primary interviews with fleet operations managers, warehouse automation specialists, customs brokerage executives, and pharmaceutical distribution directors combined with bottom-up and top-down triangulation. Secondary sources included General Authority of Customs automation directives, Ministry of Transport licensing records, MOHAP storage guidelines, and port authority throughput disclosures.
Segmentation granularity modeled service type, customer archetype, technology tier, and end-user industry across the projection horizon. CAGRs derived from volume trajectory analysis against infrastructure capacity expansion schedules and regulatory compliance timelines. Forecast inputs incorporated LNG export expansion curves, e-commerce platform penetration rates, and customs automation deployment phases without specifying implementation dates.
The model assumes a particular technology adoption path; alternative pathways for blockchain-enabled documentation or autonomous warehouse robotics would alter the outlook. Forecasts reflect assumptions about customs system integration timelines and cold-chain infrastructure investment continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Apparel Logistics Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
LAMEA Last Mile Delivery Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
Baggage Handling System Market