
 Singapore 3PL Market | 2026-2036
Singapore 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore 3PL Market Outlook
A persistent shortage of certified supply chain engineers and warehouse automation technicians is unwinding capacity expansion timelines for several operators. DHL Group leverages its integrated air-sea hub at Changi to sustain cross-border e-commerce volumes. YCH Group Pte Ltd anchors specialized pharmaceutical logistics through temperature-controlled facilities in the West Region. Keppel Logistics Pte Ltd competes on port-centric value-added services tied to the Tuas megaport development.
Third-party logistics (3PL) encompasses outsourced supply chain management functions including transportation, warehousing, inventory management, and order fulfillment, typically governed by service-level agreements specifying on-time delivery rates, inventory accuracy thresholds, and damage ratios. The primary purpose is to convert fixed logistics costs into variable expenses while accessing specialized infrastructure and expertise. Freight forwarding dominates service type revenue due to Singapore's entrenched position as a transshipment hub handling container flows between Asia and Europe. Value-added services represent the fastest-expanding segment as brands demand kitting, labeling, and reverse logistics support. E-commerce verticals command premium pricing for same-day delivery commitments, while scheduled delivery models retain stronger margins in healthcare and automotive contracts.
Singapore's Land Transport Authority coordinates heavy vehicle access rules that directly constrain last-mile fleet deployment in the Central Business District. The Infocomm Media Development Authority enforces data localization and cybersecurity standards for logistics platforms processing cross-border trade documentation. Enterprise Singapore administers productivity grants that subsidize warehouse automation and robotics adoption. Stakeholders must weigh port relocation timelines against automation investment cycles as Tuas operations progressively shift from Pasir Panjang.
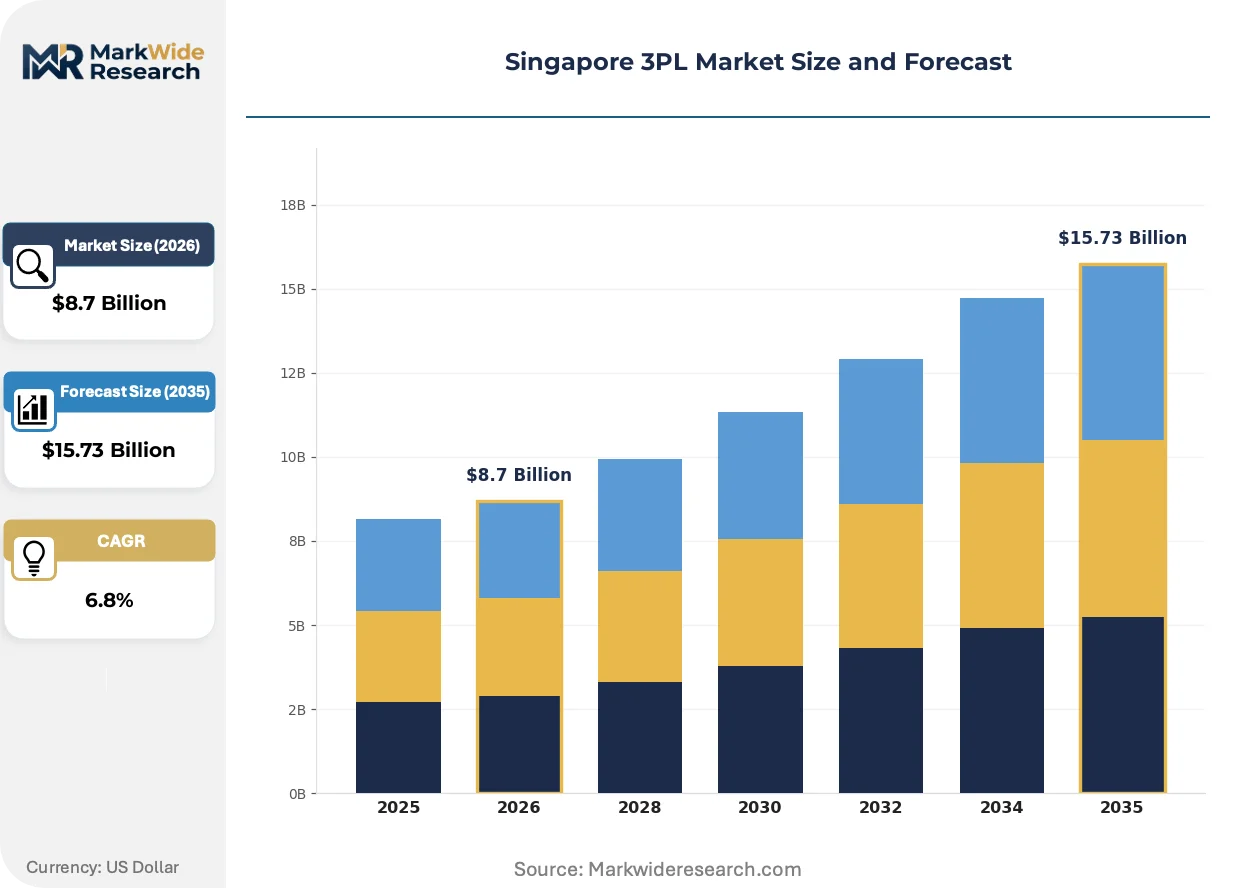
Market Dynamics
The Tuas Port relocation is compressing warehouse automation investment cycles against land scarcity constraints in western Singapore, forcing operators to consolidate multi-story facilities ahead of planned maritime traffic shifts.
Growth Catalysts
- Enterprise Singapore Productivity Grants:Subsidies covering robotics adoption and warehouse management system upgrades are accelerating automation deployment in Jurong logistics parks. Cold-chain operators access preferential funding for temperature-controlled infrastructure.
- Pharmaceutical vertical expansion:Biologics manufacturing investments by multinational drugmakers are generating specialized 3PL demand for GDP-compliant storage and distribution. Temperature excursion protocols now exceed standard pharmaceutical requirements.
- Cross-border e-commerce volumes:Southeast Asian consumer platforms are routing fulfillment through Singapore's bonded zones to exploit preferential trade agreements. Same-day delivery commitments to Johor Bahru and Batam are expanding last-mile networks.
Market Restraints
- Industrial land scarcity:Government land sales release limited parcels annually, constraining greenfield warehouse development. Lease rates in established logistics zones have compressed operating margins for asset-heavy operators.
- Certified technician shortage:The national training pipeline produces insufficient warehouse automation engineers and cold-chain equipment specialists. Recruitment timelines for maintenance roles now extend six to nine months.
- Heavy vehicle access restrictions:Land Transport Authority regulations limit diesel truck movements in the Central Business District during peak hours, constraining last-mile fleet routing efficiency for urban deliveries.
Strategic Opportunities
- Tuas Port zone development:The phased opening of container terminals creates first-mover advantage for port-centric value-added services. Bonded warehouse integration with automated container handling systems remains underdeveloped.
- Reverse logistics specialization:E-commerce return volumes exceed 25 percent of outbound flows in electronics and fashion verticals. Dedicated refurbishment and recommerce facilities command premium margins.
- Carbon accounting services:Infocomm Media Development Authority data localization requirements position Singapore-based 3PLs as compliance partners for scope-three emissions tracking across ASEAN supply chains.
Industry Challenges
- Multi-story automation integration:Vertical warehouses require specialized conveyor systems and automated storage retrieval configurations that legacy warehouse management platforms cannot orchestrate without substantial customization.
- Cybersecurity certification timelines:Cross-border trade documentation platforms must achieve Infocomm Media Development Authority compliance before processing commercial data, delaying operational launches for digital-native entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore 3PL Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Value-Added Services Industry Vertical: E-commerce, Retail, Healthcare, Automotive Delivery Model: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, Standard Delivery Customer Type: Small Businesses, Enterprises, Startups, Government |
| Companies Covered | DHL Group, DB Schenker, CEVA Logistics, YCH Group Pte Ltd, Keppel Logistics Pte Ltd, Kuehne + Nagel, CWT Ltd, DSV, Singapore Post Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore 3PL Market Strategic Shifts
Automation deployment is splitting between brownfield retrofit constraints and greenfield integrated design, with regulatory pressure on emissions and labor productivity forcing divergent capital strategies across operator portfolios.
Autonomous mobile robots are bifurcating warehouse labor models in Singapore's logistics parks. E-commerce fulfillment centers deploy fleet-based goods-to-person systems to compress pick rates, while pharmaceutical operators retain human oversight for serialization compliance. The technology is bifurcating facility economics: greenfield developments integrate ceiling-mounted infrastructure, while brownfield retrofits face aisle-width limitations that constrain robot density.
Enterprise Singapore's productivity grant framework is tightening eligibility criteria toward measurable labor savings. Operators must demonstrate headcount reduction or throughput improvement to secure robotics subsidies. Cold-chain facilities face additional energy efficiency thresholds that favor ammonia-based refrigeration over conventional systems.
Consolidated procurement of 3PL services by regional headquarters functions is displacing country-level logistics contracts. Multinational manufacturers now mandate ASEAN-wide inventory visibility and standardized service level agreements. Electronics and healthcare verticals in Singapore anchor these regional tenders, leveraging the city's trade documentation infrastructure and bonded zone network.
Singapore 3PL Market Segmentation
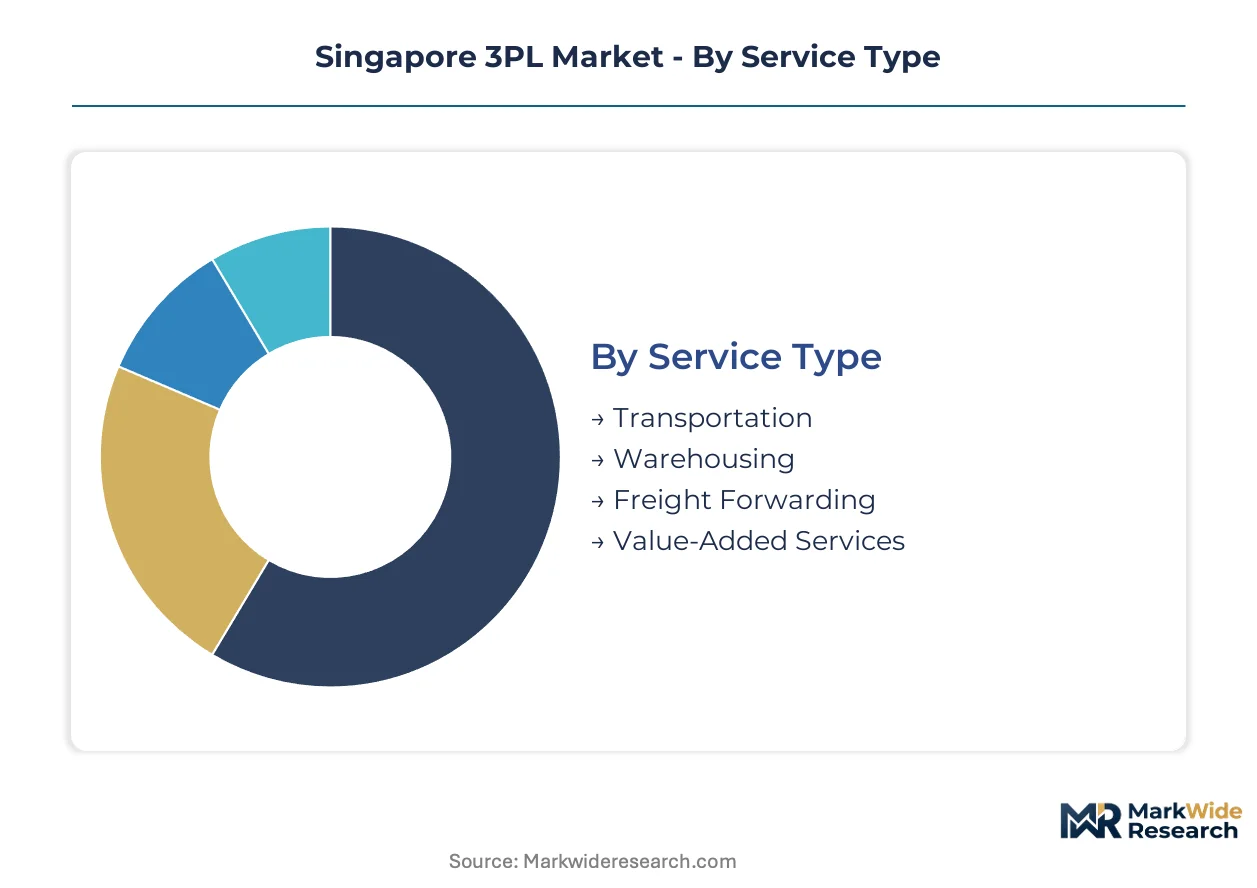
Segmentation in Singapore's 3PL market reveals how service specialization maps to margin architecture. Operators configure asset-light versus asset-heavy positions across service tiers, with automation intensity and regulatory compliance separating premium from commodity offerings.
Service Type:
Margin pools concentrate in integrated service bundles where warehousing automation and freight forwarding capabilities overlap, while standalone transportation contracts face rate compression from fleet oversupply.
- Freight Forwarding:Transshipment coordination between Asia and Europe anchors revenue through Singapore's port infrastructure. Demand concentrates in air-sea intermodal contracts serving electronics and pharmaceutical exporters, with Changi Airport's cargo terminals providing cold-chain connectivity for temperature-sensitive shipments.
- Value-Added Services:Kitting, labeling, and reverse logistics command premium pricing as brands outsource pre-retail preparation. E-commerce return volumes exceeding 25 percent of outbound flows in electronics and fashion verticals are expanding dedicated refurbishment facility footprints.
- Transportation:Fleet-based last-mile and line-haul services operate on thin margins constrained by diesel access restrictions in the Central Business District.
- Warehousing:Multi-story automated facilities in Jurong and Tuas zones compete on throughput efficiency and bonded zone integration.
Freight forwarding holds installed capacity. Value-added services is rotating up the share rankings.
Industry Vertical:
Application-specific compliance requirements create defensive moats, with GDP-certified pharmaceutical logistics and automotive sequencing services pricing at substantial premiums over retail distribution.
- Healthcare:Biologics manufacturing investments by multinational drugmakers generate specialized demand for temperature-controlled storage and distribution. Temperature excursion protocols now exceed standard pharmaceutical requirements, with Enterprise Singapore productivity grants subsidizing ammonia-based refrigeration upgrades.
- E-commerce:Same-day delivery commitments to Johor Bahru and Batam are expanding cross-border last-mile networks through Singapore's bonded zones.
- Automotive:Just-in-time sequencing contracts for regional assembly plants require precise inbound logistics coordination.
- Retail:Omnichannel fulfillment demands inventory visibility across online and physical channels, compressing margins through service complexity.
Healthcare holds installed capacity. E-commerce is climbing the fastest.
Delivery Model:
Speed-based tiering stratifies pricing power, with guaranteed same-day windows extracting premiums while scheduled delivery retains stronger margins in contractually stable healthcare and automotive relationships.
- Same-Day Delivery:E-commerce platforms fund premium logistics costs to secure market share in Southeast Asian consumer markets. Fleet deployment concentrates in western Singapore corridors connecting Jurong logistics parks to Tuas Port and cross-border causeways.
- Scheduled Delivery:Fixed-route pharmaceutical and automotive contracts provide predictable revenue with lower operational volatility than on-demand models.
- Next-Day Delivery:Regional e-commerce fulfillment through Singapore's bonded zones balances speed against customs clearance efficiency.
- Standard Delivery:Cost-optimized consolidation services compete primarily on rate, with limited differentiation beyond network coverage.
Scheduled delivery holds installed capacity. Same-day delivery is gaining share fastest.
Customer Type:
Procurement consolidation patterns separate volume-scaled enterprise tenders from fragmented small-business demand, with regional headquarters functions increasingly mandating ASEAN-wide service standardization.
- Enterprises:Multinational manufacturers anchor regional logistics tenders through Singapore, leveraging trade documentation infrastructure and bonded zone networks for ASEAN inventory visibility.
- Small Businesses:Flexible contract terms and shared warehousing access lower entry barriers, though per-unit costs exceed enterprise rates significantly.
- Startups:Digital-native entrants prioritize API-integrated fulfillment platforms with minimal capital commitment.
- Government:Public sector procurement emphasizes compliance certification and local employment quotas over cost optimization.
Enterprise contracts hold installed capacity. Small business segments are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in western Singapore logistics corridors while peripheral zones face rate compression from land scarcity and infrastructure gaps. The Jurong Innovation District and Tuas Port zone command lease premiums against eastern industrial areas with weaker port connectivity.
Jurong Innovation District
Advanced manufacturing clusters and pharmaceutical production facilities drive specialized cold-chain warehousing demand. Enterprise Singapore productivity grants subsidize robotics adoption in multi-story automated facilities. The district anchors integrated logistics parks serving biologics exporters with GDP-compliant temperature-controlled infrastructure.
Tuas Port Zone
Phased container terminal openings generate first-mover opportunities for port-centric value-added services and bonded warehouse integration. Land Transport Authority heavy vehicle access rules shape fleet deployment patterns for cross-border causeway traffic. The zone consolidates maritime trade flows as operations progressively shift from Pasir Panjang.
Changi Air-Sea Hub Corridor
Cross-border e-commerce volumes route through bonded zones exploiting preferential trade agreements with Southeast Asian markets. Infocomm Media Development Authority data localization requirements position logistics platforms as compliance partners for regional trade documentation. Same-day delivery networks expand toward Johor Bahru and Batam.
Central Business District Periphery
Last-mile fleet efficiency constraints from diesel truck movement restrictions during peak hours compress operating margins for urban delivery operators. Limited warehouse footprints force reliance on micro-fulfillment nodes and shared consolidation facilities. Premium pricing for guaranteed delivery windows partially offsets regulatory cost burdens.
Singapore 3PL Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Singapore's 3PL market. Integrated global networks with proprietary air-sea infrastructure occupy premium positions, while asset-light operators compete on flexible contract terms for mid-market segments. Three archetypes dominate: port-centric specialists leveraging Tuas megaport development, pharmaceutical cold-chain operators with GDP certification moats, and e-commerce fulfillment platforms with automated warehouse density. Competitive moves center on multi-story facility consolidation ahead of port relocation timelines and strategic partnerships for ASEAN regional network coverage.
Among integrated global networks, DHL Group anchors cross-border e-commerce volumes through its Changi air-sea hub infrastructure. YCH Group Pte Ltd exemplifies pharmaceutical specialization with temperature-controlled facilities in the West Region. Keppel Logistics Pte Ltd occupies a port-centric position tied to Tuas megaport development and value-added service integration.
| Leading Market Players |
|---|
| DHL Group |
| DB Schenker |
| CEVA Logistics |
| YCH Group Pte Ltd |
| Keppel Logistics Pte Ltd |
| Kuehne + Nagel |
| CWT Ltd |
| DSV |
| Singapore Post Limited |
| Others |
Value Chain & Pricing Dynamics
GDP certification tiers for pharmaceutical logistics simultaneously gate supplier qualification and stratify pricing power, with cold-chain operators commanding substantial premiums over ambient storage providers while uncertified competitors face exclusion from biologics contracts entirely.
Pricing Analysis
Configured-to-order pricing for specialized pharmaceutical and automotive contracts extracts margins substantially above standard warehousing rates, with three-tier pricing structure across premium, standard, and economy levels separating GDP-certified cold-chain facilities from bonded zone operators and commodity transportation providers. Price differentiation hinges on certification grade and vertical integration depth, with automated multi-story facilities in Jurong pricing above brownfield retrofits constrained by aisle-width limitations. Cost compression in standard delivery tiers is intensifying because fleet oversupply and diesel access restrictions compress operating margins, while enterprise buyers with regional ASEAN mandates exhibit lowest price sensitivity due to consolidated procurement scale.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical and automotive verticals, with biologics manufacturers and regional assembly plants demanding precise inbound coordination that tolerates minimal buffer stock. Supply concentration centers on China for warehouse automation equipment, Germany for conveyor systems, and Japan for robotics components, creating dependencies on specialized capital goods imports. Raw material inputs include lithium-ion batteries for electric last-mile fleets, ammonia-based refrigeration systems for cold-chain upgrades, and steel for multi-story facility construction. Single-source vulnerability in certified technician training pipelines extends recruitment timelines six to nine months. Distribution runs through bonded zones at Changi and Tuas for cross-border e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tuas Port relocation timelines compress automation investment cycles, creating a high-growth disruption as operators must consolidate multi-story facilities before maritime traffic shifts complete.
For Market Incumbents: Compound automation density in Jurong and Tuas zones ahead of port relocation deadlines, securing first-mover positioning for port-centric value-added services while acquiring certified cold-chain technicians to unwind maintenance bottlenecks that threaten capacity expansion timelines. For New Entrants and Emerging Players: GDP certification fast-track through Enterprise Singapore productivity grants unlocks pharmaceutical vertical entry, with dedicated refurbishment and recommerce facilities for e-commerce returns representing the most penetrable white-space target given 25 percent return volumes in electronics and fashion verticals. For Investors and Strategic Acquirers: Enterprise Singapore's tightening grant eligibility toward measurable labor savings reshapes the acquisition landscape, favoring operators with demonstrated robotics deployment and ammonia refrigeration conversion over asset-light intermediaries lacking automation infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Story Facility Consolidation | Jurong and Tuas automation density captures port relocation premiums. |
| GDP Certification Investment | Biologics manufacturing demand requires temperature-controlled infrastructure compliance. |
| Reverse Logistics Specialization | E-commerce return volumes exceed 25 percent in electronics and fashion verticals. |
| Cross-Border Last-Mile Expansion | Same-day delivery commitments to Johor Bahru and Batam exploit bonded zone connectivity. |
| Carbon Accounting Service Launch | Infocomm Media Development Authority data localization positions ASEAN compliance partnerships. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with logistics park operators, supply chain directors at pharmaceutical manufacturers, warehouse automation engineers, and Land Transport Authority planning officers; and secondary validation through Enterprise Singapore grant disbursement records, Infocomm Media Development Authority compliance filings, Jurong Town Corporation land lease data, and customs bonded zone throughput statistics. Bottom-up facility capacity assessments and top-down market sizing triangulated volume estimates.
Across the projection horizon, the analytical framework modeled service type segmentation, industry vertical compliance requirements, delivery model speed tiers, and customer procurement consolidation patterns. CAGRs were derived from facility automation deployment trajectories, port relocation phase timelines, and productivity grant absorption rates. Forecast inputs incorporated cold-chain infrastructure buildout schedules and certified technician pipeline constraints.
Underlying assumptions cover sustained biologics manufacturing investment, Tuas Port phase openings proceeding as scheduled, and Enterprise Singapore grant continuity, with deviation risk concentrated in industrial land release delays and cross-border e-commerce regulatory shifts. Revision becomes warranted when certified technician shortage severity crosses thresholds that stall automation deployment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Apparel Logistics Market
Logistics and Shipping
IoT Spend by Logistics Industry Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
Germany Same Day Delivery Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Empty Container Repositioning Optimization Platforms Market
Logistics and Shipping
Peru Freight and Logistics Market