
 Mexico Freight Forwarding Market | 2026-2036
Mexico Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Freight Forwarding Market Insights
Asset-light leasing models for cross-border trucking fleets are reshaping competitive dynamics among Mexico freight forwarding providers. Deutsche Post DHL Group leverages its bonded warehouse network to dominate pharmaceutical cold chain corridors. Kuehne + Nagel International AG anchors its position through specialized automotive parts logistics serving OEM assembly plants. Traxión sustains regional competitiveness with its integrated ground transportation platform across Mexican manufacturing hubs.
Freight forwarding encompasses the coordination and documentation of cargo movement across international borders, encompassing customs brokerage, carrier selection, cargo consolidation, and multimodal routing optimization with transit time guarantees typically ranging from two days for air to fourteen days for ocean. Its primary commercial purpose centers on reducing landed costs and transit variability for shippers lacking in-house logistics capabilities. Road freight commands the largest volume share given Mexico's extensive highway network and nearshoring-driven cross-border trucking surge, while air freight captures premium margin pools from time-sensitive electronics and pharmaceutical shipments. Door-to-door delivery mode is expanding fastest as manufacturers seek single-accountability logistics partners.
Mexico's customs administration operates under the Servicio de Administración Tributaria digital platforms, while surface transport safety falls under SCT oversight with NOM standards governing vehicle weights and hazardous materials handling. These frameworks shape demand by mandating bonded carrier certification and real-time cargo tracking for cross-border eligibility. Stakeholders must monitor evolving USMCA origin verification protocols and their downstream effects on documentation intensity and compliance costs.
Market Dynamics
Nearshoring-driven manufacturing relocation from Asia is compressing cross-border transit windows and forcing freight forwarders to integrate real-time visibility platforms with USMCA-compliant documentation systems.
Growth Catalysts
- USMCA origin verification protocols:Stricter regional content rules are compelling manufacturers to document supply chain provenance, expanding demand for customs brokerage services that validate qualifying criteria across automotive and electronics sectors.
- Bajío manufacturing corridor expansion:Querétaro, Guanajuato, and Aguascalientes are attracting foreign direct investment in aerospace and automotive clusters, generating concentrated freight volumes requiring specialized handling equipment and bonded warehousing.
- Servicio de Administración Tributaria digital platforms:Mexico's customs modernization is accelerating clearance velocities through automated risk profiling, reducing dwell times at Laredo-Columbia and Otay Mesa border crossings.
Market Restraints
- Cross-border trucking capacity concentration:Asset ownership concentrates among established carriers with bonded certifications, limiting new entrant access to USMCA-eligible lanes and inflancing spot market rates during peak seasonal demand.
- Diesel price volatility tied to Pemex supply constraints:Fuel represents the largest variable cost component for ground transportation, with price fluctuations directly compressing margins for non-hedged operators.
- Chassis availability bottlenecks at Mexican ports:Lázaro Cárdenas and Manzanillo face equipment shortages during agricultural export windows, extending container dwell times and disrupting scheduled sailings.
Strategic Opportunities
- Pharmaceutical cold chain corridors:Temperature-controlled logistics for biologics and vaccines remains underdeveloped outside Mexico City and Guadalajara, creating expansion potential for GDP-compliant warehouse networks in Monterrey and Tijuana.
- Intermodal rail integration:Kansas City Southern de México and Ferromex are expanding intermodal terminals, enabling freight forwarders to offer competitive alternatives to long-haul trucking on Mexico City-Monterrey-Laredo corridors.
- Electric vehicle battery logistics:Lithium-ion cell imports for Tesla's Nuevo León assembly plant and domestic OEM projects are generating demand for hazardous materials-certified handling and UN 38.3 testing documentation.
Industry Challenges
- Licensed customs broker scarcity:Mexico's agente aduanal certification requires multi-year apprenticeships and federal examination passage, constraining workforce scaling as transaction volumes surge.
- Real-time tracking integration with legacy TMS:Many mid-sized forwarders operate on decade-old transportation management systems that resist API connectivity with emerging IoT sensor networks and blockchain documentation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Freight Forwarding Market |
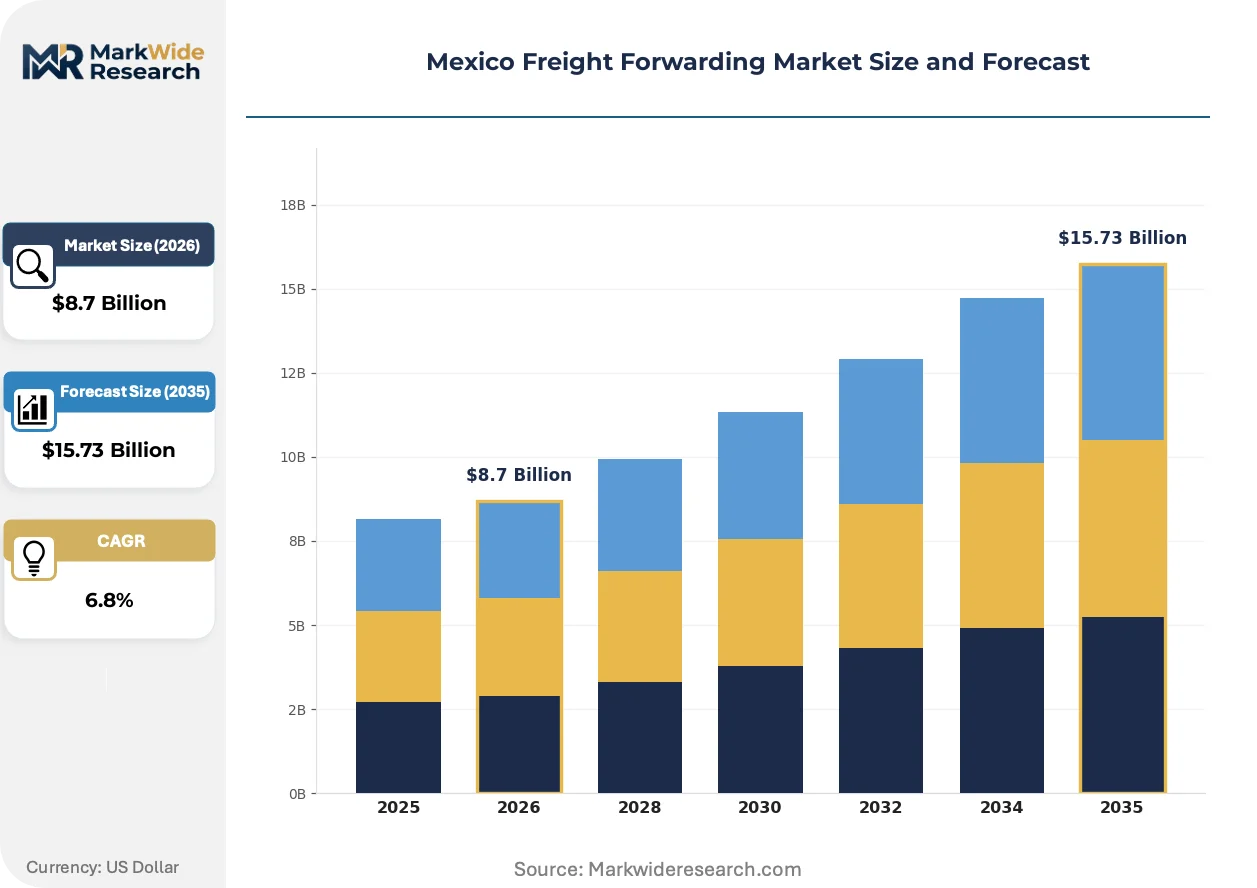
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Rail Freight, Road Freight Industry Vertical: Manufacturing, Retail, Automotive, Pharmaceuticals Delivery Mode: Door to Door, Port to Port, Terminal to Terminal, Airport to Airport Customer Type: Brokers, Exporters, Importers, Third-Party Logistics |
| Companies Covered | Deutsche Post DHL Group, Kuehne + Nagel International AG, DSV A/S, DB Schenker, Expeditors International, CEVA Logistics, C.H. Robinson, Traxión, FedEx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Freight Forwarding Market Trends and Innovations
Digital freight platforms are collapsing traditional information asymmetries between shippers and carriers, while regulatory pressure on emissions and security is accelerating technology deployment across Mexican logistics infrastructure.
Blockchain-enabled documentation is collapsing paper-based customs clearance workflows by creating immutable audit trails for USMCA origin certificates. Automotive OEMs and tier-one suppliers are mandating pilot implementations for high-value electronics shipments. This compression of verification timelines is eliminating days from cross-border transit windows previously lost to manual document reconciliation.
SCT hazardous materials regulations under NOM standards are tightening enforcement of lithium battery transport documentation and vehicle weight compliance. Forwarders must now deploy certified dangerous goods specialists at origin facilities. Electronics manufacturers shipping from Tijuana maquiladoras are restructuring packaging configurations to preempt inspection delays.
Shippers are consolidating vendor relationships around single-accountability logistics partners capable of door-to-door execution. The traditional separation of freight forwarding from ground transportation brokerage is dissolving. Automotive and aerospace manufacturers operating in Querétaro and Baja California are driving this integration most aggressively, demanding unified KPI dashboards spanning origin pickup through final-mile delivery.
Mexico Freight Forwarding Market Segmentation
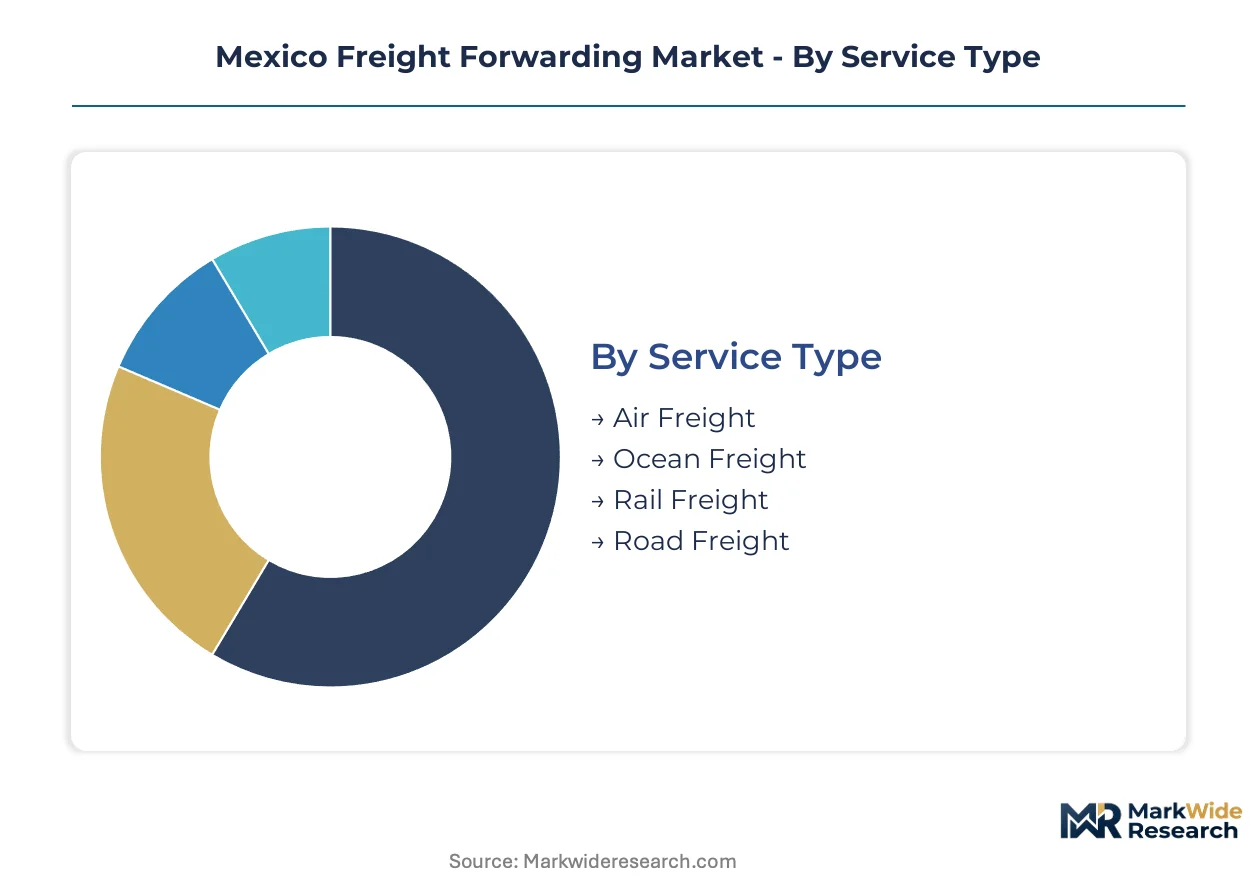
Freight forwarding segmentation in Mexico reveals distinct operational profiles across service modes and customer structures. Cycle-time differentials between air and ocean freight, combined with nearshoring-driven demand concentration in automotive and electronics corridors, determine competitive positioning and margin capture opportunities.
Service Type:
Air freight cycles inventory fastest, while ocean freight locks capital longest—this velocity spread shapes working capital requirements and customer selection criteria across forwarding portfolios.
- Road Freight:Cross-border trucking dominates volume flows through Laredo-Columbia and Otay Mesa corridors, with bonded carrier certification requirements filtering market access. Automotive OEMs expanding Bajío assembly operations drive sustained demand for USMCA-compliant documentation and real-time tracking integration.
- Ocean Freight:Containerized shipping through Lázaro Cárdenas and Manzanillo handles bulk agricultural exports and manufacturing inputs, constrained by chassis availability bottlenecks during seasonal peaks. Electronics manufacturers from Guadalajara clusters increasingly contract directly with NVOCCs to bypass intermediary markups.
- Air Freight:Time-definite services for pharmaceuticals and aerospace components command premium positioning, limited by Mexico City International Airport slot constraints and customs processing velocities.
- Rail Freight:Kansas City Southern de México and Ferromex intermodal terminals offer cost-competitive alternatives on Mexico City-Monterrey-Laredo lanes, though first-mile/last-mile coordination complexity slows adoption.
Road freight dominates installed base. Air freight is where expansion concentrates.
Industry Vertical:
Margin profiles diverge sharply between commoditized retail flows and specialized pharmaceutical cold chain requirements, with regulatory intensity acting as the primary segmentation filter.
- Automotive:Just-in-sequence delivery mandates from OEM assembly plants in Querétaro and Aguascalientes require bonded warehouse networks and EDI integration with tier-one supplier systems. USMCA origin verification protocols intensify documentation burdens for cross-border parts movements.
- Pharmaceuticals:Temperature-controlled logistics for biologics demands GDP-compliant warehouse infrastructure, concentrated in Mexico City and Guadalajara with emerging Monterrey capacity. SCT hazardous materials regulations under NOM standards govern lithium battery transport for medical devices.
- Manufacturing:Electronics and aerospace clusters in Baja California and Bajío corridor generate consolidated freight volumes requiring specialized handling equipment and customs brokerage scale.
- Retail:E-commerce fulfillment and seasonal import surges drive spot market volatility, with price sensitivity limiting forwarder margin capture compared to contracted automotive lanes.
Automotive commands the deepest forwarder relationships. Pharmaceuticals is climbing the fastest.
Delivery Mode:
Customer procurement patterns are shifting from fragmented point solutions toward unified accountability structures, collapsing traditional boundaries between forwarding and ground transportation.
- Door to Door:End-to-end execution with single-KPI dashboards is expanding most quickly as manufacturers seek reduced vendor management overhead. Aerospace and automotive producers in Querétaro and Baja California are driving this integration aggressively.
- Port to Port:Traditional FOB/CIF arrangements persist for bulk commodities and established trade lanes where shippers retain destination customs control.
- Terminal to Terminal:Rail intermodal and cross-border drayage segments use this structure, with chassis availability at Mexican ports creating operational friction.
- Airport to Airport:Premium electronics and pharmaceutical shipments utilize this mode, with Mexico City and Guadalajara cargo terminals serving as consolidation points for time-sensitive exports.
Door to door is gaining share fastest. Port to port retains volume leadership on bulk lanes.
Customer Type:
Broker consolidation and 3PL vertical integration are restructuring commission structures and direct customer access across the forwarding value chain.
- Third-Party Logistics:Integrated providers are absorbing traditional forwarding functions through proprietary customs brokerage licenses and captive trucking assets, compressing margins for standalone forwarders.
- Brokers:Independent intermediaries face margin pressure as digital freight platforms collapse information asymmetries and shippers demand direct carrier relationships.
- Exporters:Agricultural and manufacturing shippers in Sinaloa and Jalisco require seasonal capacity guarantees and cold chain certification for US market access.
- Importers:Electronics and automotive component buyers concentrate in Mexico City and Monterrey industrial parks, with USMCA compliance documentation driving brokerage selection criteria.
Third-party logistics providers dominate relationship control. Exporters represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's freight forwarding activity concentrates where export manufacturing clusters intersect with border infrastructure and port access. The country's trade surplus in automotive and electronics amplifies cross-border logistics intensity across specific industrial corridors.
Northern Border States
Chihuahua, Coahuila, and Tamaulipas host dense maquiladora networks shipping electronics and auto parts through Laredo-Columbia and Otay Mesa crossings. SAT digital platforms mandate real-time cargo tracking for bonded carrier eligibility. Ciudad Juárez and Reynosa generate concentrated freight volumes requiring USMCA-compliant documentation systems.
Bajío Region
Querétaro, Guanajuato, and Aguascalientes attract aerospace and automotive foreign direct investment driving specialized logistics demand. SCT hazardous materials regulations under NOM standards govern chemical inputs for manufacturing processes. Querétaro's aerospace cluster requires just-in-sequence delivery coordination with tier-one supplier networks.
Nuevo León
Monterrey anchors northern Mexico's industrial logistics with expanding pharmaceutical cold chain and electric vehicle battery supply chains. The state's environmental regulator enforces emissions standards for freight terminal operations. Apodaca and Santa Catarina industrial parks concentrate demand for bonded warehousing and hazardous materials-certified handling.
Jalisco
Guadalajara's electronics manufacturing and tequila export sectors generate diversified freight flows through Manzanillo port. Chassis availability bottlenecks at the port extend container dwell times during agricultural export windows. El Salto industrial corridor concentrates aerospace component suppliers requiring temperature-controlled logistics.
Mexico City Metro
The capital's consumer market and pharmaceutical distribution networks drive premium air freight and last-mile logistics intensity. AICM slot constraints limit cargo terminal expansion despite pharmaceutical and perishables demand growth. Toluca and Cuautitlán industrial zones concentrate automotive supplier parks requiring cross-border coordination.
Mexico Freight Forwarding Market Competitive Landscape
On the supply side, the industry is consolidating around integrated providers with captive customs brokerage licenses and bonded transportation assets. Asset-light digital platforms are compressing margins for traditional intermediaries while accelerating information transparency. Three archetypes dominate: global integrated logistics networks, regional trucking-forwarding hybrids, and specialized cold chain operators. M&A activity targets customs brokerage capabilities and cross-border trucking fleets.
Within the global network tier, Deutsche Post DHL Group and Kuehne + Nagel International AG exemplify multinational scale advantages through bonded warehouse networks and pharmaceutical cold chain infrastructure. Traxión represents the regional hybrid model with integrated ground transportation platforms spanning Mexican manufacturing hubs. These three anchors illustrate how competitive positioning separates global documentation scale from regional last-mile execution.
| Leading Market Players |
|---|
| Deutsche Post DHL Group |
| Kuehne + Nagel International AG |
| DSV A/S |
| DB Schenker |
| Expeditors International |
| CEVA Logistics |
| C.H. Robinson |
| Traxión |
| FedEx |
| Others |
Pricing and Supply Chain Analysis
Cross-border trucking capacity utilization at Laredo-Columbia and Otay Mesa corridors directly shapes supplier pricing power and buyer procurement flexibility. Tight bonded carrier certification requirements concentrate eligible capacity among established operators, forcing OEM procurement teams into longer contract terms during peak seasonal windows.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across automotive and electronics corridors. Price differentiation separates USMCA-compliant documentation tiers from standard brokerage services, with certification level and volume scale as primary drivers. Cost compression in spot market lanes is intensifying because digital freight platforms collapse information asymmetries between shippers and carriers. Retail importers exhibit highest price sensitivity, while pharmaceutical manufacturers accept premium positioning for GDP-certified cold chain handling.
Supply Chain Analysis
US export controls on semiconductor manufacturing equipment and advanced computing components constrain technology flows into Mexican electronics clusters. Component supply draws from China, South Korea, and Taiwan for electronics inputs, plus Germany and Japan for automotive precision parts. Raw material dependencies center on lithium-ion cells, semiconductor wafers, and specialized steel alloys. Single-source vulnerability concentrates in hazardous materials-certified chassis and bonded warehouse capacity. Distribution runs through integrated 3PL networks with captive customs brokerage licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's freight forwarding sector sits at an inflection point where SAT digital platform mandates and USMCA origin verification protocols are simultaneously compressing margins and raising barriers to entry.
For Market Incumbents: Insulate core automotive relationships through backward integration into bonded warehousing at Querétaro and Aguascalientes industrial parks. Expand captive customs brokerage headcount to offset agente aduanal scarcity threatening transaction velocity. Digital freight platforms represent the primary substitution threat requiring proprietary visibility platform deployment to maintain pricing power. For New Entrants and Emerging Players: Monterrey pharmaceutical cold chain corridors offer the most penetrable white-space target, with GDP-compliant warehouse infrastructure underdeveloped relative to demand from biologics distribution. Electric vehicle battery logistics for Tesla's Nuevo León assembly plant presents a second entry vector requiring UN 38.3 hazardous materials certification. A specialized dangerous goods handling value proposition unlocks OEM direct relationships bypassing incumbent 3PL intermediation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated providers with captive trucking assets and customs brokerage licenses. Long-term viability across the projection horizon favors acquisition targets with established SAT platform integration and cross-border bonded carrier networks. The signal to monitor is chassis availability investment at Lázaro Cárdenas and Manzanillo ports as indicator of operational commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Customs Brokerage License Acquisition | Agente aduanal certification scarcity creates defensive moats against digital platform entrants. |
| Bonded Warehouse Network Expansion | USMCA origin verification protocols intensify demand for SAT-compliant storage at Bajío manufacturing clusters. |
| Hazardous Materials Certification Investment | UN 38.3 lithium battery handling credentials unlock Tesla and domestic OEM EV supply chain access. |
| Real-Time Visibility Platform Deployment | IoT sensor integration with legacy TMS systems addresses automotive OEM just-in-sequence delivery mandates. |
| Intermodal Rail Terminal Partnerships | Kansas City Southern de México and Ferromex alliances offer cost-competitive alternatives to long-haul trucking. |
Research Methodology
Operator-level perspectives from customs brokerage directors, bonded carrier fleet managers, OEM logistics procurement leads, and SAT platform implementation specialists anchored the qualitative base. Secondary validation drew from Mexican customs administration bulletins, SCT transportation safety filings, USMCA compliance guidance documents, and cross-border trade flow databases. Bottom-up transaction volume estimates and top-down macroeconomic indicators were triangulated to establish market sizing boundaries.
Scenario-bracketing around nearshoring velocity, diesel price volatility, and customs modernization pace structured the analytical framework across the projection horizon. Segmentation dimensions modeled include service mode, industry vertical, delivery mode, and customer type. CAGRs were derived from elasticity-adjusted demand curves incorporating manufacturing FDI inflows and port capacity expansion timelines. Electric vehicle battery logistics demand and pharmaceutical cold chain infrastructure gaps served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light digital freight platforms would shift outcomes. Material shifts in USMCA enforcement intensity or Pemex diesel supply reliability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
IoT Spend by Logistics Industry Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
Ocean Freight Forwarding Market
Logistics and Shipping
Global Port Logistics Market
Logistics and Shipping
United States Freight Brokerage Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
Cargo Transportation Market
Logistics and Shipping
Colombia Third-Party Logistics (3PL) Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market