
 South Korea International Courier, Express, and Parcel (CEP) Market | 2026-2036
South Korea International Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea International Courier, Express, and Parcel (CEP) Market Insights
KC certification for drone delivery systems is unwinding competitive access, forcing operators to recalibrate fleet investments and compliance timelines. CJ Logistics leverages its integrated warehousing and last-mile network to dominate domestic express corridors. DHL Express anchors its Korean hub around Incheon International Airport, sustaining intercontinental air freight capacity. Pantos Logistics differentiates through specialized semiconductor and display panel logistics serving Samsung and LG supply chains.
South Korea International Courier, Express, and Parcel services constitute time-definite logistics solutions operating across air, ground, and maritime modes, with delivery commitments ranging from same-day to scheduled multi-day windows for documents through palletized freight. The sector functions as commercial infrastructure enabling just-in-manufacturing supply chains and direct-to-consumer e-commerce fulfillment. E-commerce customer type commands the largest volume pool, though scheduled delivery for corporate clients retains superior margin density due to contract stability and bulk pricing structures. Air delivery mode leads value contribution on cross-border lanes, while ground networks absorb the majority of domestic parcel density; drone delivery remains nascent, constrained by KC certification requirements and urban airspace management protocols.
The Korea Customs Service mandates advance cargo information filing through its UNI-PASS system, shaping clearance speed and carrier compliance costs for all international inbound flows. MFDS pharmaceutical import licensing and the Personal Information Protection Commission's data handling rules further constrain how CEP operators process cross-border consumer shipments. Stakeholders must monitor whether Seoul accelerates drone corridor approvals beyond the current Incheon and Jeju Island pilot zones, as this regulatory pivot would reshape capital expenditure allocation across the carrier base.
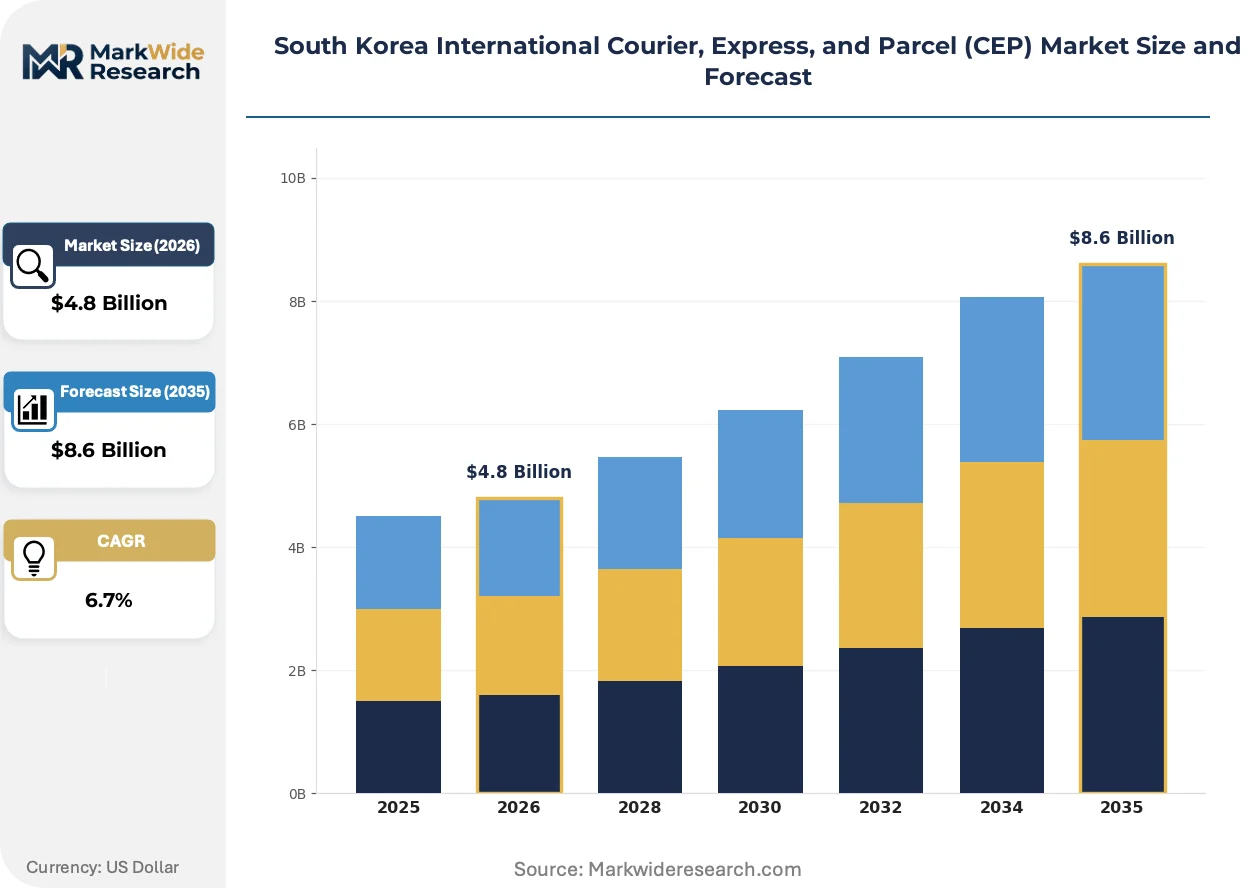
Market Dynamics
Cross-border e-commerce merchants are accelerating express delivery adoption while the Korea Customs Service's UNI-PASS automation compresses clearance timelines, creating a structural squeeze between volume surges and regulatory compliance investments.
Growth Catalysts
- Customs Modernization:UNI-PASS advance cargo information filing mandates are standardizing clearance workflows and reducing dwell times at Incheon port facilities.
- Semiconductor Supply Chains:Specialized logistics for Samsung and LG display panel shipments generate high-margin scheduled delivery contracts with predictable volume commitments.
- Drone Pilot Zones:Incheon and Jeju Island regulatory sandboxes are generating operational data for urban airspace management protocols ahead of broader KC certification.
Market Restraints
- KC Certification Barriers:Drone delivery system approval timelines extend fleet deployment schedules and concentrate investment risk among capitalized operators.
- Seoul Metropolitan Concentration:Over 60% of domestic parcel density flows through the capital region, creating last-mile bottlenecks and capacity strain during peak windows.
- Air Freight Capacity Limits:Incheon International Airport slot constraints restrict intercontinental express expansion for cross-border e-commerce volumes.
Strategic Opportunities
- Busan-Ulsan Corridor:Underpenetrated industrial zones in the southeast offer manufacturing logistics contracts outside the saturated Seoul market.
- Pharmaceutical Cold Chain:MFDS import licensing requirements create specialized service tiers with premium pricing for temperature-controlled biologics.
- Autonomous Ground Vehicles:Convergence of LiDAR navigation and warehouse robotics is enabling dark depot operations with reduced labor dependency.
Industry Challenges
- Data Localization Compliance:Personal Information Protection Commission rules constrain cross-border consumer shipment processing systems and require domestic server infrastructure.
- Pilot Certification Backlogs:Commercial drone operator licensing throughput limits fleet scaling velocity for aerial delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea International Courier, Express, and Parcel (CEP) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, International Shipping Delivery Mode: Ground, Air, Sea, Drone Customer Type: Retailers, E-commerce, Corporates, Individuals Package Type: Documents, Parcels, Pallets, Freight |
| Companies Covered | CJ Logistics, Korea Post (EMS), Hanjin Transportation, Lotte Global Logistics, DHL Express, FedEx, UPS, Pantos Logistics, DB Schenker, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea International Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital freight platforms and automated sortation systems are compressing operational latency while regulatory frameworks for unmanned aerial systems mature, reshaping capital allocation across air and ground networks.
Autonomous mobile robots in hub sortation facilities are supplanting manual parcel handling for standardized package dimensions. CJ Logistics and Lotte Global Logistics have deployed AMR fleets in their Gwangju and Icheon distribution centers, reducing sortation labor hours by approximately 40% for domestic express corridors. This automation is supplanting traditional fixed conveyor infrastructure and enabling dynamic warehouse layouts that adapt to seasonal volume spikes without structural retrofit.
The Korea Customs Service's e-commerce customs clearance simplification program is reducing documentation burdens for low-value consumer shipments under 150,000 KRW. This policy compression is accelerating clearance velocity for cross-border marketplace sellers and shifting compliance cost structures from per-shipment filing toward consolidated periodic declarations. Chinese and US-origin e-commerce parcels are the primary beneficiaries, with clearance times compressing from 48 hours to sub-6-hour windows for pre-registered merchants.
Direct-to-consumer brands are consolidating fulfillment partnerships with single-carrier express contracts rather than multi-provider rate shopping. This procurement consolidation is displacing freight brokerage intermediaries and forcing carriers to embed value-added services—returns processing, real-time tracking APIs, and customs duty prepayment—into base rate structures. The shift is most visible in beauty and electronics verticals, where subscription box merchants prioritize delivery reliability over marginal rate savings.
South Korea International Courier, Express, and Parcel (CEP) Market Segmentation
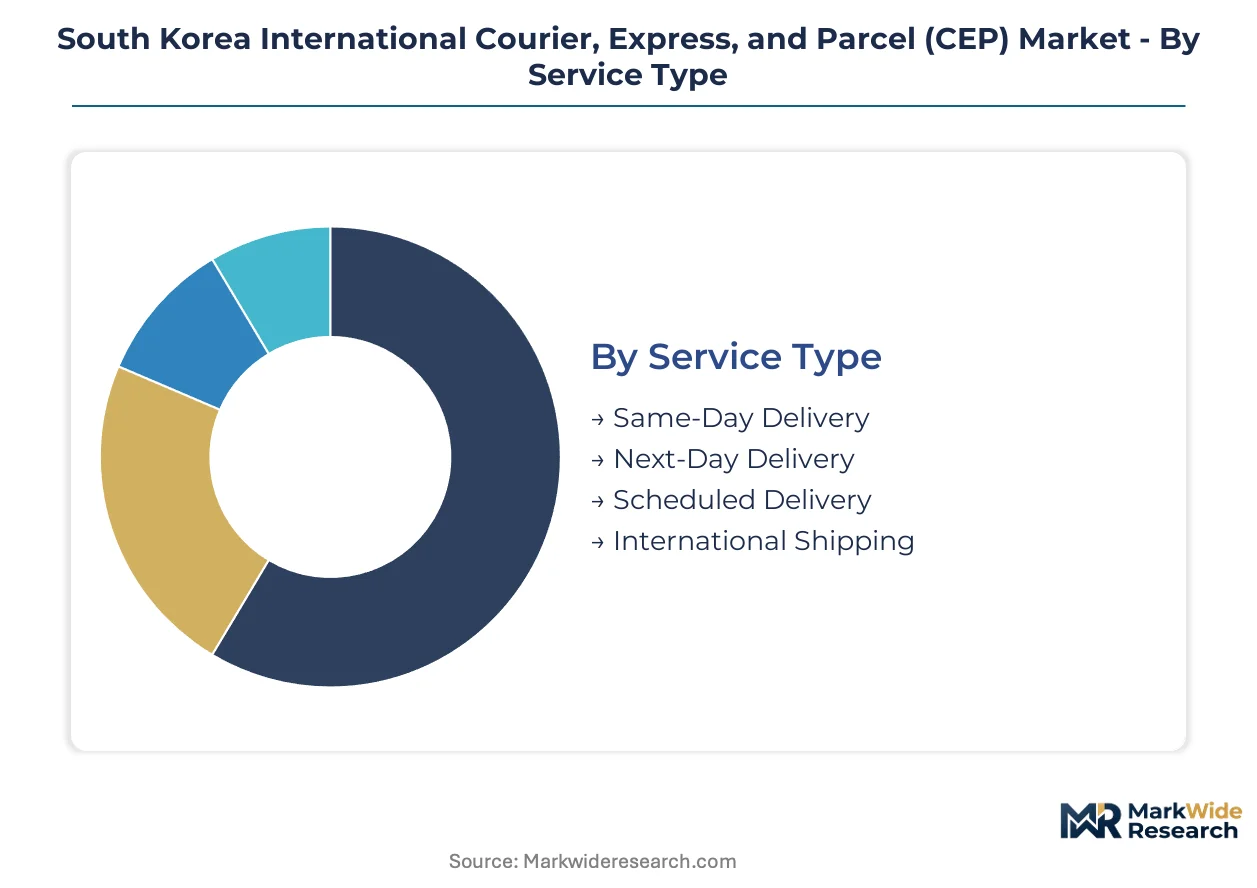
South Korea's CEP market fragments across four operational dimensions that determine carrier capital allocation and margin structure. Service type and delivery mode define infrastructure requirements, while customer and package type govern pricing power and contract stability.
Service Type:
Substitution pressure intensifies as e-commerce merchants compress delivery windows and autonomous systems erode traditional speed premiums.
- Same-Day Delivery:Ultra-time-critical service leveraging urban micro-fulfillment nodes and motorcycle courier networks. Seoul metropolitan demand from fashion and electronics verticals strains capacity during promotional windows, with MFDS pharmaceutical licensing adding compliance layers for medical shipments.
- Next-Day Delivery:Standard express commitment across domestic corridors using integrated air-ground networks. Busan-Ulsan manufacturing clusters generate predictable B2B volume outside Seoul saturation, though Incheon airport slot constraints limit cross-border scaling.
- Scheduled Delivery:Pre-arranged window service for corporate supply chains with predictable routing. Samsung and LG display panel logistics require specialized handling equipment and temperature-controlled vehicles for semiconductor components.
- International Shipping:Cross-border service governed by UNI-PASS advance filing mandates and customs clearance protocols. Chinese and US-origin e-commerce parcels dominate volume flows through Incheon Free Economic Zone.
Next-day delivery retains volume leadership; same-day delivery holds the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates capital-intensive air networks from ground infrastructure and emerging autonomous systems.
- Ground:Dense road network coverage absorbing majority of domestic parcel density. CJ Logistics and Lotte Global Logistics deploy autonomous mobile robots in Gwangju and Icheon distribution centers, reducing sortation labor hours substantially.
- Air:Intercontinental express capacity anchored around Incheon International Airport. Slot constraints restrict expansion for cross-border e-commerce volumes, forcing carriers to optimize existing freighter utilization.
- Sea:Maritime freight for non-urgent palletized cargo and consolidated container loads. Port automation at Busan and Incheon facilities compresses dwell times for scheduled industrial shipments.
- Drone:Nascent aerial delivery constrained by KC certification requirements and urban airspace management. Incheon and Jeju Island pilot zones generate operational data ahead of broader regulatory approval.
Ground networks capture volume dominance; drone delivery is expanding most quickly from regulatory sandbox foundations.
Customer Type:
Margin concentration favors contract stability and bulk pricing structures over transactional consumer volume.
- Retailers:Brick-and-mortar merchants requiring store replenishment and reverse logistics capabilities. Beauty and electronics verticals drive consolidation toward single-carrier express contracts with embedded returns processing.
- E-commerce:Direct-to-consumer marketplace sellers generating the largest volume pool. Personal Information Protection Commission data handling rules constrain cross-border consumer shipment processing systems.
- Corporates:Manufacturing and industrial clients with scheduled delivery contracts and predictable volume commitments. Semiconductor supply chains generate premium pricing for specialized logistics services.
- Individuals:Transactional C2C and B2C shipments with fragmented origin-destination pairs. Korea Customs Service e-commerce clearance simplification reduces documentation burdens for low-value consumer shipments under 150,000 KRW.
E-commerce commands volume leadership; corporate contracts maintain the steepest margin expansion trajectory.
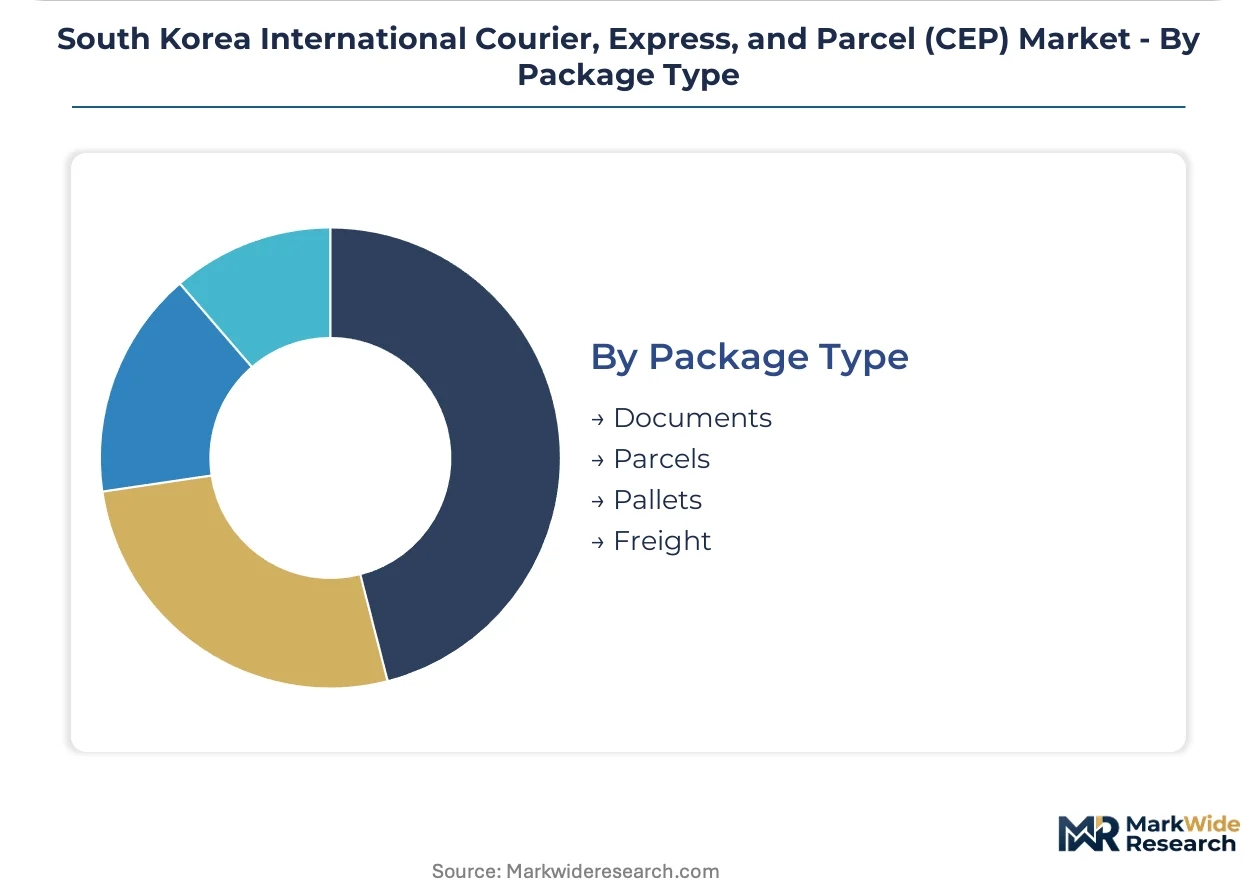
Package Type:
Application requirements dictate handling infrastructure from document pouches to palletized freight systems.
- Documents:Lightweight administrative and legal correspondence with minimal handling complexity. Digital substitution pressures transactional document volumes while certified originals sustain niche demand.
- Parcels:Standardized consumer and small-business shipments driving domestic express density. Automated sortation systems in hub facilities process standardized dimensions with reduced labor dependency.
- Pallets:Unitized freight for manufacturing supply chains and retail distribution. Semiconductor and display panel logistics require shock-resistant handling and cleanroom-compatible transport equipment.
- Freight:Bulk cargo movements outside parcel network specifications. Temperature-controlled biologics under MFDS import licensing create specialized cold chain service tiers with premium pricing structures.
Parcels retain volume leadership; freight commands the steepest value expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce merchants and semiconductor manufacturers concentrate demand across South Korea's metropolitan corridors, with logistics infrastructure clustering around customs gateways and industrial zones. The Korea Customs Service's UNI-PASS system and MFDS pharmaceutical licensing shape carrier compliance investments regionally.
Seoul Capital Area
Fashion and electronics verticals drive same-day delivery density through urban micro-fulfillment nodes. The Personal Information Protection Commission's data localization rules constrain cross-border consumer shipment processing systems. Gangnam and Yeongdeungpo logistics hubs absorb over 60% of domestic parcel volume, creating last-mile bottlenecks during promotional windows.
Busan-Ulsan Corridor
Manufacturing logistics contracts for automotive and shipbuilding supply chains generate predictable B2B volume outside Seoul saturation. Port automation at Busan facilities compresses dwell times for scheduled industrial shipments. Ulsan's petrochemical complexes anchor temperature-controlled freight movements for specialized chemical logistics.
Incheon Free Economic Zone
Cross-border e-commerce parcels from Chinese and US-origin marketplace sellers dominate volume flows through this customs modernization zone. The Korea Customs Service's e-commerce clearance simplification program accelerates sub-6-hour clearance windows for pre-registered merchants. Incheon International Airport slot constraints restrict intercontinental express expansion despite surging demand.
Daegu-Gyeongbuk
Textile and machinery manufacturing clusters generate scheduled delivery contracts with stable routing patterns. The region's underpenetrated industrial zones offer carriers manufacturing logistics opportunities beyond saturated capital markets. Gumi's electronics industrial complex sustains dedicated semiconductor component logistics corridors.
Gwangju-Honam
Autonomous mobile robot deployments in distribution centers reduce sortation labor hours for domestic express networks. Agricultural product exports through Mokpo port facilities create seasonal freight volume spikes. The region's logistics infrastructure supports Honam industrial belt manufacturing supply chains with dedicated ground networks.
South Korea International Courier, Express, and Parcel (CEP) Market Competitive Landscape
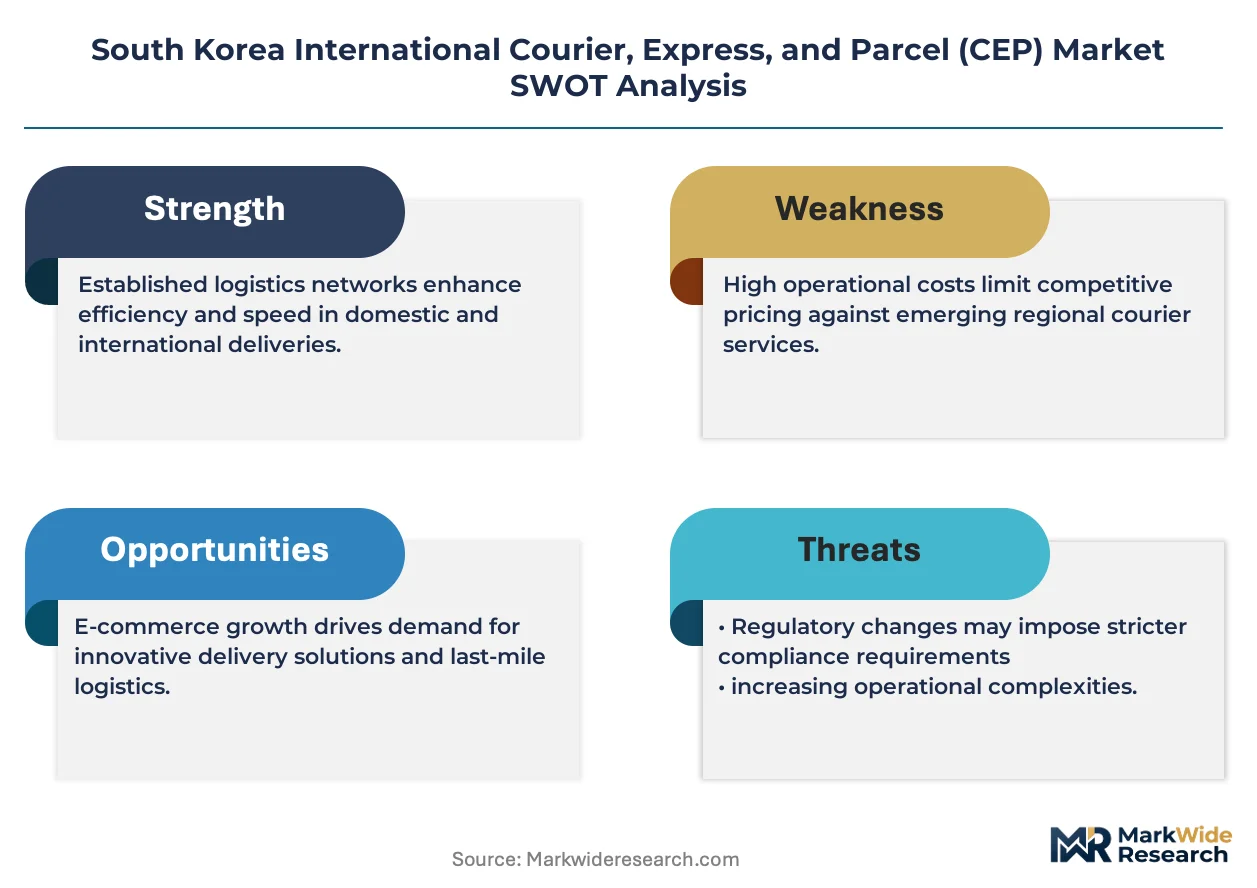
Player mix skews toward integrated domestic carriers with customs-bonded warehousing capabilities and global express networks anchored around Incheon air freight capacity. The market exhibits tiered concentration: national champions control last-mile density, global integrators dominate cross-border lanes, and specialized handlers capture high-margin semiconductor logistics. Strategic archetypes include vertically integrated conglomerate logistics arms, global express integrators with Korean hub operations, and niche semiconductor supply chain specialists. Dominant competitive moves encompass fleet automation investments and single-carrier contract consolidation by direct-to-consumer brands.
Within the integrated domestic tier, CJ Logistics and Lotte Global Logistics exemplify carriers leveraging autonomous mobile robot deployments and urban micro-fulfillment networks to compress sortation latency. Pantos Logistics occupies a specialized position serving Samsung and LG display panel supply chains with cleanroom-compatible transport equipment. DHL Express anchors the global integrator segment through its Incheon International Airport hub operations.
| Leading Market Players |
|---|
| CJ Logistics |
| Korea Post (EMS) |
| Hanjin Transportation |
| Lotte Global Logistics |
| DHL Express |
| FedEx |
| UPS |
| Pantos Logistics |
| DB Schenker |
| Others |
Pricing and Supply Chain Analysis
Long-term scheduled delivery contracts with corporate semiconductor and display panel manufacturers lock in both dedicated fleet capacity and predictable unit economics for specialized logistics operators. These agreements insulate carriers from spot-market volatility while embedding compliance costs for MFDS pharmaceutical licensing and Korea Customs Service UNI-PASS filings into negotiated rate structures.
Pricing Analysis
Cost-plus contracts with fuel surcharge indexation dominate cross-border express lanes, particularly for Chinese and US-origin e-commerce parcels routed through Incheon Free Economic Zone. Three-tier pricing structure across premium express, standard delivery, and economy deferred tiers separates time-definite commitments from flexible-window alternatives. Cost compression in economy tiers is intensifying because autonomous mobile robot deployments at CJ Logistics and Lotte Global Logistics facilities reduce sortation labor overhead. E-commerce marketplace sellers exhibit highest price sensitivity, while Samsung and LG supply chain contracts retain lowest sensitivity due to specialized handling requirements and penalty clauses for delivery failure.
Supply Chain Analysis
China and the United States anchor cross-border parcel origination for South Korea's international CEP flows, with Vietnam and Japan contributing secondary manufacturing logistics corridors. Jet fuel and aviation ground services draw from Incheon International Airport slot-constrained infrastructure, while last-mile motorcycle courier networks rest on dense urban micro-fulfillment node coverage. Single-source vulnerability concentrates in Incheon airport capacity for intercontinental express, with no viable secondary hub for trans-Pacific freighter operations. Distribution runs through integrated carrier networks with customs-bonded warehousing rather than fragmented freight brokerage intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's CEP market sits in a cyclical recovery phase driven by semiconductor capital expenditure cycles and cross-border e-commerce inventory restocking. The analysis window favors operators with embedded compliance infrastructure and automation-enabled cost structures.
For Market Incumbents: Compound defensive moats by deepening autonomous ground vehicle deployments in Gwangju and Icheon distribution centers to compress sortation labor costs further. Secure additional KC certification for drone delivery systems ahead of regulatory corridor expansion beyond Incheon and Jeju Island pilot zones, as early-mover compliance positioning will concentrate aerial network access among capitalized operators. Threat substitution from digital freight platforms demands channel control through direct API integrations with major marketplace sellers.
For New Entrants and Emerging Players: Differentiate on pharmaceutical cold chain specialization under MFDS import licensing requirements, where temperature-controlled biologics command premium pricing and incumbent coverage gaps persist. Target Busan-Ulsan manufacturing corridor contracts for automotive and shipbuilding supply chains, the most penetrable geography outside Seoul metropolitan saturation. Go-to-market angle should emphasize scheduled delivery reliability with dedicated fleet commitments rather than competing on express lane speed.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated logistics arms with captive semiconductor customer relationships and customs-bonded warehousing assets. Long-term viability over the next decade hinges on regulatory adaptation velocity rather than pure scale, favoring operators with demonstrated Korea Customs Service compliance automation. Watch KC certification approval timelines for drone delivery systems as the critical inflection indicator for aerial network capital reallocation across the carrier base.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Mobile Robot Fleet Expansion | CJ Logistics and Lotte Global Logistics deployments reduce Gwangju and Icheon sortation labor hours substantially. |
| Drone Delivery KC Certification Investment | Accelerates regulatory approval beyond Incheon and Jeju Island pilot zones for aerial network scaling. |
| Pharmaceutical Cold Chain Infrastructure | MFDS licensing compliance enables premium service tiers for temperature-controlled biologics imports. |
| Busan-Ulsan Corridor Capacity Addition | Captures underpenetrated manufacturing logistics contracts outside saturated Seoul metropolitan markets. |
| UNI-PASS System Integration Partnership | Korea Customs Service advance filing automation compresses clearance timelines for cross-border e-commerce. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Korea Customs Service regulatory filings, MFDS pharmaceutical licensing databases, and Incheon Free Economic Zone trade statistics. Primary interviews engaged logistics operations directors, e-commerce supply chain managers, semiconductor procurement leads, and customs brokerage specialists across Seoul, Busan, and Incheon clusters. Secondary validation drew from UNI-PASS system documentation, carrier fleet deployment disclosures, and autonomous vehicle pilot program reports. Bottom-up volume modeling triangulated against top-down market sizing from customs clearance data.
Segmentation dimensions modeled span service type, delivery mode, customer archetype, and package category across the projection horizon. Analytical framework incorporated semiconductor manufacturing cycle indicators, cross-border e-commerce merchant growth patterns, and KC certification approval velocity as industry-specific forecast inputs. CAGRs derived from trend extrapolation of customs modernization impacts and automation adoption curves rather than simple historical averaging.
Material uncertainties — regulatory acceleration or delay in drone corridor approvals, semiconductor capital expenditure contraction cycles, and Personal Information Protection Commission enforcement shifts — sit outside the modeled envelope. Forecasts reflect assumptions about continued UNI-PASS automation and stable aviation slot allocation at Incheon International Airport. Recalibration cycles align with material shifts in Korea Customs Service policy announcements and MFDS licensing requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Canada 3PL Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
Iraq Logistics Market
Logistics and Shipping
Nigeria Freight and Logistics Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Digital Freight Management Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Australia Last Mile Delivery Market