
 Inland Container Depot and Dry Port Market | 2026-2036
Inland Container Depot and Dry Port Market Size, Share, and Industry Trends Forecast 2026-2036
Inland Container Depot and Dry Port Market Insights
E-commerce fulfillment networks is pivoting toward dry port consolidation to reduce inland haulage costs and customs dwell times. Maersk leverages its integrated logistics platform to control end-to-end container flows from gateway ports to interior depots. DP World anchors mega-facility development across South Asia and Sub-Saharan Africa with dedicated rail links. Container Corporation of India (CONCOR) dominates domestic containerized rail movement through its statutory access to Indian Railways infrastructure.
An inland container depot (ICD) is a customs-notified area located away from seaports where containers are stored, inspected, and cleared before onward movement by rail or road, typically featuring gantry cranes with 40-tonne lifting capacity and bonded warehousing exceeding 100,000 square feet. Its primary commercial purpose is to decongest gateway ports by transferring customs and cargo-handling functions to interior logistics nodes. Warehousing services within the service-type dimension capture the largest margin pools due to extended inventory storage and value-added processing. Automated systems within the technology dimension are displacing manual gate operations and yard checks, though RFID tracking remains the dominant near-term investment category for real-time container location.
India's Central Board of Indirect Taxes and Customs (CBIC) mandates electronic sealing and risk-based inspection protocols that shape ICD operating procedures and capital expenditure patterns. The EU F-Gas Regulation and CSRD reporting requirements are forcing European dry port operators to electrify yard equipment and disclose supply-chain emissions. Stakeholders must monitor how customs digitization mandates and carbon-border adjustment mechanisms reshape facility location decisions and technology procurement priorities.
Market Dynamics
Customs digitization mandates and carbon-border adjustment mechanisms are compressing dwell times while forcing capital redeployment toward electrified yard equipment and bonded warehouse automation.
Growth Catalysts
- India's PLI scheme for logistics infrastructure:Production-linked incentives accelerate public-private depot development along the western corridor connecting JNPT to Delhi-NCR hinterlands.
- E-commerce fulfillment consolidation:Last-mile cost pressure pushes online retail networks toward dry port aggregation for containerized inventory staging.
- RFID tracking deployment:Real-time container location systems reduce manual yard checks and accelerate gate throughput at customs-notified facilities.
Market Restraints
- Land acquisition costs:Urban periphery land prices near major consumption centers constrain greenfield ICD expansion in India and Bangladesh.
- Rail infrastructure dependency:Domestic containerized rail movement requires statutory access agreements, limiting operator flexibility outside state-controlled networks.
- EU F-Gas Regulation compliance:Electrification mandates for yard cranes and reach stackers impose heavy retrofit capital burdens on European dry port operators.
Strategic Opportunities
- Sub-Saharan Africa rail-linked mega-facilities:Dedicated freight corridors connecting landlocked economies to coastal gateways remain underdeveloped relative to South Asian density.
- Automated gate systems convergence:Integration of optical character recognition with weighbridge automation compresses truck turnaround times at high-volume depots.
- India's Dedicated Freight Corridor:Dedicated passenger-free rail lines enable scheduled block train services between interior depots and gateway ports.
Industry Challenges
- Customs-IT system integration:India's CBIC electronic sealing mandates require expensive middleware development to connect legacy warehouse management systems with national risk-assessment platforms.
- Skilled gantry crane operators:Remote-container handling certification programs lag facility expansion timelines across emerging logistics corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inland Container Depot and Dry Port Market |
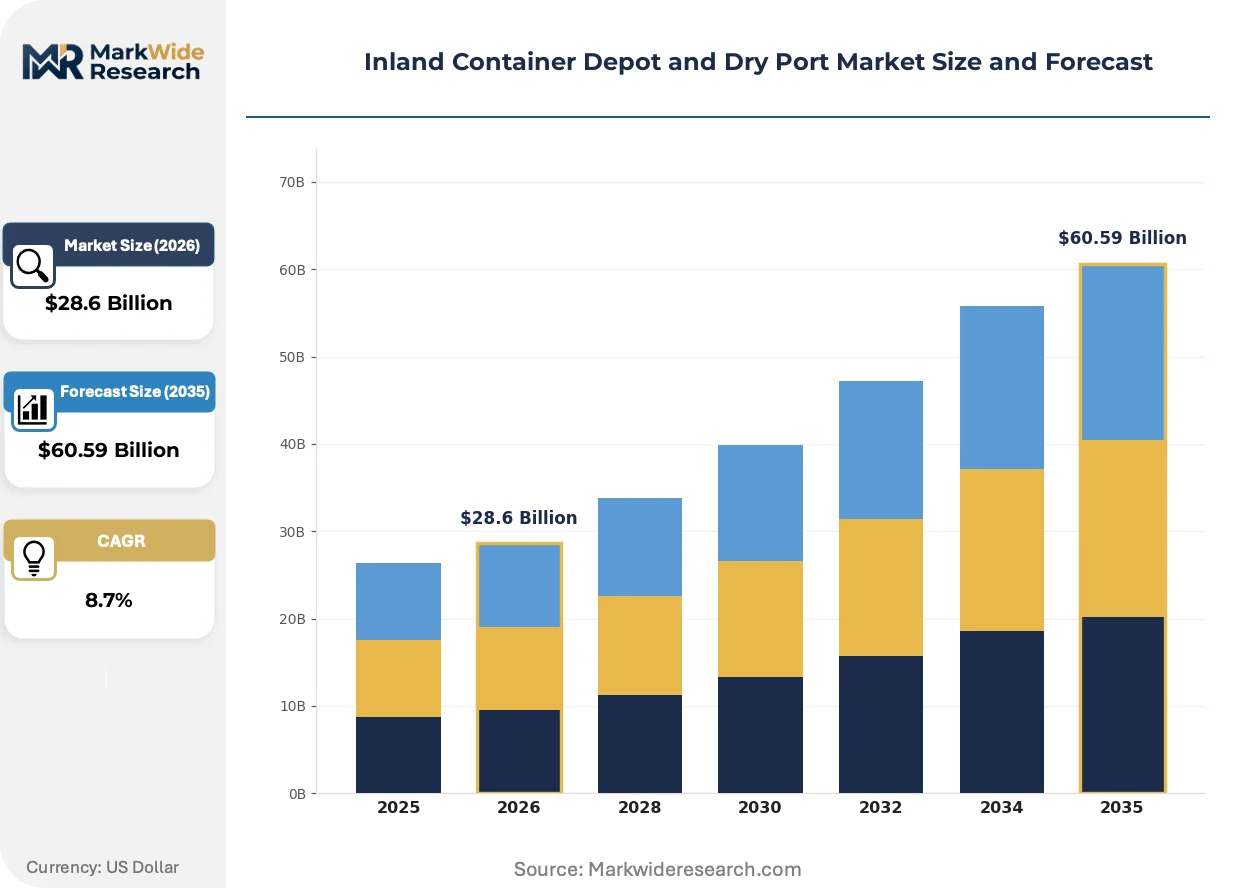
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Loading, Unloading, Warehousing, Customs Clearance End User: Logistics Providers, Freight Forwarders, Shipping Companies, Importers Technology: Automated Systems, RFID Tracking, Inventory Management Software, Online Booking Capacity: Small Scale, Medium Scale, Large Scale, Mega Facilities |
| Companies Covered | Boasso Global, Maersk, Container Corporation of India (CONCOR), APM Terminals, Hapag-Lloyd, DP World, Hutchison Ports, PSA International, Gateway Distriparks Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inland Container Depot and Dry Port Market Trends and Innovations
Digitization of customs workflows and electrification of material-handling equipment are compressing facility design cycles while opening margin pools in bonded value-added services.
Automated yard management systems are modularizing container storage density and retrieval speed through algorithmic slotting optimization. Third-party logistics providers operating high-throughput depots in India and Vietnam adopt these platforms fastest. The technology is modularizing traditional fixed-bay warehouse layouts into dynamic, density-responsive storage configurations.
The EU CSRD reporting requirements force facility operators to disclose Scope 3 supply-chain emissions and electrify diesel-powered yard equipment. European dry port developers now prioritize grid-connected crane infrastructure and solar canopy installations over conventional diesel backup systems. German and Dutch inland terminals face the steepest compliance timelines, accelerating procurement of battery-electric reach stackers.
Shippers now demand integrated customs-bonded warehousing with value-added processing rather than pure transshipment services. This unbundles traditional port-centric logistics into distributed interior nodes handling labeling, kitting, and quality inspection. The shift concentrates revenue growth in India's western corridor facilities serving Delhi-NCR manufacturing clusters.
Inland Container Depot and Dry Port Market Segmentation
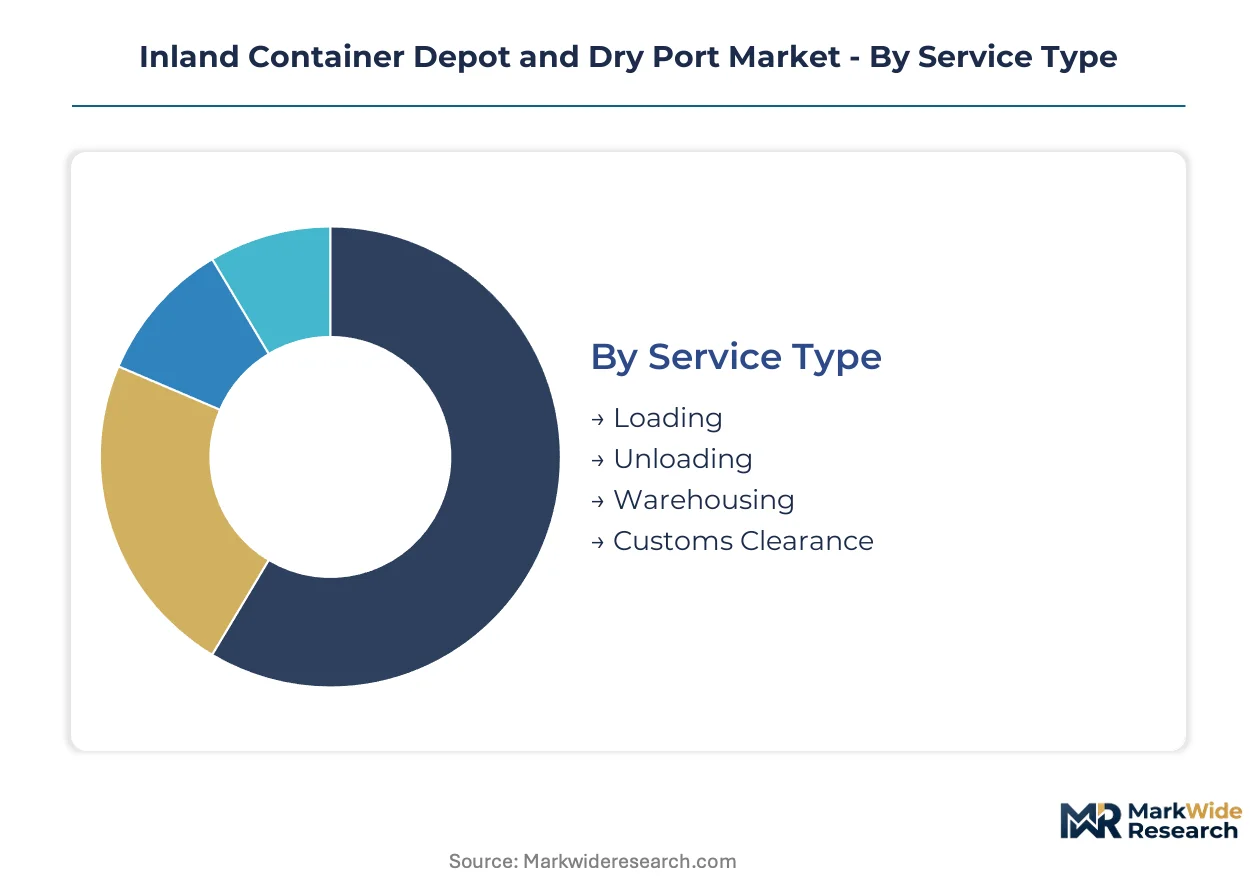
ICD and dry port operators configure service bundles and technology stacks around distinct cargo velocity profiles and customs complexity tiers. Segmentation reveals where margin pools concentrate across bonded warehousing, automated yard management, and rail-linked mega-facilities.
Service Type:
Customization intensity varies sharply across this category, from standardized container movements to highly tailored value-added processing.
- Warehousing:Bonded storage exceeding 100,000 square feet with extended inventory dwell generates premium margins through value-added services like labeling and kitting. Demand clusters in India's western corridor facilities serving Delhi-NCR manufacturing clusters, driven by e-commerce inventory staging requirements.
- Customs Clearance:Electronic sealing integration and risk-based inspection protocols require expensive middleware connecting legacy WMS to national risk-assessment platforms. India's CBIC mandates compress dwell times while forcing capital redeployment toward automated documentation systems.
- Loading:Gantry crane operations with 40-tonne lifting capacity handle container transfers between rail, road, and storage bays.
- Unloading:Reach stacker and forklift coordination manages container stripping and stuffing at customs-notified facilities.
Leading the category by volume: Warehousing. Expanding most quickly: Customs Clearance.
End User:
Cost-to-serve economics diverge widely across customer types, from asset-heavy shipping lines to broker-dependent importers.
- Logistics Providers:Third-party operators like Maersk and DP World demand integrated platform control over end-to-end container flows from gateway ports to interior depots. These customers drive fastest adoption of automated yard management systems.
- Shipping Companies:Ocean carriers prioritize vessel schedule reliability through pre-port customs clearance and guaranteed rail slot allocation.
- Freight Forwarders:NVOCCs and customs brokers require flexible booking windows and multi-modal documentation support.
- Importers:Manufacturing and retail shippers seek bonded value-added processing rather than pure transshipment, unbundling traditional port-centric logistics into distributed interior nodes.
Dominant by contract value: Logistics Providers. Gaining share fastest: Importers with integrated processing demands.
Technology:
Maturity gradients separate proven tracking infrastructure from emerging automation platforms still in pilot deployment.
- RFID Tracking:Real-time container location systems remain the dominant near-term investment category, reducing manual yard checks and accelerating gate throughput at high-volume facilities. Third-party logistics providers in India and Vietnam adopt these platforms fastest.
- Automated Systems:Optical character recognition converged with weighbridge automation compresses truck turnaround times, though full deployment requires electrified yard equipment retrofits under EU F-Gas Regulation timelines.
- Inventory Management Software:Algorithmic slotting optimization modularizes traditional fixed-bay warehouse layouts into dynamic, density-responsive storage configurations.
- Online Booking:Digital slot reservation platforms integrate with national customs-IT systems for advance cargo declaration.
Widest installed base: RFID Tracking. Steepest expansion trajectory: Automated Systems.
Capacity:
Scale economies and land acquisition constraints create distinct competitive moats across facility size tiers.
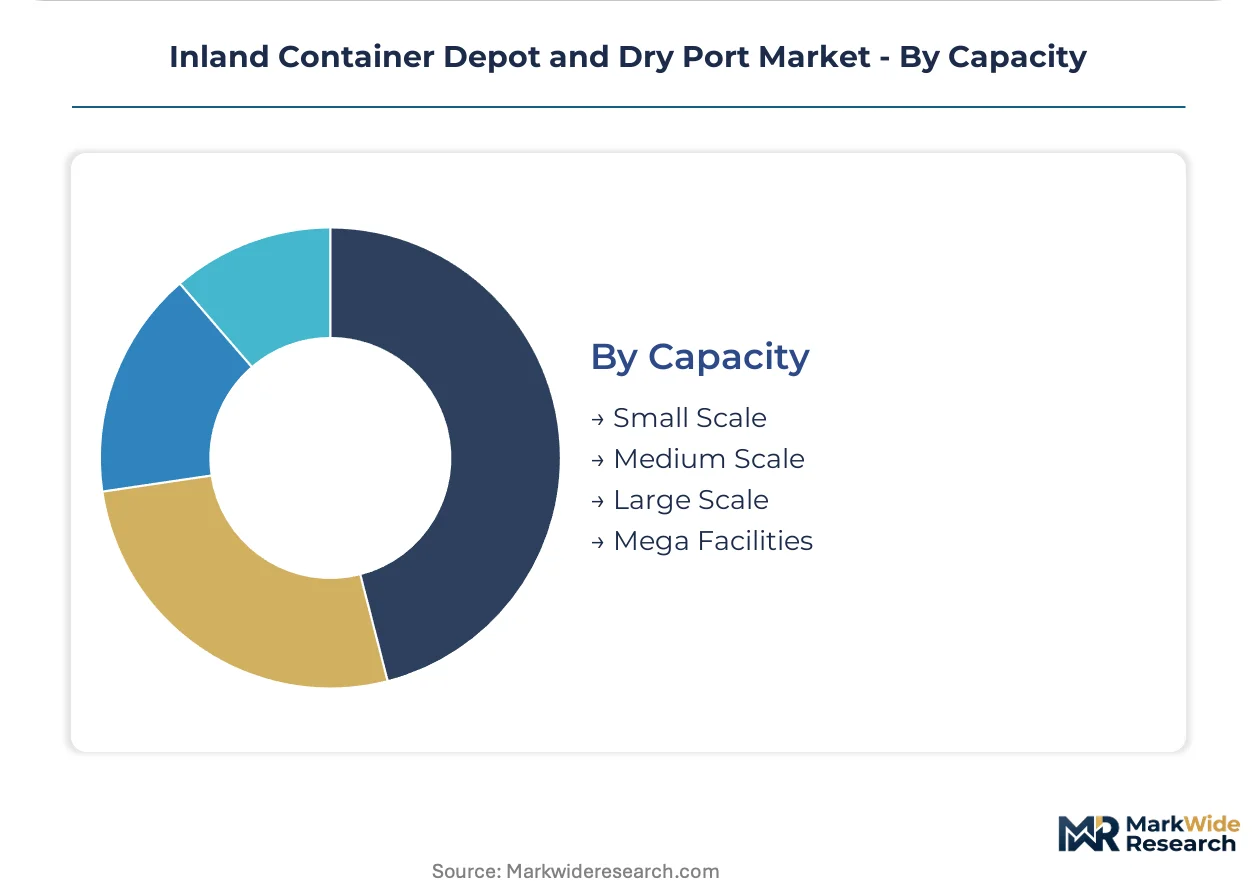
- Mega Facilities:Rail-linked complexes exceeding 500,000 TEU annual throughput anchor dedicated freight corridor strategies, with DP World developing such assets across South Asia and Sub-Saharan Africa. Urban periphery land prices constrain greenfield expansion near major consumption centers.
- Large Scale:Facilities serving regional manufacturing clusters capture scheduled block train services on India's Dedicated Freight Corridor.
- Medium Scale:Mid-tier depots balance customs clearance efficiency with lower capital intensity for emerging logistics corridors.
- Small Scale:Satellite facilities extend gateway port reach into secondary hinterlands with limited rail infrastructure.
Highest throughput concentration: Mega Facilities. Fastest development pipeline: Large Scale facilities along India's western corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones and Free Trade Warehousing Zones in India, Vietnam, and Bangladesh are concentrating dry port investment along dedicated freight corridors and coastal manufacturing belts. These tax-advantaged enclaves reduce customs dwell times and attract third-party logistics operators seeking bonded warehousing capacity. Government production-linked incentive schemes in South Asia now explicitly cover logistics infrastructure, accelerating depot development in hinterland manufacturing corridors.
India
The Dedicated Freight Corridor connecting Jawaharlal Nehru Port Trust to Delhi-NCR hinterlands drives containerized rail movement demand. The Central Board of Indirect Taxes and Customs mandates electronic sealing and risk-based inspection protocols that reshape capital expenditure patterns at customs-notified facilities. Gujarat's Mundra-Pipavav logistics cluster anchors mega-facility development with dedicated rail links serving western manufacturing belts.
Vietnam
Manufacturing relocation from China accelerates bonded warehousing demand at interior logistics nodes near Hanoi and Ho Chi Minh City industrial zones. The Ministry of Industry and Trade's logistics development strategy prioritizes dry port connectivity to deep-water gateway ports at Cai Mep and Hai Phong. The northern provinces of Bac Ninh and Vinh Phuc concentrate ICD development serving electronics contract manufacturers.
Germany
The EU F-Gas Regulation and Corporate Sustainability Reporting Directive force electrification of yard cranes and reach stackers at Rhine corridor dry ports. The Duisburg inland terminal complex exemplifies mega-facility scale with scheduled block train services connecting to North Sea ports. Bavarian logistics hubs face compressed compliance timelines for battery-electric equipment procurement under federal climate protection mandates.
United Arab Emirates
Jebel Ali Free Zone Authority incentives attract third-party logistics providers establishing regional distribution centers with integrated dry port functions. The UAE's national logistics strategy targets multimodal connectivity between Dubai's container terminals and Abu Dhabi industrial zones. Dubai South's logistics district concentrates automated yard management system deployment for high-throughput e-commerce fulfillment.
Bangladesh
Chittagong port congestion drives demand for interior customs clearance facilities serving Dhaka-Narayanganj garment manufacturing clusters. The Bangladesh Economic Zones Authority offers tax holidays for logistics infrastructure investments along the Dhaka-Chittagong corridor. The Savar-Ashulia industrial belt anchors dry port development with limited rail infrastructure necessitating road-heavy multimodal solutions.
Inland Container Depot and Dry Port Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated ocean carriers and pure-play terminal operators occupying distinct competitive tiers. Market structure concentrates around statutory rail access holders in India, global port operators with inland extension strategies, and regional third-party logistics platforms. Three archetypes dominate: state-affiliated rail-landed incumbents, vertically integrated shipping lines controlling end-to-end container flows, and independent depot operators specializing in customs-bonded value-added services. Capacity expansion along dedicated freight corridors and strategic partnerships for automated yard technology deployment represent the dominant competitive moves.
Among integrated carrier-affiliated operators, Maersk and Hapag-Lloyd exemplify the shipping line archetype extending control from gateway ports to interior logistics nodes. Container Corporation of India occupies a unique position as the statutory rail-access incumbent dominating domestic containerized movement through Indian Railways infrastructure. DP World represents the global port operator archetype anchoring mega-facility development across South Asia and Sub-Saharan Africa with dedicated rail-linked strategies. These three entities sit within different competitive tiers but collectively illustrate how rail access, customs integration, and scale economics determine positioning in high-growth corridors.
| Leading Market Players |
|---|
| Boasso Global |
| Maersk |
| Container Corporation of India (CONCOR) |
| APM Terminals |
| Hapag-Lloyd |
| DP World |
| Hutchison Ports |
| PSA International |
| Gateway Distriparks Limited |
| Others |
Pricing and Supply Chain Analysis
Electrification of yard cranes and reach stackers under EU F-Gas Regulation timelines is simultaneously inflating capital expenditure requirements and consolidating procurement power among operators with balance-sheet capacity for grid-connected infrastructure. This technology transition compresses margins for mid-tier depots while amplifying pricing leverage for mega-facility developers with statutory rail access.
Pricing Analysis
Premium pricing attaches to guaranteed lead-time slots on India's Dedicated Freight Corridor, while spot-market container handling at peripheral depots trades at discounted rates. Three-tier pricing structure across premium guaranteed-rail, standard scheduled-service, and economy spot-handling levels reflects customs integration depth and yard automation maturity. Pricing pressure stems from land acquisition cost inflation near Delhi-NCR and Mumbai consumption clusters, squeezing greenfield project returns. Small-scale satellite operators exhibit highest price sensitivity due to road-heavy cost structures, whereas integrated logistics providers like Maersk and DP World absorb premiums for end-to-end control.
Supply Chain Analysis
Direct-to-shipper channels handle e-commerce fulfillment demand through bonded warehousing integration, bypassing traditional freight forwarder intermediation. Equipment manufacturing concentrates in China, Germany, and South Korea for gantry cranes and reach stackers. Bonded warehouse construction draws from Indian steel, Chinese automation components, and European electrification systems. Supply chain risk centers on single-source vulnerability for 40-tonne lifting capacity crane systems with extended order backlogs. Distribution runs through statutory rail-access holders in India, global port operators with inland extension strategies, and regional third-party logistics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Land scarcity near western corridor consumption clusters constrains capacity addition, propping pricing power for incumbent operators with existing rail-linked real estate.
For Market Incumbents: To counter margin compression from EU F-Gas Regulation electrification mandates, prioritize backward integration into solar canopy installations and battery-electric reach stacker fleets. Consolidate position by acquiring distressed mid-tier depots in India's western corridor facing land-lease renewal pressures. For New Entrants and Emerging Players: India's PLI scheme for logistics infrastructure opens a window for greenfield mega-facility development along underpenetrated eastern corridor routes connecting Kolkata to Bangladesh border manufacturing zones. Target customs-bonded value-added processing services for garment exporters seeking Delhi-NCR aggregation points. Pursue joint venture structures with Container Corporation of India to secure statutory rail access. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated ocean carriers seeking end-to-end container flow control. Long-term viability favors operators with Dedicated Freight Corridor slot guarantees and electronic sealing integration with CBIC platforms. Monitor customs digitization mandate compliance timelines as inflection indicator for facility obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Linked Mega-Facility Development | DP World anchors South Asian expansion with dedicated freight corridor slot guarantees. |
| Automated Yard Management Deployment | Optical character recognition integration compresses truck turnaround at high-throughput Indian depots. |
| Electrification Retrofit Program | EU F-Gas Regulation compliance forces battery-electric reach stacker procurement at Rhine corridor terminals. |
| Customs-IT System Integration | CBIC electronic sealing mandates require middleware connecting legacy WMS to national risk-assessment platforms. |
| Bonded Value-Added Service Expansion | Labeling and kitting operations capture margin pools from e-commerce inventory staging demand. |
Research Methodology
Multi-period observation of container dwell times, rail slot utilization rates, and customs clearance velocity anchored the trend analysis, supplemented by interviews with depot operations managers, Indian Railways scheduling officers, customs brokerage executives, and third-party logistics platform directors. Secondary validation drew from CBIC electronic sealing mandate documentation, Dedicated Freight Corridor traffic statistics, EU F-Gas Regulation compliance disclosures, and containerized rail movement customs records. Bottom-up facility capacity assessments and top-down corridor demand modeling were triangulated to constrain forecast variance.
Input-output matrices structured the analytical framework across service type, technology adoption tier, capacity scale, and end-user archetype throughout the forecast period. CAGRs were derived from regression analysis against rail infrastructure investment cycles and customs digitization rollout schedules. Modeled segmentation dimensions included bonded warehousing intensity, yard automation maturity, and statutory rail access status. Industry-specific forecast inputs incorporated Dedicated Freight Corridor commissioning timelines and PLI scheme disbursement patterns.
Caveats apply where land acquisition litigation delays or customs-IT system integration failures could materially shift the outlook for facility commissioning schedules. Forecasts reflect assumptions regarding electrification equipment supply chain normalization and skilled gantry crane operator training program expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
Asia Pacific Finished Vehicle Logistics Market
Logistics and Shipping
Cold Chain Logistics Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Czech Republic Freight and Logistics Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
France Cold Chain Logistics Market