
 Spain Automotive OEM Coatings Market | 2026-2036
Spain Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Automotive OEM Coatings Market Analytics
The direct supply channel between coating formulators and Martorell assembly complexes is narrowing as Volkswagen Group Spain consolidates qualified vendor lists. PPG Industries leverages its proximity to Catalan production hubs to sustain just-in-time delivery contracts. BASF SE anchors its southern European distribution through dedicated blending facilities near Valencia port operations.
Spain Automotive OEM Coatings comprise pigmented resin systems applied to vehicle bodies prior to final assembly, typically formulated with polyurethane, epoxy, or acrylic binders at film builds of 25-50 microns to deliver corrosion resistance and aesthetic finish. Their primary purpose is to protect unibody and panel substrates from environmental degradation while enabling brand-specific color matching across production batches. Waterborne coatings now dominate exterior applications as VOC compliance tightens, while powder coatings command the underbody segment where chip resistance requirements are most severe. Electrostatic spray technology leads the technology dimension due to transfer efficiency advantages on complex body geometries.
Spain's Ministry for the Ecological Transition enforces EU REACH and F-Gas Regulation limits on solvent content, compelling reformulation investments from all suppliers. The Spanish Association of Automobile Manufacturers (ANFAC) coordinates industry-wide compliance timelines with national regulators. Stakeholders must monitor how Madrid's pending industrial emissions standards will affect curing oven energy profiles and coating line capital cycles.
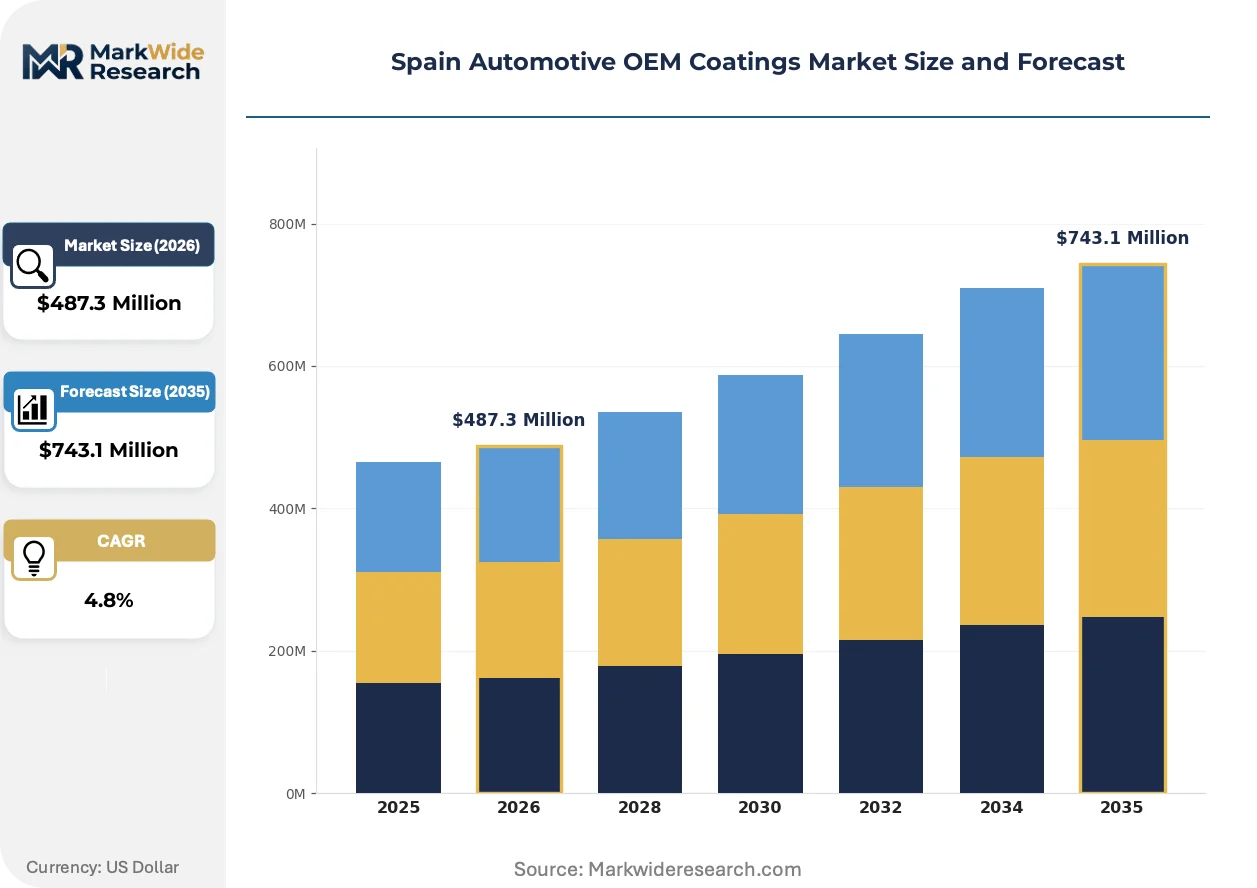
Market Dynamics
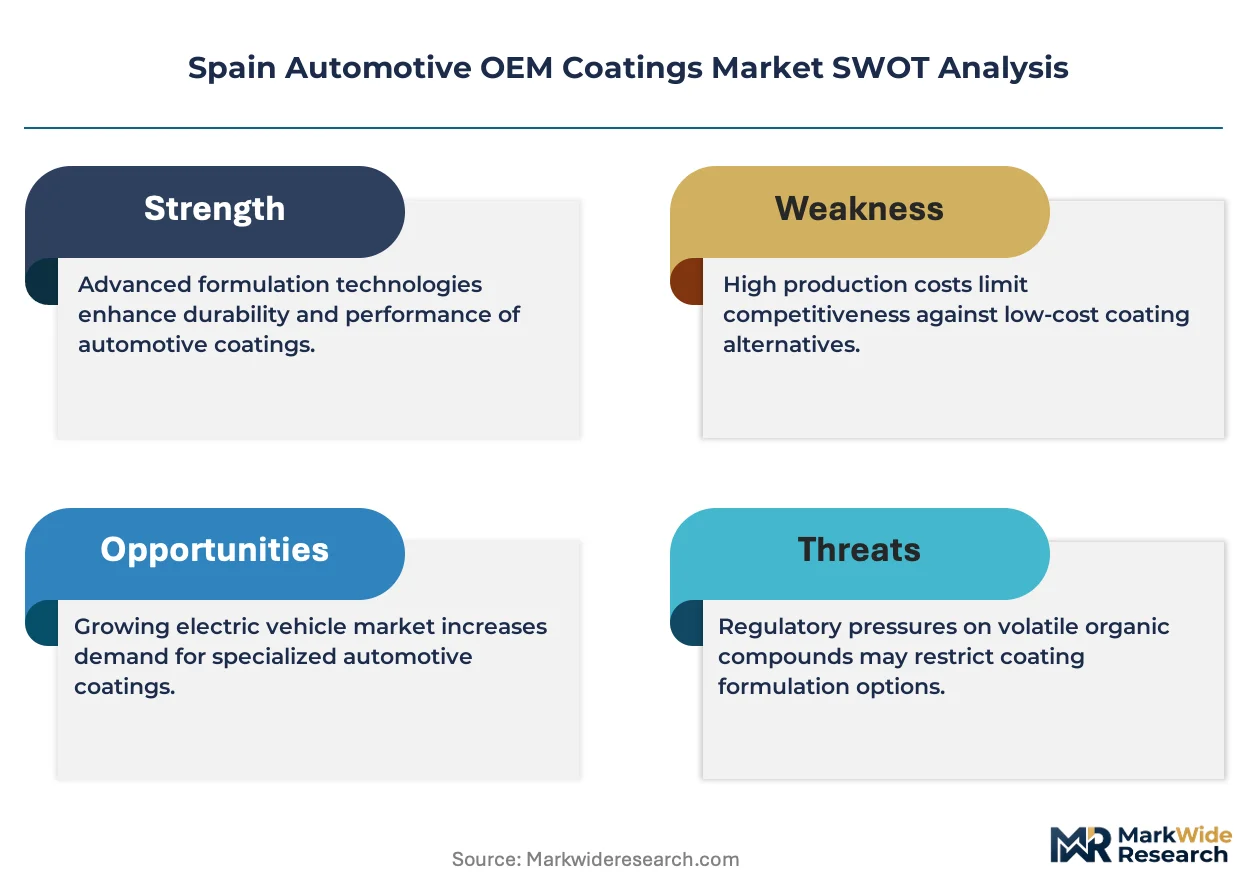
Spain's automotive OEM coatings sector is undergoing a forced transition as EU REACH VOC limits compel solvent-based system phase-outs, with waterborne technology adoption now determining supplier survival rather than competitive advantage.
Growth Catalysts
- Electric vehicle production expansion:Battery-electric vehicle assembly lines at Martorell and Vitoria-Gasteiz require specialized coating protocols for aluminum-intensive body architectures, pulling demand for low-temperature cure systems.
- EU F-Gas Regulation compliance:Spain's national adaptation mandates fluorinated gas reductions in coating operations, accelerating investment in infrared and UV curing technologies that eliminate thermal oven dependencies.
- Basque Country manufacturing corridor concentration:Dense clustering of Tier-1 stamping and body-in-white facilities around Bilbao creates localized demand density that supports dedicated blending plant economics.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress formulator margins and destabilize annual contract pricing with Martorell and Zaragoza assembly complexes.
- Qualified vendor list consolidation:Volkswagen Group Spain's narrowing approved supplier roster concentrates procurement power among three coating formulators, raising barriers for specialty chemical entrants.
- Waterborne system technical ceiling:Current waterborne polyurethane chemistry cannot match solvent-based alternatives for chip resistance in underbody applications, preserving powder coating dominance in that segment.
Strategic Opportunities
- Andalusian supplier park development:Emerging electric vehicle investments around Seville create greenfield coating line demand outside established Basque-Catalonia supply chains.
- EU Green Deal industrial funding:NextGenerationEU facility modernization grants enable Spanish OEMs to retrofit curing infrastructure for energy-efficient coating processes.
- Digital color matching convergence:Integration of spectrophotometric measurement with automated tinting systems allows real-time batch correction, reducing rework rates at high-volume plants.
Industry Challenges
- Formulation chemist shortage:Spain's technical universities produce insufficient polymer science graduates trained in low-VOC resin system design, forcing suppliers to recruit from German and French talent pools.
- Multi-standard certification complexity:Simultaneous compliance with EU REACH, Spain's national industrial emissions standards, and OEM-specific material data sheet requirements extends product qualification timelines.
- Legacy solvent line stranded asset risk:Coatings suppliers face write-downs on dedicated solvent-based production assets before depreciation cycles complete, complicating capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Automotive OEM Coatings Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne Coatings, Solvent-Borne Coatings, Powder Coatings, UV-Curable Coatings Application: Exterior Coatings, Interior Coatings, Underbody Coatings, Engine Coatings End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Technology: Electrostatic Spray, Roller Coating, Airless Spray, Dipping |
| Companies Covered | AkzoNobel N.V., Axalta Coating Systems, BASF SE, PPG Industries, The Sherwin-Williams Company, Beckers Group, Jotun, Nippon Paint Holdings, RPM International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Automotive OEM Coatings Market Evolving Landscape
Coating technology in Spain's automotive sector is pivoting around environmental compliance mandates that are rewriting formulation priorities, curing methods, and supplier-customer technical collaboration models.
UV-curable clearcoat technology is rendering obsolete traditional thermal-cure systems in interior trim applications. Seat frame and dashboard component suppliers at Vitoria-Gasteiz are adopting UV lines to eliminate energy-intensive oven cycles. This shift is compressing the addressable market for conventional two-component polyurethane clears and forcing specialty chemical suppliers to reallocate R&D spending toward photoinitiator chemistry.
Spain's Ministry for the Ecological Transition is tightening national industrial emissions standards beyond baseline EU REACH requirements, with draft rules targeting nitrogen oxide releases from curing ovens. Paint shop operators at Martorell and Figueruelas must install regenerative thermal oxidizers or face production quota restrictions. The exterior body coating segment bears the heaviest compliance burden due to its multi-layer bake sequences and higher solvent loading.
Automotive procurement teams are consolidating coating supply contracts into multi-year framework agreements with embedded technical service provisions. Tier-1 body panel stampers in Catalonia are shifting from spot purchases to integrated supply partnerships that include on-site color laboratory staffing. This pattern is most pronounced at high-volume plants serving export markets where color consistency defects trigger contractual penalties.
Spain Automotive OEM Coatings Market Segmentation
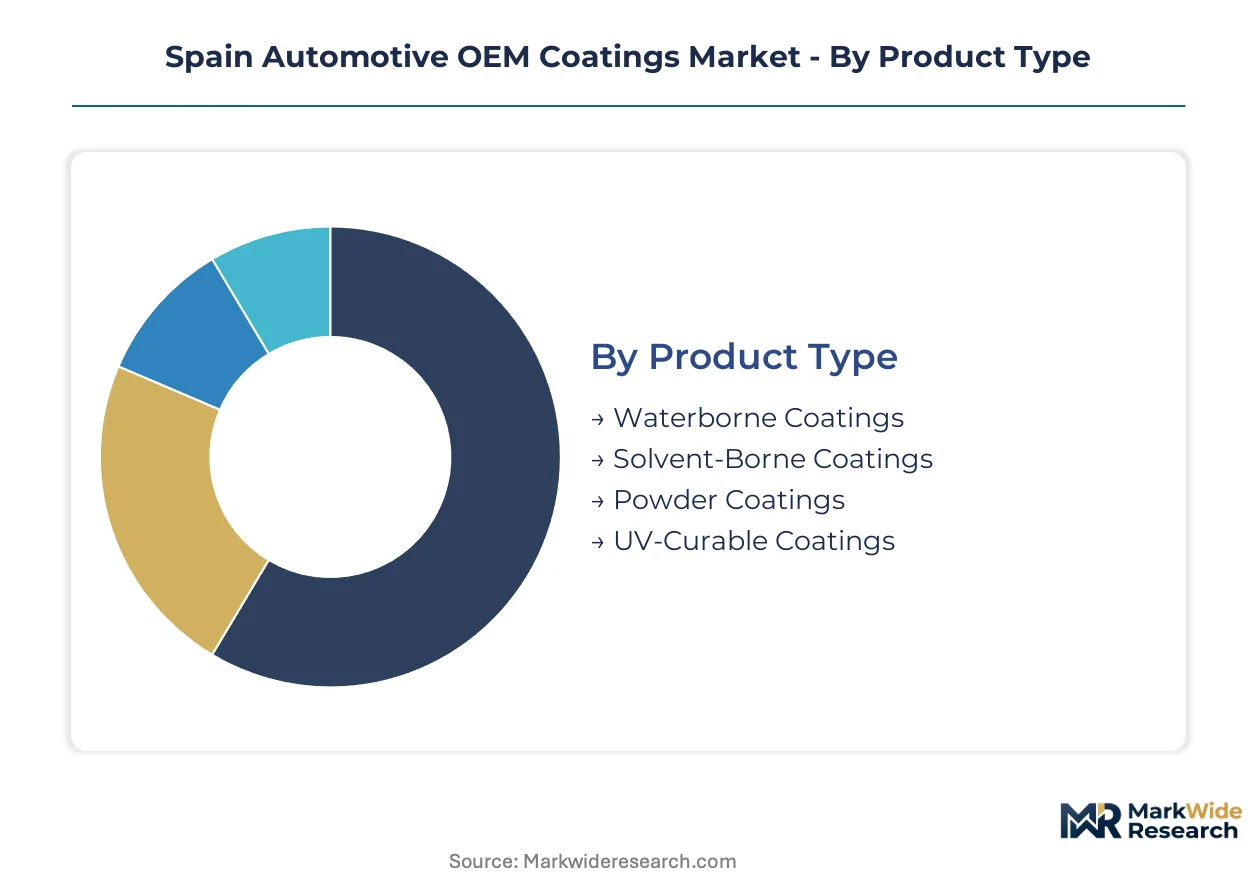
Coating formulators in Spain navigate four distinct segmentation axes that determine formulation priorities, curing infrastructure investments, and customer qualification pathways. Each dimension reflects the tension between EU REACH compliance deadlines and the technical requirements of Martorell, Vitoria-Gasteiz, and Zaragoza assembly complexes.
Product Type:
Mature solvent systems face forced phase-out while emerging low-VOC chemistries capture reformulation budgets across all four technology platforms.
- Waterborne Coatings:Polyurethane-acrylic dispersions with 15-20% organic solvent content now dominate exterior body applications at Martorell. Basque Country stamping plants specify these systems for aluminum-intensive electric vehicle architectures where low-temperature cure protects battery-adjacent structural adhesives.
- Solvent-Borne Coatings:High-solids two-component urethanes retain underbody and engine bay applications where chip resistance specifications exceed current waterborne performance ceilings. ANFAC-coordinated compliance timelines force accelerated line conversions at Figueruelas and Valencia plants.
- Powder Coatings:Thermoset epoxy-polyester hybrids command chassis and suspension component finishing at Vitoria-Gasteiz commercial vehicle lines.
- UV-Curable Coatings:Acrylate oligomer systems eliminate thermal oven cycles for interior trim at Catalan dashboard suppliers.
Waterborne systems handle the majority of throughput; UV-curable platforms are gaining share fastest as seat frame manufacturers retrofit Vitoria-Gasteiz lines.
Application:
Volume concentration follows the multi-layer bake sequences of unibody construction, with each application zone imposing distinct corrosion resistance and aesthetic finish specifications.
- Exterior Coatings:Basecoat-clearcoat systems at 35-50 micron film builds deliver color matching precision and UV durability for visible body panels. Martorell's export-volume plants drive demand for automated tinting integration that reduces batch-to-batch variation penalties.
- Interior Coatings:Low-gloss polyurethane clears for dashboard and door panel substrates prioritize scratch resistance and volatile organic compound emissions compliance for cabin air quality standards.
- Underbody Coatings:Chip-resistant PVC plastisols and rubberized asphaltic coatings protect rocker panels and floor pans from stone impact.
- Engine Coatings:Heat-resistant silicone-modified alkyd systems withstand under-hood thermal cycling at Zaragoza powertrain assembly.
Exterior applications absorb the largest coating volumes per vehicle; interior systems are expanding most quickly through UV line conversions.
End User:
Customer segmentation tracks powertrain technology transitions and price-tier positioning that reshape substrate materials and curing protocols.
- Passenger Vehicles:High-volume unibody construction at Martorell and Figueruelas drives standardized color palettes and just-in-time delivery contracts with dedicated blending facilities near Barcelona port operations.
- Commercial Vehicles:Cab-over-engine architectures at Vitoria-Gasteiz impose severe chip resistance requirements for gravel-road duty cycles in export markets.
- Electric Vehicles:Battery-electric platforms require aluminum-intensive body structures with low-temperature cure systems that preserve adhesive bonding integrity.
- Luxury Vehicles:Low-volume specialty finishes at limited Catalonia assembly operations demand custom color matching with extended bake cycles for depth and clarity.
Passenger vehicle lines generate the dominant order volumes; electric vehicle coating specifications are climbing the fastest as Martorell expands dedicated BEV production.
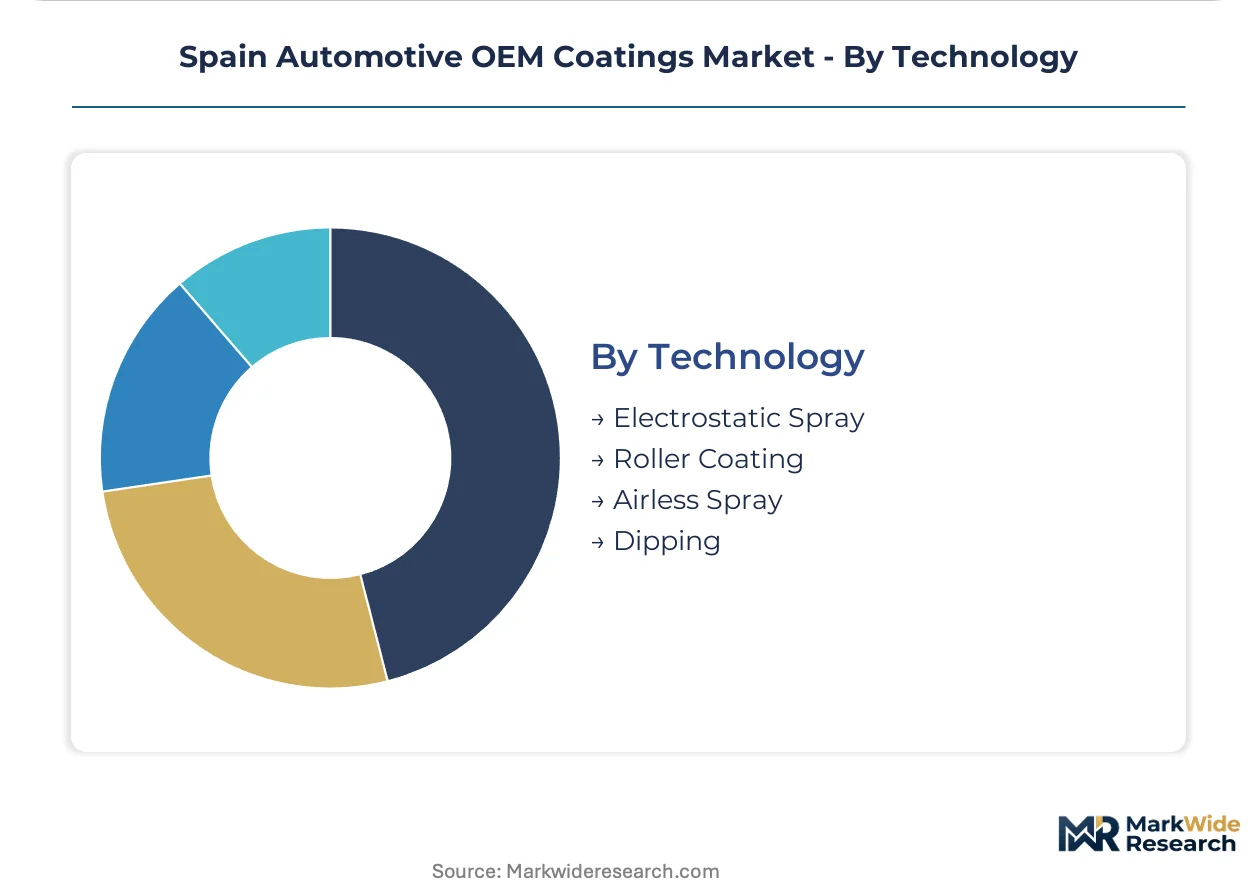
Technology:
Transfer efficiency and substrate geometry dictate equipment selection across the four deposition methods, with capital cycles extending 10-15 years.
- Electrostatic Spray:Rotating bell atomizers with 85-90% transfer efficiency dominate complex body geometries at high-volume Martorell operations, reducing overspray waste and booth maintenance cycles.
- Roller Coating:Continuous film application for flat stock preprocessing at Tier-1 stamping suppliers in the Basque Country enables precise thickness control on hood and decklid outer panels.
- Airless Spray:High-pressure hydraulic atomization serves underbody and cavity wax injection where substrate access limits electrostatic effectiveness.
- Dipping:Total immersion systems for primer application on welded subassemblies ensure complete coverage of box sections and reinforcements.
Electrostatic spray lines process the majority of body surface area; roller coating is expanding most quickly through integrated coil coating investments at Bilbao-area steel service centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation compliance timelines and NextGenerationEU facility modernization grants are redirecting coating demand toward low-VOC and energy-efficient curing systems across Spanish manufacturing corridors.
Catalonia
Martorell assembly complexes drive demand for waterborne basecoat-clearcoat systems with automated tinting integration. Spain's Ministry for the Ecological Transition enforces national industrial emissions standards that mandate regenerative thermal oxidizer installation at high-volume paint shops. Barcelona port operations anchor dedicated blending facilities serving just-in-time delivery contracts for export-volume plants.
Basque Country
Vitoria-Gasteiz commercial vehicle lines require chip-resistant powder coatings for gravel-road duty cycles in export markets. EU REACH VOC limits compel solvent-based system phase-outs with ANFAC-coordinated compliance timelines. Bilbao-area steel service centers support integrated coil coating investments for hood and decklid preprocessing.
Valencia
Figueruelas assembly operations accelerate line conversions under compressed ANFAC compliance schedules for waterborne technology adoption. Spain's national adaptation of EU REACH restrictions forces reformulation investments from all suppliers. Valencia port operations host dedicated blending facilities anchoring southern European distribution networks.
Andalusia
Seville-area electric vehicle investments create greenfield coating line demand outside established supply chains. NextGenerationEU grants enable OEMs to retrofit curing infrastructure for energy-efficient processes. Emerging supplier park development targets aluminum-intensive body architectures with low-temperature cure requirements.
Spain Automotive OEM Coatings Market Competitive Landscape
On the supply side, the industry is consolidating around qualified vendor lists as procurement power concentrates among high-volume assembly complexes. Three strategic archetypes dominate: integrated chemical conglomerates with captive resin production, specialized coating formulators with regional blending networks, and diversified materials suppliers leveraging adjacent industrial coatings expertise. Competitive intensity centers on multi-year framework agreements with embedded technical service provisions and geographic proximity to Catalan and Basque manufacturing corridors.
Within the integrated chemical conglomerate tier, BASF SE and PPG Industries exemplify supply-side positioning through dedicated distribution infrastructure. Axalta Coating Systems occupies a position among specialized automotive coating formulators with focused OEM qualification pathways. These three anchors represent distinct strategic approaches to serving Martorell and Vitoria-Gasteiz assembly requirements.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| Axalta Coating Systems |
| BASF SE |
| PPG Industries |
| The Sherwin-Williams Company |
| Beckers Group |
| Jotun |
| Nippon Paint Holdings |
| RPM International |
| Others |
Value Network & Pricing Analysis
Titanium dioxide feedstock concentration in Chinese sulfate-process facilities ties directly to margin compression at Spanish formulators serving Martorell assembly contracts. Pigment cost volatility propagates through annual contract renegotiations with Volkswagen Group Spain procurement teams.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs coating supply contracts in the Spanish market. Price differentiation hinges on volume commitment scale and EU REACH compliance certification tier, with export-volume plants at Martorell commanding steepest discounts through multi-year framework agreements. Pricing pressure stems from titanium dioxide feedstock volatility and qualified vendor list consolidation. Tier-1 stamping suppliers in the Basque Country exhibit highest price sensitivity due to compressed automotive OEM transfer pricing.
Supply Chain Analysis
Contract manufacturing concentration rests with PPG Industries, BASF SE, and Axalta Coating Systems operating dedicated blending facilities near Barcelona and Valencia port operations. Raw material dependencies draw from German specialty resin producers, Chinese titanium dioxide processors, and Belgian photoinitiator suppliers. Supply chain risk centers on single-source vulnerability for low-VOC polyurethane dispersions. Distribution runs through just-in-time delivery contracts with on-site color laboratory staffing at high-volume assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's automotive OEM coatings sector represents a high-growth disruption as EU F-Gas Regulation compliance forces wholesale curing technology replacement across Martorell and Vitoria-Gasteiz paint shops.
For Market Incumbents: Insulate qualified vendor list positions through backward integration into waterborne resin production and captive supply of low-temperature cure systems for electric vehicle architectures. Threat substitution comes from UV-curable platform specialists displacing conventional polyurethane clears in interior trim applications. Priority lever: dedicated blending capacity expansion near emerging Andalusian electric vehicle supplier parks. For New Entrants and Emerging Players: Establish a beachhead in UV-curable acrylate oligomer systems for Vitoria-Gasteiz seat frame manufacturers retrofitting lines to eliminate thermal oven cycles. White-space targets include Seville-area greenfield coating line demand and digital color matching convergence with automated tinting integration. Go-to-market angle: technical service partnerships with on-site spectrophotometric measurement staffing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional coating formulators holding Basque Country stamping plant relationships but lacking waterborne technology portfolios. Long-term viability favors suppliers with integrated low-VOC resin capabilities and electric vehicle qualification pathways. Signal to watch: NextGenerationEU grant disbursement velocity for curing infrastructure retrofit projects.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne System Capacity Expansion | Captures reformulation budgets as ANFAC-coordinated EU REACH compliance deadlines accelerate solvent line phase-outs at Figueruelas. |
| UV Curing Technology Licensing | Eliminates thermal oven dependencies for Vitoria-Gasteiz interior trim suppliers facing F-Gas Regulation emission limits. |
| Backward Integration into Resin Production | Secures margin pools currently captured by German specialty chemical suppliers of low-VOC polyurethane dispersions. |
| Andalusian Supplier Park Joint Venture | Positions blending infrastructure ahead of Seville-area electric vehicle investments requiring aluminum-compatible low-temperature cure systems. |
| Digital Color Matching Platform Partnership | Reduces batch-to-batch variation penalties at Martorell export-volume plants through real-time spectrophotometric correction. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coating formulator technical directors, OEM platform engineers at Martorell and Vitoria-Gasteiz, Tier-1 stamping procurement leads in the Basque Country, and ANFAC regulatory affairs coordinators. Secondary validation drew from EU REACH regulatory filings, Spanish Ministry for the Ecological Transition emissions standards drafts, SEC 10-K disclosures of listed coating suppliers, and vehicle production databases tracking assembly volumes by propulsion architecture. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and technology segmentation dimensions.
Calibration anchored volume and value outputs to known production capacities at qualified vendor list suppliers and verified coating consumption rates per vehicle class. Segmentation dimensions modeled encompass waterborne, solvent-borne, powder, and UV-curable chemistries; exterior, interior, underbody, and engine applications; passenger, commercial, electric, and luxury vehicle end users; and electrostatic spray, roller coating, airless spray, and dipping technologies. CAGRs were derived from production volume trajectories and content-per-vehicle trends across the projection horizon, with electric vehicle penetration rates and EU compliance timeline rigor serving as primary forecast sensitivity inputs.
Sensitivities concentrate around EU F-Gas Regulation enforcement timing, titanium dioxide feedstock price volatility, and electric vehicle production ramp schedules at Martorell. Forecasts reflect assumptions regarding ANFAC-coordinated compliance adherence and NextGenerationEU facility modernization grant disbursement velocity. Quarterly review of regulatory filing deadlines, pigment commodity indices, and OEM capital expenditure announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
North America Coil Coatings Market
Coatings
Global Laser Cladding Service Market
Coatings
Hydrophilic Coatings Market
Coatings
Morocco Automotive OEM Coatings Market
Coatings
Global Polyaspartic Coatings Market
Coatings
Global Water-Based Coatings Market
Coatings
Bio-Based Coatings Market
Coatings
Fillers and Coating Market
Coatings
Electrically Conductive Coating Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
Global Optical Coating Market
Coatings
Global Floor Coatings Market
Coatings
Fire Retardant Coatings Market