
 Europe Protective Coatings Market | 2026-2036
Europe Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Protective Coatings Market Foresight
Aftermarket service revenue is reconfiguring margin capture across the European protective coatings value chain. PPG Industries extends its platform through technical service contracts tied to marine dry-dock schedules. Akzo Nobel dominates architectural and industrial maintenance specifications via its Interpon powder coatings network. Hempel A/S anchors offshore wind sector penetration with specialized anti-corrosion systems for monopile foundations.
Europe protective coatings are formulated polymer systems—typically epoxy, polyurethane, or zinc-rich chemistries applied at dry film thicknesses of 100–500 micrometers—that cure into adherent barriers against moisture, chemicals, and mechanical abrasion. Their primary purpose is extending asset life in corrosive environments across infrastructure, transportation, and energy installations. Epoxy formulations lead industrial maintenance owing to substrate adhesion and chemical resistance, while water-based technologies gain share as solvent-based systems face tightening VOC regulations under REACH. Powder coatings occupy the premium architectural segment where zero-VOC emission and overspray recovery justify capital-intensive application equipment.
EMA, ECHA, and the EU Green Deal collectively constrain formulation chemistry and mandate lifecycle transparency across the European protective coatings supply base. REACH registration requirements elevate compliance costs for imported raw materials, while the F-Gas Regulation indirectly shapes insulation coating specifications in cold-climate energy infrastructure. Stakeholders must monitor the interplay between carbon border adjustments and bio-based resin certification schemes as procurement criteria evolve.
Market Dynamics
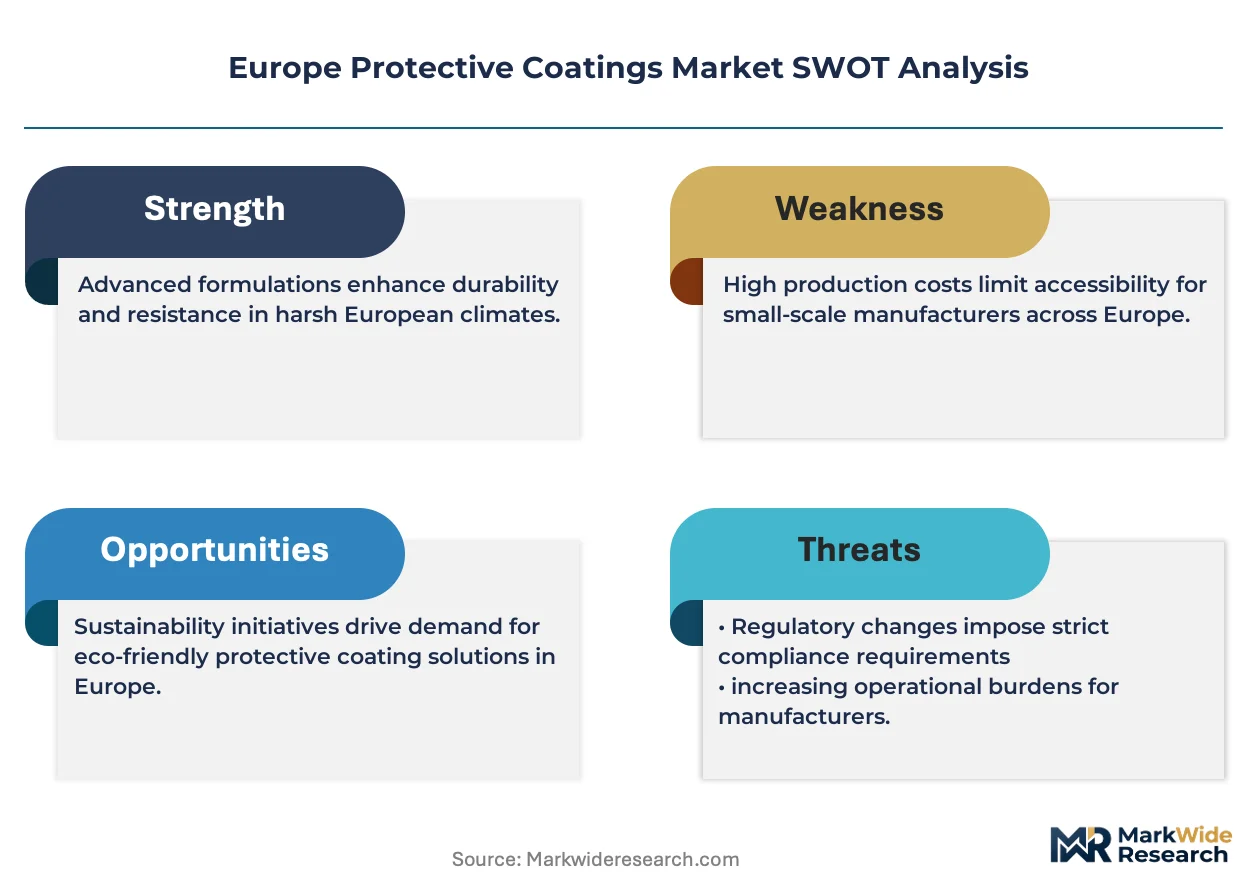
REACH compliance deadlines and the EU Green Deal are forcing solvent-to-water technology transitions across European coating formulation, compressing margins for legacy producers while opening specification windows for compliant alternatives.
Growth Catalysts
- Offshore wind buildout:North Sea monopile foundations require specialized anti-corrosion systems at film thicknesses exceeding 400 micrometers, creating sustained demand pull from Orsted, RWE, and Equinor installation schedules.
- REACH Annex XVII amendments:Tightening VOC limits in decorative and industrial maintenance coatings are mandating water-based epoxy and polyurethane conversions, accelerating replacement cycles in Germany's automotive OEM supply chain.
- EU Carbon Border Adjustment Mechanism:Imported steel and aluminum substrates face embedded carbon reporting requirements, favoring domestic coating applicators with certified lifecycle transparency in French and Dutch port infrastructure projects.
Market Restraints
- Raw material concentration:Epoxy resin supply concentrates among three German and Dutch chemical producers, exposing formulators to bisphenol-A and amine hardener price volatility during energy-intensive production curtailments.
- Application equipment lock-in:Solvent-based spray booths represent sunk capital for 60% of continental maintenance contractors, creating technical friction against water-based system conversions despite regulatory pressure.
- Qualified applicator scarcity:NACE and FROSIO-certified inspectors remain concentrated in Hamburg-Rotterdam-Antwerp corridor, constraining project execution speed in Baltic and Mediterranean expansion markets.
Strategic Opportunities
- Polish and Romanian industrial zones:Automotive component manufacturing is migrating eastward from Germany's Saxony and Bavaria regions, creating greenfield specification opportunities for powder coating integrators near Krakow and Cluj-Napoca.
- Hydrogen infrastructure coating:High-pressure vessel and pipeline specifications for H2 transport require novel barrier chemistries against embrittlement, opening R&D partnerships with Siemens Energy and Thyssenkrupp installations.
- Digital coating specification platforms:Building information modeling integration allows real-time thickness monitoring and warranty documentation, capturing margin from EPC contractors in Dutch civil engineering consortiums.
Industry Challenges
- Cross-border formulation registration:ECHA substance dossier requirements vary by member state implementation, extending product launch timelines by 8-14 months for multi-national coating portfolios.
- Legacy asset retrofit complexity:Chemical processing facilities in Belgium's Antwerp port cluster require hot-work permit coordination and production shutdown windows, compressing application seasonality and crew utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Protective Coatings Market |
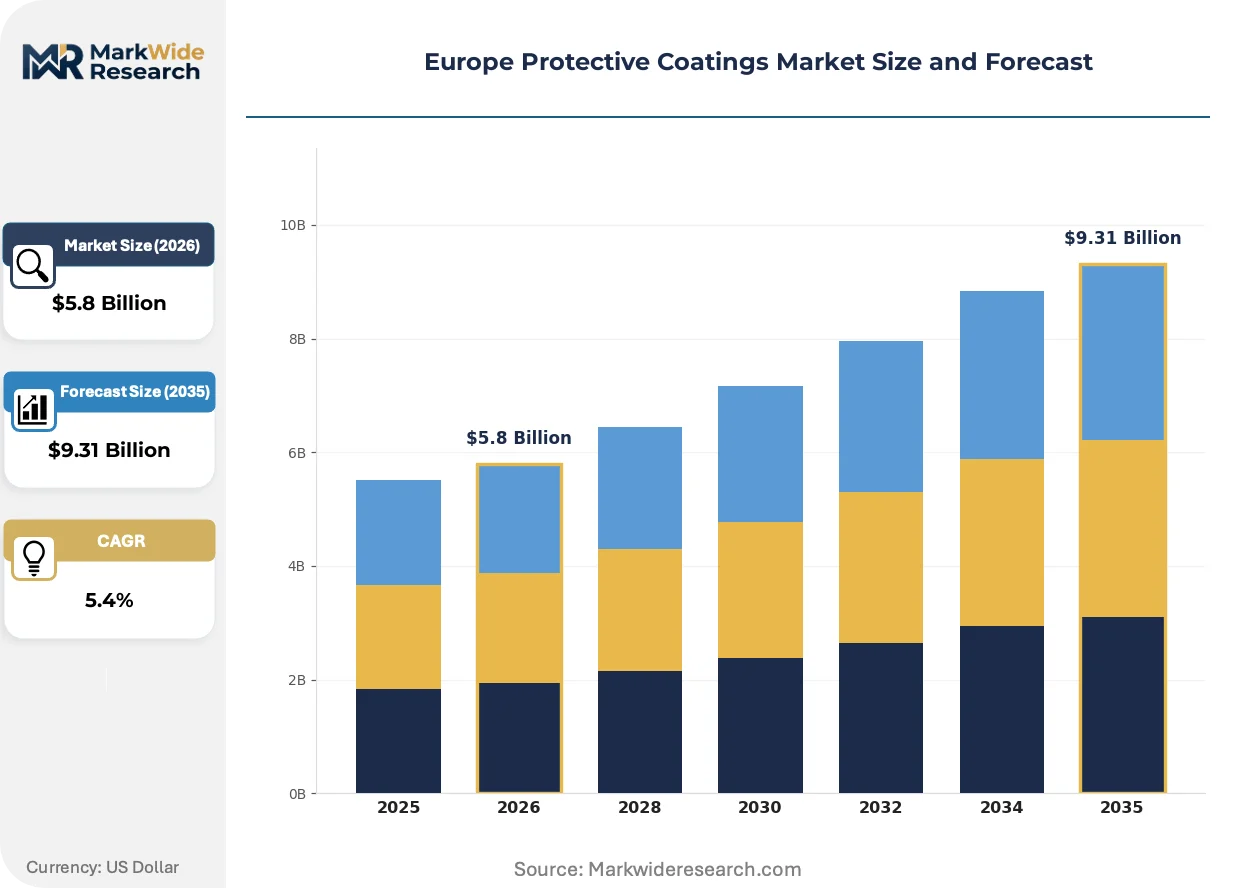
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Zinc Rich End User: Aerospace, Automotive OEMs, Marine, Construction Application: Corrosion Protection, Fire Protection, Wear Resistance, Chemical Resistance Technology: Water-Based, Solvent-Based, Powder Coatings, UV-Cured |
| Companies Covered | Hempel A/S, BASF SE, Akzo Nobel NV, RPM International Inc, Beckers Group, PPG Industries Inc, Jotun, Teknos Group, The Sherwin-Williams Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Protective Coatings Market Shifts & Advancements
Formulation chemistry and application methodology are converging around zero-VOC compliance and predictive asset management, redefining how coating value is captured across the European industrial base.
Self-healing polymer networks incorporating microcapsulated corrosion inhibitors are rendering obsolete conventional passive barrier systems in subsea and splash-zone applications. Norwegian and Danish offshore operators are piloting these chemistries on transformer platforms and jacket legs. The technology is compressing maintenance interval economics from five-year cycles toward ten-year guarantees, reshaping contractor service revenue models.
ECHA's restriction proposal on intentionally added microplastics is forcing reformulation of textured architectural coatings and anti-slip deck systems. Industrial consequences include accelerated bio-based filler development from lignin and cellulose sources. The Nordic construction sector, particularly Swedish and Finnish infrastructure agencies, is responding fastest through green public procurement criteria that pre-qualify microplastic-free alternatives.
Asset owner engineering teams are consolidating coating specification authority away from maintenance contractors and toward centralized technical procurement functions. This pattern concentrates volume with approved manufacturer lists and compresses spot-buying margins for regional distributors. The shift is most visible in German chemical processing and French nuclear maintenance, where TotalEnergies and EDF have implemented digital specification libraries with automated compliance checking.
Europe Protective Coatings Market Segmentation
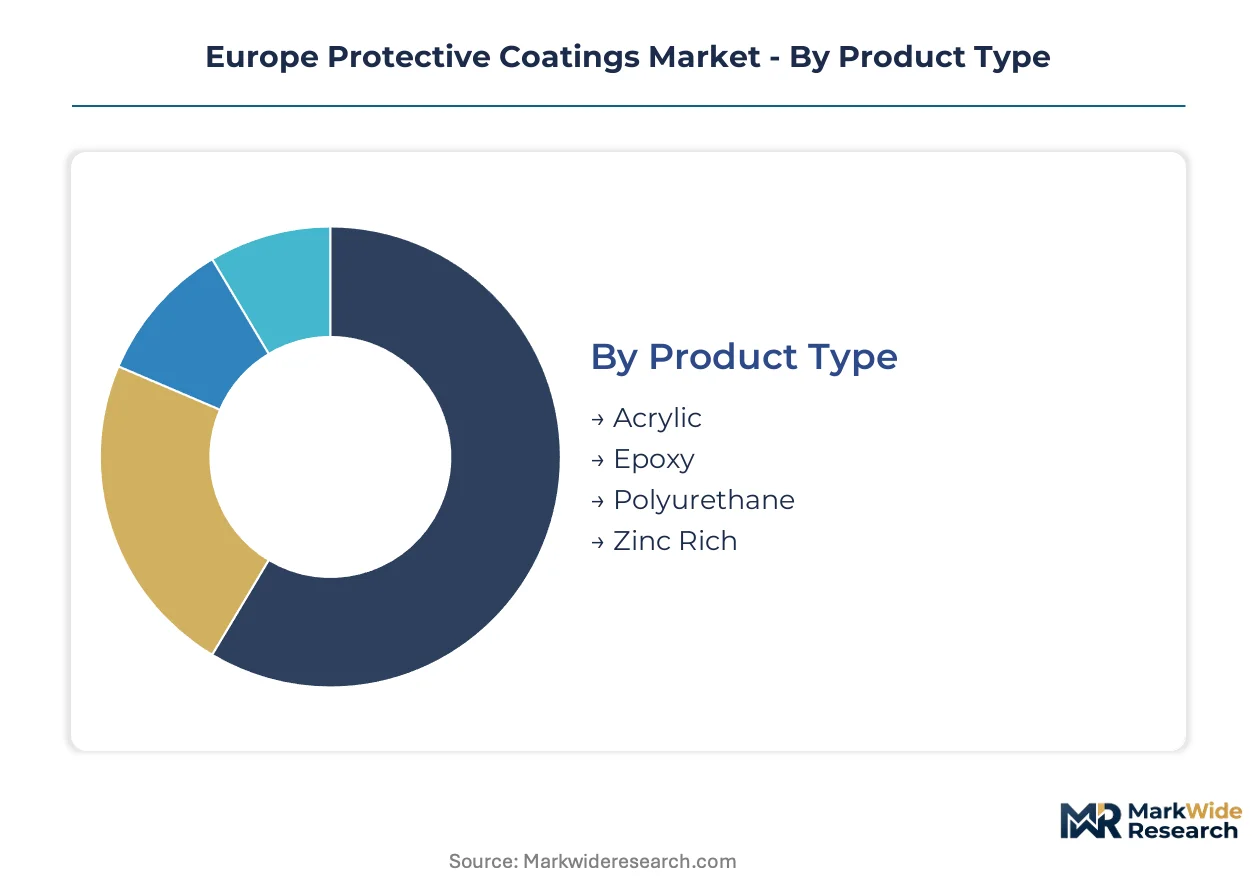
Protective coatings specification in Europe follows distinct technical hierarchies across product chemistry, end-use environment, and application method. Each segmentation dimension carries regulatory and procurement implications that determine margin capture and competitive positioning.
Product Type:
Use-case spectrum spans passive barrier systems through active sacrificial chemistries, with film thickness and cure requirements varying dramatically across substrate exposure severity.
- Epoxy:Two-part thermosetting systems built from bisphenol-A resins and polyamine hardeners deliver superior substrate adhesion and chemical resistance. German chemical processing facilities and Dutch port infrastructure specify epoxy at 250-400 micrometer dry film thickness for immersion service. REACH solvent restrictions are accelerating water-based epoxy conversions in automotive OEM supply chains.
- Polyurethane:Aliphatic and aromatic isocyanate-cured topcoats provide UV stability and color retention for exterior architectural exposure. Demand concentrates in French nuclear maintenance and Scandinavian bridge infrastructure where aesthetic durability intersects with corrosion protection. The segment is closing the gap fastest as topcoat specifications over epoxy primers become standard in offshore wind monopile protection systems.
- Acrylic:Thermoplastic resin systems offering rapid dry-to-touch properties and VOC compliance advantages in decorative maintenance applications.
- Zinc Rich:Inorganic and organic zinc silicate primers providing galvanic protection through sacrificial anode mechanisms at 75-85% metallic loading.
The dominant share belongs to Epoxy, while Polyurethane is closing the gap fastest.
End User:
Customer procurement sophistication ranges from specification-grade engineering teams to price-sensitive maintenance contractors, with certification requirements and warranty terms scaling accordingly.
- Marine:Dry-dock and new-build vessel applications demand anti-fouling and anti-corrosion systems certified by classification societies. North Sea offshore wind installation vessels and Orsted service craft drive specification-grade volume through Hamburg-Rotterdam-Antwerp applicator networks.
- Automotive OEMs:Paint shop integration requires electrocoat-compatible primers and chip-resistant underbody coatings with zero-defect quality protocols. German Saxony and Bavaria manufacturing clusters specify powder coating and water-based systems under OEM-approved manufacturer lists.
- Construction:Steel frame fire protection and infrastructure corrosion coatings for bridges, stadiums, and commercial buildings.
- Aerospace:Chromate-free pretreatments and high-performance topcoats for airframe and component protection under EASA certification requirements.
Marine commands the largest procurement volume, though Automotive OEMs are expanding most quickly through Eastern European supplier park migrations.
Application:
Functional performance requirements determine formulation complexity, with life-cycle cost modeling favoring premium chemistries in critical asset protection scenarios.
- Corrosion Protection:Barrier and inhibitive systems preventing electrochemical substrate degradation through moisture and oxygen exclusion. Offshore wind monopile foundations in Danish and German North Sea zones specify multi-layer systems exceeding 400 micrometers total film build.
- Chemical Resistance:Epoxy novolac and vinyl ester formulations protecting storage tanks and processing equipment against acid, alkali, and solvent exposure. Belgian Antwerp port petrochemical facilities drive specification demand with hot-work permit constraints compressing application windows.
- Fire Protection:Intumescent coatings expanding under heat exposure to insulate structural steel against critical temperature thresholds.
- Wear Resistance:Ceramic-filled and fluoropolymer-modified systems for abrasion-prone surfaces in material handling and processing equipment.
Corrosion Protection retains the dominant specification share, while Chemical Resistance is climbing the fastest on petrochemical capacity expansion.
Technology:
Regulatory compliance trajectories and capital equipment requirements create distinct competitive moats across application methodology categories.
- Water-Based:Acrylic and polyurethane dispersions with VOC content below REACH Annex XVII thresholds for decorative and industrial maintenance applications. German automotive OEM supply chains are mandating water-based conversions for body shop and component coating operations.
- Powder Coatings:Thermosetting epoxy and polyester systems applied electrostatically with near-zero VOC emission and overspray recovery economics. French and Italian architectural metal fabricators specify powder for curtain wall and window frame applications.
- Solvent-Based:Conventional high-solids and conventional-solids systems facing phased regulatory pressure but retained for specialized immersion and chemical resistance specifications.
- UV-Cured:Rapid-cure acrylate oligomer systems for flat-line wood coating and specialized industrial applications with limited European penetration.
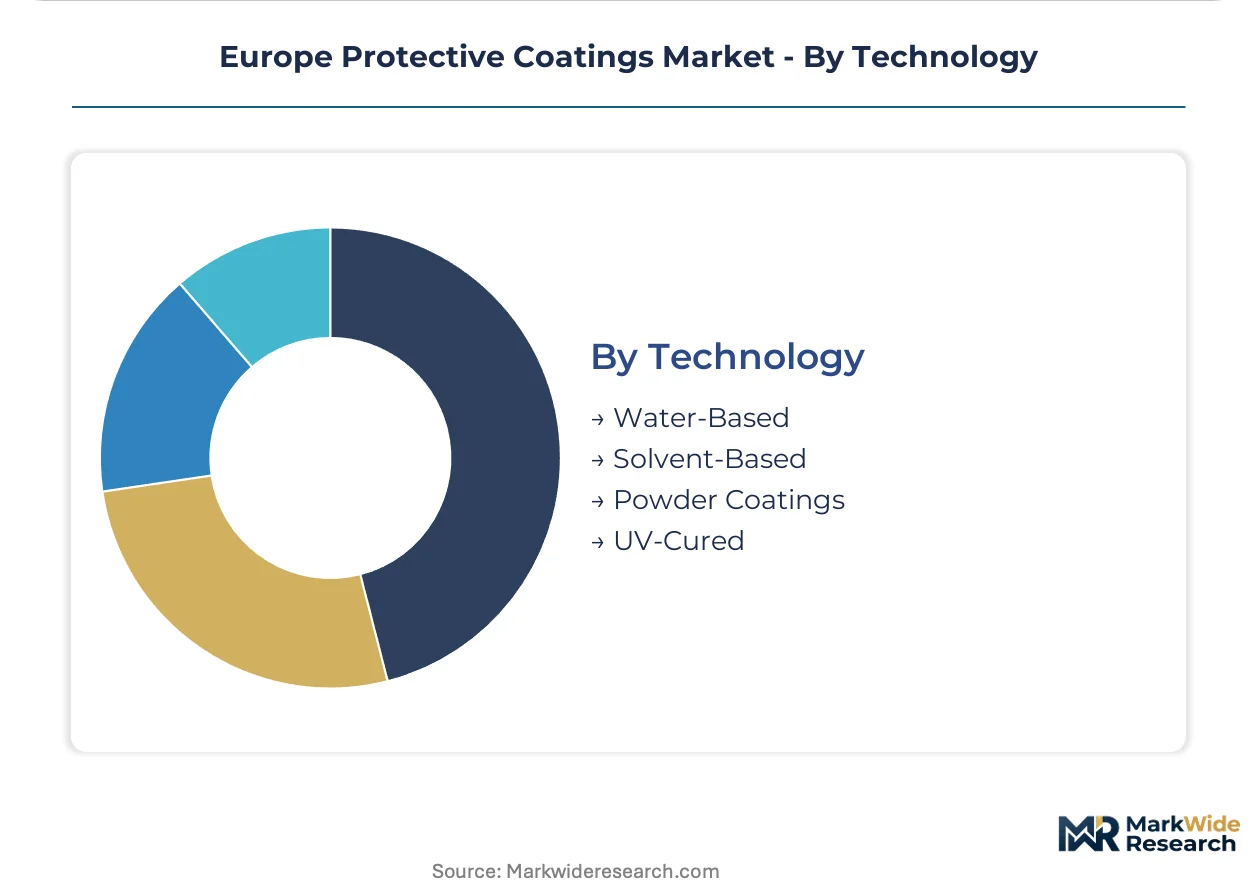
Water-Based technology holds the specification momentum, while Powder Coatings is gaining share fastest on architectural sustainability procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Eastern European automotive supplier parks exhibit acute price sensitivity, while North Sea offshore wind operators prioritize technical performance over procurement cost. This elasticity divergence shapes regional formulation strategies and service bundling across the continent.
Germany
Automotive OEM paint shops in Saxony and Bavaria mandate water-based epoxy conversions under REACH Annex XVII phasedown schedules. The country's Federal Environment Agency enforces VOC thresholds that compress solvent-based system margins. Industrial maintenance clusters around Cologne-Düsseldorf-Ruhr specify 300-micrometer film builds for chemical processing infrastructure.
Netherlands
Rotterdam port infrastructure and offshore wind installation vessels drive specification-grade marine coating procurement. The Dutch National Institute for Public Health and the Environment implements REACH substance dossier requirements that extend product launch timelines. EPC contractors in the Randstad corridor integrate digital specification platforms with real-time thickness monitoring.
France
Nuclear maintenance operations at EDF facilities and bridge infrastructure across Île-de-France specify aliphatic polyurethane topcoats for UV stability. The country's ecological transition ministry enforces EU Green Deal carbon reporting requirements on imported steel substrates. Lyon-based architectural metal fabricators specify powder coating systems for curtain wall applications.
Denmark
Ørsted installation schedules and transformer platform maintenance create sustained demand for subsea anti-corrosion systems. The Danish Environmental Protection Agency pilots microplastic-free coating pre-qualification through green public procurement criteria. Copenhagen-Roskilde corridor contractors test self-healing polymer networks on jacket legs and monopile foundations.
Poland
Automotive component manufacturing migration from German border regions generates greenfield powder coating demand near Krakow and Katowice. The country's Chief Inspectorate of Environmental Protection adopts REACH implementation timelines that lag Western counterparts by 12-18 months. Silesian industrial zones attract specification-grade applicators serving Volkswagen and BMW supplier parks.
Europe Protective Coatings Market Competitive Landscape
Capability concentration sits with specialized marine and industrial formulators; scale advantage sits with diversified chemical conglomerates and cross-sector coatings portfolios. The European protective coatings sector structures around three tiers: integrated chemical majors with resin backward integration, standalone coating specialists with application service bundling, and regional formulators serving price-sensitive maintenance contractors. Dominant competitive moves include technical service contract capture tied to asset maintenance schedules and water-based formulation conversions ahead of regulatory deadlines.
Within the specialist tier, Hempel A/S and Jotun exemplify marine-focused positioning anchored to offshore wind sector penetration. Akzo Nobel NV occupies a position spanning architectural powder coatings and industrial maintenance specifications. BASF SE represents the integrated chemical major archetype with captive epoxy resin supply. These three enterprises collectively illustrate the capability-scale tension reshaping procurement authority consolidation and compliant formulation transitions across European industrial end-uses.
| Leading Market Players |
|---|
| Hempel A/S |
| BASF SE |
| Akzo Nobel NV |
| RPM International Inc |
| Beckers Group |
| PPG Industries Inc |
| Jotun |
| Teknos Group |
| The Sherwin-Williams Company |
| Others |
Supply & Pricing Matrix
REACH Annex XVII solvent restrictions compress margins for legacy formulators while opening specification windows for water-based alternatives, determining both the premium-to-economy spread across German automotive OEM supply chains and the geographic concentration of compliant resin production.
Pricing Analysis
Aftermarket technical service contracts tied to marine dry-dock schedules drive lifetime value capture for specialized applicators. Pricing stratifies across specification-grade, certified-maintenance, and spot-buying tiers, with differentiation anchored in FROSIO/NACE inspector certification and warranty-backed film thickness guarantees. Cost compression in solvent-based segments intensifies because of bisphenol-A and amine hardener volatility during German and Dutch chemical producer curtailments. Eastern European automotive supplier parks exhibit acute price sensitivity, while North Sea offshore wind operators prioritize technical performance over procurement cost.
Supply Chain Analysis
Export-control scrutiny on dual-use chemical precursors limits flows of specialized epoxy hardeners and corrosion inhibitors into European coating formulation. Epoxy resin supply draws from German and Dutch chemical majors, with zinc metal feedstock anchored in Nordic and Belgian refining operations. Single-source vulnerability concentrates in bisphenol-A resin supply among three continental producers. Distribution runs through Hamburg-Rotterdam-Antwerp applicator networks serving marine and offshore wind installation schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Protective Coatings Market functions as a regulatory-moat story. REACH compliance entrenchment creates switching costs that favor incumbents with established ECHA substance dossiers and approved manufacturer list positioning.
For Market Incumbents: Build certification moats through accelerated water-based epoxy and polyurethane conversions ahead of Annex XVII phasedown deadlines. Deepen backward integration into captive amine hardener supply to buffer against German chemical producer curtailment risk. Capture technical service contract volume tied to Ørsted and RWE offshore wind maintenance schedules. Consolidate specification authority through digital coating libraries with automated REACH compliance checking for EDF and TotalEnergies procurement functions. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian automotive supplier parks where powder coating demand outruns qualified applicator supply. Target hydrogen infrastructure coating specifications for Siemens Energy and Thyssenkrupp high-pressure vessel installations, where novel barrier chemistries against embrittlement remain underdeveloped. Penetrate through digital specification platform partnerships with Dutch EPC contractors integrating real-time thickness monitoring. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustments reshape the acquisition landscape toward domestic applicators with certified lifecycle transparency. Long-term viability centers on formulators with water-based technology portfolios and offshore wind sector penetration. Acquisition target archetype: mid-cap specialists with FROSIO-certified inspector networks and monopile foundation specification track records. Watch the interplay between bio-based resin certification schemes and procurement criteria evolution as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Formulation Conversion | REACH Annex XVII compliance secures specification access in German automotive OEM supply chains. |
| Offshore Wind Technical Service Expansion | Ørsted and Equinor installation schedules create recurring revenue from monopile maintenance contracts. |
| Backward Integration into Epoxy Resin | Captive bisphenol-A supply buffers margin compression from Dutch and German producer curtailments. |
| Digital Specification Platform Deployment | Building information modeling integration captures margin from Dutch civil engineering consortiums. |
| Hydrogen Infrastructure Coating Development | Novel barrier chemistries against embrittlement open R&D partnerships with Siemens Energy installations. |
Research Methodology
Operator-level perspectives from plant engineers at Belgian Antwerp petrochemical facilities, marine coating applicators in the Hamburg-Rotterdam-Antwerp corridor, automotive OEM paint shop managers in Saxony and Bavaria, and EPC procurement officers in the Dutch Randstad anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation against ECHA substance dossier databases, Cefic chemical industry reports, customs trade data on epoxy resin flows, and SEC filings from listed coating manufacturers. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Scenario bracketing around REACH implementation timelines and EU Green Deal carbon border adjustment phasing structured the projection framework. Segmentation dimensions modeled include product chemistry tier, end-use environment severity, application method compliance trajectory, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume forecasts incorporating raw material price volatility assumptions and installation schedule visibility from major offshore wind developers. Industry-specific inputs encompassed film thickness specification trends and qualified applicator capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in energy-intensive chemical production costs, North Sea offshore wind capital commitment cycles, or Eastern European automotive investment flows would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation pacing and technology substitution elasticities. Cross-checking against ECHA registration database trends and Cefic production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Australia Industrial Coatings Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
Topcoat Market
Coatings
Global Solar Panel Coatings Market
Coatings
Vietnam Architectural Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Trim Coatings Market
Coatings
Shipping Container Coatings Market
Coatings
Global Pipe Coatings Market
Coatings
Japan Protective Coatings Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Bio-Fouling Prevention Coatings Market
Coatings
Global Smart Coating Market
Coatings
Thailand Architectural Coatings Market
Coatings
Rail Coatings Market