
 Saudi Arabia Pharmaceutical Market | 2026-2036
Saudi Arabia Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Pharmaceutical Market Outlook
Hospital procurement channels in Saudi Arabia is narrowing as the Ministry of Health consolidates purchasing through NUPCO, the national unified procurement company. Pfizer Inc. leverages its established oncology portfolio to sustain institutional contracts across King Faisal Specialist Hospital and Research Centre and other tertiary facilities. Tabuk Pharmaceuticals anchors its position through backward integration into active pharmaceutical ingredient sourcing, reducing import dependency. Jamjoom Pharmaceuticals Co. competes on cost-engineered generics tailored to SFDA bioequivalence requirements.
Pharmaceuticals in Saudi Arabia encompass chemically synthesized or biologically derived substances formulated for disease prevention, diagnosis, or treatment, with specifications governed by SFDA Good Manufacturing Practice guidelines and ICH stability protocols. The primary commercial purpose centers on therapeutic intervention across acute and chronic care pathways within a health system transitioning toward insurance-based reimbursement. Prescription drugs dominate value pools as chronic disease prevalence rises, while biologics capture expanding margin concentration in oncology and immunology despite cold-chain infrastructure demands. Generics face structural pressure from local content mandates under the Saudi Vision 2030 localization targets, though price ceilings limit absolute profitability.
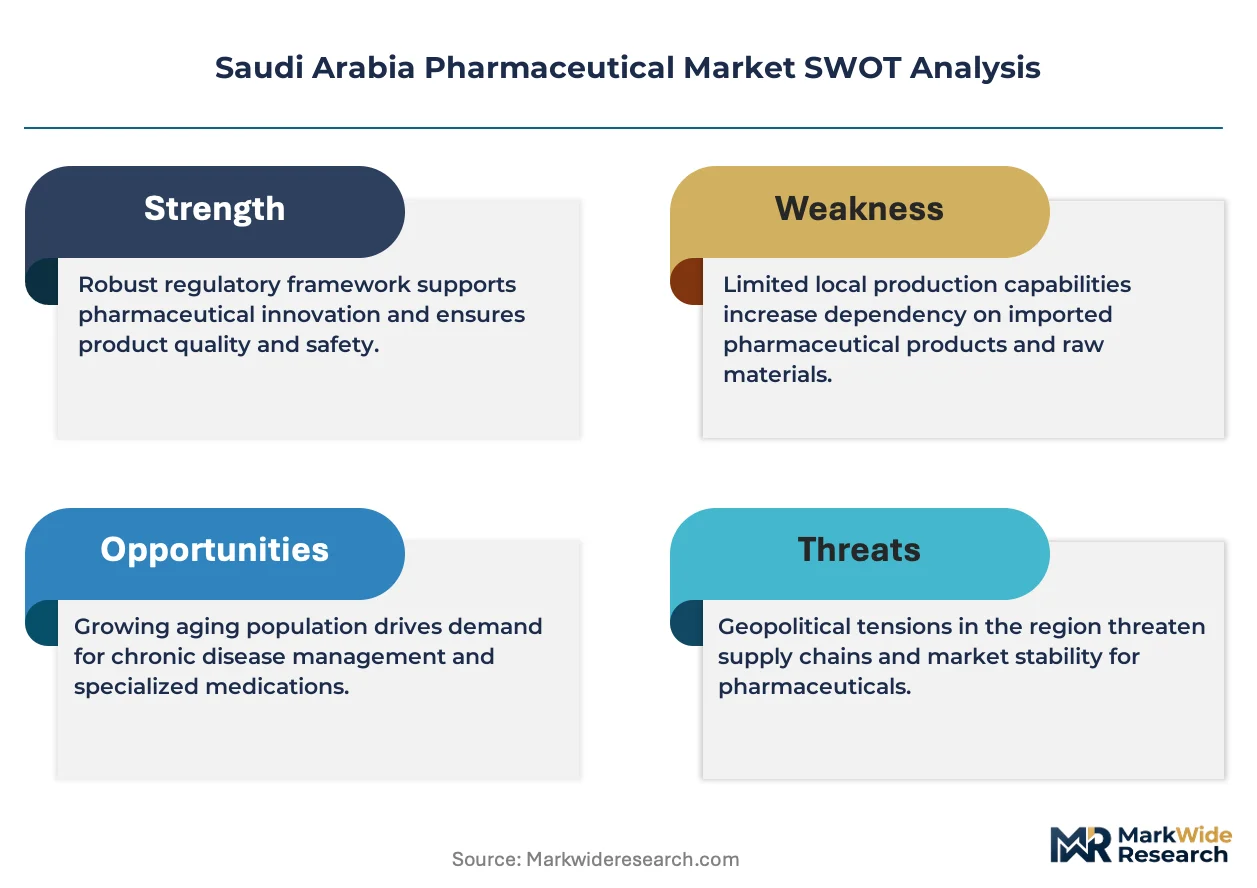
SFDA regulates product registration, manufacturing inspections, and pharmacovigilance, with bioequivalence study requirements for generics tightening market access for non-compliant applicants. The Saudi Food and Drug Authority also enforces GCC harmonized standards alongside WHO prequalification references for imported biologics. NUPCO's centralized tendering introduces volume-based procurement discipline that rewards manufacturers with domestic production capacity. Stakeholders must monitor the pace of health insurance mandate expansion and the localization threshold escalations that will determine competitive viability for imported versus locally manufactured therapies.
Market Dynamics
NUPCO's centralized procurement mandate is compressing hospital purchasing autonomy and forcing manufacturers to restructure distribution relationships around single-tender volumes rather than fragmented institutional contracts.
Growth Catalysts
- Health Sector Transformation Program:Government investment in tertiary care infrastructure is expanding specialty therapy demand across oncology and immunology service lines.
- SFDA bioequivalence harmonization:Tightened generics standards are accelerating technology transfer partnerships that upgrade local manufacturing capabilities.
- Chronic disease prevalence:Rising diabetes and cardiovascular burden in Riyadh and Jeddah is expanding prescription drug volume pools through insurance-mandated coverage expansion.
Market Restraints
- API import dependency:Active pharmaceutical ingredient sourcing concentrates in Indian and Chinese suppliers, exposing manufacturers to currency volatility and shipping disruptions.
- Price ceiling compression:NUPCO tender mechanisms cap reimbursement rates for established molecules, constraining margin recovery on local production investments.
- Cold-chain infrastructure gaps:Biologics distribution requires temperature-controlled logistics that remain underdeveloped outside major metropolitan clusters.
Strategic Opportunities
- Localization mandates under Vision 2030:Domestic production thresholds create preferential tender access for manufacturers with Saudi-based formulation facilities.
- Biosimilar development:Patent cliffs on reference biologics open white space for cost-engineered alternatives targeting oncology and autoimmune indications.
- Digital therapeutics integration:Remote patient monitoring platforms are converging with chronic disease management protocols in Ministry of Health pilot programs.
Industry Challenges
- SFDA inspection backlog:Manufacturing site approval timelines stretch 18-24 months, delaying product launches and freezing capital in work-in-progress inventory.
- Bioprocessing skill scarcity:Cell culture and downstream purification expertise remains concentrated among expatriate workforces with limited local training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Pharmaceutical Market |
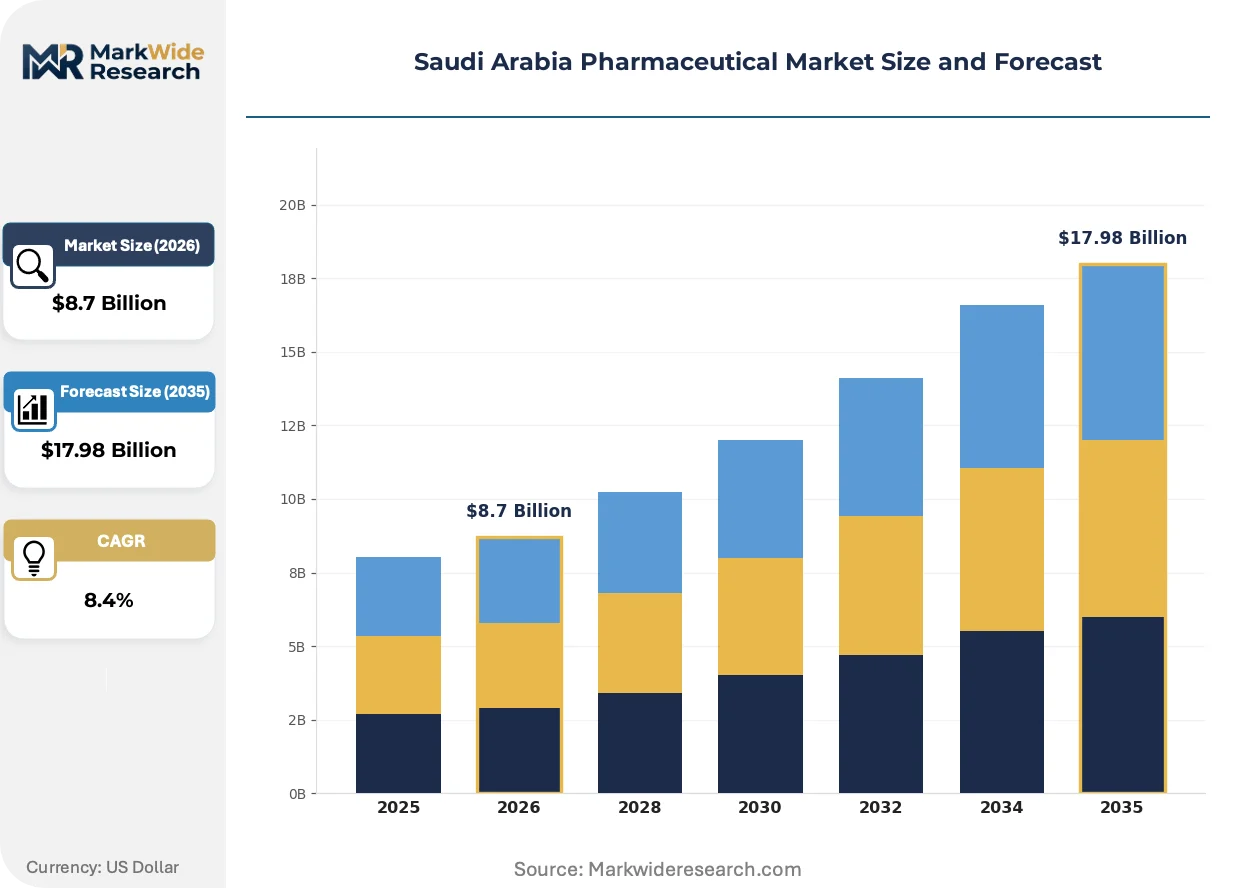
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Biologics, Generics Therapy Area: Cardiovascular, Oncology, Neurology, Diabetes Delivery Mode: Oral, Injection, Topical, Inhalation End User: Hospitals, Retail Pharmacies, Clinics, Home Care |
| Companies Covered | Pfizer Inc., Sanofi, Novartis AG, AstraZeneca Plc, Merck & Co., Inc., GSK Plc, SPIMACO, Jamjoom Pharmaceuticals Co., Tabuk Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Pharmaceutical Market Strategic Shifts
Digital infrastructure is virtualizing traditional pharmaceutical value chains, compressing the distance between manufacturing intelligence and clinical decision-making while regulatory frameworks accelerate localization requirements.
Continuous manufacturing technology is virtualizing batch-based production economics. King Faisal Specialist Hospital and Research Centre procurement teams are piloting real-time release testing protocols that accept quality data streams in lieu of finished-goods quarantine. This compression is collapsing inventory holding periods and enabling just-in-time supply contracts that penalize delivery variance rather than specification deviation.
SFDA's alignment with ICH Q12 lifecycle management guidelines is formalizing post-approval change management protocols. Manufacturers can now implement manufacturing process modifications through established change control categories rather than supplemental applications. Biologics producers with established Saudi operations are exploiting this regulatory efficiency to accelerate technology transfer from parent facilities.
Hospital formulary committees are consolidating purchasing authority under NUPCO's centralized tendering, displacing individual pharmacy department autonomy. Volume aggregation is compressing supplier rosters and privileging manufacturers with domestic production certificates. Riyadh-based tertiary facilities are leading this consolidation, with Jeddah clusters following 12-18 months behind in procurement centralization maturity.
Saudi Arabia Pharmaceutical Market Segmentation
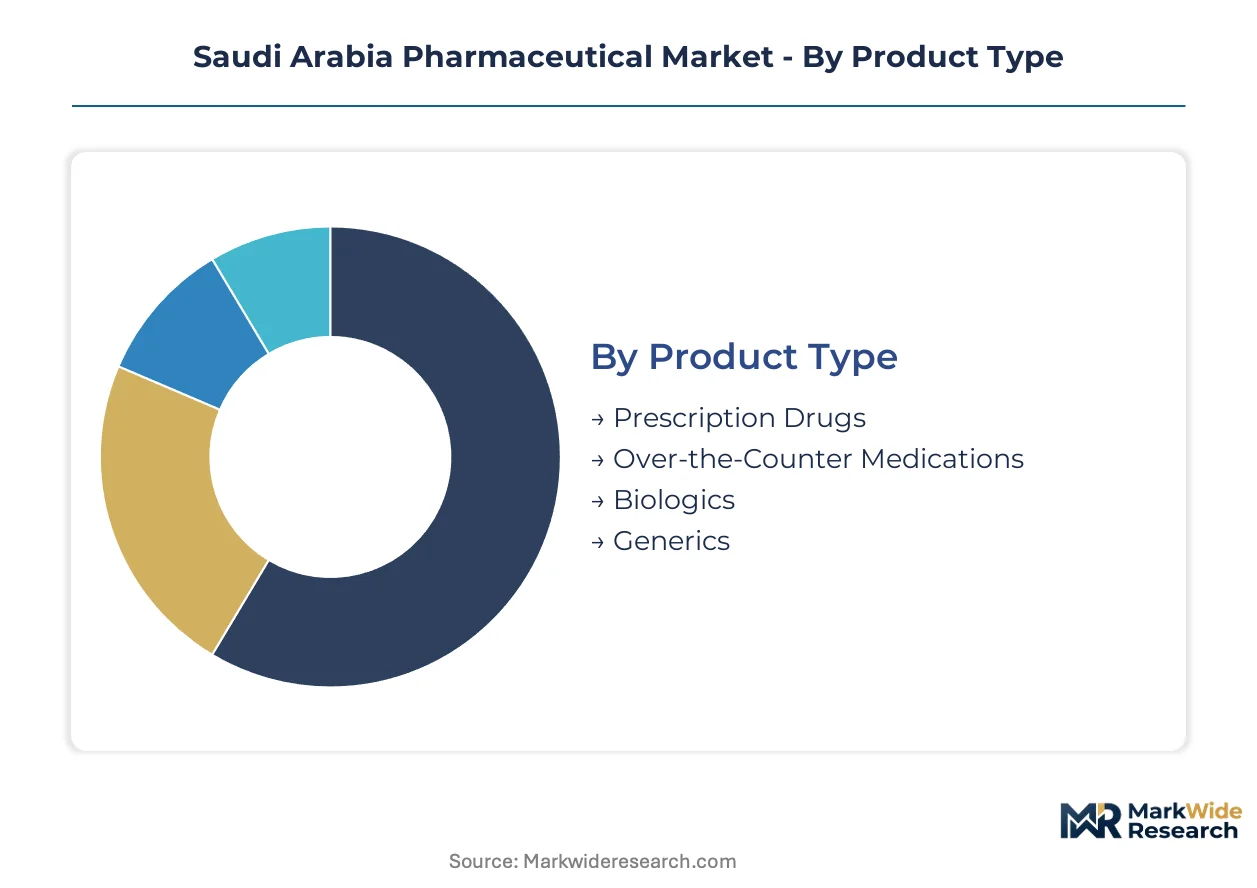
Segmentation in the Saudi Arabia pharmaceutical market reveals how NUPCO procurement, SFDA regulatory pathways, and Vision 2030 localization mandates reshape competitive positioning across product categories. Understanding these divisions exposes where margin pools concentrate and where volume tenders compress profitability.
Product Type:
Cycle times vary sharply across product types, with biologics requiring extended cold-chain logistics and prescription drugs turning through retail channels fastest.
- Prescription Drugs:Chronic disease protocols in Riyadh and Jeddah drive volume concentration. Insurance mandate expansion under the Health Sector Transformation Program is accelerating dispensing frequency through hospital outpatient departments.
- Biologics:Temperature-sensitive monoclonal antibodies and recombinant proteins require validated cold-chain infrastructure. King Faisal Specialist Hospital and Research Centre anchors demand for oncology and immunology biologics despite distribution cost premiums.
- Over-the-Counter Medications:Self-medication patterns concentrate in retail pharmacy clusters across urban centers. Consumer familiarity with analgesic and gastrointestinal categories supports repeat purchase velocity.
- Generics:SFDA bioequivalence standards filter applicant pools. Local manufacturers with domestic formulation certificates capture preferential NUPCO tender access.
Prescription drugs anchor the volume base while biologics gains share at the steepest rate.
Therapy Area:
Cost tiers separate therapy areas, with oncology biologics commanding premium reimbursement and cardiovascular generics facing NUPCO price ceiling compression.
- Oncology:Targeted therapies and immuno-oncology agents command institutional procurement priority. Tertiary care expansion under Vision 2030 health infrastructure investment is expanding infusion center capacity.
- Cardiovascular:Antihypertensive and anticoagulant categories dominate prescription volume pools. Chronic disease prevalence in Riyadh metropolitan clusters sustains recurring demand.
- Diabetes:Insulin analogs and oral hypoglycemic agents face formulary scrutiny. Ministry of Health screening programs are expanding diagnosed patient pools.
- Neurology:Disease-modifying therapies for multiple sclerosis and epilepsy require specialist prescribing networks. Distribution concentrates through hospital neurology departments.
Cardiovascular therapies anchor the volume base while oncology gains share at the steepest rate.
Delivery Mode:
Application requirements dictate delivery mode selection, with hospital-based infusion therapy favoring injection formats and chronic outpatient management defaulting to oral compliance.
- Oral:Tablet and capsule formulations dominate outpatient dispensing. Retail pharmacy networks in Jeddah and Riyadh prioritize shelf-stable solid dosage forms.
- Injection:Intravenous and subcutaneous delivery requires healthcare professional administration. Hospital procurement consolidation through NUPCO favors pre-filled syringe formats.
- Topical:Dermatological and transdermal applications serve localized treatment protocols. Compounding pharmacy capabilities remain limited outside tertiary centers.
- Inhalation:Respiratory therapy devices require patient training infrastructure. Pulmonology department partnerships determine formulary placement.
Oral delivery anchors the volume base while injection gains share at the steepest rate.
End User:
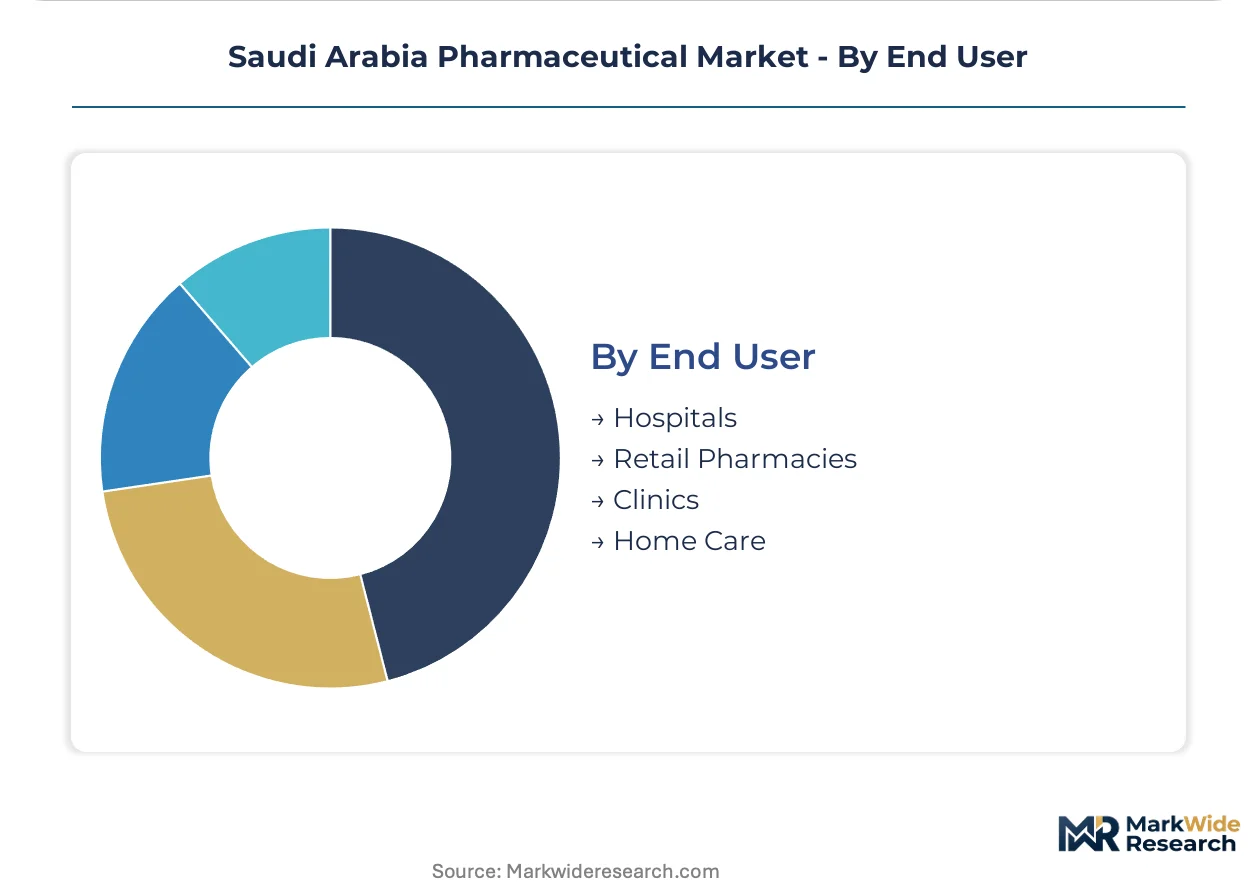
Customer type determines procurement pathway, with NUPCO centralized tendering displacing hospital pharmacy autonomy while retail channels serve cash-paying and insured outpatients.
- Hospitals:Institutional procurement concentrates through NUPCO tender mechanisms. Tertiary facilities in Riyadh anchor specialty therapy demand.
- Retail Pharmacies:Community dispensing faces margin pressure from price controls. Chain consolidation is concentrating purchasing power.
- Clinics:Primary care settings favor generic prescribing protocols. Ministry of Health primary health center expansion is extending reach.
- Home Care:Post-acute and palliative therapy delivery requires nursing support infrastructure. Insurance reimbursement for home infusion remains limited.
Hospital procurement anchors the volume base while home care gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA anchors pharmaceutical governance across Saudi Arabia's health system transformation, with sub-regional demand clustering around tertiary care infrastructure and procurement consolidation patterns.
Riyadh
Chronic disease prevalence and tertiary care expansion drive prescription volume concentration. The Health Sector Transformation Program channels investment into oncology and immunology service lines. King Faisal Specialist Hospital and Research Centre anchors specialty biologics procurement through NUPCO tender mechanisms.
Eastern Province
Industrial zone proximity supports active pharmaceutical ingredient import logistics and local formulation facilities. SFDA manufacturing inspections concentrate on Jubail and Dammam production sites. Dammam pharmaceutical clusters serve as distribution hubs for cold-chain biologics targeting hospital networks.
Western Region
Jeddah retail pharmacy density and medical tourism traffic sustain over-the-counter and prescription dispensing velocity. Ministry of Health primary health center expansion extends generic drug access. Jeddah tertiary facilities trail Riyadh by 12-18 months in NUPCO procurement centralization maturity.
NEOM Northwest
Greenfield health infrastructure investment creates demand for digital therapeutics integration and remote patient monitoring platforms. Vision 2030 localization mandates attract manufacturing joint ventures. NEOM pharmaceutical zones target bioprocessing capabilities to reduce expatriate workforce dependency.
Saudi Arabia Pharmaceutical Market Competitive Environment
Multinational innovators and domestic manufacturers split the market along patent-protected specialty and cost-engineered generic vectors. Consolidation pressure from NUPCO volume aggregation privileges players with domestic production certificates. Three archetypes dominate: research-intensive originators with oncology portfolios, backward-integrated local producers with API sourcing control, and bioequivalence-focused generic specialists. Competitive moves center on technology transfer partnerships and localization joint ventures.
Within the originator tier, Pfizer Inc. and Novartis AG exemplify institutional contract anchoring through established specialty portfolios. Among domestic manufacturers, SPIMACO and Tabuk Pharmaceuticals occupy positions shaped by Vision 2030 localization thresholds and preferential tender access. Jamjoom Pharmaceuticals Co. represents the bioequivalence-compliant generic archetype competing on cost-engineered formulations tailored to SFDA tightened standards.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi |
| Novartis AG |
| AstraZeneca Plc |
| Merck & Co., Inc. |
| GSK Plc |
| SPIMACO |
| Jamjoom Pharmaceuticals Co. |
| Tabuk Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Indian and Chinese API manufacturing is compressing supplier margins and enabling Saudi formulation facilities to negotiate favorable input pricing. NUPCO's volume aggregation transfers this leverage into tender-winning positions for domestic manufacturers.
Pricing Analysis
Riyadh-Jeddah price spreads for identical molecules reach double digits, reflecting cold-chain cost premiums and distribution density gaps. Three-tier pricing structure across originator biologics, licensed biosimilars, and SFDA-certified generics separates procurement tiers. Cost compression in the generic segment is intensifying because NUPCO ceiling rates anchor reimbursement regardless of API import volatility. Retail pharmacy chains exhibit highest price sensitivity, while tertiary hospital formulary committees prioritize clinical outcome guarantees over unit cost.
Supply Chain Analysis
Upstream active pharmaceutical ingredient production draws from India, China, and limited European specialty chemical suppliers. Key inputs include fermentation-derived antibiotics, synthetic organic intermediates, and recombinant protein cell lines. Single-source vulnerability concentrates in oncology biologics where cold-chain certification limits qualified vendors. Distribution runs through NUPCO central warehouses to hospital networks, bypassing traditional wholesaler markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi pharmaceutical demand fragments across NUPCO institutional procurement, retail pharmacy chains, and emerging home infusion channels. This dispersion creates niche entry points for specialized players outside volume-tender battlegrounds.
For Market Incumbents: Build regulatory certification moats through SFDA bioequivalence study investments and domestic formulation facility expansion. Anchor NUPCO tender positions by securing local production certificates ahead of Vision 2030 threshold escalations. Counter biosimilar entrants by locking oncology biologics contracts with real-world evidence protocols at King Faisal Specialist Hospital and Research Centre. For New Entrants and Emerging Players: Home care infusion services in Jeddah and Riyadh represent the most penetrable entry point, with insurance reimbursement gaps creating cash-pay opportunities outside NUPCO procurement. Target digital therapeutics integration partnerships with Ministry of Health chronic disease pilot programs. Establish go-to-market presence through specialist nursing networks rather than hospital pharmacy committees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across generic formulation manufacturing as continuous processing technology reduces batch-scale requirements. Five-to-ten year viability favors acquisition targets with backward integration into API sourcing and established SFDA inspection track records. Monitor NUPCO tender participation rates as early signals of competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Bioequivalence Certification | Unlocks NUPCO preferential tender access for domestic manufacturers. |
| API Backward Integration | Reduces currency exposure and secures supply continuity for formulation facilities. |
| Biosimilar Development Partnership | Captures oncology and immunology volume as reference biologics face patent cliffs. |
| Cold-Chain Infrastructure Investment | Enables biologics distribution beyond Riyadh-Jeddah metropolitan clusters. |
| Digital Therapeutics Integration | Aligns with Ministry of Health remote patient monitoring pilot expansion. |
Study Parameters
Desk research of SFDA registration databases, NUPCO tender documentation, and GCC trade flow statistics preceded structured interviews with hospital procurement managers, regulatory affairs leads at domestic manufacturers, formulary directors at tertiary facilities, and pharmaceutical distribution channel heads. Primary fieldwork combined with secondary validation through WHO prequalification records and ICH stability protocol references. Bottom-up volume modeling triangulated against top-down health expenditure projections.
Assumptions held fixed include SFDA regulatory alignment with ICH guidelines and NUPCO centralized procurement mandate continuity, while variables included health insurance mandate expansion pace and Vision 2030 localization threshold escalations. Segmentation modeling spanned product type, therapy area, delivery mode, and end user across the analysis window. CAGRs derived from regression against chronic disease prevalence trajectories and tertiary care infrastructure investment schedules, with biologics cold-chain capacity buildout and generic manufacturing technology transfer timelines as key inputs.
Practitioners should monitor SFDA inspection backlog clearance rates and NUPCO tender volume allocation shifts for early signals of competitive repositioning. Cross-checking against WHO prequalification status changes and GCC harmonized standard updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Calcimimetic Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Vaginal Ring Market