
 Asia-Pacific Gastrointestinal Drugs Market | 2026-2036
Asia-Pacific Gastrointestinal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Gastrointestinal Drugs Market Outlook
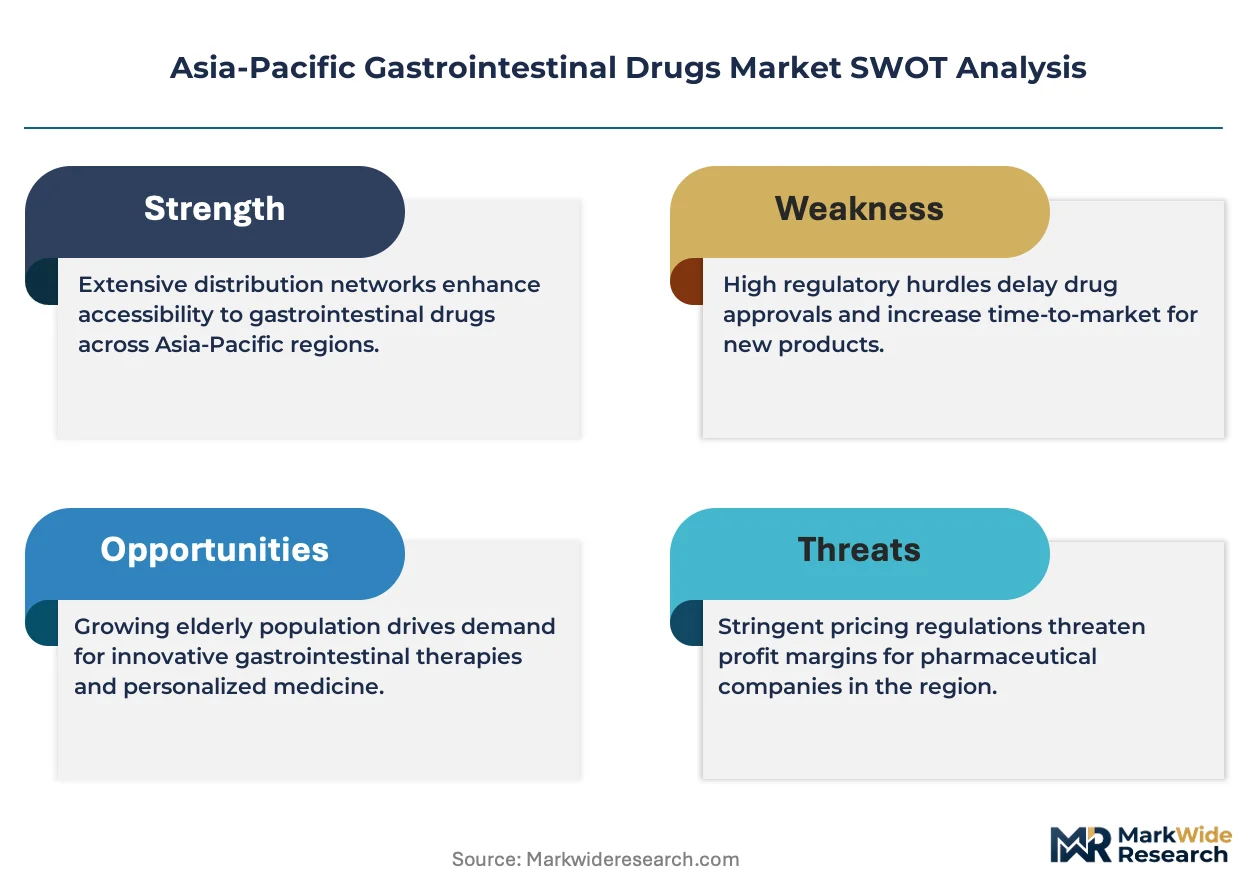
Combination therapy bundling of proton pump inhibitors with antacids is expanding as hospital formularies seek cost-efficient ulcer management protocols. Takeda Pharmaceutical Company Limited leverages its heritage in acid-related disorder therapies to sustain premium positioning across Japanese and Southeast Asian markets. Dr. Reddy's Laboratories Ltd. anchors its competitive stance through high-volume oral generic manufacturing for Indian and export markets. Sun Pharmaceutical Industries Ltd. differentiates via integrated active pharmaceutical ingredient-to-finished-dose capabilities that control cost structures in price-sensitive segments.
Asia-Pacific gastrointestinal drugs encompass chemically synthesized and biologically derived pharmaceutical agents formulated for the treatment, management, or symptomatic relief of disorders affecting the esophagus, stomach, intestines, and associated accessory organs, with oral solid dosages typically requiring gastric acid resistance through enteric coating or delayed-release matrix systems to preserve therapeutic integrity. These products serve to modulate gastric pH, regulate motility, reduce inflammation, or eradicate pathogenic colonization in clinical and ambulatory settings. Proton pump inhibitors command the largest revenue pool due to chronic prescription patterns in gastroesophageal reflux disease, while antidiarrheals demonstrate the fastest volume expansion linked to rising infectious disease incidence in tropical climates. The therapy area segmentation reveals irritable bowel syndrome as an emerging focus for novel mechanism drug development, whereas peptic ulcer therapy represents a mature category facing biosimilar and generic erosion.
Japan's PMDA enforces stringent stability testing and post-market surveillance for oral gastrointestinal formulations, while India's CDSCO mandates incremental bioequivalence documentation that shapes generic market entry timelines. Australia's TGA aligns with ICH quality guidelines but imposes additional regional labeling requirements that complicate multi-country product registration strategies. Stakeholders must monitor regulatory divergence in pharmacovigilance reporting obligations as a determinant of portfolio prioritization and launch sequencing across the region.
Market Dynamics
Hospital procurement consolidation across Southeast Asia is compressing supplier margins while elevating volume commitments for proton pump inhibitor manufacturers serving ulcer management protocols.
Growth Catalysts
- CDSCO bioequivalence mandates:India's tightened documentation requirements for oral generics are filtering substandard manufacturers and concentrating market share among compliant domestic producers.
- Enteric coating technology maturation:Advances in pH-dependent polymer matrices are extending drug stability in tropical climates, expanding addressable markets across Indonesia and Philippines.
- China's retail pharmacy consolidation:Tier-one city chains are standardizing gastrointestinal portfolios, creating predictable demand baselines for chronic therapy suppliers.
Market Restraints
- API import dependency:Active pharmaceutical ingredient sourcing concentrates in eastern Chinese manufacturing clusters, exposing formulators to shipping volatility and customs delays.
- PMDA stability testing burden:Japan's extended post-approval surveillance protocols add eighteen to twenty-four months to product launch timelines for new entrants.
- Biosimilar erosion in peptic ulcer therapy:Biologic analogues are capturing hospital formulary slots previously held by small-molecule acid suppressants in Australian tertiary centers.
Strategic Opportunities
- Vietnam's underpenetrated hospital sector:Provincial healthcare infrastructure expansion is creating first-mover advantages for proton pump inhibitor suppliers establishing direct distribution.
- Digital pharmacy integration:Telemedicine platforms in South Korea are enabling prescription-to-doorstep delivery models for irritable bowel syndrome maintenance therapies.
- TGA-ICH alignment:Australia's streamlined quality guidelines reduce multi-country registration complexity for manufacturers targeting Pacific Rim markets simultaneously.
Industry Challenges
- Pharmacovigilance reporting fragmentation:Divergent adverse event documentation standards between PMDA, CDSCO, and TGA force redundant safety database maintenance.
- Legacy ERP integration:Hospital procurement systems across Thailand and Malaysia require customized EDI protocols that delay electronic order automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gastrointestinal Drugs Market |
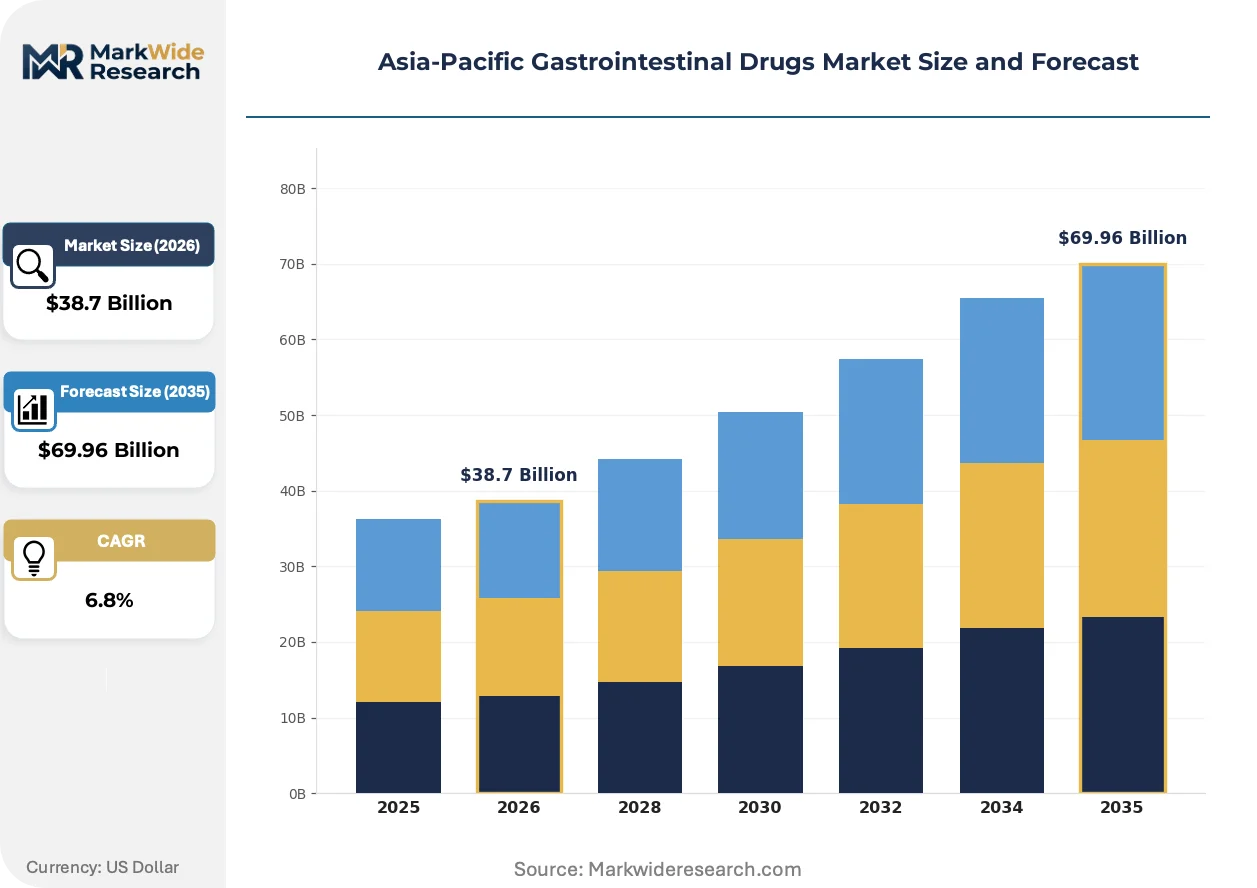
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antacids, Proton Pump Inhibitors, Antidiarrheals, Laxatives Therapy Area: Peptic Ulcer, Irritable Bowel Syndrome, Gastroesophageal Reflux Disease, Constipation Delivery Mode: Oral, Injectable, Topical, Transmucosal End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Takeda Pharmaceutical Company Limited, Astellas Pharma Inc., Dr. Reddy’s Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Cipla Ltd., AstraZeneca PLC, Eisai Co., Ltd., Daiichi Sankyo Company, Limited, Kalbe Farma, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gastrointestinal Drugs Market Strategic Shifts
Formulation science is pivoting toward patient adherence engineering as chronic gastrointestinal conditions demand multi-year therapy continuity in aging Asia-Pacific populations.
Multilayer tablet architectures are modularizing dose delivery across proton pump inhibitor and antibiotic combinations. Japanese hospital pharmacies are adopting these fixed-dose products for Helicobacter pylori eradication protocols. The technology is modularizing manufacturing workflows by enabling single-press production of previously separate administration sequences.
PMDA's 2023 revision to stability testing guidelines for moisture-sensitive oral solids is forcing reformulation of existing delayed-release products. Domestic Japanese manufacturers are accelerating investment in barrier packaging technologies. Southeast Asian exporters targeting Japan must now validate accelerated aging data under elevated humidity conditions previously exempted.
Retail pharmacy chains in China's Yangtze River Delta are unbundling gastrointestinal diagnostics from prescription fulfillment. Community clinics now perform rapid urease testing before recommending therapy. This pattern is most visible in Shanghai and Hangzhou, where vertical integration between diagnostic device suppliers and pharmacy networks is compressing the prescriber-pharmacist transaction loop.
Asia-Pacific Gastrointestinal Drugs Market Segmentation
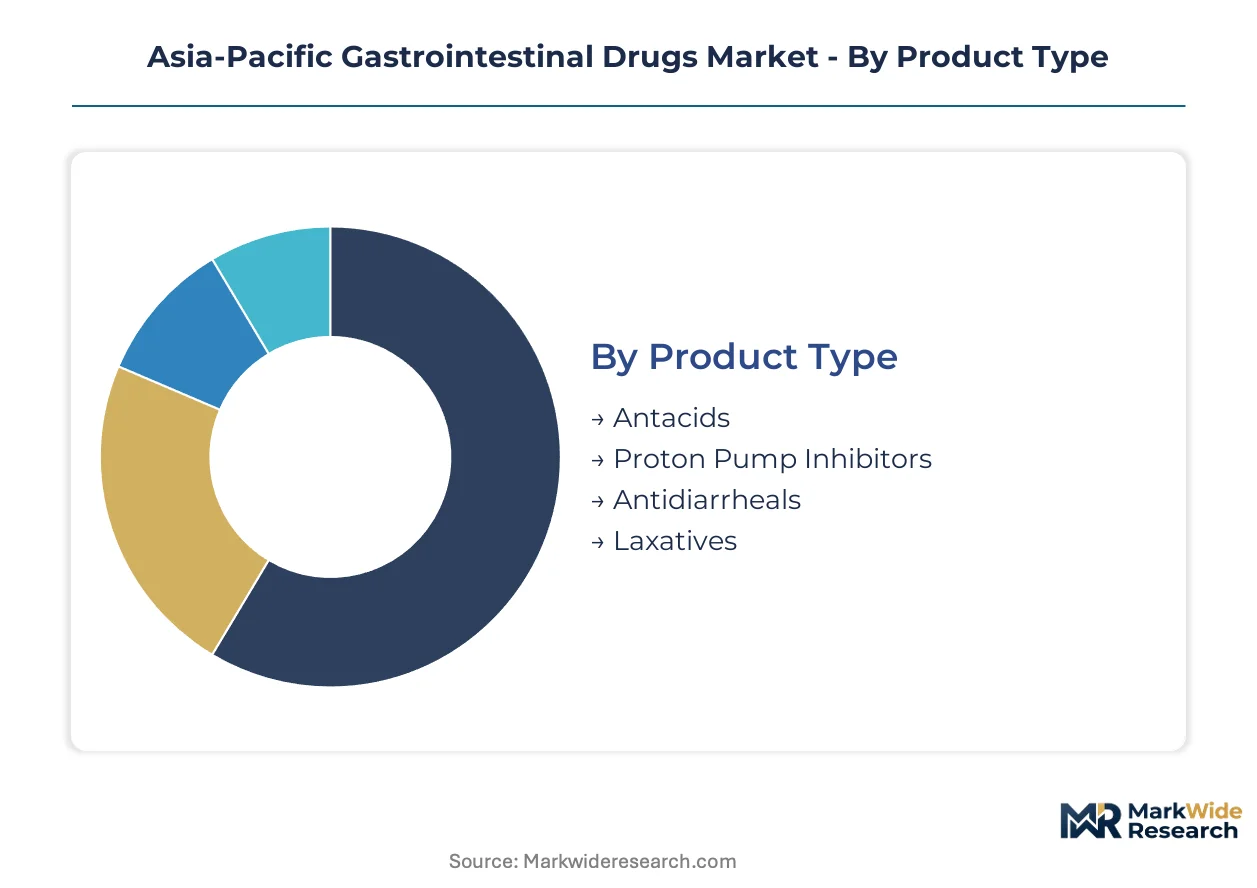
Gastrointestinal drug segmentation in Asia-Pacific reflects divergent regulatory pathways and procurement economics. Each category maps distinct certification burdens to addressable patient populations across hospital, retail, and ambulatory channels.
Product Type:
Proton pump inhibitors and antacids face Japan PMDA stability testing mandates, while antidiarrheals navigate India's CDSCO bioequivalence documentation for tropical climate formulations.
- Antacids:Aluminum and magnesium hydroxide compounds neutralize gastric acid through rapid chemical reaction. Hospital formularies across Thailand and Vietnam favor these for immediate symptomatic relief in emergency departments, though retail pharmacy chains in China's tier-one cities are consolidating portfolios around fixed-dose combinations with alginate.
- Proton Pump Inhibitors:Omeprazole, esomeprazole, and lansoprazole suppress gastric acid secretion via irreversible H+/K+ ATPase inhibition. Japanese and Australian tertiary centers drive chronic prescription volumes for gastroesophageal reflux disease maintenance, with Southeast Asian hospital procurement consolidation compressing supplier margins while elevating volume commitments.
- Antidiarrheals:Loperamide and bismuth subsalicylate formulations address infectious and functional diarrhea. Demand concentrates in Indonesia and Philippines where tropical climate conditions elevate enteric pathogen exposure.
- Laxatives:Osmotic, stimulant, and bulk-forming agents manage constipation. Polyethylene glycol solutions gain traction in South Korean home care settings linked to aging demographics.
Proton pump inhibitors sit at the top of the volume ranking, with antidiarrheals climbing the fastest.
Therapy Area:
Peptic ulcer therapy commands mature hospital procurement contracts, while irritable bowel syndrome attracts novel mechanism development investment.
- Peptic Ulcer:Helicobacter pylori eradication protocols and acid suppression therapies dominate hospital formularies. Australian tertiary centers are substituting biosimilar analogues for small-molecule acid suppressants, eroding traditional revenue pools.
- Irritable Bowel Syndrome:Serotonin modulators and guanylate cyclase agonists target visceral hypersensitivity and bowel dysfunction. South Korean telemedicine platforms are enabling prescription-to-doorstep delivery for maintenance therapies.
- Gastroesophageal Reflux Disease:Chronic acid suppression drives proton pump inhibitor consumption. China's retail pharmacy consolidation in Yangtze River Delta cities is standardizing diagnostic-therapy bundles with rapid urease testing.
- Constipation:Opioid-induced and functional constipation categories expand with aging populations. Japanese PMDA post-market surveillance requirements extend eighteen to twenty-four months for new entrant launches.
Gastroesophageal reflux disease anchors revenue concentration, with irritable bowel syndrome expanding most quickly.
Delivery Mode:
Oral solid dosages require enteric coating or delayed-release matrices to preserve therapeutic integrity against gastric acid, while injectable formats concentrate in hospital critical care.
- Oral:Tablets, capsules, and suspensions constitute the dominant administration route. PMDA's 2023 stability testing revision for moisture-sensitive oral solids forces reformulation of delayed-release products targeting Japanese markets.
- Injectable:Intravenous proton pump inhibitors serve acute upper gastrointestinal bleeding in hospital settings. Provincial healthcare infrastructure expansion in Vietnam creates first-mover advantages for suppliers establishing direct distribution.
- Topical:Rectal formulations address localized inflammation and delivery bypass. Usage concentrates in Australian and New Zealand ambulatory surgical recovery protocols.
- Transmucosal:Buccal and sublingual absorption routes bypass first-pass metabolism. Limited adoption outside Japanese geriatric care facilities managing dysphagia.
Oral formats dominate prescription volumes, with injectable formats gaining share fastest in acute care expansion.
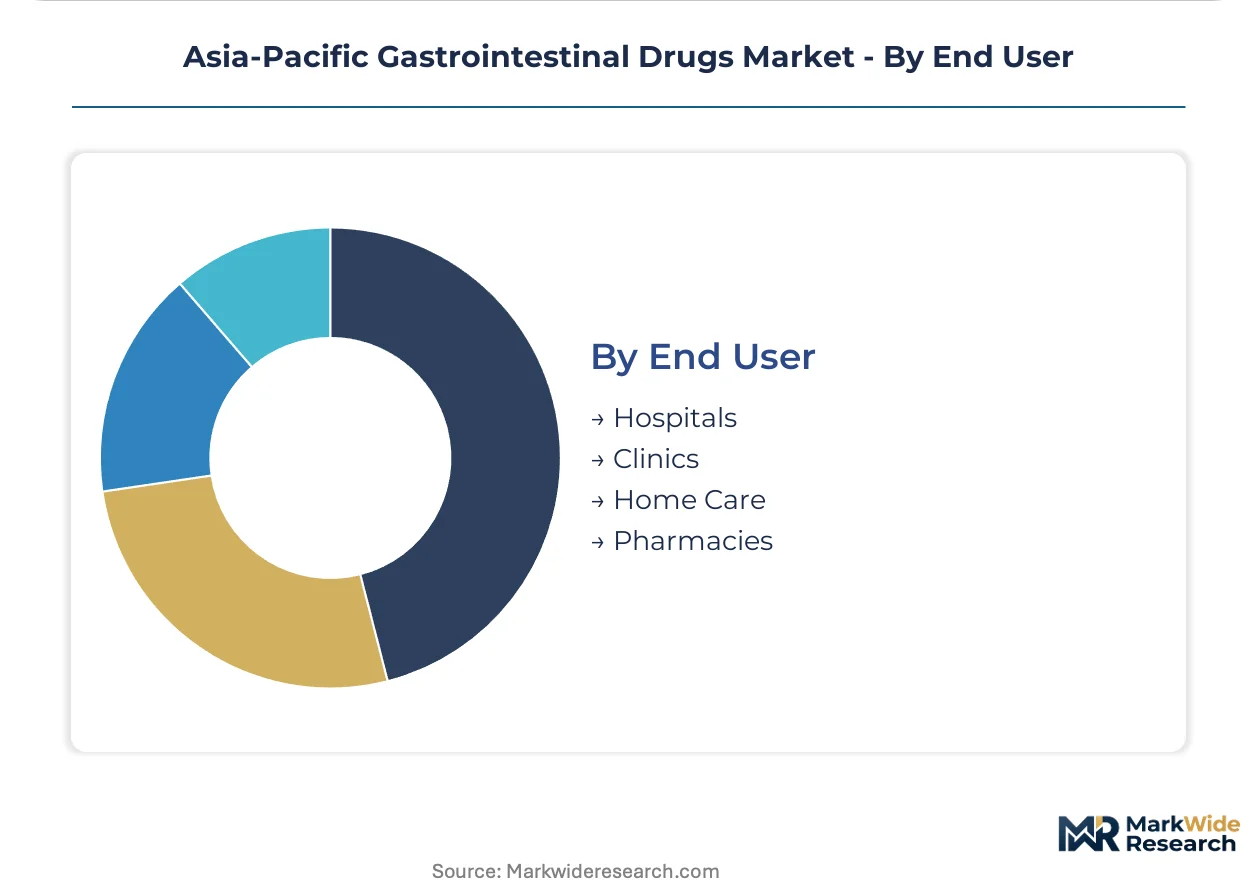
End User:
Hospital procurement systems across Southeast Asia demand customized EDI protocols, while home care channels leverage digital pharmacy integration.
- Hospitals:Tertiary and secondary facilities administer acute and chronic gastrointestinal therapies. Thailand and Malaysia require legacy ERP integration that delays electronic order automation for proton pump inhibitor suppliers.
- Clinics:Outpatient settings manage stable chronic conditions and initial diagnostics. Community clinics in Shanghai and Hangzhou perform rapid urease testing before therapy recommendation.
- Home Care:Self-administered maintenance therapies for reflux and irritable bowel syndrome. South Korean telemedicine platforms enable prescription fulfillment without clinic visitation.
- Pharmacies:Retail chains in China's tier-one cities consolidate gastrointestinal portfolios. Vertical integration between diagnostic device suppliers and pharmacy networks compresses prescriber-pharmacist transaction loops.
Hospitals retain the highest prescription volume, with home care channels showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's post-war pharmaceutical infrastructure established the region's first scaled gastrointestinal drug manufacturing base. Domestic innovators pioneered proton pump inhibitor chemistry that spread across Asia-Pacific markets through licensing arrangements. Contemporary demand patterns now diverge across regulatory environments shaped by national health technology assessment bodies.
Japan
Chronic gastroesophageal reflux disease prescriptions drive sustained proton pump inhibitor consumption in tertiary centers. PMDA's 2023 stability testing revision for moisture-sensitive oral solids extends launch timelines for new entrants by eighteen to twenty-four months. Osaka-based manufacturers accelerate barrier packaging investment to meet accelerated aging validation requirements under elevated humidity protocols.
China
Retail pharmacy consolidation in tier-one cities concentrates demand for chronic acid suppression therapies. NMPA bioequivalence documentation for oral generics filters substandard manufacturers and elevates compliant domestic producers. Yangtze River Delta diagnostic-therapy bundles integrate rapid urease testing with pharmacy fulfillment, compressing prescriber-pharmacist transaction loops in Shanghai and Hangzhou.
India
High-volume oral generic manufacturing anchors export supply to Southeast Asian and African markets. CDSCO tightened bioequivalence requirements reshape competitive positioning by extending documentation burdens for market entry. Hyderabad and Ahmedabad clusters concentrate active pharmaceutical ingredient-to-finished-dose capabilities that control cost structures in price-sensitive segments.
Australia
Tertiary hospital formularies substitute biosimilar analogues for small-molecule acid suppressants, eroding traditional peptic ulcer therapy revenue pools. TGA alignment with ICH quality guidelines reduces multi-country registration complexity for manufacturers targeting Pacific Rim markets simultaneously. Melbourne and Sydney procurement consolidation elevates volume commitments for compliant suppliers.
South Korea
Telemedicine platforms enable prescription-to-doorstep delivery for irritable bowel syndrome maintenance therapies in aging demographics. MFDS post-market surveillance requirements shape pharmacovigilance database investments for chronic therapy suppliers. Seoul Capital Area digital pharmacy integration outpaces provincial infrastructure, creating two-speed market access patterns.
Asia-Pacific Gastrointestinal Drugs Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory compliance and therapeutic innovation dimensions. Japanese and European-origin innovators command formulary positioning through heritage acid-related disorder portfolios. Indian and Southeast Asian manufacturers anchor the volume tier through scaled generic production. The competitive landscape segments into three archetypes: heritage innovators with legacy brand equity, vertically integrated generic specialists, and regional distributors with hospital procurement relationships. Consolidation pressures intensify as Southeast Asian hospital systems centralize purchasing and compress supplier margins.
Within the heritage innovator tier, Takeda Pharmaceutical Company Limited and Astellas Pharma Inc. exemplify sustained premium positioning through Japanese market dominance and Southeast Asian licensing networks. Among Indian-based integrated manufacturers, Dr. Reddy's Laboratories Ltd. and Sun Pharmaceutical Industries Ltd. occupy positions defined by high-volume oral generic output and captive active pharmaceutical ingredient supply. Cipla Ltd. represents the export-oriented archetype with concentrated presence in price-sensitive emerging markets.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Astellas Pharma Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Cipla Ltd. |
| AstraZeneca PLC |
| Eisai Co., Ltd. |
| Daiichi Sankyo Company, Limited |
| Kalbe Farma |
| Others |
Value Chain & Pricing Dynamics
API bulk chemical indices in eastern Chinese manufacturing clusters cascade through formulation economics into three distinct pricing tiers across Asia-Pacific gastrointestinal markets. Cost compression in proton pump inhibitor generics feeds back into active pharmaceutical ingredient sourcing decisions as Indian manufacturers rebalance captive production against import exposure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage innovator brands from bioequivalent generics and unbranded commodity tablets. Price differentiation hinges on PMDA stability certification and hospital formulary tier placement. Cost compression in Southeast Asian hospital procurement is intensifying because volume-commitment contracts compress supplier margins. Retail pharmacy chains in China's tier-one cities demonstrate highest price sensitivity, while Japanese tertiary centers maintain lowest sensitivity due to reimbursement insulation.
Supply Chain Analysis
India's PLI scheme for active pharmaceutical ingredients is reshaping sourcing patterns away from concentrated eastern Chinese clusters. API production draws from Hyderabad and Ahmedabad hubs, with finished-dose formulation tethered to Southeast Asian packaging facilities. Single-source vulnerability concentrates in enteric coating polymer supply. Distribution runs through hospital procurement consortia in Thailand and Malaysia alongside direct-to-pharmacy networks in South Korea's digital health corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where PMDA's 2023 stability testing revision for moisture-sensitive oral solids accelerates barrier packaging investment and premium tier consolidation.
For Market Incumbents: Anchor market position through backward integration into enteric coating polymer production and accelerated barrier packaging capacity in Osaka manufacturing clusters. Biosimilar substitution in Australian tertiary centers threatens small-molecule acid suppressant revenue pools, demanding formulary lock-in through multi-year hospital procurement contracts. For New Entrants and Emerging Players: CDSCO tightened bioequivalence documentation in India opens a window for compliant domestic manufacturers to capture export share from substandard competitors. Vietnam's provincial healthcare infrastructure expansion represents the most penetrable geography, with first-mover advantage available through direct distribution bypassing legacy distributor networks. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated generic specialists possessing captive API supply and PMDA-certified Japanese distribution infrastructure. Long-term viability favors manufacturers with dual regulatory footprint spanning India's CDSCO and Japan's PMDA compliance regimes. Watch for accelerated hospital procurement consolidation in Southeast Asia as inflection signal for margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | PMDA stability validation accelerates Japanese market entry timelines for moisture-sensitive formulations. |
| Backward Integration into API Production | Captive omeprazole intermediate supply insulates margin structures from Chinese shipping volatility. |
| Hospital Procurement System Partnership | Direct EDI integration with Thailand's centralized purchasing platforms secures volume commitments. |
| Digital Pharmacy Platform Integration | South Korean telemedicine partnerships enable prescription-to-doorstep delivery for IBS maintenance therapies. |
| Multilayer Tablet Manufacturing Scale-Up | Single-press production of fixed-dose H. pylori combinations captures Japanese hospital pharmacy adoption. |
Study Parameters
Multiple input streams — primary interviews with formulary directors and CDSCO regulatory affairs leads, secondary validation through FDA Orange Book filings and Japanese PMDA approval databases, and trade flow analysis from Indian pharmaceutical export statistics — were reconciled through bottom-up prescription volume modeling and top-down market sizing triangulation.
Historical volume trajectories were cross-referenced against expert panel assessments of bioequivalence documentation timelines and hospital procurement consolidation velocity across the analysis window. Segmentation dimensions encompassed therapy area, delivery mode, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to PMDA launch timeline extensions and China's retail pharmacy consolidation patterns.
Revisions become necessary when CDSCO further tightens bioequivalence requirements, PMDA extends stability testing protocols, or Southeast Asian hospital procurement centralization accelerates beyond modeled velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Global Anti Epileptic Drugs for Pediatrics Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Angiogenesis Inhibitors and Stimulators Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Global Acne Medication Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
RAS-Acting Agents Market
Pharmaceuticals
Intelligent Pills Market
Pharmaceuticals
Rupatadine Fumarate API Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Global Orphan Drugs Market