
 Eperisone Hcl Market | 2026-2036
Eperisone Hcl Market Size, Share, and Industry Trends Forecast 2026-2036
Eperisone Hcl Market Insights
Continuous manufacturing technology is narrowing the cost gap between batch and flow chemistry production of active pharmaceutical ingredients. Eisai Co., Ltd. leverages its integrated R&D infrastructure to sustain quality leadership in Japanese hospital channels. Sun Pharmaceutical Industries Ltd. anchors its position through backward integration into key starting materials for generic eperisone formulations. Teva Pharmaceutical Industries Ltd. competes across European pharmacy networks with specialized packaging formats for elderly adherence.
Eperisone hydrochloride functions as a centrally acting muscle relaxant with a piperidine-derived structure, inhibiting voltage-gated calcium channels at the spinal reflex arc to reduce myotonia without significant sedation. The compound's 2-oxazolidinone moiety confers improved blood-brain barrier permeability compared to structurally related tolperisone. Tablet formulations occupy the largest volume share across hospital and pharmacy channels, while injectable delivery modes capture premium pricing in acute postoperative rehabilitation settings where rapid onset proves clinically essential. Long-term care facilities represent an expanding end-user segment as aging populations in developed markets shift muscle spasticity management from acute to maintenance settings.
FDA bioequivalence standards for abbreviated new drug applications govern generic eperisone entry into US pharmacy distribution, while EMA's MDR framework shapes clinical evidence requirements for device-drug combination products in European rehabilitation clinics. Japan's PMDA maintains distinct pharmacokinetic reference ranges that influence formulation development by domestic manufacturers. Stakeholders must monitor evolving pharmacovigilance signal detection protocols across these jurisdictions, as regulatory divergence in muscle relaxant safety monitoring could fragment approval pathways and reshape competitive access timelines.
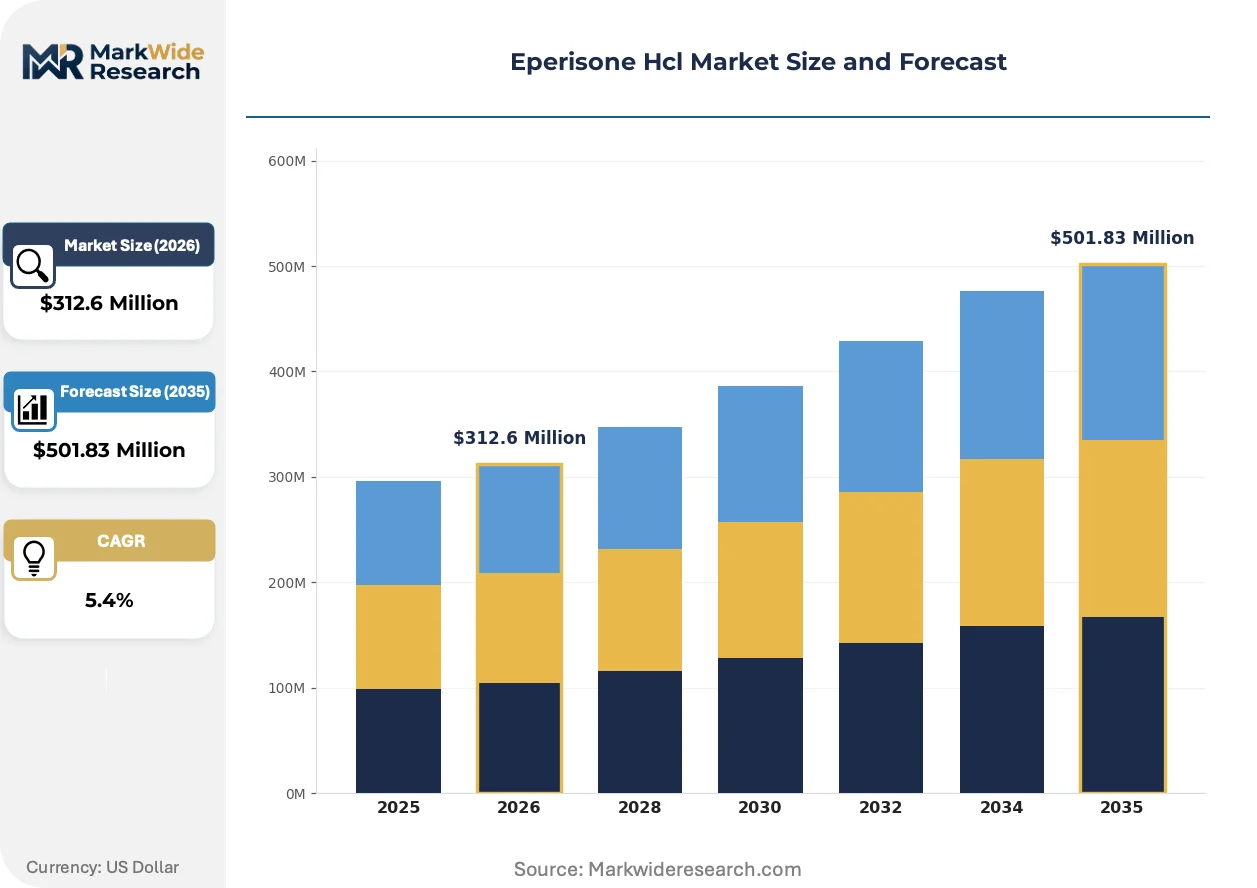
Market Dynamics
EMA pharmacovigilance tightening for muscle relaxant formulations is compressing approval timelines while continuous manufacturing technology narrows cost differentials between batch and flow chemistry API production.
Growth Catalysts
- Aging demographics in Japan:The country's geriatric rehabilitation sector generates sustained hospital procurement for maintenance-phase muscle spasticity management. Long-term care facilities now represent an expanding institutional channel.
- MDR framework in Europe:Device-drug combination products face elevated clinical evidence requirements that favor established manufacturers with integrated quality systems. Rehabilitation clinics increasingly specify certified combination therapies.
- Continuous flow chemistry:Pharmaceutical manufacturers adopting this production technology achieve tighter process control and reduced solvent waste. Cost convergence with traditional batch methods accelerates generic API accessibility.
Market Restraints
- API supply concentration:Backward integration into key starting materials limits supplier diversity, with captive production concentrated among integrated pharmaceutical conglomerates. Smaller generic formulators face input security vulnerabilities.
- Bioequivalence validation costs:FDA abbreviated new drug application requirements impose substantial clinical pharmacokinetic study burdens. Generic entrants must demonstrate equivalence to reference listed drugs through expensive crossover trials.
- Neuromuscular blocker substitution:Acute surgical settings increasingly favor depolarizing agents with faster reversal profiles. Eperisone's competitive positioning in postoperative rehabilitation encounters protocol displacement pressure.
Strategic Opportunities
- German pain management clinics:Tighter EMA vigilance requirements create competitive moats for manufacturers with established pharmacovigilance infrastructure. Specialized compliance capabilities differentiate supplier selection.
- Injectable-to-oral switching protocols:Hospital discharge pathways increasingly emphasize maintenance therapy transitions. Formulation developers capturing this handoff point secure longitudinal patient relationships.
- PMDA reference range harmonization:Japan's distinct pharmacokinetic standards favor domestic manufacturers with localized development expertise. Foreign entrants must establish Tokyo-based clinical operations to compete.
Industry Challenges
- Quality-by-design implementation:ICH Q8-Q12 guidelines require sophisticated process analytical technology deployment. Mid-scale manufacturers lack capital reserves for real-time release testing infrastructure.
- Cross-jurisdiction signal detection:Divergent pharmacovigilance protocols between EMA, FDA, and PMDA fragment safety database management. Coordinated adverse event reporting demands specialized regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eperisone Hcl Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $501.83 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injections, Powders Application: Muscle Spasticity, Pain Management, Neurologic Disorders, Rehabilitation End User: Clinics, Hospitals, Pharmacies, Long-term Care Facilities Delivery Mode: Oral, Injectable, Topical, Transdermal |
| Companies Covered | Eisai Co., Ltd., Taisho Pharmaceutical Co., Ltd., Aarti Drugs Ltd., Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Mitsubishi Tanabe Pharma, Zhejiang Hisun Pharmaceutical, Jiangsu Hengrui Medicine Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eperisone Hcl Market Trends and Innovations
Manufacturing technology convergence and regulatory evidence standardization are compressing development timelines while reshaping competitive differentiation in muscle relaxant supply.
Continuous manufacturing platforms for piperidine-derived APIs is hybridizing batch efficiency with flow chemistry precision. Japanese hospital procurement channels now specify real-time release testing capabilities as a supplier qualification criterion. This technology compression enables domestic manufacturers to defend quality leadership against lower-cost imports.
REACH chemical safety dossier requirements are extending to pharmaceutical intermediates with environmental release potential. European API manufacturers must now submit extended safety data sets for piperidine derivative starting materials. German chemical production clusters are consolidating environmental compliance functions to amortize documentation costs across product portfolios.
Hospital formulary committees are consolidating muscle relaxant categories around dual-mechanism candidates with demonstrated functional outcomes. Japanese geriatric rehabilitation centers now require mobility endpoint data for maintenance therapy authorization. This evidence-based preference shift favors suppliers with published real-world effectiveness studies over traditional promotional access models.
Eperisone Hcl Market Segmentation
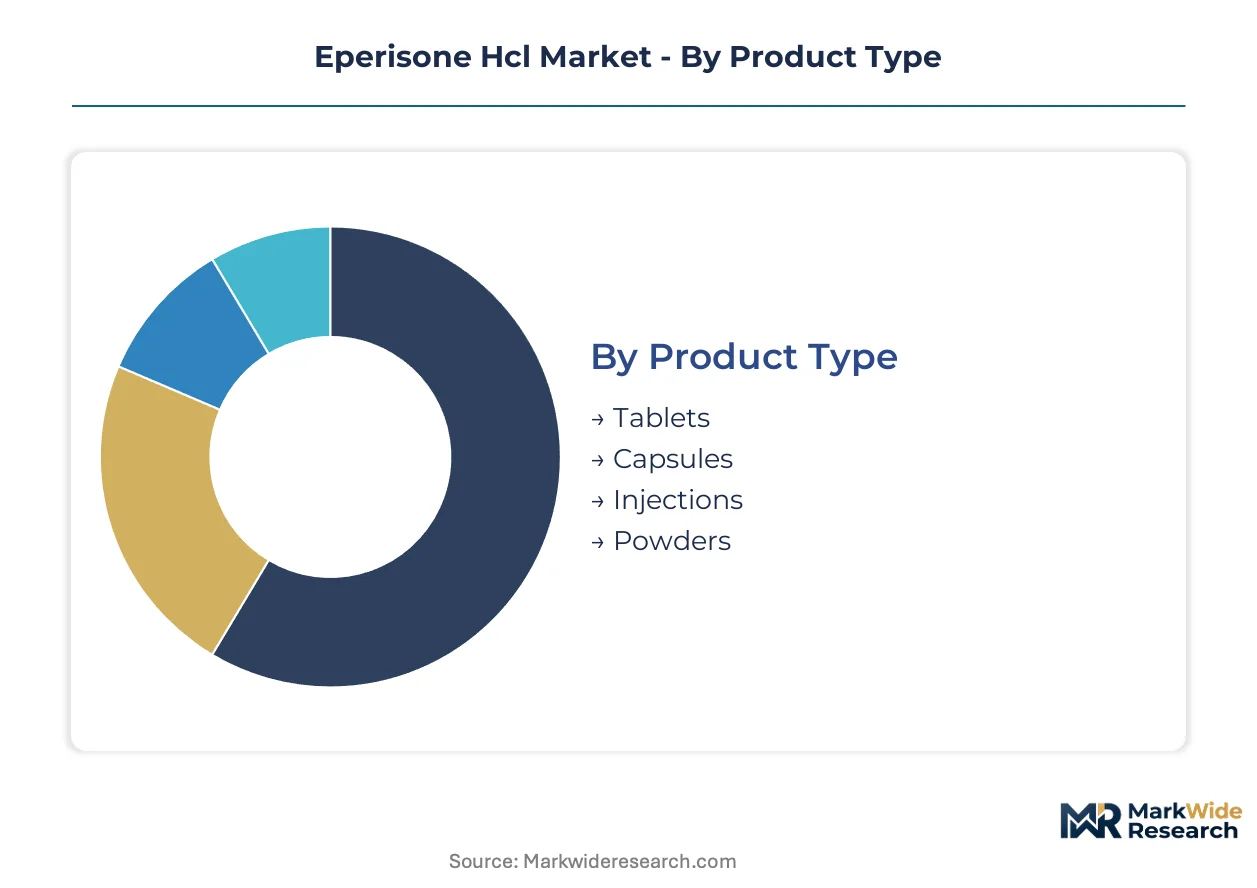
Segmentation in the Eperisone Hcl market reveals how formulation choices, clinical settings, and delivery technologies concentrate procurement power among specific institutional buyers. Manufacturers align product development with the technical requirements of Japan's geriatric rehabilitation networks and Germany's pain management clinics.
Product Type:
Cost tier differentiation across solid and liquid dosage forms determines margin structures and capital intensity requirements for API conversion.
- Tablets:Compressed formulations with defined dissolution profiles dominate hospital procurement volumes in Japan's maintenance-phase muscle spasticity protocols. German pain management clinics specify tablet stability under ambient storage conditions for outpatient dispensing.
- Injections:Parenteral solutions command premium positioning in acute postoperative rehabilitation where rapid onset proves clinically essential. European rehabilitation clinics increasingly require real-time release testing documentation for injectable batch certification.
- Capsules:Gelatin-shell encapsulation offers bioavailability advantages for patients with swallowing difficulties in long-term care settings.
- Powders:Bulk API formulations supply compounding pharmacies and regional generic manufacturers with formulation flexibility.
Tablets hold installed capacity. Injections are rotating up the share rankings.
Application:
Clinical indication focus shapes regulatory evidence requirements and determines which manufacturers capture formulary authorization from institutional purchasers.
- Muscle Spasticity:Primary indication for centrally acting muscle relaxants with established spinal reflex arc modulation. Japanese geriatric rehabilitation centers generate sustained procurement for maintenance-phase management of age-related spasticity.
- Pain Management:Adjunctive therapy in multimodal analgesia protocols for chronic musculoskeletal conditions. German clinics face tightened EMA pharmacovigilance requirements for muscle relaxant formulations in this category.
- Neurologic Disorders:Off-label utilization in upper motor neuron syndrome requires specialized neurological consultation for authorization.
- Rehabilitation:Post-stroke and post-surgical functional recovery programs emphasize mobility endpoint outcomes for therapy continuation.
Muscle Spasticity anchors volume concentration. Pain Management is climbing the fastest as EMA vigilance standards reshape supplier qualification.
End User:
Customer type determines packaging specifications, distribution logistics, and the depth of clinical evidence required for procurement authorization.
- Hospitals:Integrated health systems in Japan specify real-time release testing capabilities as mandatory supplier qualification criteria. Bulk purchasing agreements concentrate volume among domestic manufacturers with localized production infrastructure.
- Long-term Care Facilities:Aging population shifts in developed markets drive expansion of maintenance-phase muscle spasticity management outside acute settings. These institutions require elderly-adherent packaging formats with compliance monitoring features.
- Clinics:Outpatient rehabilitation centers prioritize cost efficiency in procurement decisions for recurring patient populations.
- Pharmacies:Retail dispensing channels compete on generic substitution policies and patient counseling services.
Hospitals hold installed capacity. Long-term Care Facilities are rotating up the share rankings.
Delivery Mode:
Administration route selection reflects the clinical urgency of onset requirements and the duration of therapy intended for specific patient populations.
- Oral:Swallowable dosage forms dominate maintenance therapy with established bioavailability profiles. Japanese PMDA reference ranges influence formulation development for this delivery mode.
- Injectable:Parenteral administration captures acute rehabilitation settings where rapid therapeutic effect supersedes patient convenience considerations.
- Topical:Localized application formulations address patients with systemic absorption concerns or polypharmacy complications.
- Transdermal:Patch-based delivery systems remain under development for sustained release in chronic spasticity management.
Oral delivery holds installed capacity. Injectable is gaining share fastest in postoperative rehabilitation protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in eperisone hydrochloride APIs tilt toward net-import dependence in European formulation markets while Japanese manufacturers maintain domestic supply sufficiency. Export volumes from Indian and Chinese API producers service generic formulators across multiple continents. Regional regulatory divergence shapes localized production strategies.
Japan
Geriatric rehabilitation centers in Tokyo and Osaka generate sustained hospital procurement for maintenance-phase muscle spasticity management. PMDA maintains distinct pharmacokinetic reference ranges that influence formulation development by domestic manufacturers. Kanto and Kansai industrial clusters host integrated pharmaceutical production infrastructure serving domestic hospital channels.
Germany
Pain management clinics in Bavaria and North Rhine-Westphalia face tightened EMA pharmacovigilance requirements for muscle relaxant formulations. REACH chemical safety dossier requirements extend to pharmaceutical intermediates with environmental release potential. Frankfurt-Rhine-Main chemical production clusters consolidate environmental compliance functions across product portfolios.
United States
FDA bioequivalence standards for abbreviated new drug applications govern generic eperisone entry into pharmacy distribution networks. Postoperative rehabilitation protocols in academic medical centers drive demand for rapid-onset injectable formulations. New Jersey and Massachusetts pharmaceutical corridors concentrate generic formulation development capabilities.
India
CDSCO regulatory pathways facilitate API export to European and North American generic formulators. Backward integration into key starting materials anchors competitive positioning among integrated pharmaceutical conglomerates. Gujarat and Maharashtra chemical manufacturing zones concentrate piperidine derivative production capacity.
China
NMPA oversight of active pharmaceutical ingredient quality standards shapes export competitiveness to regulated markets. Continuous manufacturing technology adoption narrows cost differentials in piperidine-derived API production. Jiangsu and Zhejiang pharmaceutical industrial parks expand flow chemistry capabilities for muscle relaxant intermediates.
Eperisone Hcl Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with integrated quality systems and captive API production. Three strategic archetypes dominate: Japanese incumbents with hospital channel lock-in, Indian and Chinese API-forward suppliers with cost-optimized generic positioning, and European formulators with regulatory compliance specialization. Competitive moves center on pharmacovigilance infrastructure investment and continuous manufacturing technology licensing.
Among Japan-based pharmaceutical manufacturers, Eisai Co., Ltd. and Mitsubishi Tanabe Pharma exemplify the integrated incumbent archetype with established hospital procurement relationships. Indian API and formulation specialists including Sun Pharmaceutical Industries Ltd. represent the cost-optimized generic vector with backward integration into key starting materials. These groupings illustrate how geographic origin and corporate structure align with divergent competitive positioning in muscle relaxant supply.
| Leading Market Players |
|---|
| Eisai Co., Ltd. |
| Taisho Pharmaceutical Co., Ltd. |
| Aarti Drugs Ltd. |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Mitsubishi Tanabe Pharma |
| Zhejiang Hisun Pharmaceutical |
| Jiangsu Hengrui Medicine Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese piperidine derivative production is compressing API spot pricing while simultaneously accelerating supplier consolidation among integrated manufacturers with captive backward integration into key starting materials. Japanese hospital procurement channels now demand real-time release testing capabilities as a non-negotiable qualification criterion, forcing price premiums for compliant suppliers against commoditized generic entrants.
Pricing Analysis
Hospital procurement managers anchor a three-tier pricing structure across premium, standard, and economy levels in eperisone formulations. Price differentiation hinges on certification grade under EMA pharmacovigilance standards and volume scale in annual tender agreements. Cost compression in standard-tier tablets is intensifying because Indian API exporters are expanding flow chemistry capacity. Long-term care facilities exhibit the highest price sensitivity, while acute rehabilitation clinics prioritize rapid-onset injectables with minimal elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic risk planning for multinational generic formulators sourcing piperidine-derived intermediates. API production concentrates in China, India, and Japan, with formulation finishing distributed across Germany and the United States. The supply chain rests on 4-piperidone hydrochloride, acetic anhydride, and oxazolidinone precursor chemicals as critical inputs. Single-source vulnerability in Japanese domestic manufacturers creates procurement bottlenecks during PMDA inspection backlogs. Distribution runs through hospital group purchasing organizations in developed markets and regional pharmacy wholesalers in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neuromuscular blocker substitution in acute surgical settings threatens eperisone's postoperative rehabilitation positioning, requiring incumbents to defend maintenance-phase indications through outcome evidence generation.
For Market Incumbents: Pre-empt formulary displacement by embedding pharmacovigilance infrastructure ahead of EMA signal detection protocol harmonization. Secure backward integration into oxazolidinone starting materials to buffer against Indian API cost compression. Capture long-term care channel expansion through elderly-adherent packaging investments that generic entrants cannot replicate without formulation expertise. For New Entrants and Emerging Players: Establish a beachhead in German pain management clinics where tightened EMA vigilance requirements create compliance moats against low-cost imports. Target the injectable-to-oral switching protocol segment with specialized discharge pathway formulations. Penetrate through real-time release testing partnerships with mid-scale European manufacturers lacking capital for in-house analytical infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous manufacturing technology adoption, favoring scaled players with existing flow chemistry assets. Five-to-ten year viability hinges on acquiring Japanese domestic manufacturers with PMDA-harmonized pharmacokinetic reference range expertise. Monitor EMA-FDA-PMDA pharmacovigilance convergence negotiations as the critical inflection signal for cross-border approval timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | Flow chemistry adoption in Jiangsu and Zhejiang industrial parks narrows cost differentials against batch API producers. |
| Pharmacovigilance Infrastructure Investment | EMA signal detection protocol compliance creates competitive moats for German pain clinic suppliers against generic entrants. |
| Backward Integration into Key Starting Materials | Captive 4-piperidone hydrochloride production secures input cost stability for Indian integrated pharmaceutical conglomerates. |
| Injectable-to-Oral Formulation Development | Hospital discharge pathway capture secures longitudinal patient relationships in Japanese geriatric rehabilitation networks. |
| Real-Time Release Testing Certification | PMDA-mandated supplier qualification criteria in Tokyo and Osaka procurement channels defend domestic manufacturer positioning. |
Research Methodology
Operator-level perspectives from regulatory affairs leads, hospital procurement managers, formulary directors, and API manufacturing plant managers anchored the qualitative base for this analysis. Primary interview findings were cross-validated against FDA abbreviated new drug application filings, EMA pharmacovigilance signal detection databases, PMDA approval documentation, and Japanese hospital procurement tender records. Bottom-up volume modeling by formulation type and top-down market sizing through trade flow analysis were triangulated to establish consistency bounds.
Scenario-bracketing around EMA-FDA-PMDA regulatory convergence timelines and continuous manufacturing adoption curves structured the analytical framework across the projection horizon. Segmentation dimensions included dosage form, clinical indication, delivery mode, end-user institution type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions indexed to API cost compression trends. Forecast inputs incorporated REACH chemical safety dossier expansion impacts and geriatric rehabilitation bed capacity expansion in Japanese prefectures.
Macroeconomic conditions sit as an overlay; deviation in yen-euro exchange rates, API import tariff schedules, or pharmaceutical reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions on regulatory timeline convergence and technology adoption S-curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Vaginal Ring Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Topical Drugs CDMO Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Cyclosporine Drugs Market