
 Prostaglandin Analogs Market | 2026-2036
Prostaglandin Analogs Market Size, Share, and Industry Trends Forecast 2026-2036
Prostaglandin Analogs Market Insights
Branded formulation consistency is unwinding price-based competition in favor of efficacy-assured prescribing. Pfizer Inc. leverages its manufacturing scale to supply active pharmaceutical ingredients across multiple analog classes. Allergan (AbbVie) anchors its position through specialized ophthalmic channels and physician education programs. Santen Pharmaceutical Co., Ltd. competes with differentiated preservative-free formulations that target tolerability-sensitive patient segments.
Prostaglandin analogs comprise synthetic derivatives of prostaglandin F2α, typically formulated as 0.005% latanoprost or 0.03% bimatoprost ophthalmic solutions with pH-adjusted buffered vehicles for corneal penetration. These compounds reduce intraocular pressure by increasing uveoscleral outflow, serving as first-line therapy for open-angle glaucoma and ocular hypertension. Among product types, latanoprost maintains the largest volume position due to extensive generic availability, while bimatoprost captures disproportionate value through its dual-mechanism pressure reduction and eyelash growth indications. Application segments show glaucoma treatment as the mature revenue base, with eye pressure reduction in ocular hypertension representing the fastest-growing addressable pool as screening expands.
FDA bioequivalence requirements for ophthalmic generics, EMA's MDR-aligned quality standards for preservative systems, and Japan's PMDA stability guidelines collectively elevate manufacturing barriers and shape product differentiation strategies. These frameworks push sponsors toward in-house analytical capabilities and documented sterility assurance. Stakeholders must monitor how evolving regulatory expectations for extractables and leachables testing will reshape formulation choices and supplier qualification timelines.
Market Dynamics
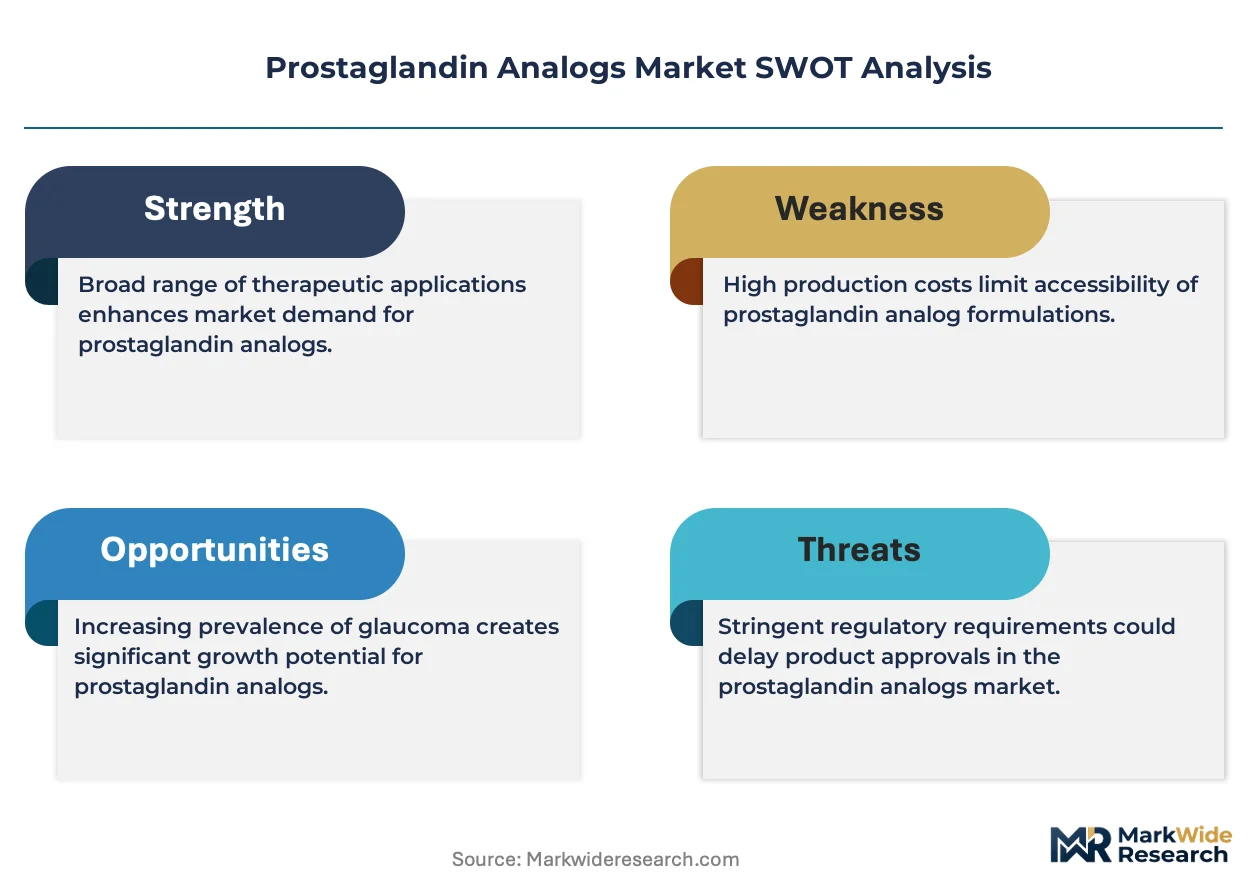
FDA bioequivalence enforcement for ophthalmic generics is compressing formulation differentiation windows and forcing sponsors toward documented sterility assurance and in-house analytical capabilities.
Growth Catalysts
- EMA MDR-aligned quality standards:Preservative system validation requirements in Europe are accelerating facility upgrades among contract manufacturers serving EU markets.
- Ocular hypertension screening expansion:Diagnostic protocol adoption in United States ophthalmology clinics is enlarging the addressable patient pool beyond diagnosed glaucoma cases.
- Preservative-free formulation demand:Tolerability-sensitive patient segments in Japan are pulling differentiated vehicle technologies from Santen Pharmaceutical and domestic competitors.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for prostaglandin F2α derivatives clusters among Indian and Chinese specialty chemical manufacturers, exposing sponsors to geopolitical logistics friction.
- Extractables and leachables testing burden:FDA container closure system requirements are extending supplier qualification timelines by 12-18 months for novel packaging configurations.
- Generic price compression:Multi-source latanoprost availability in United States pharmacy benefit manager formularies is eroding branded pricing power regardless of formulation claims.
Strategic Opportunities
- Underpenetrated ocular hypertension:Brazil's expanding private insurance coverage for preventive ophthalmology creates volume expansion potential ahead of generic saturation.
- Combination therapy convergence:Fixed-dose prostaglandin-beta blocker formulations are capturing compliance-advantaged prescribing in Germany's statutory health insurance system.
- Direct-to-clinic distribution:Specialized ophthalmology channel bypass of wholesale distributors is capturing margin in United States ambulatory surgical center networks.
Industry Challenges
- Sterility assurance validation:Aseptic manufacturing competency gaps among mid-scale CMOs are constraining sponsor outsourcing options for preservative-free presentations.
- Legacy ERP integration:Electronic batch record system deployment for FDA 21 CFR Part 11 compliance is requiring 18-24 month implementation cycles at established manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prostaglandin Analogs Market |
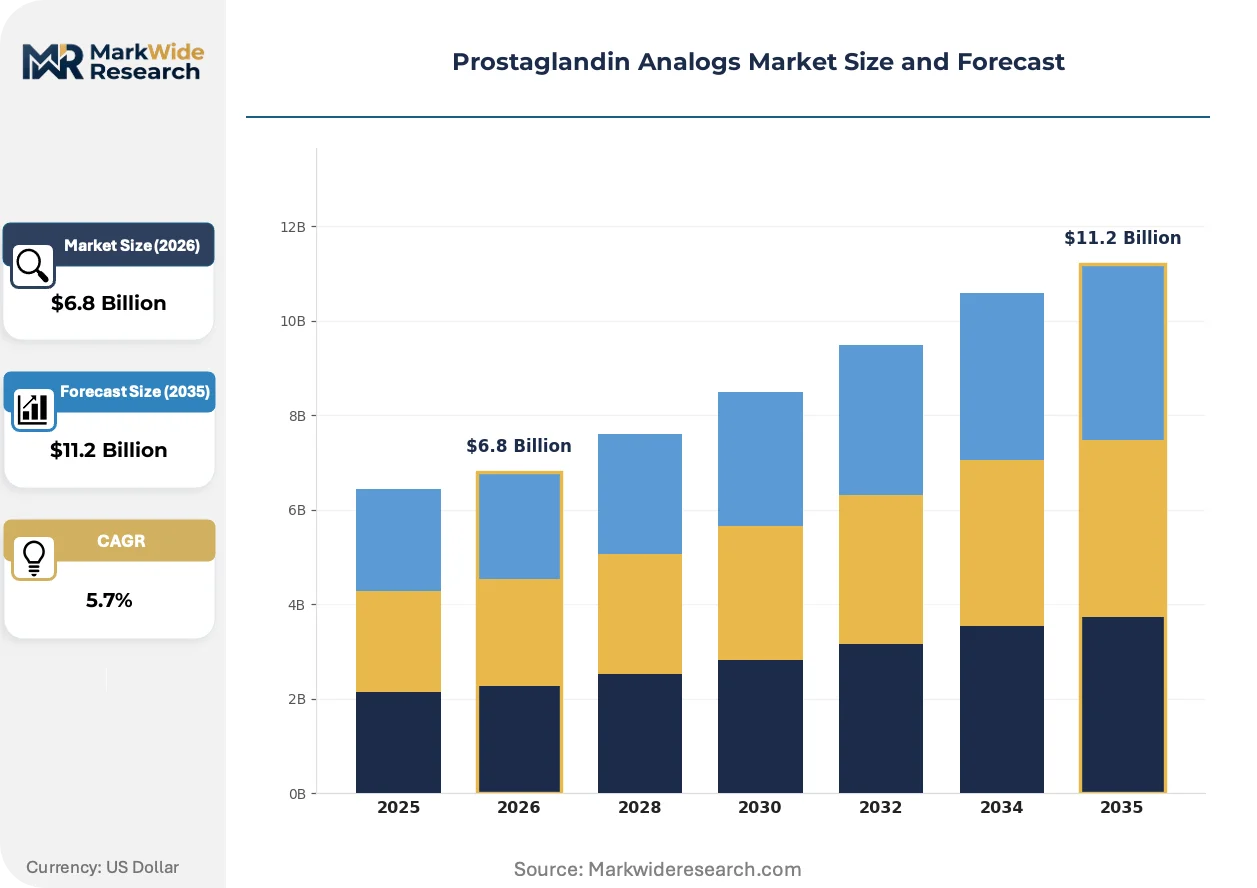
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latanoprost, Bimatoprost, Travoprost, Unoprostone Application: Glaucoma Treatment, Eye Pressure Reduction, Ocular Hypertension, Other Therapeutic Uses End User: Hospitals, Clinics, Pharmacies, Homecare Settings Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Institutional Sales |
| Companies Covered | Pfizer Inc., Allergan (AbbVie), Novartis AG, Bausch Health Companies Inc., Santen Pharmaceutical Co., Ltd., Sun Pharmaceutical Industries Ltd., Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Aerie Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prostaglandin Analogs Market Trends and Innovations
Formulation science and distribution architecture are undergoing parallel transformation as tolerability demands and channel economics reshape competitive positioning in ophthalmic therapeutics.
Preservative-free multidose delivery systems are miniaturizing container closure complexity while maintaining sterility assurance. European ophthalmology clinics in Germany and France are adopting these systems at twice the rate of conventional unit-dose alternatives. This technology is miniaturizing the trade-off between patient convenience and formulation purity that has historically forced a binary choice.
Japan's PMDA stability guidelines for ophthalmic solutions are tightening forced degradation study requirements for new molecular entity filings. Sponsors must now submit 24-month real-time data prior to approval, compressing development timelines and favoring established analytical platforms. Japanese domestic manufacturers with captive stability chambers are capturing disproportionate share of regional partnership discussions.
Physician education programming is displacing traditional pharmaceutical representative detailing in United States glaucoma management. Academic medical center ophthalmology departments in Boston and San Francisco are consolidating purchasing authority through specialty pharmacy committees. This concentration is most visible in Medicare Part B reimbursement pathways where outcome documentation requirements favor integrated delivery networks over independent practice associations.
Prostaglandin Analogs Market Segmentation
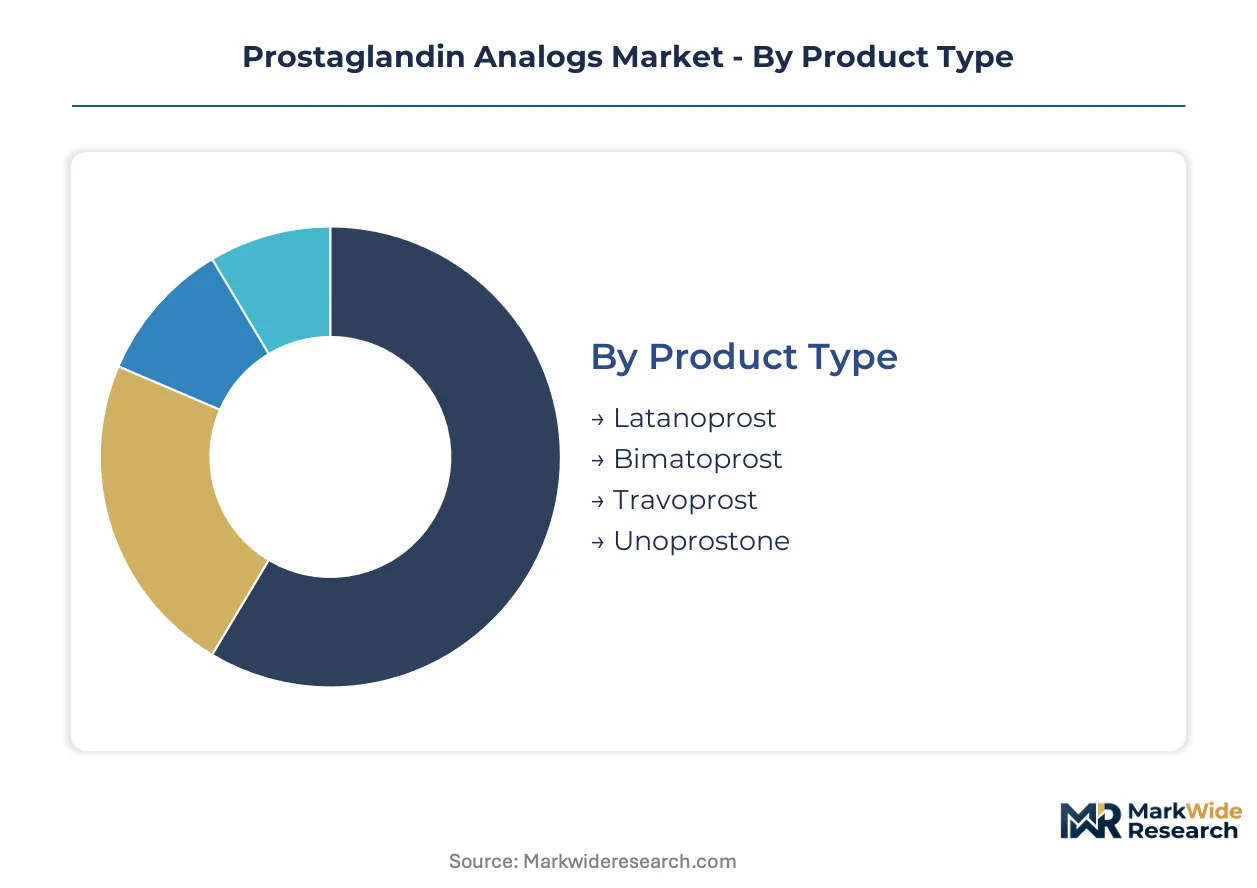
Prostaglandin analogs fragment across formulation chemistry, clinical indication, care setting, and procurement channel. Each dimension carries distinct substitution dynamics and margin profiles that reshape competitive positioning.
Product Type:
Generic substitution pressure concentrates most intensely on mature synthetic derivatives where multi-source availability has collapsed price premiums.
- Latanoprost:The 0.005% isopropyl ester formulation of prostaglandin F2α remains the most prescribed first-line therapy. United States pharmacy benefit managers have driven this segment toward commodity economics despite documented bioequivalence variability concerns.
- Bimatoprost:Amide-modified prostaglandin analog with dual outflow mechanisms and distinct cosmetic indications. Japan's preservative-free demand and eyelash growth approvals in North American markets sustain differentiated pricing power against generic encroachment.
- Travoprost:Fluorinated prostaglandin analog with buffered vehicle systems targeting tolerability-sensitive patients. European ophthalmology clinics in Germany and France favor this chemistry for preservative-free multidose presentations.
- Unoprostone:Docosanoid derivative with distinct receptor selectivity profile. Limited to niche refractory cases where first-line analogs fail, constraining volume expansion despite documented efficacy in Japanese clinical practice.
Latanoprost anchors the volume base while bimatoprost gains share at the steepest rate.
Application:
Clinical indication segmentation traces the progression from diagnosed disease management toward preventive intervention and adjacent therapeutic expansion.
- Glaucoma Treatment:Open-angle glaucoma represents the established revenue foundation. Medicare Part B reimbursement pathways in the United States favor documented outcome metrics that integrated delivery networks capture more effectively than independent practices.
- Eye Pressure Reduction:Pre-surgical and post-surgical pressure management in cataract and refractive procedures. Ambulatory surgical center networks in Florida and Texas are consolidating purchasing through direct-to-clinic distribution arrangements.
- Ocular Hypertension:Elevated intraocular pressure without optic nerve damage. Diagnostic protocol expansion in Brazilian private insurance networks and United States screening programs enlarges the addressable pool fastest.
- Other Therapeutic Uses:Adjunctive applications including steroid-induced pressure elevation and neuroprotective investigation. Academic medical centers in Boston and San Francisco drive off-label utilization through investigator-initiated protocols.
Glaucoma treatment anchors the volume base while ocular hypertension gains share at the steepest rate.
End User:
Care setting segmentation reflects divergent procurement authority, reimbursement mechanics, and patient compliance monitoring capabilities.
- Hospitals:Inpatient and emergency ophthalmology services with centralized pharmacy formulary control. Academic medical center consolidation in the United States has shifted purchasing toward specialty pharmacy committees with outcome documentation requirements.
- Clinics:Outpatient ophthalmology practices including independent associations and integrated delivery networks. Physician education programming is displacing traditional pharmaceutical representative detailing in Medicare Part B pathways.
- Pharmacies:Retail and mail-order dispensing with pharmacy benefit manager formulary constraints. United States multi-source latanoprost availability has compressed margins regardless of branded formulation claims.
- Homecare Settings:Self-administered therapy with telemedicine monitoring integration. Japan's aging demographics and established reimbursement pathways support sustained volume concentration.
Clinics anchor the volume base while homecare settings gain share at the steepest rate.
Distribution Channel:
Channel segmentation tracks the disintermediation of wholesale distributors as specialized ophthalmology networks seek margin capture and supply security.
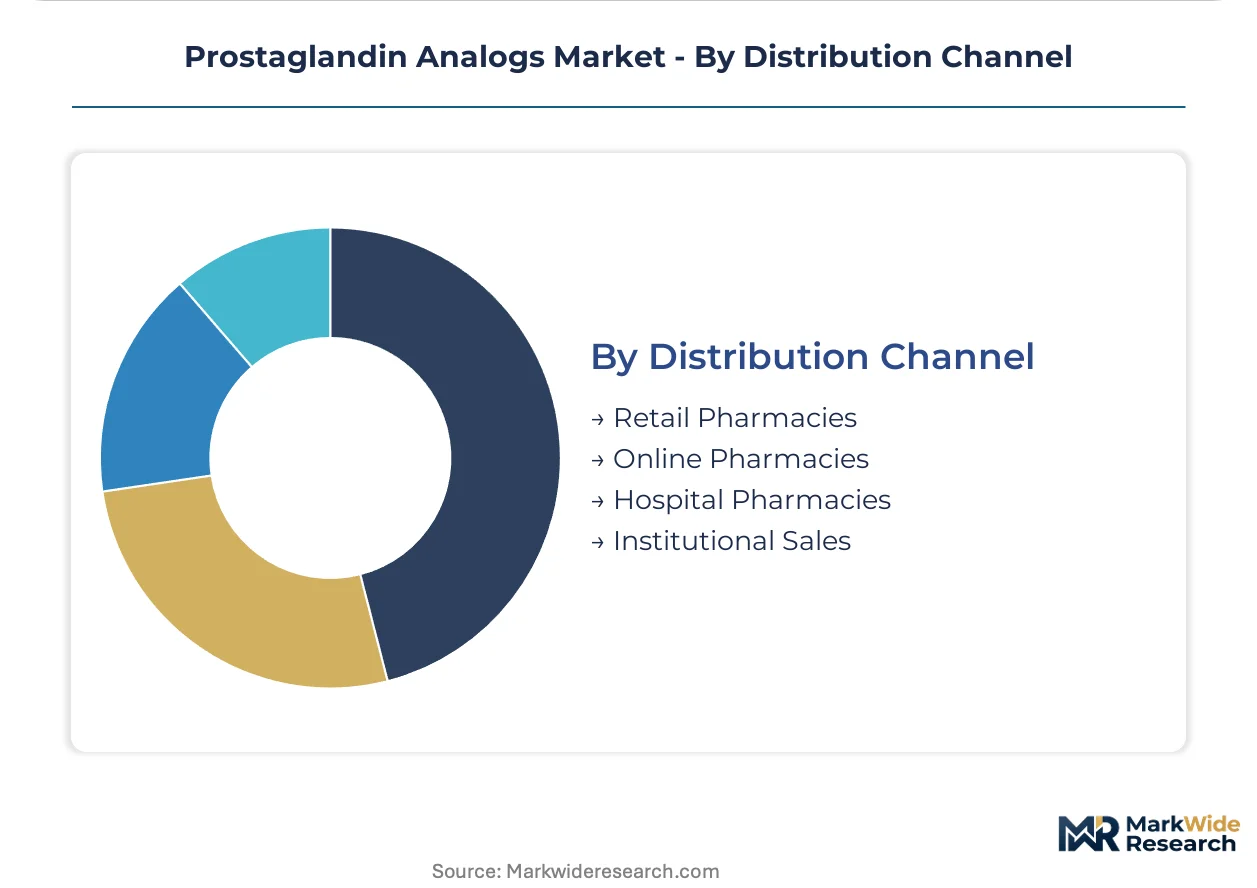
- Retail Pharmacies:Community and chain dispensing with formulary tier placement determining access. United States pharmacy benefit manager negotiations have eroded branded pricing power through generic substitution mandates.
- Online Pharmacies:Direct-to-patient dispensing with cold chain and documentation requirements. European EMA MDR-aligned quality standards for preservative systems accelerate facility upgrades among contract manufacturers serving digital channels.
- Hospital Pharmacies:Centralized inpatient and outpatient dispensing with 340B pricing implications. Academic medical center networks in Boston and San Francisco consolidate authority through specialty pharmacy committees.
- Institutional Sales:Direct manufacturer-to-provider arrangements bypassing wholesale distribution. Ambulatory surgical center networks in the United States capture margin through specialized ophthalmology channel concentration.
Retail pharmacies anchor the volume base while institutional sales gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports prostaglandin F2α active pharmaceutical ingredients to formulation sponsors in the United States, Germany, and Japan, creating a trade-flow corridor that shapes regional supply security calculations.
United States
Aging demographics and Medicare Part B reimbursement pathways sustain volume concentration for first-line glaucoma therapy. FDA bioequivalence enforcement for ophthalmic generics tightens manufacturing documentation requirements. Academic medical center networks in Boston and San Francisco consolidate purchasing through specialty pharmacy committees with outcome documentation mandates.
Germany
Statutory health insurance system demand for fixed-dose combination therapies drives prescribing volume for prostaglandin-beta blocker formulations. EMA MDR-aligned quality standards for preservative systems accelerate contract manufacturer facility upgrades. Ophthalmology clinics in Munich and Heidelberg adopt preservative-free multidose delivery systems at elevated rates.
Japan
Tolerability-sensitive patient segments pull differentiated preservative-free formulations from domestic and multinational sponsors. PMDA stability guidelines require 24-month real-time forced degradation data prior to new molecular entity approval. Domestic manufacturers with captive stability chambers capture disproportionate regional partnership share.
Brazil
Expanding private insurance coverage for preventive ophthalmology enlarges the addressable patient pool beyond diagnosed glaucoma cases. ANVISA regulatory pathways for imported finished formulations create compliance complexity for multinational sponsors. São Paulo and Rio de Janeiro ophthalmology clinic networks drive diagnostic protocol adoption.
China
Domestic API production capacity for prostaglandin derivatives expands amid import substitution policy support. NMPA quality consistency evaluation requirements for generic ophthalmic solutions elevate analytical capability investments. Yangtze River Delta chemical manufacturers cluster specialty prostaglandin intermediate production.
Prostaglandin Analogs Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and channel access dimensions, producing a tiered structure where scale-driven API suppliers, specialized ophthalmic marketers, and generic volume players occupy distinct competitive positions. Three archetypes dominate: multinational pharmaceutical conglomerates with integrated manufacturing and distribution, regional ophthalmic specialists with differentiated vehicle technologies, and contract research and manufacturing organizations serving sponsor outsourcing demand. Consolidation through targeted acquisitions and strategic partnerships for preservative-free formulation capabilities represents the dominant competitive trajectory.
Within the multinational conglomerate tier, Pfizer Inc. and Novartis AG exemplify scale-driven positions spanning API supply through finished formulation distribution. Santen Pharmaceutical Co., Ltd. occupies a specialist position reflecting Japanese domestic manufacturing capabilities and preservative-free formulation focus. Allergan, now within AbbVie's portfolio, represents the ophthalmic channel concentration archetype with legacy physician education infrastructure.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Allergan (AbbVie) |
| Novartis AG |
| Bausch Health Companies Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Aerie Pharmaceuticals, Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for prostaglandin F2α active pharmaceutical ingredients lock in supply access for United States and European formulation sponsors while constraining price visibility against spot-market volatility in Indian and Chinese specialty chemical markets. These contractual structures concentrate pricing power among API manufacturers with validated sterility assurance, forcing finished-formulation sponsors to absorb margin compression or accelerate backward integration into intermediate production.
Pricing Analysis
Prior-generation latanoprost formulations trade at commodity price points under pharmacy benefit manager generic substitution mandates, while next-generation preservative-free bimatoprost and travoprost presentations command sustained premiums through differentiated vehicle technologies. Three-tier pricing structure across preservative-free premium, buffered standard, and generic economy levels reflects FDA bioequivalence tiering and EMA MDR-aligned quality certification. Cost compression in the generic tier intensifies because multi-source latanoprost availability erodes branded pricing power regardless of formulation claims. Hospital pharmacy committees exhibit lowest price sensitivity due to 340B pricing insulation, while retail pharmacy dispensing faces highest sensitivity from formulary tier placement negotiations.
Supply Chain Analysis
India and China anchor prostaglandin F2α intermediate and API production for global formulation sponsors, with Yangtze River Delta and Hyderabad chemical clusters feeding downstream finishing operations in the United States, Germany, and Japan. The supply chain draws from isopropyl ester precursors, fluorinated intermediates, and amide-modified derivatives as critical inputs. Single-source vulnerability concentrates in Indian API manufacturers serving FDA-regulated markets, where geopolitical logistics friction and CDSCO export documentation delays create supply continuity exposure. Distribution runs through specialized ophthalmology channels bypassing wholesale distributors in United States ambulatory surgical center networks, while retail and hospital pharmacy segments maintain traditional wholesale-mediated procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prostaglandin analogs sit in early-cycle expansion as ocular hypertension screening protocols enlarge the addressable patient pool beyond diagnosed glaucoma cases across United States, Brazilian, and Japanese ophthalmology networks. This preventive intervention tailwind supports volume growth ahead of generic saturation in mature glaucoma segments.
For Market Incumbents: Compound formulation differentiation through preservative-free vehicle technologies and captive stability chamber investments to meet Japan's PMDA 24-month real-time data requirements. Defend against emerging entrant archetypes with generic latanoprost volume plays by securing direct-to-clinic distribution arrangements in United States ambulatory surgical center networks. Vertical integration into prostaglandin F2α intermediate production mitigates API supply concentration risk from Indian and Chinese specialty chemical manufacturers. For New Entrants and Emerging Players: Differentiate on tolerability-sensitive patient segments through preservative-free multidose delivery systems targeting Japan's aging demographics and European EMA MDR-aligned quality standards. Brazil's expanding private insurance coverage for preventive ophthalmology represents the most penetrable geography ahead of generic saturation. A go-to-market angle anchored in physician education programming displaces traditional pharmaceutical representative detailing in Medicare Part B reimbursement pathways. For Investors and Strategic Acquirers: Regional ophthalmic specialists with differentiated vehicle technologies and established PMDA stability chamber infrastructure offer acquisition exposure to preservative-free formulation premiumization. Long-term viability over a 5-10 year window rests on sponsor ability to navigate FDA bioequivalence enforcement and EMA extractables and leachables testing burdens. The signal to watch is ANVISA regulatory pathway simplification for imported finished formulations in Brazilian private insurance networks, which would accelerate market entry for multinational sponsors.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation Development | Captures tolerability-sensitive segments in Japan and Germany through PMDA and EMA compliance. |
| Backward Integration into API Production | Reduces exposure to Indian and Chinese specialty chemical supply concentration and logistics friction. |
| Direct-to-Clinic Distribution Buildout | Bypasses wholesale distributors to capture margin in United States ambulatory surgical center networks. |
| Physician Education Programming Investment | Displaces traditional detailing in Medicare Part B pathways with outcome documentation capabilities. |
| Stability Chamber Infrastructure Expansion | Accelerates Japan partnership discussions through captive 24-month real-time forced degradation capacity. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs leads, formulary directors at United States pharmacy benefit managers, and ophthalmology clinic procurement managers anchors the qualitative findings against secondary validation from FDA 505(b)(2) filings, EMA MDR technical documentation, and Japanese PMDA new molecular entity approval records. Bottom-up and top-down triangulation reconciles patient volume estimates from Medicare Part B claims data with API trade flow analysis from Indian and Chinese customs records.
Sensitivity analysis across formulation chemistry, clinical indication severity, care setting procurement authority, and regional regulatory cluster variations shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product type chemistry, application indication line, end-user setting, and distribution channel structure. CAGRs derive from iterative reconciliation of historical volume trends with sponsor pipeline disclosures and diagnostic protocol adoption curves in key ophthalmology networks.
Material uncertainties — FDA bioequivalence enforcement intensity, EMA extractables and leachables testing timeline extensions, and geopolitical logistics friction in API trade corridors — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and reimbursement continuity that could revise substantially with shifts in Medicare Part B policy or ANVISA import simplification. Recalibration cycles align with material shifts in ocular hypertension screening protocol adoption and preservative-free formulation technology validation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Xanthine Oxidase Inhibitors Market
Pharmaceuticals
Calcimimetic Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Global Bone Morphogenetic Protein Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Triamcinolone Ointment Chlorofluorocarbons Market
Pharmaceuticals
Carbetocin Injection Market