
 Global Commercial Vehicles Lubricants Market | 2026-2036
Global Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Vehicles Lubricants Market Foresight
API CK-4 and FA-4 specification-grade engine oils is bifurcating the competitive landscape into premium synthetic suppliers and conventional blenders. Exxon Mobil Corporation leverages its backward integration into Group II and Group III base oil production to sustain margin control across North American fleet channels. FUCHS specializes in high-performance hydraulic fluids for construction and mining equipment, occupying a defensible technical niche against commodity competitors. TotalEnergies extends its European service center network to anchor aftermarket loyalty among logistics companies operating cross-border routes.
Commercial vehicles lubricants are formulated blends of base oils and additive packages engineered to reduce friction, dissipate heat, and prevent wear in powertrain and auxiliary systems operating under severe duty cycles, with viscosity grades typically ranging from SAE 5W-30 for light trucks to SAE 15W-40 for heavy-duty diesel engines. Engine oil commands the largest revenue pool given drain interval extension requirements and OEM fill specifications, yet synthetic transmission fluid for automated manual gearboxes represents the fastest-growing product category as fleet operators adopt fuel-efficiency technologies. Heavy duty trucks generate disproportionate volume demand per unit, while refrigerated trucks create specialized lubricant needs due to stop-start engine cycles and auxiliary compressor loads.
The EPA regulates heavy-duty engine emissions and lubricant performance through its SmartWay and GHG Phase 3 programs, while REACH in Europe restricts certain additive chemistries and mandates extended drain biodegradability disclosures. India's BIS enforces IS 13656 standards for automotive engine oils, creating compliance barriers for imported formulations. Fleet procurement managers must monitor how OEM warranty terms tie to specific oil specifications as electrified powertrains and alternative fuels complicate traditional lubricant selection frameworks.
Market Dynamics
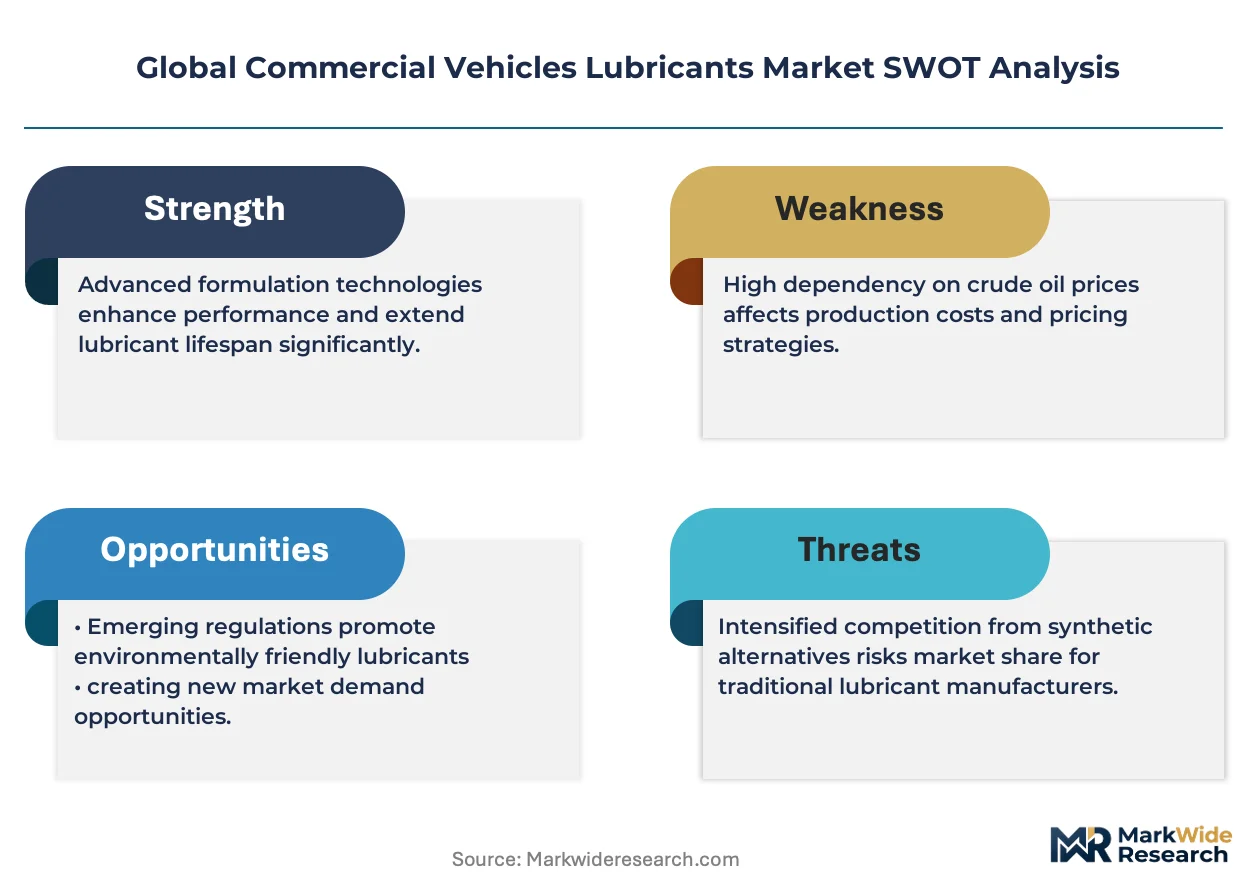
The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles are compressing drain intervals and mandating higher-performance lubricant formulations across North American fleet operations. This regulatory pressure is forcing reformulation investments while simultaneously opening premium synthetic segments.
Growth Catalysts
- Last-mile delivery network expansion:Logistics companies scaling urban freight operations are extending scheduled maintenance programs, creating recurring demand for high-frequency oil change services in dense metropolitan zones.
- API FA-4 specification adoption:The newer fuel-efficient oil standard is penetrating heavy-duty fleets as OEMs certify engines for lower viscosity grades, unlocking synthetic penetration in long-haul trucking.
- India highway freight tonnage growth:Commercial vehicle sales and cargo movement on national highways continue climbing, concentrating volume demand in one of the world's largest road transport markets.
Market Restraints
- Group II/III base oil supply concentration:Refinery capacity for high-quality base stocks clusters in specific coastal manufacturing hubs, exposing blenders to feedstock availability shocks and transport cost volatility.
- REACH additive chemistry restrictions:ECHA regulations on zinc dialkyldithiophosphate and other extreme-pressure compounds are forcing costly reformulation of gear oils and hydraulic fluids for European market access.
- Electrified powertrain substitution:Battery-electric and hydrogen fuel cell commercial vehicles eliminate engine oil demand entirely, threatening the core revenue pool in urban delivery and municipal bus segments.
Strategic Opportunities
- Refrigerated truck auxiliary systems:Stop-start engine cycles and compressor loads in cold-chain logistics create specialized lubricant needs for compressor oils and auxiliary power units that commodity suppliers underserve.
- Automated manual transmission fluid demand:AMT adoption for fuel efficiency is generating synthetic transmission fluid requirements that command price premiums over conventional driveline products.
- Biodegradable hydraulic fluids for construction:EU Green Deal procurement guidelines and site-level environmental compliance are creating preference shifts toward bio-based formulations in European infrastructure projects.
Industry Challenges
- OEM warranty specification complexity:Powertrain electrification and alternative fuel compatibility are multiplying the number of distinct oil specifications fleet managers must track, increasing technical support costs and inventory SKU proliferation.
- Additive package certification timelines:New chemistries require extended field testing for API and ACEA approvals, compressing product development windows as regulatory deadlines approach.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Vehicles Lubricants Market |
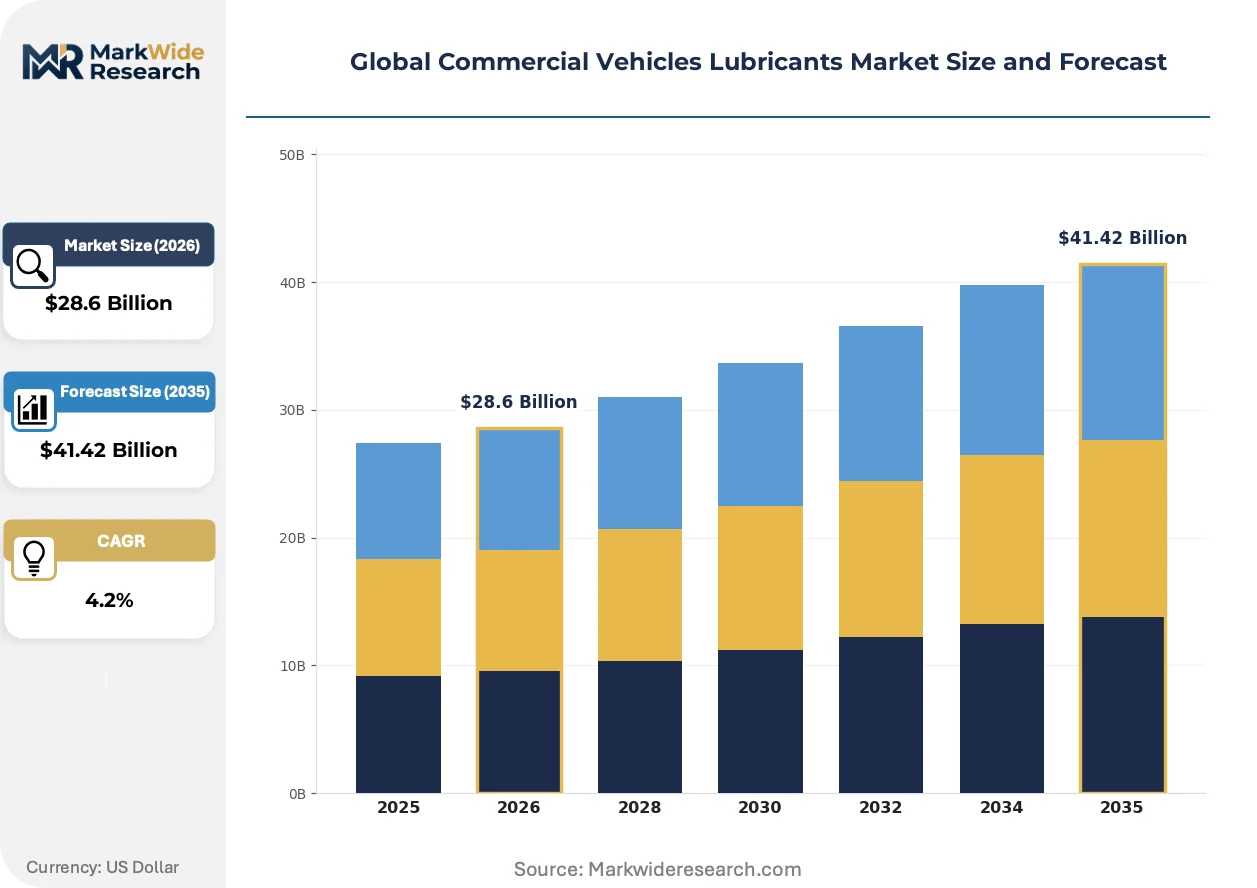
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $41.42 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Fluid, Grease, Transmission Fluid, Brake Fluid Vehicle Category: Heavy Duty Trucks, Light Commercial Trucks, Buses, Pickups, Delivery Vans, Refrigerated Trucks End User: Fleet Operators, Logistics Companies, Public Transport Services, Construction Enterprises, Mining Firms, Agricultural Contractors Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Aftermarket Dealers, Service Centers, Wholesale Distributors |
| Companies Covered | Royal Dutch Shell plc, Exxon Mobil Corporation, BP plc, Chevron Corporation, TotalEnergies, China Petroleum & Chemical Corporation, Indian Oil Corporation Limited, FUCHS, Valvoline Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Vehicles Lubricants Market Shifts & Advancements
Synthetic formulation technologies are fragmenting competitive advantage away from scale-based blending toward specialized additive chemistry capabilities. Three developments are compressing traditional supply relationships.
Low-viscosity engine oils are penetrating heavy-duty segments previously dominated by SAE 15W-40 grades. Fleet operators running automated manual transmissions and aerodynamic tractor packages are adopting SAE 5W-30 and 10W-30 synthetic blends to capture fuel economy gains. This viscosity grade compression is miniaturizing the addressable market for conventional mineral oil blenders while expanding margin pools for Group III and PAO-based suppliers.
REACH in Europe is mandating extended drain biodegradability disclosures and restricting specific friction modifier chemistries. The regulation is forcing reformulation of hydraulic fluids used in construction and agriculture, with compliance costs falling disproportionately on mid-sized blenders lacking in-house toxicology testing. Construction equipment OEMs serving German and French markets are now pre-qualifying suppliers based on ECHA registration completeness.
Fleet procurement departments are consolidating lubricant purchasing through integrated service contracts rather than spot-buying from jobbers. Large logistics operators running cross-border routes are selecting single suppliers capable of delivering consistent specification grades across multiple countries, displacing fragmented local distributor relationships. This buying-pattern concentration is most visible in Germany and Poland, where major freight corridors anchor centralized procurement decisions.
Global Commercial Vehicles Lubricants Market Segmentation
Commercial vehicles lubricants fragment across four dimensions that determine pricing power and channel economics. Product specifications dictate formulation complexity, while vehicle duty cycles shape volume concentration and drain interval economics. Fleet procurement patterns and distribution infrastructure complete the commercial architecture.
Product Type:
Margin pools concentrate in synthetic formulations where additive chemistry and base oil quality create differentiation barriers against commodity blenders.
- Engine Oil:Formulated from Group II, III, or PAO base stocks with detergent-dispersant and anti-wear additive packages, typically SAE 5W-30 to 15W-40 viscosity grades. Demand concentrates in long-haul trucking fleets across the United States and Germany as EPA Phase 3 and EU GHG standards compress drain intervals and mandate higher-performance specifications.
- Transmission Fluid:Synthetic blends engineered for automated manual gearboxes and dual-clutch systems, requiring precise friction modification. Logistics operators in Poland and the Czech Republic are expanding AMT-equipped fleet purchases, generating synthetic fluid requirements that command price premiums over conventional driveline products.
- Gear Oil:Extreme-pressure lubricants for axle and differential systems, formulated with sulfur-phosphorus additive chemistry.
- Hydraulic Fluid:Anti-wear and biodegradable formulations for construction and mining equipment power systems.
- Grease:Thickened lubricants for chassis points, bearings, and fifth-wheel applications.
- Brake Fluid:Glycol-ether or silicone-based hydraulic fluids meeting DOT specifications for commercial braking systems.
The dominant share belongs to Engine Oil, while Transmission Fluid is closing the gap fastest.
Vehicle Category:
Volume demand scales with vehicle mass and operating severity, creating tiered consumption patterns across duty cycles.
- Heavy Duty Trucks:Class 8 tractors and rigid trucks operating long-haul and regional distribution routes, consuming 40-60 liters per oil change. Fleets traversing India's Golden Quadrilateral highway network generate concentrated demand as freight tonnage climbs on national corridors connecting Delhi, Mumbai, Chennai, and Kolkata.
- Refrigerated Trucks:Cold-chain vehicles with stop-start engine cycles and auxiliary compressor loads requiring specialized compressor oils and APUs. European logistics operators running cross-border routes between Spain, France, and Germany face undersupply of commodity lubricant suppliers for these auxiliary systems.
- Light Commercial Trucks:Class 3-6 vehicles for urban freight and regional distribution.
- Buses:Transit and coach vehicles with high-idle operating profiles and extended drain intervals.
- Pickups:Light-duty commercial utilities with mixed personal and work use patterns.
- Delivery Vans:Last-mile urban freight vehicles facing electrification pressure in municipal zones.
Heavy Duty Trucks anchor volume demand, though Refrigerated Trucks are expanding most quickly as cold-chain infrastructure scales.
End User:
Procurement sophistication varies sharply between integrated fleet operations and fragmented contractor segments.
- Fleet Operators:Large-scale vehicle owners with centralized maintenance programs and specification control. North American for-hire carriers with 500-plus unit fleets are consolidating lubricant purchasing through integrated service contracts, displacing spot-buying from jobbers.
- Logistics Companies:Asset-light and asset-heavy freight operators managing multi-country route networks. German and Polish corridor operators now select single suppliers capable of delivering consistent specification grades across border crossings.
- Public Transport Services:Municipal and regional bus authorities with extended tender cycles.
- Construction Enterprises:Project-based equipment operators with seasonal demand patterns.
- Mining Firms:Open-pit and underground operators with severe-duty lubricant requirements.
- Agricultural Contractors:Seasonal machinery operators with dispersed geographic footprints.
Fleet Operators command the largest procurement volumes, while Logistics Companies are gaining share fastest through cross-border consolidation.
Distribution Channel:
Channel economics shift with service bundling requirements and fleet scale thresholds.
- Service Centers:Integrated maintenance facilities combining oil changes with inspection and repair services. Urban logistics hubs in Mumbai and Bangalore are expanding scheduled maintenance programs as last-mile delivery networks densify, creating recurring demand for high-frequency oil change services.
- Direct Sales:Manufacturer-to-fleet contracts bypassing distributor margins for large accounts. TotalEnergies extends its European service center network to anchor aftermarket loyalty among logistics companies operating cross-border routes.
- Aftermarket Dealers:Independent distributors serving fragmented customer bases.
- Wholesale Distributors:Regional bulk suppliers to jobbers and smaller service outlets.
- Retail Outlets:Consumer-accessible points for owner-operator and small fleet purchases.
- Online Platforms:E-commerce channels for standardized product procurement.
Service Centers capture the dominant transaction volume, while Direct Sales is climbing the fastest as fleet procurement departments consolidate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Fleet operators in developed markets absorb premium synthetic pricing for fuel efficiency gains, while emerging market buyers remain highly sensitive to per-liter costs despite volume growth.
United States
Long-haul trucking fleets dominate lubricant consumption as EPA Phase 3 standards compress drain intervals. The EPA mandates higher-performance formulations through SmartWay certification requirements. Dallas-Fort Worth anchors concentrated demand where major for-hire carriers operate maintenance hubs along Interstate 35.
Germany
Cross-border logistics operators generate synthetic transmission fluid demand through automated manual gearbox adoption. REACH restricts zinc dialkyldithiophosphate in gear oil formulations, forcing additive reformulation. The Rhine-Ruhr corridor concentrates fleet service centers where procurement departments consolidate supplier relationships.
India
Commercial vehicle sales on national highways drive volume expansion as freight tonnage climbs the Golden Quadrilateral network. BIS enforces IS 13656 standards for automotive engine oils, creating compliance barriers for imported formulations. Mumbai and Bangalore service centers expand scheduled maintenance programs for last-mile delivery networks.
China
Heavy-duty truck production sustains base oil demand despite electrification headwinds in urban delivery. The MIIT implements fuel consumption limits for commercial vehicles that indirectly shape lubricant performance requirements. Shandong Province clusters refinery capacity for Group II and Group III base stock production.
Poland
Central European logistics operators select single suppliers for cross-border route consistency. EU Green Deal procurement guidelines favor biodegradable hydraulic fluids in infrastructure projects. The Silesian industrial zone concentrates construction equipment fleets driving specialized fluid demand.
Global Commercial Vehicles Lubricants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the commercial vehicles lubricants market. Integrated oil majors leverage backward integration into base oil production to control margins, while specialized blenders compete on formulation expertise. Three archetypes dominate: vertically integrated petrochemical conglomerates, regional base oil producers with blending assets, and additive-focused specialty chemical suppliers. Competitive moves concentrate on portfolio diversification toward synthetic grades and geographic expansion through service center networks.
Within the integrated oil major tier, Exxon Mobil Corporation and Royal Dutch Shell plc represent scale-driven positions anchored by captive base oil supply chains. TotalEnergies occupies a European service network position, while FUCHS exemplifies the specialty blender archetype with technical formulation focus. These named entities illustrate how competitive positioning fragments between margin-controlled upstream integration and niche technical differentiation.
| Leading Market Players |
|---|
| Royal Dutch Shell plc |
| Exxon Mobil Corporation |
| BP plc |
| Chevron Corporation |
| TotalEnergies |
| China Petroleum & Chemical Corporation |
| Indian Oil Corporation Limited |
| FUCHS |
| Valvoline Inc. |
| Others |
Supply & Pricing Matrix
API CK-4 and FA-4 certification tiers gate both supply qualification and price differentiation simultaneously, as blenders lacking additive chemistry capabilities cannot access premium fleet contracts regardless of base oil sourcing economics. Fleet procurement managers tie multi-year service agreements to specification compliance, compressing margin pools for commodity suppliers while synthetic formulators capture extended drain interval premiums.
Pricing Analysis
After-sales service bundling drives lifetime value as logistics operators consolidate lubricant purchasing through integrated maintenance contracts rather than per-liter spot transactions. Three-tier pricing structure across premium synthetic, mid-grade Group III, and economy mineral oil levels separates API FA-4 certified formulations from conventional CK-4 blends and unlicensed imports. Cost compression in the economy tier is intensifying because Indian fleet operators prioritize per-liter costs over drain interval economics. Owner-operators running single trucks exhibit highest price sensitivity, while cross-border logistics companies absorb synthetic premiums for fuel efficiency gains and warranty compliance.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes elevates inbound logistics costs for additive packages sourced from specialty chemical manufacturers in Germany and the Netherlands. Base oil production concentrates in the United States, China, and South Korea, with Group II and III refinery capacity clustering in coastal manufacturing hubs. Formulation draws from polyalphaolefin synthetic base stocks, detergent-dispersant additive packages, and viscosity index improvers. Single-source vulnerability persists for zinc dialkyldithiophosphate extreme-pressure compounds facing REACH restriction. Distribution runs through integrated service centers for fleet accounts, with wholesale distributors serving fragmented jobber networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, as OEM warranty specifications and EPA Phase 3 compliance requirements create switching costs that lock fleet customers into approved supplier relationships.
For Market Incumbents: Compound backward integration into Group III base oil production to defend margin structure against feedstock volatility threatening commodity blenders. Deepen service center network density along India's Golden Quadrilateral corridor to preempt emerging local formulators. Prioritize additive chemistry R&D investment for biodegradable hydraulic fluids as EU Green Deal procurement guidelines harden environmental compliance requirements. For New Entrants and Emerging Players: API FA-4 fast-track certification offers the most penetrable entry point for synthetic formulators targeting North American long-haul fleets seeking fuel economy gains. Target refrigerated truck auxiliary systems in European cold-chain logistics, where commodity suppliers underserve compressor oil and APU lubricant needs. Pursue direct sales contracts with mid-sized Polish logistics operators running cross-border routes, as these buyers consolidate supplier relationships but lack scale for incumbent volume discounts. For Investors and Strategic Acquirers: EPA Phase 3 implementation reshapes the acquisition landscape toward additive-focused specialty chemical suppliers with in-house toxicology testing capabilities. Mid-cap blenders with ECHA registration completeness and OEM pre-qualification status represent prime targets. Long-term viability centers on electrification exposure management—prioritize assets with transmission fluid and hydraulic fluid diversification away from engine oil concentration. Watch battery-electric commercial vehicle penetration rates in urban delivery segments as the critical inflection signal for core revenue pool erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Production | Captive supply chains insulate margin control from refinery capacity shocks in Shandong and Gulf Coast hubs. |
| Biodegradable Hydraulic Fluid Certification | ECHA registration completeness unlocks German and French infrastructure procurement under EU Green Deal guidelines. |
| Automated Manual Transmission Fluid Formulation | Synthetic friction modification capabilities capture premium pricing from Polish and Czech logistics fleet upgrades. |
| Direct Sales Contract Consolidation | Single-supplier agreements with cross-border operators displace fragmented distributor relationships in European corridors. |
| Refrigerated Truck Auxiliary System Specialization | Compressor oil and APU lubricant expertise addresses undersupply in European cold-chain logistics networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, EPA SmartWay certification databases, and SEC filings from integrated oil majors. Fleet procurement managers, aftermarket service center operators, additive chemistry R&D directors, and BIS compliance officers provided qualitative input on specification evolution and buying pattern shifts. Bottom-up triangulation across individual product segments and top-down validation against national highway freight tonnage statistics ensured consistency.
Segmentation dimensions modeled include lubricant product type, vehicle duty cycle severity, fleet procurement sophistication, and distribution channel structure across the projection horizon. CAGRs derive from regression analysis of historical commercial vehicle sales, drain interval compression rates under tightening emissions standards, and synthetic penetration curves in automated manual transmission adoption. Forecast inputs incorporate base oil capacity expansion announcements and REACH additive chemistry restriction timelines.
Decision-makers should treat outputs as directional under assumptions of sustained highway freight growth and phased electrification penetration; material deviation in battery-electric commercial vehicle adoption rates would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Automotive Engine Oils Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Industrial Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Africa Lubricants Market
Lubricants
Slideway Oil Market
Lubricants
Global Lubrication Systems Market
Lubricants
Construction Lubricants Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
Philippines Lubricants Market
Lubricants
Singapore Commercial Vehicles Lubricants Market
Lubricants
Forestry Lubricants Market
Lubricants
Norway Lubricants Market
Lubricants
Global Independent Lubricant Manufacturers Market