
 Spain Automotive Lubricants Market | 2026-2036
Spain Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Automotive Lubricants Market Analytics
The capital-intensity divergence between integrated refiners and independent blenders is rotating competitive advantage toward companies with captive base-oil supply. Repsol S.A. leverages its Tarragona refining complex to secure feedstock continuity for automotive lubricant output. Cepsa anchors its position through Andalusian production assets that reduce import dependency. Shell plc differentiates via specialized synthetic formulations targeting high-performance engines.
Automotive lubricants comprise formulated oils and functional fluids engineered from base stocks combined with additive packages containing detergents, dispersants, anti-wear agents, and viscosity modifiers, typically blended to SAE viscosity grades and API service categories to reduce friction, dissipate heat, and prevent component degradation in powertrain systems. Engine oils occupy the dominant value share across the product type dimension, while synthetic and semi-synthetic grades within the performance level dimension capture expanding margin pools as OEM fill specifications tighten. Service stations and auto parts stores within the distribution channel dimension retain the largest transaction volume, though online retail is gaining traction among fleet buyers seeking bulk procurement efficiency.
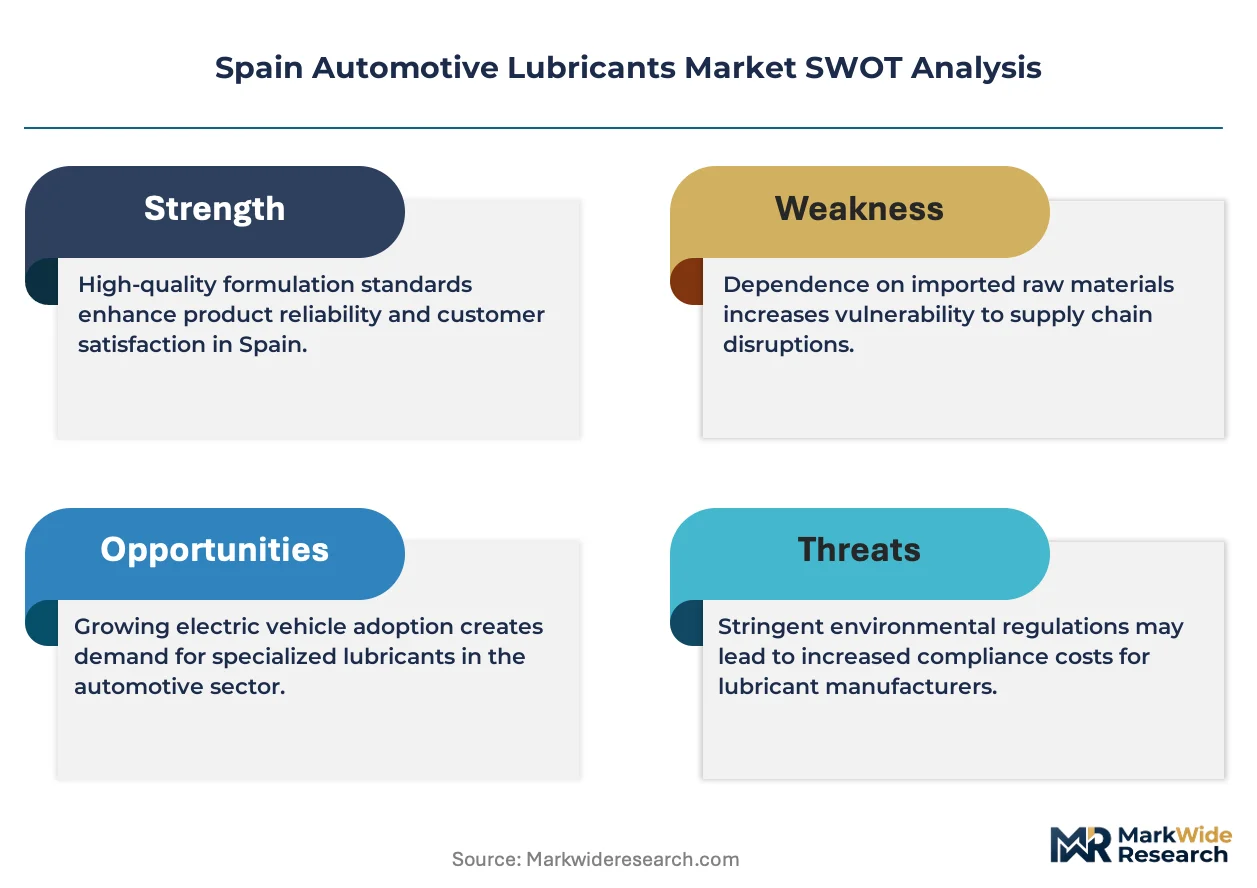
Spain's lubricant sector operates under REACH compliance obligations administered by ECHA, national waste oil management protocols enforced by regional environmental authorities, and EU Green Deal decarbonization targets that push reformulation toward lower-viscosity and bio-based alternatives. These frameworks elevate product registration costs for importers while creating compliance barriers that favor domestic blenders with established regulatory relationships. Stakeholders must monitor evolving OEM specifications and circular-economy mandates to align portfolio development with enforceable performance standards.
Market Dynamics
Synthetic lubricant formulations are compressing the addressable market for mineral-based products as Spain's Royal Decree on waste oils tightens disposal compliance costs for fleet operators.
Growth Catalysts
- EU Green Deal decarbonization targets:OEM fill specifications are tightening toward lower-viscosity grades, pulling demand toward synthetic and semi-synthetic lubricants that reduce friction losses.
- Commercial logistics fleet consolidation:Large operators around Barcelona and Madrid corridors are standardizing procurement on high-drain-interval synthetics to minimize vehicle downtime.
- REACH compliance obligations:Registration cost barriers favor domestic blenders with established ECHA relationships, concentrating margin capture among integrated refiners.
Market Restraints
- Base oil supply concentration:Spain's dependence on Group II/III imports from Mediterranean refiners exposes blenders to freight volatility and currency fluctuation.
- Reformulation cost escalation:Bio-based additive packages require R&D outlays that compress returns for mid-scale independents lacking captive chemistry capabilities.
- Extended drain intervals:Synthetic durability improvements are reducing per-vehicle lubricant consumption volumes across heavy-duty segments.
Strategic Opportunities
- Andalusian industrial corridor:Underpenetrated fleet density around Seville and Málaga offers volume expansion for distributors with service infrastructure.
- Online bulk procurement platforms:Fleet buyers are migrating from traditional auto parts stores to digital channels that consolidate multi-location ordering.
- Circular-economy mandates:Regional environmental authorities are incentivizing re-refined base oil uptake, creating positioning space for recyclers with collection networks.
Industry Challenges
- Additive chemistry specialization:Formulation expertise in viscosity modifier-synthetic base oil compatibility is scarce among regional technical staff.
- OEM certification timelines:API SP and ILSAC GF-6 approval cycles extend 18-24 months, delaying product launches for challengers.
- Legacy mineral oil inventory:Distributors face write-down pressure as service stations accelerate grade mix shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Automotive Lubricants Market |
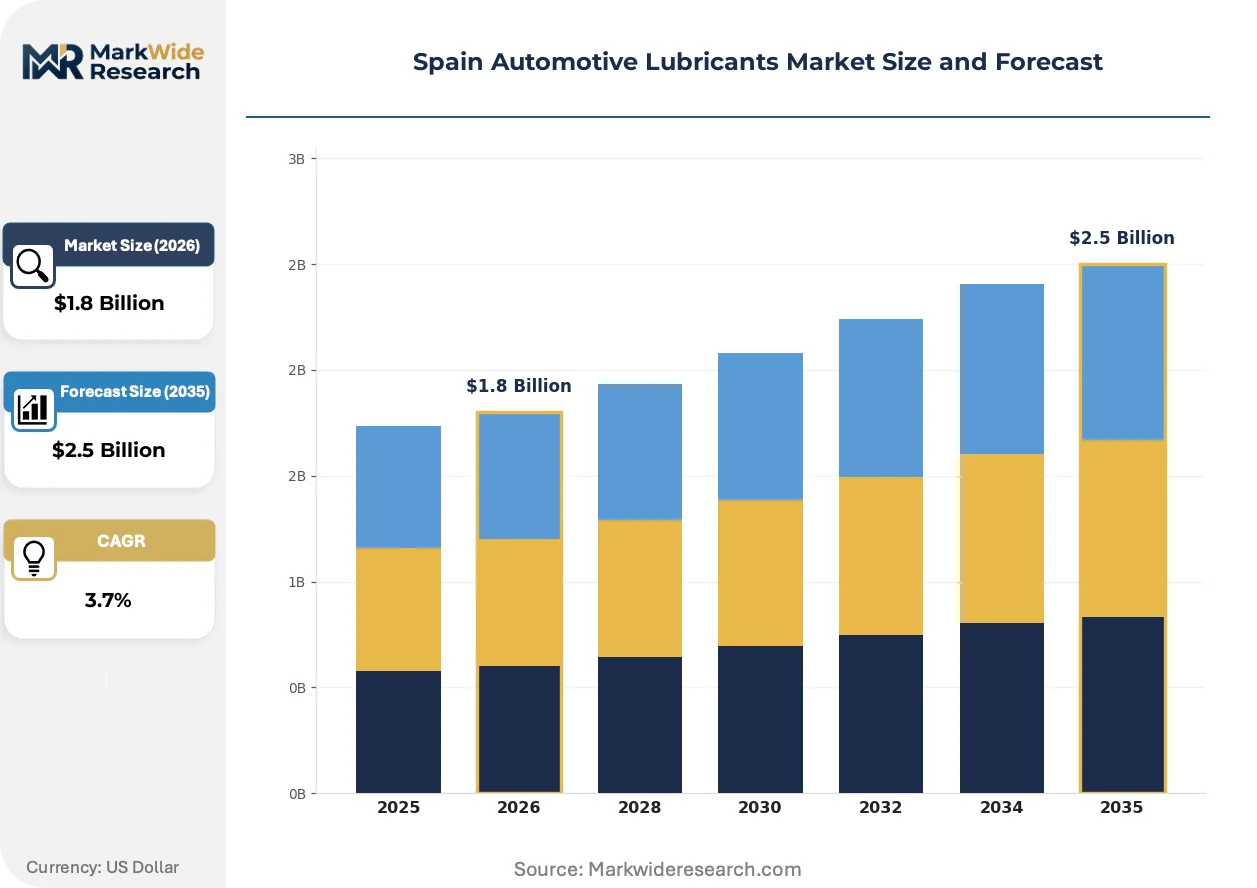
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Transmission Fluids, Greases, Hydraulic Fluids End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles Distribution Channel: Online Retail, Auto Parts Stores, Supermarkets, Service Stations Performance Level: Standard, High Mileage, Synthetic, Semi-Synthetic |
| Companies Covered | Repsol S.A., Cepsa, TotalEnergies SE, Shell plc, BP PLC (Castrol), ExxonMobil Corporation, Fuchs Petrolub SE, Chevron Corporation, Valvoline Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Automotive Lubricants Market Evolving Landscape
Reformulation priorities are pivoting toward friction reduction and thermal stability as powertrain electrification and downsized turbocharged engines impose new operating conditions on lubricant systems.
Polyalphaolefin (PAO) synthetic base stocks are supplanting Group I mineral oils in high-performance engine applications. Fleet operators in the Madrid logistics corridor are adopting PAO-based 0W-20 and 5W-30 grades for their turbocharged diesel fleets. This substitution is compressing the premium-mineral segment and elevating margin concentration among blenders with Group III/IV supply security.
Spain's national waste oil management protocols are mandating cradle-to-grave tracking for lubricant disposal. The Royal Decree enforcement is raising compliance costs for independent workshops and accelerating consolidation toward authorized collection networks. Service stations in Catalonia and the Basque Country are responding by integrating certified re-refining partnerships into their value propositions.
Fleet procurement patterns are fragmenting across centralized bulk purchasing and decentralized emergency top-up needs. Large logistics operators are disintermediating traditional distributors through direct manufacturer contracts for scheduled maintenance, while smaller operators retain auto parts store relationships for unplanned consumption. This bifurcation is most pronounced in the industrial corridors surrounding Valencia and Zaragoza.
Spain Automotive Lubricants Market Segmentation
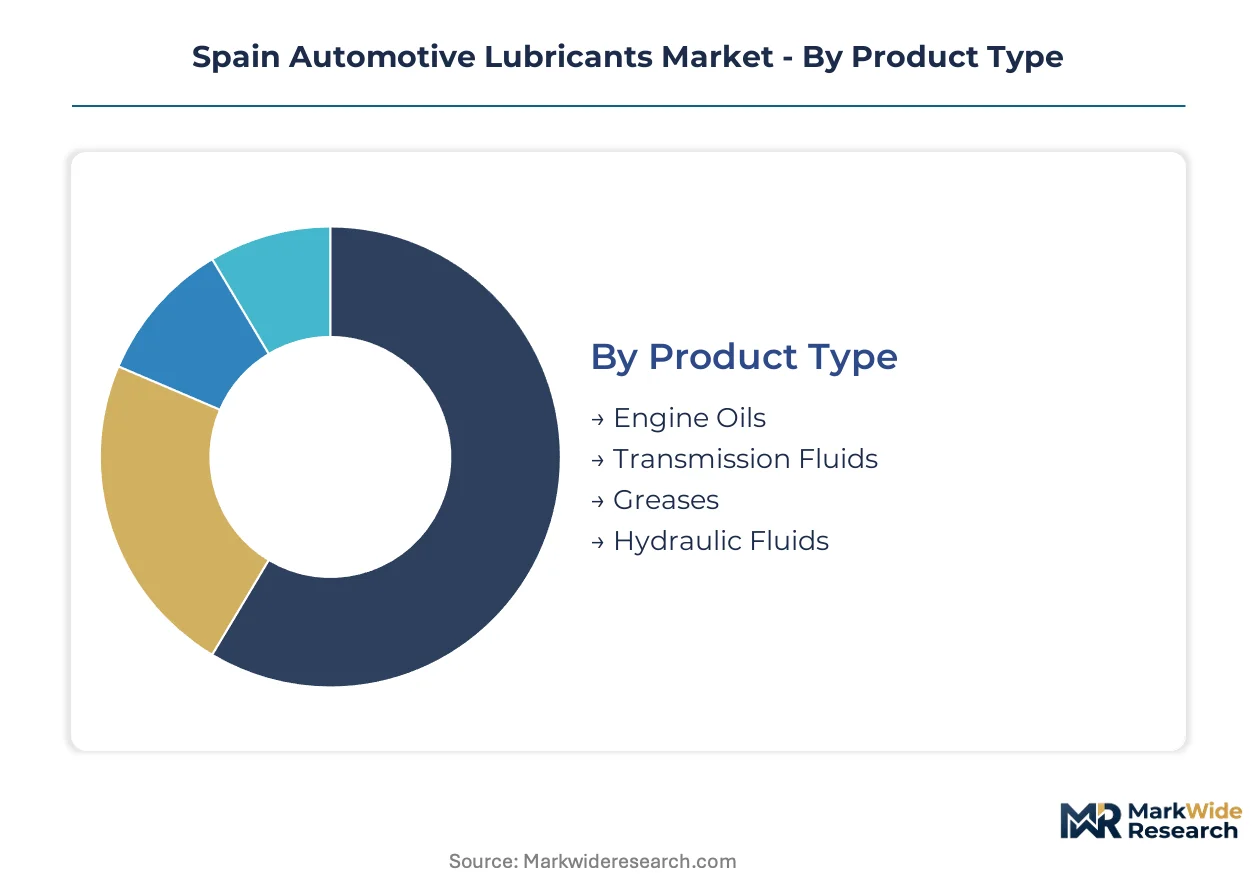
Segmentation in Spain's automotive lubricants market reveals how margin pools concentrate around performance tiers and fleet procurement patterns. Understanding these divisions exposes where integrated refiners capture value versus where independents compete on service flexibility.
Product Type:
Engine oils command the deepest margin pools across this category, while transmission fluids and functional fluids serve specialized applications with differentiated pricing power.
- Engine Oils:Formulated from base stocks with detergent-dispersant additive packages meeting SAE viscosity grades and API service categories. Demand concentrates in the Barcelona-Madrid logistics corridors where fleet operators specify extended-drain synthetic grades to minimize vehicle downtime under Spain's tightening waste oil disposal rules.
- Transmission Fluids:Specialized formulations for automatic and manual gearboxes requiring precise friction modification and thermal stability. Procurement is rotating toward synthetic ATF grades in commercial vehicle fleets around Valencia as OEM fill specifications tighten.
- Greases:Thickened lubricants for chassis and bearing applications with NLGI consistency grades.
- Hydraulic Fluids:Anti-wear formulations for power steering and suspension systems.
Engine oils hold installed capacity. Transmission fluids are rotating up the share rankings.
End User:
Volume distribution across vehicle categories reflects Spain's fleet composition and service infrastructure density.
- Passenger Vehicles:Light-duty gasoline and diesel engines requiring 5W-30 and 0W-20 grades. The Madrid metropolitan area generates concentrated demand for synthetic formulations as independent workshops face compliance cost pressure from regional environmental authorities enforcing cradle-to-grave waste oil tracking.
- Commercial Vehicles:Fleet-operated vans and light trucks with standardized procurement. Large logistics operators in Catalonia are disintermediating distributors through direct manufacturer contracts for scheduled maintenance programs.
- Two-Wheelers:Motorcycles and scooters with wet clutch compatibility requirements.
- Heavy-Duty Vehicles:Long-haul trucks and construction equipment with severe-duty lubricant specifications.
Passenger vehicles anchor volume throughput. Commercial vehicles are climbing the fastest on value per liter metrics.
Distribution Channel:
Channel selection determines working capital intensity and customer relationship durability in Spain's fragmented service landscape.
- Online Retail:Digital platforms enabling multi-location fleet procurement with consolidated invoicing. Large operators around Zaragoza and Valencia corridors are migrating emergency top-up purchases to specialized B2B portals that bypass traditional auto parts store markups.
- Auto Parts Stores:Independent and chain retailers serving walk-in trade and smaller workshops. These outlets retain relevance for unplanned consumption in secondary cities where service station density remains thin.
- Supermarkets:Mass-market retailers carrying economy-grade packaged lubricants for DIY consumers.
- Service Stations:Integrated oil change facilities with immediate availability and disposal services.
Service stations hold installed capacity. Online retail is gaining share fastest among fleet accounts.
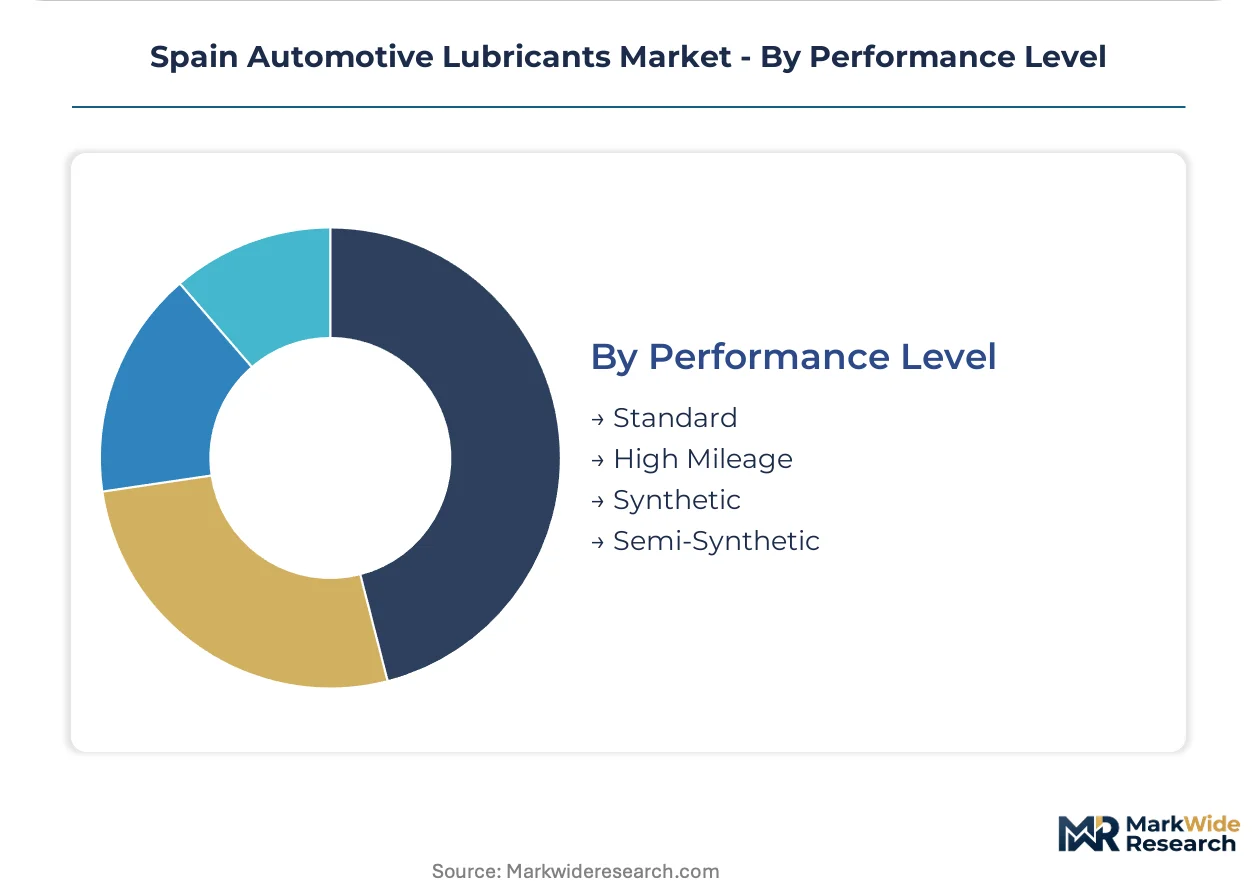
Performance Level:
Performance tier selection directly maps to customer sophistication and total cost-of-ownership calculation maturity.
- Synthetic:Group III/IV base stock formulations with PAO content delivering thermal stability and extended drain intervals. Fleet operators in Seville and Málaga corridors are standardizing on 0W-20 and 5W-30 synthetics to reduce friction losses and align with EU Green Deal decarbonization targets.
- Semi-Synthetic:Blended formulations combining Group II mineral and synthetic base stocks. This tier captures price-sensitive commercial users in Andalusia seeking performance improvement without full synthetic premiums.
- High Mileage:Seal conditioner-enhanced formulations for vehicles exceeding 100,000 kilometers.
- Standard:Conventional mineral oil grades facing compression from reformulation mandates and extended drain interval requirements.
Synthetic grades hold installed capacity. Semi-synthetic is rotating up the share rankings as a bridge technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet buyers in Madrid and Barcelona corridors exhibit low price elasticity for synthetic grades, while independent workshops in secondary Andalusian markets remain highly sensitive to per-liter costs.
Madrid
Commercial logistics operators around the Madrid metropolitan beltway are consolidating procurement on 0W-20 and 5W-30 synthetic formulations. Spain's Royal Decree on waste oils imposes cradle-to-grave tracking obligations that elevate compliance costs for independent workshops. The A-1 and A-2 highway corridors host dense fleet maintenance depots where direct manufacturer contracts are displacing traditional distributor relationships.
Catalonia
Barcelona's port-adjacent logistics clusters generate concentrated demand for extended-drain synthetic lubricants in heavy-duty applications. ECHA-administered REACH compliance creates registration barriers that favor domestic blenders with established regulatory pathways. The Baix Llobregat industrial zone anchors lubricant blending capacity serving both passenger and commercial vehicle segments.
Andalusia
Fleet density around Seville and Málaga remains underpenetrated relative to northern corridors, creating volume expansion opportunities for distributors investing in service infrastructure. Regional environmental authorities enforce national waste oil protocols with varying intensity across provinces. The Campo de Gibraltar refining complex anchors base oil supply security for integrated producers serving southern markets.
Valencia
Mid-sized logistics operators in the Valencia corridor are bifurcating procurement between scheduled bulk purchases and emergency top-up needs via digital channels. EU Green Deal decarbonization targets pull OEM fill specifications toward lower-viscosity grades. The Sagunto port zone concentrates chemical processing assets that support additive package formulation for regional blenders.
Basque Country
Industrial vehicle fleets in Bilbao and San Sebastián corridors maintain above-average synthetic penetration due to early adoption of turbocharged diesel powertrains. Regional environmental authorities in the Basque Country apply stringent waste oil collection mandates that accelerate workshop consolidation. The Bilbao metropolitan area hosts specialized distributors with certified re-refining partnerships.
Spain Automotive Lubricants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Spain's automotive lubricants sector. Repsol S.A. and Cepsa leverage captive refining assets to secure base oil continuity, while international majors compete through formulation specialization and fleet direct contracts. The market structure rewards backward integration into base stock production and forward integration into collection networks for re-refining compliance. Dominant competitive moves include capacity optimization at Tarragona and Andalusian refining complexes, plus strategic partnerships with logistics fleet operators for scheduled maintenance programs.
Within the integrated refiner tier, Repsol S.A. and Cepsa exemplify the capital-intensity advantage of captive base-oil supply from Tarragona and Andalusian production assets. Shell plc occupies a position among international majors differentiating through specialized synthetic formulations. These three companies represent the competitive archetypes shaping margin distribution: domestic integrated producers leveraging feedstock security against global formulators competing on technical performance specifications.
| Leading Market Players |
|---|
| Repsol S.A. |
| Cepsa |
| TotalEnergies SE |
| Shell plc |
| BP PLC (Castrol) |
| ExxonMobil Corporation |
| Fuchs Petrolub SE |
| Chevron Corporation |
| Valvoline Inc. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Mediterranean Group II/III refineries shapes both supply concentration and price floors for Spanish blenders. Integrated producers with captive Tarragona and Andalusian assets extract margin premiums as independents absorb freight volatility from import-dependent feedstock positions.
Pricing Analysis
After-sales service contracts and extended-drain-interval programs drive lifetime value capture for lubricant suppliers. Three-tier pricing structure across premium synthetic, semi-synthetic bridge, and economy mineral levels stratifies by SAE viscosity grade and OEM certification tier. Cost compression in the mineral tier intensifies because EU Green Deal reformulation mandates accelerate grade mix shifts. Fleet operators around Madrid and Barcelona corridors exhibit lowest price sensitivity for certified synthetics, while independent workshops in secondary Andalusian markets resist per-liter premiums.
Supply Chain Analysis
Just-in-time inventory preferences dominate among fleet operators seeking to minimize working capital tied to bulk lubricant storage. Base oil supply draws from Netherlands, Belgium, and domestic Tarragona refining capacity. Additive packages rest on specialized chemistry from Germany and the United States. Single-source vulnerability concentrates in Group III base stock channels through Rotterdam port logistics. Distribution runs through authorized service stations with cradle-to-grave waste oil tracking compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's lubricant sector approaches a platform-economics inflection as fleet procurement portals disintermediate traditional distributor networks. Interoperability between re-refining collection systems and OEM certification databases will determine which blenders capture circular-economy positioning.
For Market Incumbents: Consolidate backward integration into Group III/IV base oil supply through Tarragona capacity optimization or long-term offtake agreements with Mediterranean refiners. Deepen channel control by embedding certified re-refining partnerships into service station networks before regional environmental authorities tighten cradle-to-grave tracking mandates.
For New Entrants and Emerging Players: Lead with digital procurement platforms targeting mid-sized logistics operators in the underpenetrated Seville-Málaga corridor. The Andalusian fleet density gap offers most penetrable volume expansion for distributors investing in localized service infrastructure. Position through direct manufacturer contracts that bypass traditional auto parts store markups for scheduled maintenance programs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated refiners with captive base oil supply and established ECHA regulatory pathways. Long-term viability over the next decade hinges on positioning for circular-economy mandates and bio-based additive formulation capabilities. Watch for inflection when re-refined base oil uptake thresholds trigger preferential procurement terms from fleet sustainability officers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil | Captive Tarragona feedstock security insulates Repsol and Cepsa from Mediterranean freight volatility. |
| Re-Refining Collection Network Expansion | Certified partnerships with regional environmental authorities lock in circular-economy compliance positioning. |
| Digital Fleet Procurement Platform Launch | B2B portals consolidate multi-location ordering for logistics operators around Zaragoza and Valencia corridors. |
| Bio-Based Additive Package Development | Reformulation toward EU Green Deal targets requires R&D investment in viscosity modifier-synthetic compatibility. |
| Direct Manufacturer Contract Proliferation | Scheduled maintenance agreements displace traditional distributors in Catalonia's port-adjacent logistics clusters. |
Research Methodology
A standing panel of lubricant blend plant managers, fleet procurement directors at logistics operators, aftermarket distributor executives, and ECHA regulatory affairs specialists provided ongoing calibration. Primary interviews combined with secondary validation against customs trade data, ACC industry reports, SEC filings from integrated refiners, and vehicle production databases. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include product type, performance level, end-user vehicle category, and distribution channel complexity. CAGRs derived from regression analysis of historical consumption patterns and projected fleet composition shifts. Forecast inputs incorporated OEM fill specification tightening timelines and re-refining capacity buildout assumptions.
Forecasts assume regulatory continuity in EU REACH administration and Spain's Royal Decree waste oil protocols; material policy shifts would require re-modeling. Revision becomes warranted when synthetic grade penetration in commercial fleets crosses thresholds that compress mineral oil demand faster than base stock supply adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Specialty Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Biolubricants Market
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Bio-Based Lubricants Market
Lubricants
ASEAN Lubricants Market
Lubricants
Global Grease Cartridges Market
Lubricants
Slideway Oil Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Anti-Static Oil Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Iraq Lubricants Market
Lubricants
Spain Automotive Engine Oils Market