
 Malaysia Automotive Lubricants Market | 2026-2036
Malaysia Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Automotive Lubricants Market Foresight
Aftermarket service revenue is fragmenting across multiple channel tiers as vehicle parc expansion outpaces traditional workshop consolidation. PETRONAS leverages its integrated refinery and retail network to dominate domestic supply chains. Shell plc competes through premium synthetic formulations targeted at passenger car owners. Exxon Mobil Corporation anchors its position via technical partnerships with commercial fleet operators seeking extended drain intervals.
Automotive lubricants are formulated base oil and additive packages engineered to reduce friction, dissipate heat, and prevent wear in powertrain components, with viscosity grades typically ranging from 0W-20 for modern gasoline engines to 15W-40 for heavy-duty diesel applications. Engine oil commands the largest product type position due to mandatory change intervals, while transmission fluid grows fastest as automatic and CVT penetration rises among Malaysian passenger car buyers. The aftermarket provider channel captures margin concentration through bundled service packages, though independent garages retain volume leadership in motorcycle and aging vehicle segments.
Malaysia's Department of Environment enforces Euro emission standards that tighten lubricant specifications for sulfur and ash content, while SIRIM Berhad administers product certification and labeling requirements that filter substandard imports. The Ministry of International Trade and Industry coordinates domestic manufacturing incentives that shape local blending capacity expansion. Stakeholders must monitor regulatory alignment between ASEAN harmonized standards and Malaysia's national adoption timeline to anticipate specification shifts ahead of compliance deadlines.
Market Dynamics
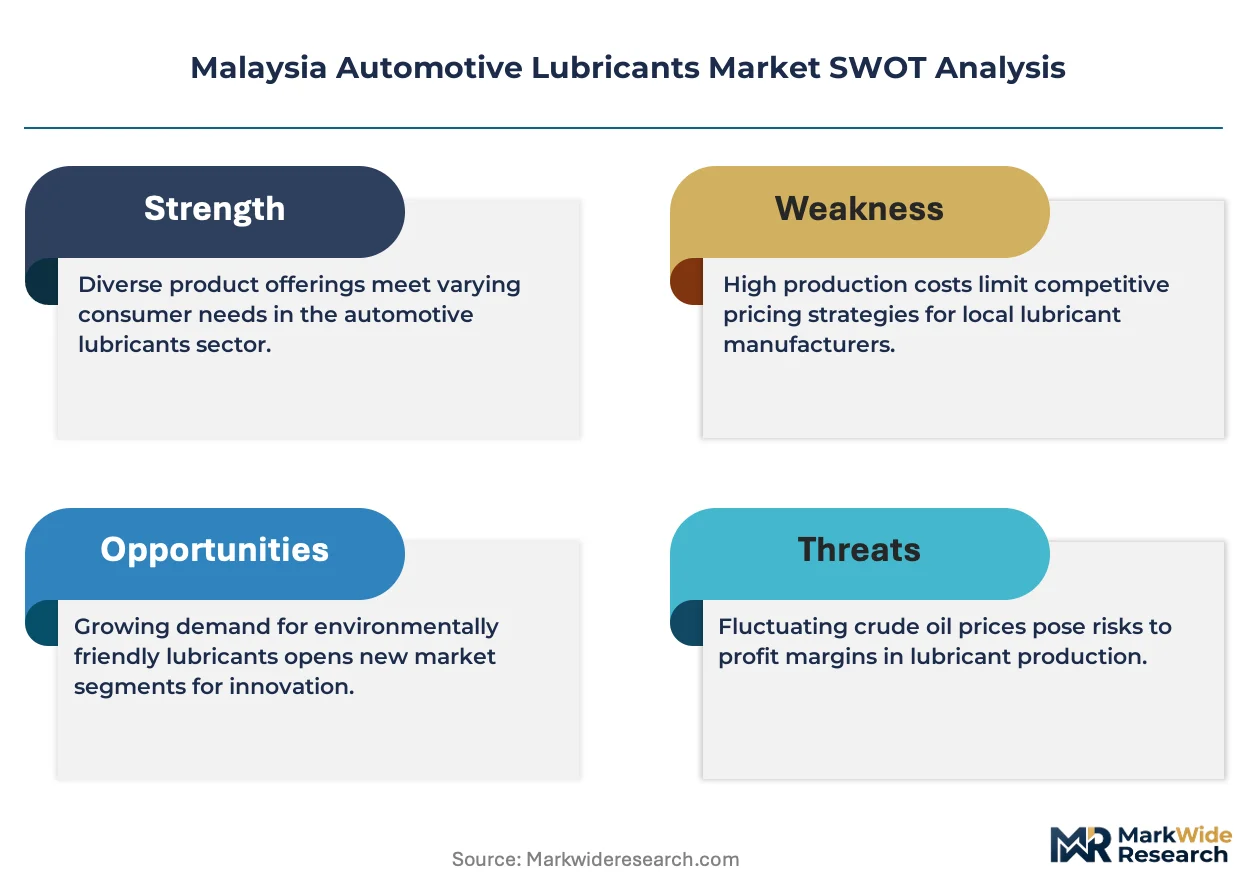
The Malaysia Automotive Lubricants Market is being restructured by Euro emission standard adoption, which forces fleet operators and workshops to upgrade from mineral-based formulations to low-SAPS synthetic blends. This regulatory compression cascades through procurement specifications, blending capacity allocation, and channel certification requirements.
Growth Catalysts
- Euro 5 Alignment:Malaysia's Department of Environment enforcement tightens sulfur and ash content limits, compelling commercial fleets to replace conventional lubricants with compliant synthetic formulations.
- Automatic Transmission Penetration:Rising CVT and dual-clutch adoption among passenger car buyers in the Klang Valley corridor expands demand for specialized transmission fluids with extended service intervals.
- Extended Drain Intervals:Fleet operators in Peninsular Malaysia prioritize lubricants enabling longer service cycles to reduce vehicle downtime and maintenance labor costs.
Market Restraints
- Base Oil Import Concentration:Malaysia's blending facilities depend on Group II and Group III base oil shipments from Singapore and South Korea, exposing margins to freight cost volatility and currency fluctuation.
- Substandard Import Competition:Non-certified lubricants entering through informal channels undercut SIRIM Berhad-certified products on price while eroding quality benchmarks.
- Mineral Oil Substitution Lag:Aging motorcycle and commercial vehicle parc in rural Sabah and Sarawak retains demand for lower-cost mineral formulations, slowing premium product conversion.
Strategic Opportunities
- Johor Bahru Logistics Corridor:Proximity to Singapore's refining hub positions southern Malaysia for integrated blending-to-distribution facilities serving cross-border fleet operations.
- Hybrid Powertrain Fluids:Dual-clutch and hybrid-specific lubricant formulations address emerging thermal management requirements as electrified vehicle sales expand.
- Digital Service Integration:Independent garages adopting IoT-enabled oil condition monitoring can bundle predictive maintenance with lubricant sales, capturing aftermarket margin concentration.
Industry Challenges
- SIRIM Certification Timelines:Product registration delays of 4-6 months constrain new formulation launches and tie up working capital in compliance documentation.
- Workshop Technician Training:Euro 5-specified lubricant handling and disposal protocols require upskilling across Malaysia's fragmented independent garage network, particularly in secondary cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Automotive Lubricants Market |
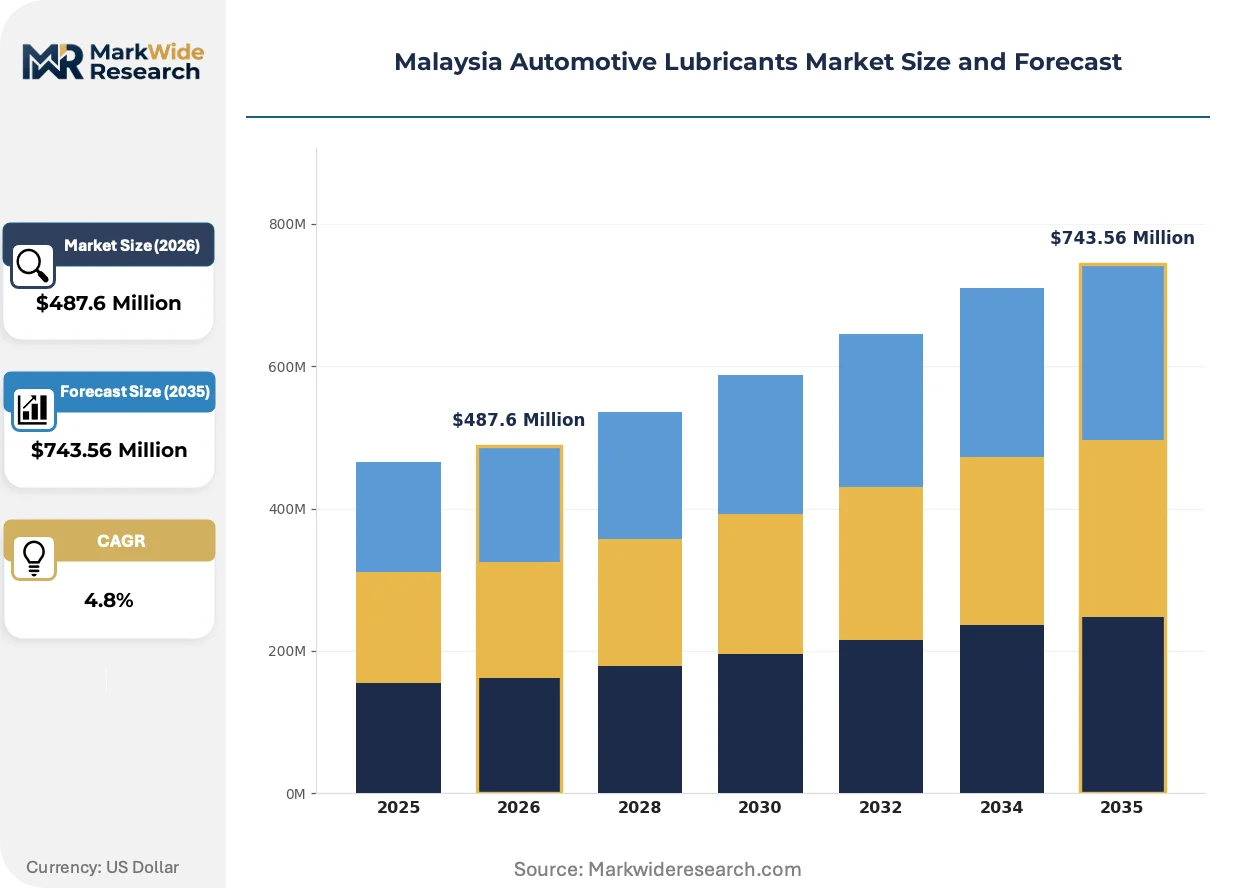
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Greases End User: OEMs, Aftermarket Providers, Independent Garages, Vehicle Assemblers Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Distribution Channel: Online Stores, Retail Outlets, Service Stations, Distributors |
| Companies Covered | Petroliam Nasional Berhad (PETRONAS), Shell plc, BP p.l.c., Exxon Mobil Corporation, Chevron Corporation, TotalEnergies, FUCHS, Petron Corporation, Valvoline Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Automotive Lubricants Market Shifts & Advancements
Formulation chemistry and distribution architecture are converging to reshape how lubricants reach end-users. Three distinct vectors—synthetic blend evolution, regulatory specification tightening, and channel digitization—are restructuring competitive positioning across the value chain.
Synthetic base stocks are hybridizing with bio-derived esters to achieve simultaneous viscosity stability and biodegradability targets. PETRONAS and international blenders are field-testing these formulations with Klang Valley fleet operators seeking to meet corporate sustainability commitments. This hybridizing chemistry is compressing the performance gap between premium synthetics and mid-tier mineral blends, forcing price repositioning across product tiers.
SIRIM Berhad's alignment with ASEAN harmonized lubricant standards is tightening labeling and performance certification requirements. The industrial consequence is accelerated consolidation among smaller domestic blenders unable to absorb testing costs. Workshop chains in Peninsular Malaysia are responding by restricting procurement to pre-certified supplier lists, filtering out informal import channels.
Commercial fleet procurement is consolidating through direct supplier agreements that bypass traditional distributor markups. Large logistics operators in the Klang Valley corridor are negotiating volume contracts with blending facilities for customized formulations with embedded telematics tracking. This concentration is most visible in express delivery and cold-chain segments where vehicle utilization rates demand predictable lubricant supply security.
Malaysia Automotive Lubricants Market Segmentation
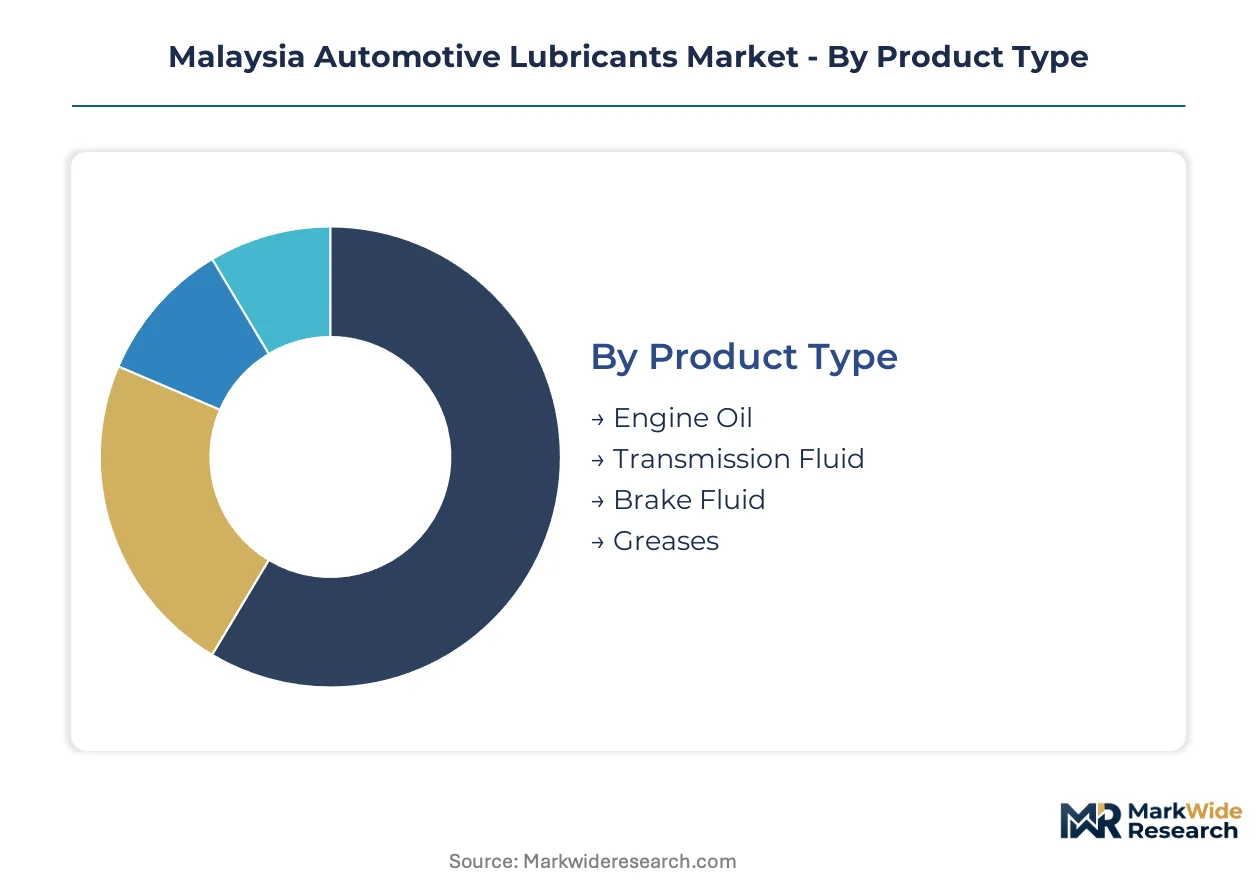
Malaysia's automotive lubricants market segments along four distinct axes that determine procurement velocity, margin capture, and regulatory exposure. Product chemistry, end-user sophistication, vehicle duty cycles, and channel accessibility each create divergent competitive dynamics across Peninsular Malaysia and East Malaysia.
Product Type:
Cycle times vary dramatically across lubricant categories, with engine oil turning over fastest due to mandatory change intervals while greases persist longest in sealed chassis applications.
- Engine Oil:Formulated from base oil and additive packages spanning 0W-20 to 15W-40 viscosity grades, this category commands procurement priority across Klang Valley OEM workshops and independent garages serving high-density vehicle populations. Mandatory drain intervals compress inventory cycles and sustain volume concentration.
- Transmission Fluid:Specialized formulations for automatic, CVT, and dual-clutch systems address rising penetration of advanced transmissions among Malaysian passenger car buyers. Extended service intervals and thermal stability requirements concentrate demand in urban service centers with diagnostic capabilities.
- Brake Fluid:Hygroscopic glycol-ether formulations require periodic replacement per SIRIM Berhad safety protocols, generating steady aftermarket pull from brake service specialists.
- Greases:Lithium and calcium-thickened lubricants serve chassis and bearing applications with multi-year replacement cycles, concentrating volume in commercial fleet maintenance depots.
Engine oil anchors the volume base while transmission fluid gains share at the steepest rate.
End User:
Cost tier stratification separates specification-intensive buyers from price-sensitive procurement, with certification requirements filtering participation at each level.
- OEMs:Vehicle manufacturers and authorized dealerships specify factory-fill and service-fill lubricants meeting proprietary approvals, with PETRONAS and Shell plc dominating technical partnerships through integrated supply agreements.
- Aftermarket Providers:Branded workshop chains bundle lubricant sales with predictive maintenance services, capturing margin concentration through certified technician networks and telematics-enabled oil monitoring in the Klang Valley corridor.
- Independent Garages:Fragmented single-location operators across Peninsular Malaysia and East Malaysia retain volume leadership in motorcycle and aging vehicle segments, sourcing through distributor networks with limited SIRIM Berhad certification enforcement.
- Vehicle Assemblers:Local assembly operations for commercial and passenger vehicles procure bulk lubricants under long-term contracts tied to production schedules and export compliance requirements.
Independent garages handle the highest transaction volumes while aftermarket providers extract the steepest margin expansion.
Vehicle Type:
Application severity drives formulation differentiation, with duty cycles ranging from light-duty urban commuting to continuous-load highway hauling across Malaysian road networks.
- Passenger Cars:Modern gasoline and diesel engines in the Klang Valley corridor demand low-SAPS synthetic blends aligned with Euro 4 and Euro 5 emission standards, with viscosity grades trending toward 0W-20 and 5W-30 for fuel efficiency optimization.
- Commercial Vehicles:Fleet operators across Peninsular Malaysia prioritize 15W-40 and 10W-40 heavy-duty formulations enabling extended drain intervals to minimize downtime, with procurement consolidating through direct supplier agreements bypassing traditional distribution.
- Motorcycles:High-temperature 10W-40 and 20W-50 mineral and semi-synthetic formulations dominate rural Sabah and Sarawak where aging parc and price sensitivity slow premium conversion.
- Heavy-Duty Trucks:Long-haul logistics operators in the Johor Bahru corridor specify API CK-4 and FA-4 compliant lubricants with advanced soot handling and oxidation resistance for severe service cycles.
Commercial vehicles generate the most intensive consumption rates while passenger cars drive specification upgrades fastest.
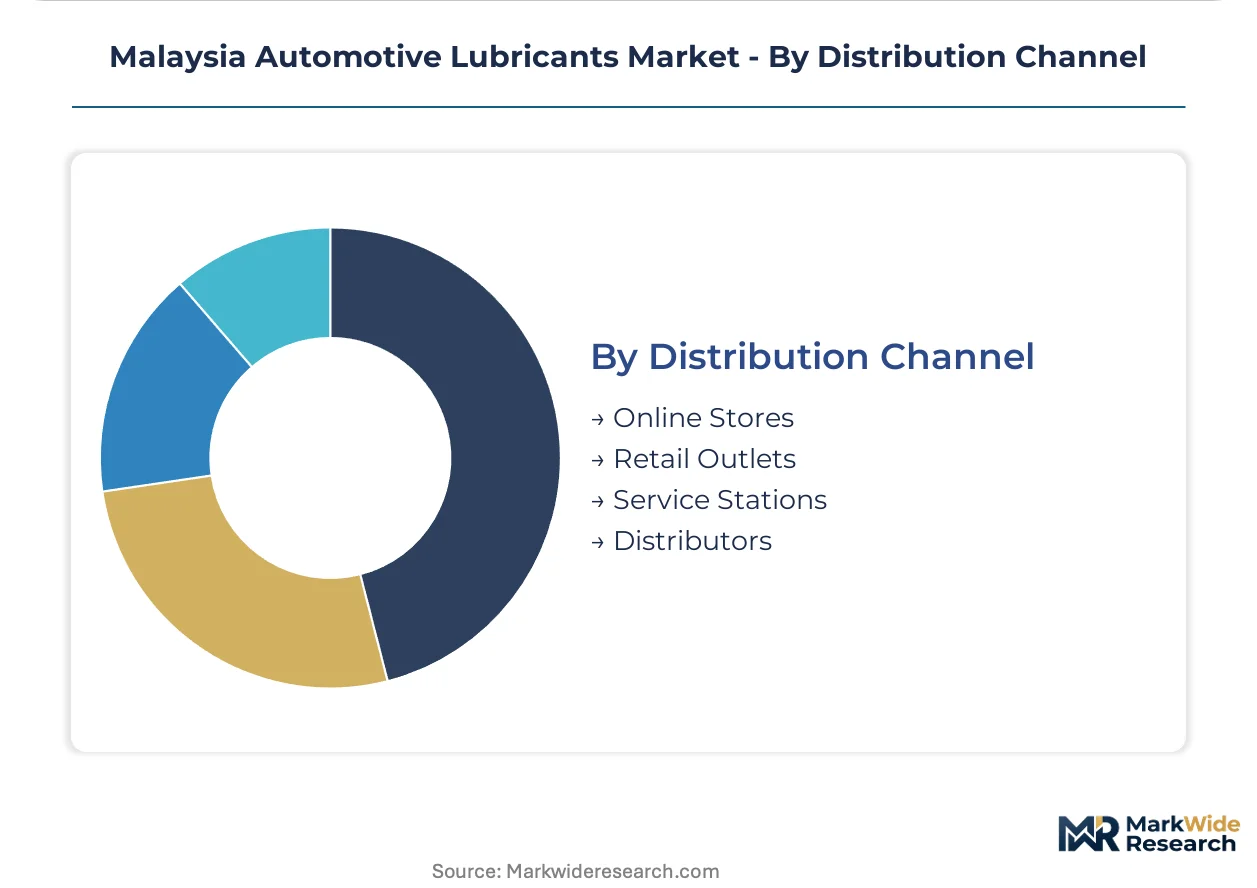
Distribution Channel:
Channel maturity varies from legacy petroleum retail networks to emerging digital platforms, with certification and logistics capabilities determining viable participation.
- Online Stores:E-commerce platforms and lubricant brand direct-to-consumer sites serve DIY enthusiasts and small fleet operators, with SIRIM Berhad certification verification remaining inconsistent across digital listings.
- Retail Outlets:Hypermarkets and automotive specialty stores in urban centers stock consumer-packaged lubricants for self-service buyers, competing on price transparency and brand recognition.
- Service Stations:PETRONAS and Shell plc retail networks integrate lubricant sales with fuel transactions and quick-lube bays, leveraging location density in the Klang Valley for impulse and scheduled maintenance capture.
- Distributors:Regional warehousing operations supply independent garages and secondary-city workshops across Peninsular Malaysia and East Malaysia, absorbing inventory risk and credit extension for fragmented end-users.
Service stations command the densest geographic footprint while online stores expand most rapidly among digitally enabled customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across Malaysian sub-markets, with fleet operators in Peninsular Malaysia absorbing premium synthetic premiums while rural East Malaysia buyers resist conversion from mineral formulations. This demand-elasticity contrast shapes regional procurement patterns and channel development priorities.
Klang Valley
Passenger car density and OEM workshop concentration drive specification-intensive demand for low-SAPS synthetic blends aligned with Euro 5 standards. The Department of Environment enforces emission compliance timelines that accelerate lubricant upgrades in Selangor and Kuala Lumpur. Shah Alam industrial zones host blending facilities supplying certified formulations to authorized service networks.
Johor Bahru Corridor
Cross-border logistics operations with Singapore generate intensive commercial vehicle lubricant consumption with extended drain interval requirements. The Iskandar Malaysia development corridor attracts integrated blending-to-distribution investments leveraging proximity to Singapore refining capacity. Pasir Gudang industrial areas concentrate bulk procurement contracts for regional fleet operators.
Penang and Northern Region
Electronics manufacturing clusters sustain light commercial vehicle fleets with predictable maintenance schedules favoring synthetic formulations. The Ministry of International Trade and Industry coordinates manufacturing incentives that shape local blending capacity allocation. Butterworth logistics hubs channel lubricant distribution to secondary cities across Perak and Kedah.
Sabah
Aging motorcycle and commercial vehicle parc retains dominant mineral oil demand due to price sensitivity and limited SIRIM Berhad certification enforcement. Rural road conditions accelerate wear cycles but compress willingness-to-pay for premium products. Kota Kinabalu serves as the primary distribution node with limited penetration of synthetic formulations beyond urban centers.
Sarawak
Oil and gas operations in Bintulu and Miri generate specialized industrial lubricant demand distinct from automotive applications, though commercial vehicle fleets serving these sectors follow similar procurement patterns. The state's infrastructure development programs expand heavy-duty truck utilization without corresponding specification upgrades. Kuching automotive service networks remain fragmented with inconsistent certified product availability.
Malaysia Automotive Lubricants Market Competitive Landscape
Capability concentration sits with integrated refinery operators; scale advantage sits with international majors with established brand equity. The market structures around three tiers: national oil companies with captive supply chains, global lubricant specialists with formulation R&D depth, and regional distributors serving price-sensitive segments. Competitive moves center on direct fleet procurement agreements and SIRIM certification pre-qualification for workshop network access.
Among integrated energy companies, Petroliam Nasional Berhad (PETRONAS) anchors the domestic supply chain through refinery-linked blending and retail network density. Shell plc and Exxon Mobil Corporation exemplify international majors competing via technical specification leadership and fleet operator partnerships. These three entities occupy positions spanning factory-fill agreements, aftermarket certification programs, and direct commercial procurement channels.
| Leading Market Players |
|---|
| Petroliam Nasional Berhad (PETRONAS) |
| Shell plc |
| BP p.l.c. |
| Exxon Mobil Corporation |
| Chevron Corporation |
| TotalEnergies |
| FUCHS |
| Petron Corporation |
| Valvoline Inc |
| Others |
Supply & Pricing Matrix
Blending facility undercapacity in southern Peninsular Malaysia concentrates pricing leverage among integrated refinery operators while compressing margins for independent distributors dependent on spot base oil procurement. This utilization asymmetry forces fleet buyers into long-term offtake agreements to secure synthetic formulation supply, while independent garages absorb volatile distributor markups on mineral oil products.
Pricing Analysis
Long-term offtake contracts dominate commercial fleet procurement in the Klang Valley corridor, locking in volume commitments for low-SAPS synthetic blends at fixed premiums over spot mineral oil rates. Price differentiation rests on SIRIM Berhad certification grade and volume scale, with certified formulations commanding substantial premiums over informal imports. Cost compression in the mineral oil tier is intensifying because substandard imports from unregulated channels undercut compliant products. Independent garages in East Malaysia exhibit the highest price sensitivity, while express delivery fleets in Johor Bahru absorb premium synthetic pricing to minimize vehicle downtime.
Supply Chain Analysis
Contract manufacturing concentration sits with Singapore and South Korean refineries supplying Group II and Group III base oils to Malaysian blending facilities in Pasir Gudang and Shah Alam. Raw material dependencies center on API Group II/III base stocks, additive packages from specialty chemical suppliers, and packaging materials from regional converters. Single-source vulnerability runs through the Singapore-Johor Bahru logistics corridor where customs delays or freight disruptions cascade through just-in-time blending schedules. Distribution runs through PETRONAS and Shell plc retail networks for consumer segments, while commercial fleets procure through direct supplier agreements bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against electrification-driven lubricant demand erosion as hybrid and battery-electric vehicle penetration accelerates across ASEAN markets. Incumbents must navigate the threat of declining internal combustion engine parc while capturing emerging thermal management fluid opportunities.
For Market Incumbents: Insulate core engine oil revenue by securing factory-fill agreements with emerging domestic EV assemblers and hybrid platform suppliers. Accelerate backward integration into additive package formulation to reduce dependency on imported chemical inputs. Expand SIRIM Berhad certification pre-qualification programs to filter informal import competition from workshop procurement lists.
For New Entrants and Emerging Players: Pursue white-space positioning in hybrid-specific thermal management fluids where formulation specifications remain unsettled and incumbent certification advantages are weakest. Target Sabah and Sarawak independent garage networks with competitively priced semi-synthetic products bridging mineral and full synthetic tiers. Deploy mobile blending unit partnerships to overcome distribution infrastructure gaps in East Malaysia.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic blending capacity as Euro 5 compliance forces equipment upgrades and testing infrastructure investment. Long-term viability favors integrated operators with captive base oil supply and retail network density over pure-play distributors. Acquisition targets should demonstrate established SIRIM certification pipelines and direct fleet procurement relationships. Monitor Johor Bahru corridor logistics investment announcements as inflection indicators for cross-border supply chain consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Blending Capacity Expansion | Domestic facilities in Shah Alam and Pasir Gudang upgrade to meet Euro 5 low-SAPS formulation demand. |
| SIRIM Certification Pre-Qualification | Workshop chains restrict procurement to certified suppliers, filtering informal import channels from distribution. |
| Direct Fleet Procurement Agreements | Logistics operators in Klang Valley negotiate volume contracts bypassing traditional distributor markups. |
| Hybrid Powertrain Fluid Development | Dual-clutch and thermal management formulations address electrified vehicle sales expansion requirements. |
| Digital Service Integration | IoT-enabled oil condition monitoring bundles predictive maintenance with lubricant sales capture. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with fleet procurement managers, independent garage owners, blending facility technical directors, and PETRONAS retail network operators. Secondary validation drew from SIRIM Berhad certification databases, Department of Environment emission standard enforcement records, Ministry of International Trade and Industry incentive disclosures, and ASEAN harmonized lubricant standard documentation. Bottom-up volume estimates from end-user consumption patterns were triangulated against top-down production capacity assessments from domestic blending facilities.
Calibration against historical base oil import volumes and lubricant sales tax records anchored the projection framework across the analysis window. Segmentation dimensions modeled include product chemistry tier, end-user sophistication level, vehicle duty cycle severity, and distribution channel accessibility. CAGRs were derived from regression analysis of parc expansion rates, drain interval extension trends, and synthetic formulation penetration curves. Industry-specific inputs incorporated Euro emission standard compliance timelines and automatic transmission penetration forecasts from vehicle registration data.
Macroeconomic conditions sit as an overlay; deviation in ringgit-dollar exchange rates, Singapore refining margins, or regional freight costs would shift the trajectory of import-dependent pricing tiers. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and emission standard adoption pacing. Quarterly review of SIRIM certification application backlogs and Johor Bahru logistics corridor investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Italy Automotive Lubricants Market
Lubricants
Hydraulic Fluids and Process Oil Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Drilling Lubricants Market
Lubricants
Technical Fluids Market
Lubricants
Nigeria Lubricants Market
Lubricants
Norway Lubricants Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Hydropower Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Qatar Lubricants Market
Lubricants
Lubricity Improvers Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
Thailand Lubricants Market