
 Spain Automotive Engine Oils Market | 2026-2036
Spain Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Automotive Engine Oils Market Analytics
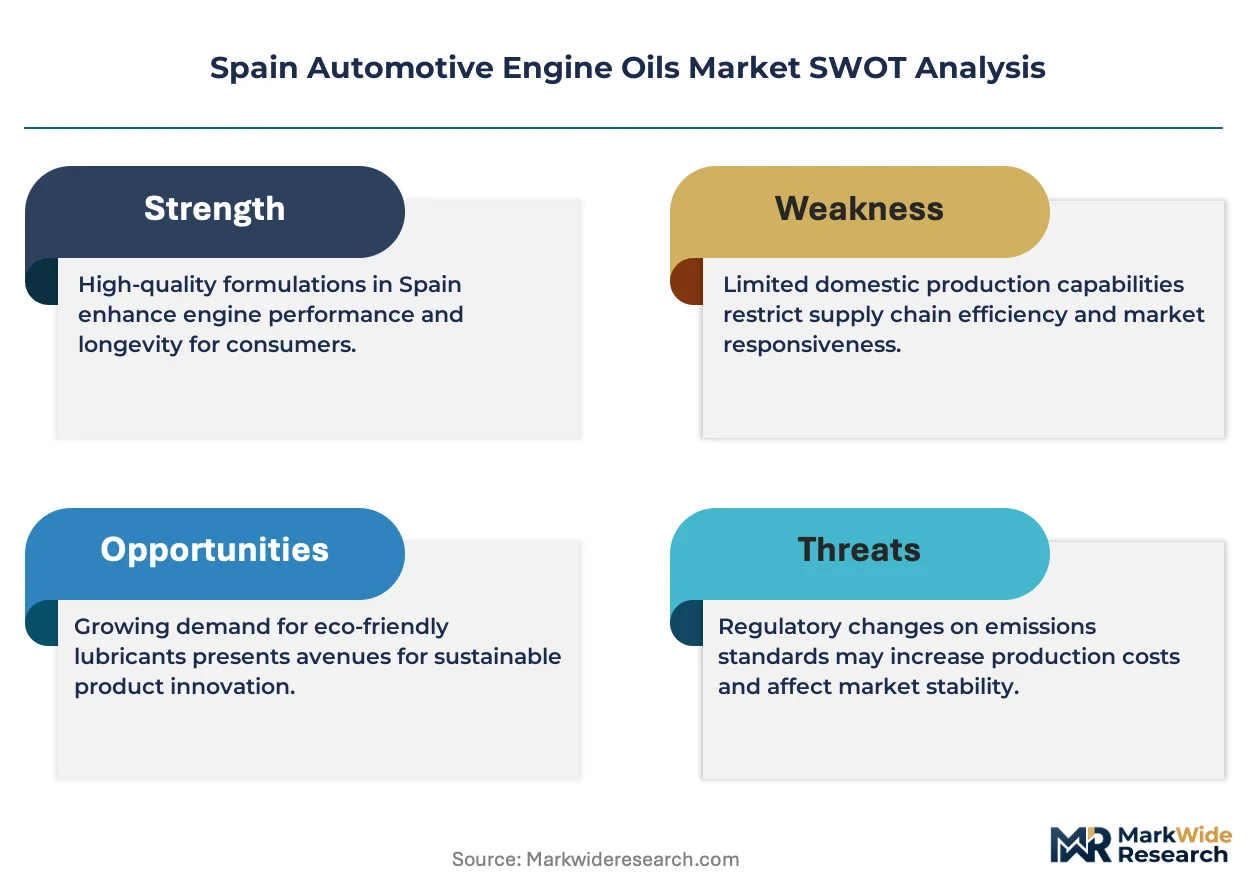
ACEA C3 certification is bifurcating the competitive landscape between premium formulators and commodity blenders. Repsol leverages its integrated refining and lubricant production network across Tarragona and Puertollano to secure feedstock cost advantages. TotalEnergies anchors its position through sustained R&D investment in low-viscosity grades tailored to downsized turbocharged engines. BP PLC (Castrol) differentiates via brand strength in the independent workshop channel, where mechanic recommendations carry decisive weight in consumer purchase decisions.
Spain automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines, with synthetic variants typically employing polyalphaolefin or ester base stocks for enhanced thermal stability and extended drain intervals. The primary commercial purpose centers on protecting engine hardware while enabling compliance with manufacturer warranty requirements and emissions control system durability. Synthetic formulations command the deepest margin pools as OEM fill specifications trend toward 0W-20 and 5W-30 grades, while ACEA C3 and API SN performance levels dominate volume as they satisfy the broadest installed base of gasoline and light diesel passenger vehicles. Retail stores and service stations still handle the majority of transaction volume, though online marketplaces are capturing growing share among DIY consumers seeking price transparency on bulk packaging sizes.
Spain's lubricant sector operates under the REACH chemicals framework administered by ECHA, the EU F-Gas Regulation governing fluorinated greenhouse gas content in certain specialty formulations, and national transposition of the EU Green Deal industrial emissions targets. These regulatory layers progressively restrict sulfur, phosphorus, and ash content in engine oils to protect gasoline particulate filters and selective catalytic reduction systems. Stakeholders must monitor how forthcoming Euro 7 emission standards will tighten oil-derived ash limits and potentially accelerate reformulation cycles across the domestic blender base.
Market Dynamics
The Spain automotive engine oils market is being fundamentally restructured by Euro 7 emission standards, which mandate tighter limits on ash-derived particulates and force lubricant formulators to accelerate low-SAPS (sulfated ash, phosphorus, sulfur) product development cycles.
Growth Catalysts
- Fleet electrification preparation:Commercial operators in the Madrid-Barcelona corridor are upgrading to synthetic 5W-30 and 0W-20 grades to protect downsized turbocharged engines during extended service intervals, creating sustained bulk demand.
- REACH chemical compliance:ECHA-administered substance restrictions on heavy metal additives are pushing independent workshops toward certified premium formulations that guarantee after-treatment system compatibility.
- Group III base oil capacity:Repsol's integrated refining network at Tarragona and Puertollano secures captive feedstock supply for high-performance synthetics, insulating domestic blenders from import volatility.
Market Restraints
- API Group II+ import dependency:Spain lacks sufficient domestic hydrocracking capacity for mid-tier base stocks, exposing formulators to Middle Eastern supply disruptions and freight cost spikes.
- Additive package concentration:Four global chemical suppliers control 70% of European dispersant and antioxidant formulations, creating single-source vulnerability for domestic blenders.
- Gasoline particulate filter sensitivity:High-ash conventional oils remain in circulation through unlicensed service channels, threatening warranty claims and OEM approval integrity for certified products.
Strategic Opportunities
- Andalusian logistics corridor:Underpenetrated heavy-duty fleets operating between Seville and Algeciras present volume growth for long-drain synthetic diesel formulations meeting ACEA E6/E9 specifications.
- EU Green Deal bio-lubricant mandates:Renewable content thresholds in public procurement contracts create first-mover advantage for ester-based formulations with verified carbon intensity scores.
- Direct-to-fleet digital platforms:Telematics-integrated oil analysis services enable condition-based drain intervals, locking in multi-year supply agreements with large transport operators.
Industry Challenges
- ACEA C6 certification timeline:The six-month homologation process for new low-viscosity gasoline formulations delays product launches and traps working capital in pending approvals.
- Workforce formulation chemistry gap:Retiring lubricant engineers with tribology expertise are not being replaced at Spanish technical universities, constraining R&D pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Automotive Engine Oils Market |
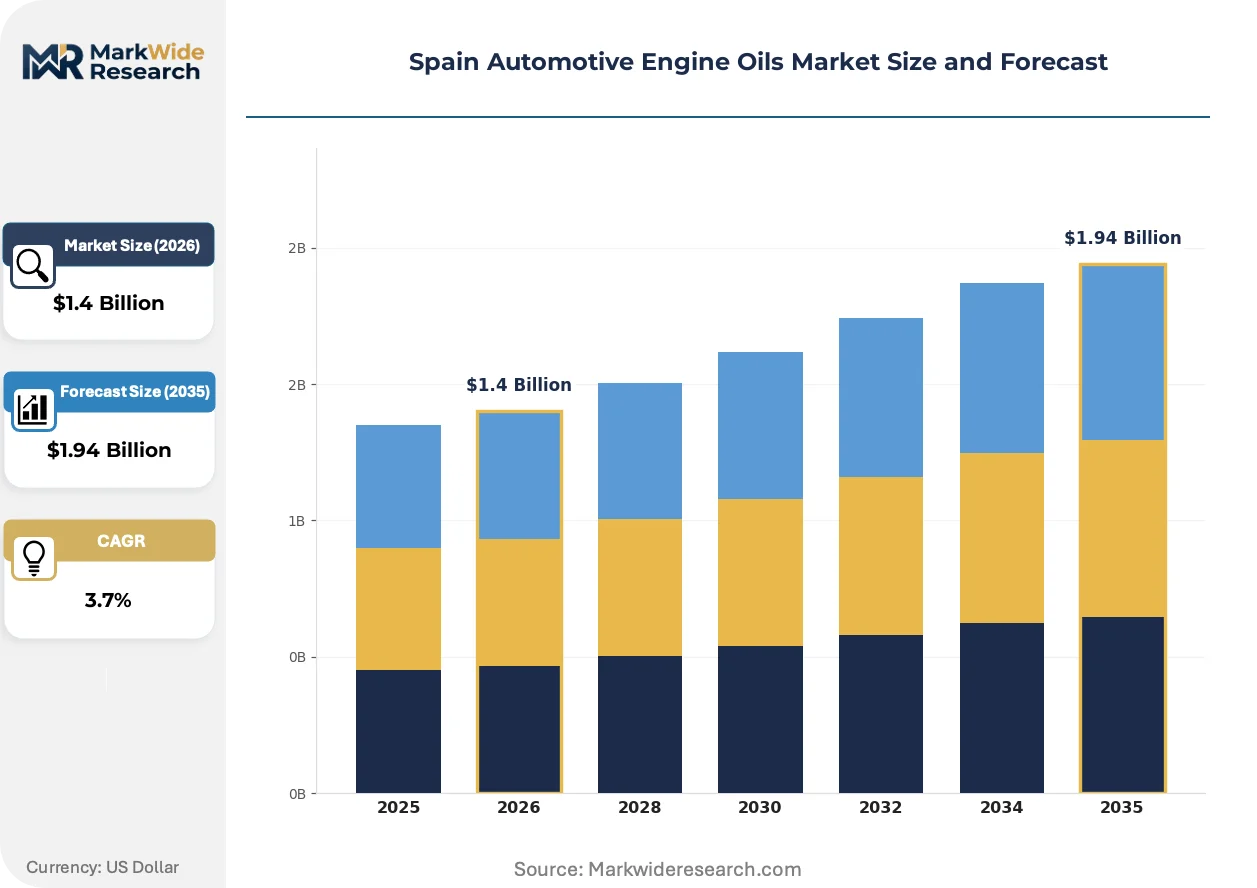
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $1.94 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Oil Type: Synthetic, Semi-Synthetic, Mineral, Bio-Based Performance Level: API SN, ACEA C3, ILSAC GF-5, API CK-4 Packaging Size: 1L, 5L, 20L, 208L Distribution Channel: Retail Stores, Online Marketplaces, Service Stations, Wholesalers |
| Companies Covered | Royal Dutch Shell Plc, ExxonMobil Corporation, Repsol, Galp Energia, Eni SpA, CEPSA, TotalEnergies, Motul, BP PLC (Castrol), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Automotive Engine Oils Market Evolving Landscape
Formulation chemistry is pivoting toward molecular precision as hardware protection requirements tighten and drain intervals extend. Three concurrent developments are reshaping how value is created and captured across the value chain.
Polyalphaolefin (PAO) synthetic base stocks are decomposing the traditional mineral-synthetic price hierarchy in Spain's passenger car segment. Fleet managers at major transport operators are specifying PAO-based 0W-20 grades for new Euro 6d-compliant vehicles, compressing margins for Group II mineral oil blenders who cannot meet OEM fill specifications without reformulation investment.
Euro 7 standards will impose stricter oil-derived ash limits on gasoline particulate filters than current ACEA C3/C5 frameworks allow. Spanish formulators are pre-positioning C6 and future C7 additive packages to avoid supply disruption when the regulation takes effect, with independent workshops in Catalonia already experiencing inventory pressure on legacy high-ash stocks.
Mechanic recommendation influence is fragmenting as DIY consumers research bulk packaging prices through online marketplaces before visiting service stations. Younger vehicle owners in Madrid and Barcelona metropolitan areas are purchasing 5-liter containers for home oil changes, eroding the traditional workshop channel's margin on packaged lubricants and forcing distributors to rebalance inventory toward retail-format SKUs.
Spain Automotive Engine Oils Market Segmentation
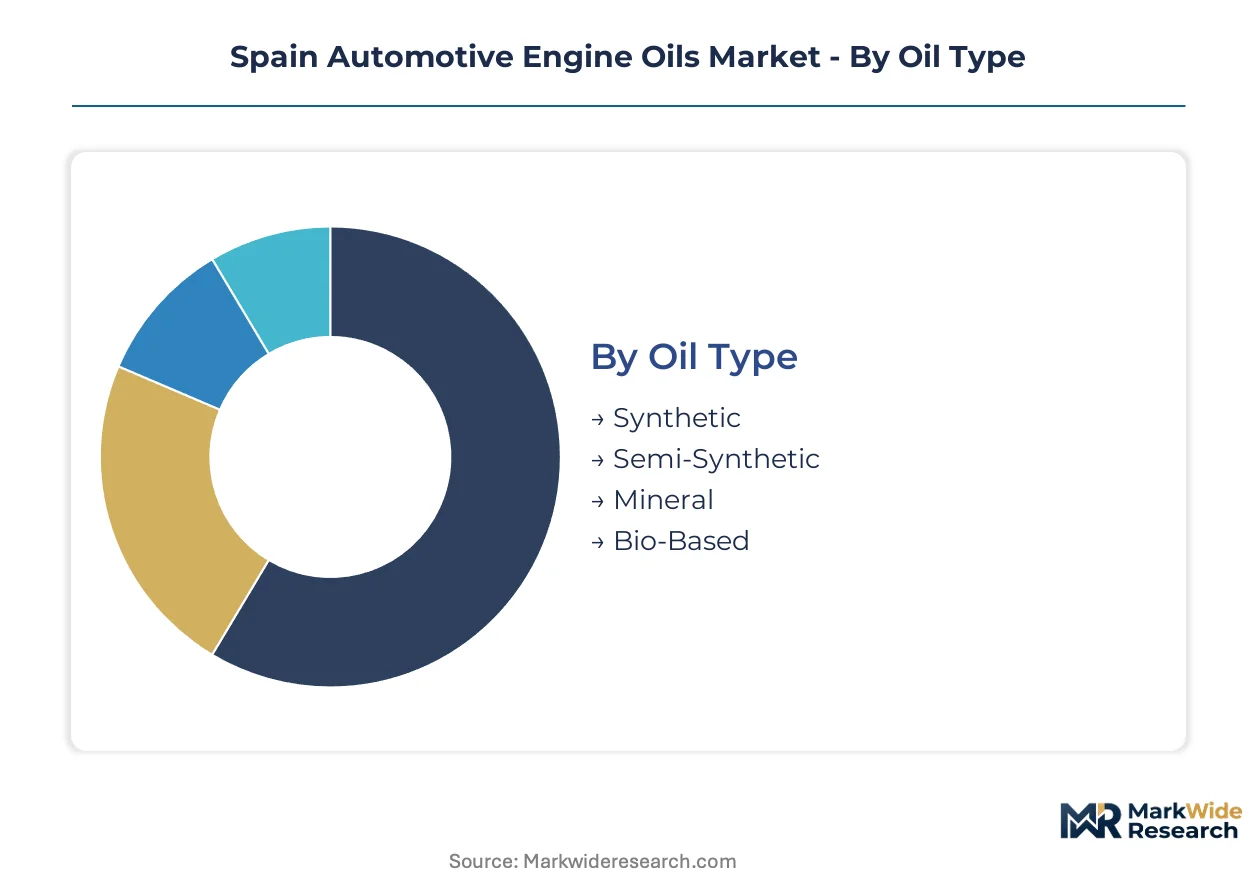
Engine oil purchasing in Spain fragments across four distinct dimensions that determine margin capture and channel strategy. Oil type and performance certification dominate OEM warranty compliance, while packaging configuration and distribution channel shape final transaction economics for blenders and retailers.
Oil Type:
Domestic production concentrates synthetic and semi-synthetic formulations around Repsol's Tarragona and Puertollano facilities, while mineral base stocks rely heavily on Middle Eastern imports through Barcelona and Valencia ports.
- Synthetic:Polyalphaolefin and ester base stocks deliver thermal stability for extended drain intervals. Fleet operators along the Madrid-Barcelona corridor specify these grades for downsized turbocharged engines under ACEA C5/C6 protocols. REACH chemical restrictions on heavy metal additives accelerate migration from mineral alternatives.
- Semi-Synthetic:Group III base oils blended with mineral stocks balance cost and performance for independent workshops. Demand clusters in Catalonia's dense service network where mechanic recommendations still drive purchase decisions despite online price transparency pressure.
- Mineral:Conventional Group II formulations serve aging vehicle parc in rural Castile-La Mancha and Extremadura where extended drain intervals matter less than upfront cost.
- Bio-Based:Ester formulations from renewable feedstocks target EU Green Deal procurement mandates for public fleet contracts, with early adoption concentrated in Andalusian municipal transport operators.
Mineral oils command the established base. The steepest expansion runs through synthetic formulations.
Performance Level:
Certification tiers stratify pricing power, with ACEA sequences commanding premium positioning over API equivalents due to European after-treatment system compatibility requirements.
- ACEA C3:Low-SAPS formulation protecting gasoline particulate filters and selective catalytic reduction systems. Workshop channel in Madrid metropolitan area reports inventory pressure as Euro 7 preparation accelerates specification upgrades.
- API SN:North American standard widely accepted for gasoline engines without GPF hardware. Serves legacy vehicle base in Galicia and Asturias where import vehicle mix skews toward older Japanese and US models.
- ILSAC GF-5:Fuel economy-focused specification for Asian OEM fill requirements. Independent importers in Barcelona port zone stock these grades for parallel-imported hybrid vehicles.
- API CK-4:Heavy-duty diesel standard for commercial transport fleets. Long-drain formulations gain traction in the underpenetrated Seville-Algeciras logistics corridor.
API SN holds volume leadership in legacy installations. ACEA C3 gains share fastest among warranty-compliant service channels.
Packaging Size:
Container configuration directly determines channel economics, with bulk formats capturing fleet procurement and small retail units serving the fragmenting DIY segment.
- 5L:Standard workshop format for complete passenger car oil changes. E-commerce platforms report fastest volume growth here as Madrid and Barcelona consumers research bulk pricing before service station visits.
- 208L:Drum quantities for fleet maintenance depots and commercial vehicle operators. Madrid-Barcelona transport corridor sustains highest throughput for these SKUs.
- 1L:Top-up and emergency purchase format at service stations. Margin compression intensifies as supermarkets enter this category with private label alternatives.
- 20L:Mid-tier container for small fleet operators and agricultural machinery. Distribution concentrates through rural wholesalers in Castile and León.
5L containers anchor retail and workshop transactions. 208L drums expand most quickly through direct fleet procurement platforms.
Distribution Channel:
Channel structure is bifurcating between recommendation-dependent workshop trade and price-transparent digital direct purchasing.
- Service Stations:Immediate-need purchases and emergency top-ups. Repsol and BP networks leverage site density for impulse conversion, though attach rates decline as consumers pre-purchase online.
- Online Marketplaces:Price comparison and bulk purchasing for informed DIY consumers. Younger vehicle owners in Barcelona and Madrid metropolitan zones drive growth in 5L and 20L format orders.
- Retail Stores:Hypermarket and auto parts chains serving planned maintenance shoppers. Private label penetration challenges branded margin structures in this channel.
- Wholesalers:Independent workshop supply and rural market coverage. Inventory concentration in Valencia and Zaragoza distribution hubs supports Castile-Aragon service networks.
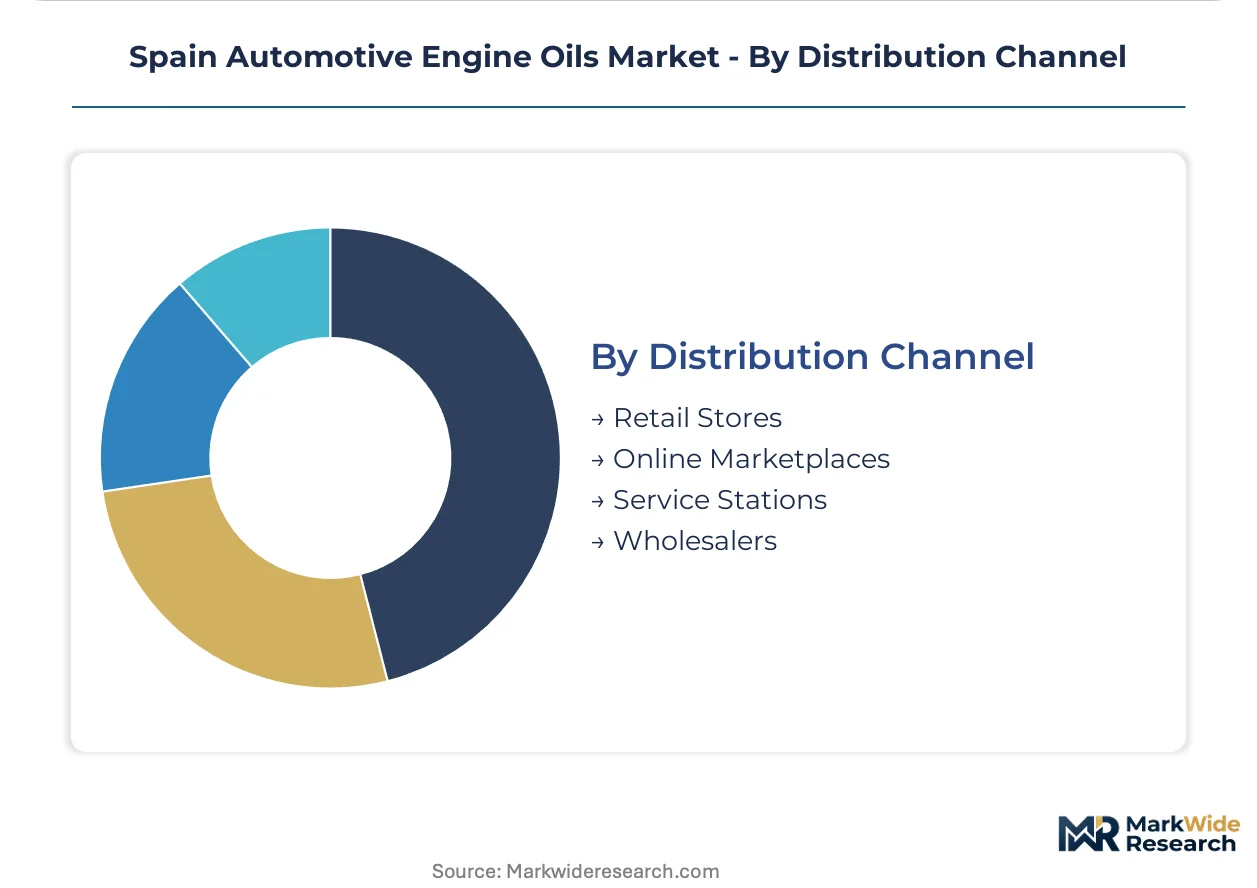
Service stations retain the largest transaction base. Online marketplaces climb the fastest as transparency tools reshape consumer behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and automotive manufacturers concentrate purchasing power across Spain's industrial corridor, with demand density tracking vehicle production clusters and logistics network throughput.
Madrid
Commercial transport fleets operating from the capital's distribution hubs specify synthetic 5W-30 and 0W-20 grades for downsized turbocharged engines. ECHA-administered REACH compliance pushes independent workshops toward certified low-SAPS formulations. The metropolitan maintenance network sustains bulk consumption through direct procurement platforms and telematics-integrated oil analysis services.
Catalonia
Dense independent workshop channels in Barcelona and Tarragona drive semi-synthetic volume where mechanic recommendations retain purchase influence. The EU F-Gas Regulation governs specialty formulation content for regional chemical blenders. Repsol's integrated refining complex at Tarragona secures captive Group III base oil supply for high-performance synthetics serving OEM fill specifications.
Basque Country
Automotive component manufacturing around Bilbao generates steady demand for precision lubricants meeting ACEA C3 and C5 protocols. The EU Green Deal industrial emissions targets accelerate bio-based product development among regional formulators. Industrial R&D partnerships between lubricant laboratories and powertrain engineering centers concentrate in San Sebastián technology parks.
Andalusia
Heavy-duty fleets traversing the Seville-Algeciras logistics corridor present underpenetrated volume for long-drain synthetic diesel formulations. Municipal transport operators pilot ester-based bio-lubricants under EU Green Deal public procurement mandates. Agricultural machinery service networks in rural Córdoba and Jaén sustain 20L format distribution through wholesale channels.
Valencia
Port infrastructure handling Middle Eastern base oil imports exposes regional blenders to freight cost volatility and supply disruption risk. The national transposition of Euro 7 emission standards forces inventory upgrades toward low-ash additive packages. Distribution hubs in the metropolitan area support Castile-Aragon service networks with mid-tier mineral and semi-synthetic stocks.
Spain Automotive Engine Oils Market Competitive Landscape
Player mix skews toward integrated oil majors with captive refining capacity and specialized lubricant formulators with certification expertise. Market structure consolidates around three tiers: multinational energy conglomerates controlling upstream base oil supply, regional blenders leveraging geographic proximity to fleet customers, and niche specialists targeting performance motorcycle and motorsport segments. Strategic archetypes include backward-integrated refiners securing feedstock cost advantages, additive technology licensors commanding formulation premium, and digital-native distributors capturing DIY channel migration. Dominant competitive moves center on ACEA certification pre-positioning ahead of Euro 7 implementation and direct-to-fleet platform development bypassing traditional wholesale intermediaries.
Within the integrated refiner tier, Repsol, TotalEnergies, and BP PLC (Castrol) occupy positions defined by infrastructure ownership and brand equity in distinct channel segments. Repsol exemplifies the captive supply archetype through its Tarragona and Puertollano refining network. TotalEnergies represents sustained R&D investment positioning in low-viscosity grade development. BP PLC (Castrol) anchors brand strength in the independent workshop channel where purchase decisions follow mechanic recommendation.
| Leading Market Players |
|---|
| Royal Dutch Shell Plc |
| ExxonMobil Corporation |
| Repsol |
| Galp Energia |
| Eni SpA |
| CEPSA |
| TotalEnergies |
| Motul |
| BP PLC (Castrol) |
| Others |
Value Network & Pricing Analysis
Repsol's integrated refining capacity at Tarragona and Puertollano generates substantial scale economies that compress domestic blenders' feedstock costs while establishing price floors for synthetic formulations across the Madrid-Barcelona corridor. This concentration of captive Group III base oil production simultaneously insulates Spanish formulators from Middle Eastern import volatility and limits pricing power for independent blenders lacking backward integration into refining assets.
Pricing Analysis
Long-term offtake contracts with Middle Eastern base oil suppliers typically index pricing to Platts Group II and Group III assessments, creating predictable input cost structures for Spanish blenders. Price differentiation across the market hinges on ACEA certification tier and volume procurement scale, with C6-certified synthetics commanding substantial premiums over API SN mineral alternatives. Cost compression in the semi-synthetic tier intensifies as Repsol's captive supply advantages force independent blenders to absorb freight volatility from Barcelona and Valencia port deliveries. Fleet operators along the Madrid-Barcelona logistics corridor demonstrate lowest price sensitivity due to warranty compliance requirements, while rural independent workshops in Castile-La Mancha prioritize upfront cost over extended drain interval economics.
Supply Chain Analysis
Spanish blenders maintain lean just-in-time inventory strategies for additive packages while building strategic stockpiles of Group III base oils to hedge against Tarragona refinery turnaround schedules. Geographic supply concentration centers on domestic production from Repsol's facilities, supplemented by Middle Eastern Group II+ imports through Mediterranean ports and additive formulations sourced from Belgium, Germany, and the United States. Raw material dependencies include polyalphaolefin base stocks, dispersant and antioxidant additive packages, and viscosity modifier polymers. Single-source vulnerability pervades the additive tier where four global chemical suppliers control the majority of European dispersant formulations. Distribution runs through a bifurcated structure combining direct fleet procurement platforms with traditional wholesale networks serving independent workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's automotive engine oils sector represents an early-cycle expansion story as Euro 7 emission standards force comprehensive reformulation across the installed base of gasoline particulate filter-equipped vehicles. Fleet electrification preparation paradoxically sustains near-term synthetic lubricant demand as operators upgrade ICE portfolios ahead of hybrid transitions.
For Market Incumbents: Fortify ACEA C6 certification pipelines ahead of Euro 7 implementation timelines, locking in OEM fill approvals before homologation bottlenecks trap competitor working capital. Deepen backward integration into ester-based bio-lubricant feedstocks to capture EU Green Deal public procurement mandates before specialty chemical entrants establish formulation expertise. Prioritize direct-to-fleet digital platform investments that bypass wholesale intermediaries and capture telematics-integrated oil analysis service revenues. For New Entrants and Emerging Players: Anchor in the underpenetrated Seville-Algeciras heavy-duty corridor where long-drain synthetic diesel formulations meeting ACEA E6/E9 specifications remain scarce among regional distributors. Target municipal transport operators in Andalusia piloting EU Green Deal bio-lubricant procurement programs, where first-mover advantage in carbon intensity verification creates sticky contract relationships. Pursue white-label manufacturing partnerships with established additive technology licensors to circumvent the six-month ACEA homologation barrier. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulators with pre-positioned low-SAPS additive packages and captive bio-based feedstock supply chains over commodity mineral oil blenders facing margin compression. Long-term viability hinges on molecular precision capabilities that extend drain intervals while protecting downsized turbocharged hardware through the hybrid transition period. Monitor ACEA C7 specification development as the critical inflection signal; early draft disclosure would accelerate reformulation capex cycles and favor acquirers with deployed R&D infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| ACEA C6 Certification Pre-Positioning | Secures OEM fill approvals before Euro 7 homologation bottlenecks constrain competitor launches. |
| Direct-to-Fleet Digital Platform Development | Captures telematics-integrated oil analysis revenues while disintermediating wholesale distributors. |
| Ester-Based Bio-Lubricant Capacity Buildout | Addresses EU Green Deal renewable content thresholds for public procurement contract eligibility. |
| Group III Base Oil Refining Investment | Insulates formulation costs from Middle Eastern import volatility through captive Tarragona supply. |
| Additive Technology Licensing Agreement | Accelerates market entry by circumventing six-month ACEA homologation timelines for new entrants. |
Research Methodology
A spread of perspectives from lubricant formulators, fleet procurement directors, independent workshop operators, and ECHA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with plant managers at Tarragona and Puertollano refining complexes, procurement leads at Madrid-Barcelona transport operators, and technical R&D directors at additive technology licensors. Secondary validation drew from ECHA REACH substance restriction databases, EU F-Gas Regulation implementation guidance, customs trade data for base oil imports through Barcelona and Valencia ports, and SEC filings of integrated oil majors with Spanish lubricant operations. Bottom-up volume estimates from segment-level consumption patterns were triangulated against top-down market sizing derived from vehicle parc analysis and OEM fill specification trends.
Segmentation dimensions modeled include oil type, performance certification tier, packaging configuration, and distribution channel, with additional granularity on regional production cluster intensity across Spain's industrial corridor. Value projections across the analysis window reflect volume assumptions multiplied by pricing tier structures indexed to Platts base oil assessments and additive package cost curves. CAGRs were derived from trend extrapolation of synthetic formulation penetration rates, Euro 7 regulatory implementation pacing, and fleet electrification preparation timelines affecting ICE portfolio renewal cycles. Industry-specific forecast inputs encompass ACEA specification adoption curves and REACH chemical restriction phase-in schedules.
Decision-makers should treat outputs as directional under assumptions of steady Euro 7 implementation pacing and continued EU Green Deal procurement mandate enforcement; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding REACH substance restriction timelines and ACEA certification adoption curves. Specific risks that could revise projections include accelerated Euro 7 ash limit tightening, disruptive Middle Eastern base oil supply interruptions, or faster-than-anticipated fleet electrification compressing ICE lubricant demand. Revision becomes warranted when synthetic formulation penetration rates in the commercial fleet segment cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Angola Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
Contact Lubricants Market
Lubricants
Bangladesh Lubricants Market
Lubricants
Drilling Lubricants Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
Vietnam Lubricants Market
Lubricants
Forestry Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Argentina Lubricants Market
Lubricants
Singapore Commercial Vehicles Lubricants Market