
 Saudi Arabia Lubricants Market | 2026-2036
Saudi Arabia Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Lubricants Market Outlook
Low-viscosity synthetic formulations and Group III base oil upgrading is rewriting product specifications across the Saudi lubricants sector. Saudi Aramco leverages its integrated refining and base oil production to dominate upstream supply security. Petromin Corporation anchors downstream distribution through its nationwide service network and OEM partnerships. Shell PLC competes in the premium synthetic segment with specialized formulations for high-temperature desert operating conditions.
Lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with viscosity grades typically spanning ISO VG 32 to VG 680 for industrial applications and SAE 0W-16 to 20W-50 for automotive engines. Engine oil commands the largest volume share due to the Kingdom's substantial passenger vehicle and commercial fleet, while synthetic base oil categories are expanding fastest as OEM drain interval specifications tighten and energy efficiency regulations intensify. The industrial machinery application segment carries elevated margin pools, particularly in mining equipment and power generation turbines where downtime costs justify premium product procurement.
SFDA oversight of chemical product safety, SASO quality mark requirements for lubricant labeling and performance claims, and MEE environmental discharge regulations collectively shape product registration pathways and formulation compliance burdens for market participants. The EU's F-Gas Regulation and REACH chemical transparency frameworks also influence export-oriented Saudi blenders supplying European OEM aftermarket channels. Stakeholders must monitor how carbon intensity disclosure requirements and circular economy mandates will alter base oil sourcing strategies and re-refining investment economics.
Market Dynamics
Aramco's upstream dominance in Group II/III base oil production is compressing margin pools for independent blenders while redirecting procurement security calculations toward captive supply arrangements.
Growth Catalysts
- Vision 2030 Industrial Corridors:Manufacturing and logistics zones at Jubail, Yanbu, and King Abdullah Economic City are generating anchored demand for hydraulic fluids and turbine oils.
- SFDA Chemical Safety Mandates:Registration requirements for lubricant formulations are accelerating product quality upgrades and pushing substandard imports toward formal channels.
- Extended Drain Interval Specifications:OEM service manuals from European and Japanese vehicle assemblers are specifying synthetic 5W-30 and 0W-20 grades for Saudi operating conditions.
Market Restraints
- Base Oil Supply Concentration:Over 70% of domestic Group II/III supply originates from Aramco's Yanbu and Jubail refineries, creating single-source dependency for independent blenders.
- Re-refining Capacity Gap:Used oil collection infrastructure remains underdeveloped across the Kingdom's western and southern provinces, limiting circular economy participation.
- Import Price Volatility:Additive packages and specialty esters priced in euros and dollars expose local formulators to currency fluctuation costs they cannot fully pass through.
Strategic Opportunities
- NEOM Industrial Zone:The giga-project's renewable energy and desalination equipment fleets will require specialized low-temperature hydraulic fluids and biodegradable greases.
- Red Sea Port Logistics:Transshipment volume growth at Jeddah Islamic Port creates demand for marine cylinder oils and stern tube lubricants serving Africa-bound vessel traffic.
- SASO Energy Efficiency Labeling:Upcoming mandatory efficiency grades for automotive lubricants will reward early movers with synthetic formulation capabilities and testing infrastructure.
Industry Challenges
- Additive Chemist Talent Scarcity:Formulation expertise for high-temperature, high-dust desert specifications resides predominantly with multinational technical centers, not local operations.
- SFDA Registration Timelines:New product approvals currently stretch 8-14 months, delaying market entry for reformulated synthetics and inhibiting rapid response to OEM specification changes.
- Used Oil Collection Integration:Fragmented generator and fleet operator maintenance practices complicate reverse logistics for re-refining feedstock security.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Lubricants Market |
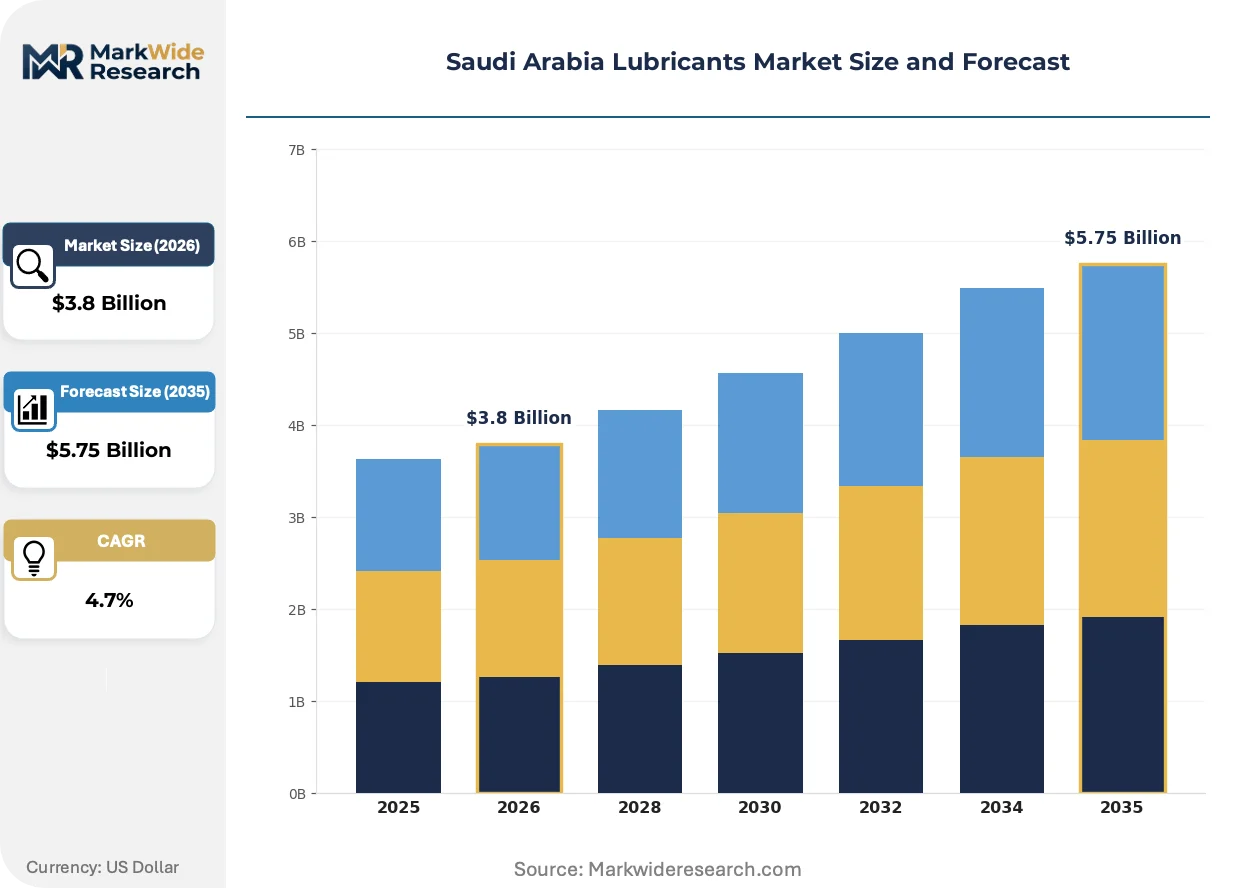
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
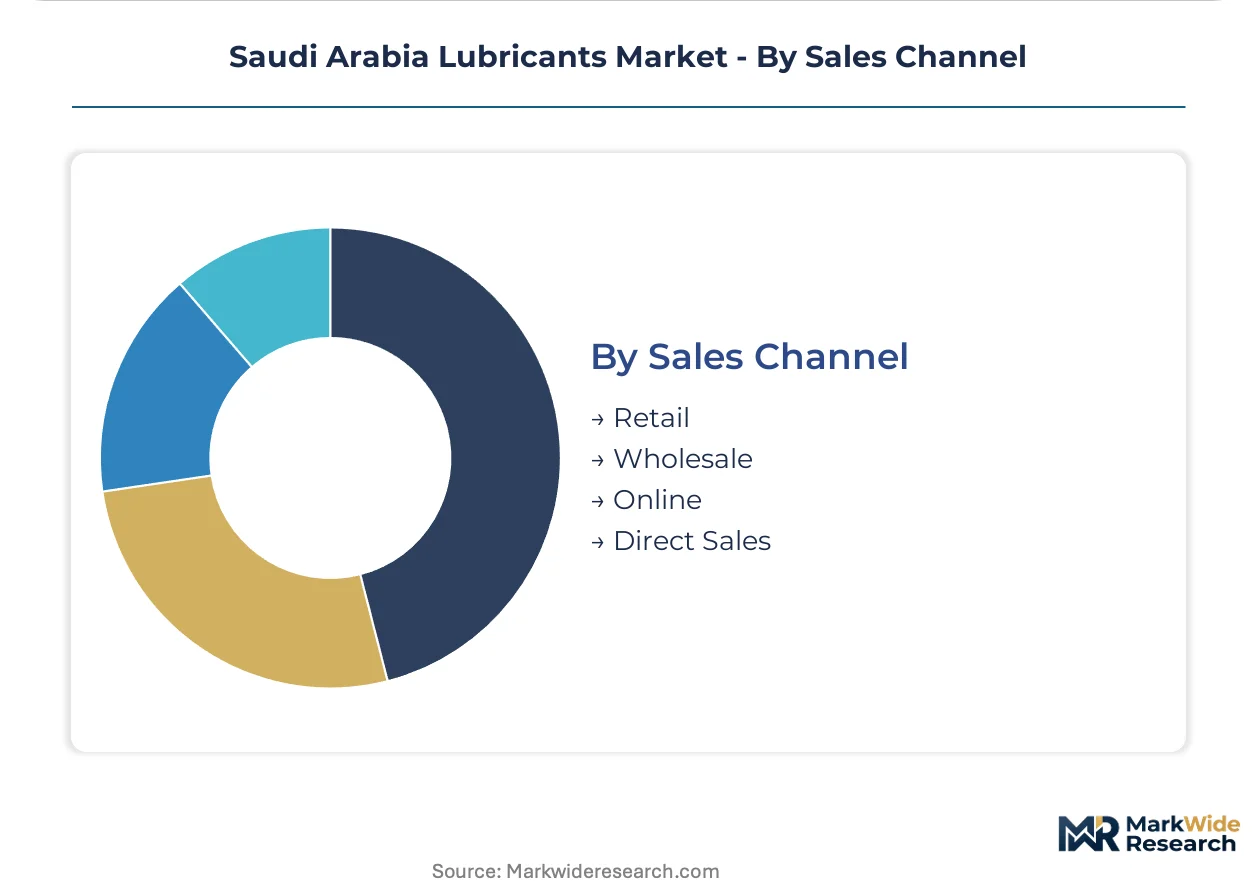
| Segmentation | Product Type: Engine Oil, Hydraulic Fluid, Gear Oil, Grease Base Oil: Mineral Oil, Synthetic Oil, Bio-Based Oil, Semi-Synthetic Oil Application: Automotive, Industrial Machinery, Marine, Aviation Sales Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | BP PLC (Castrol), Petromin Corporation, Saudi Aramco, Chevron Corporation, TotalEnergies, Shell PLC, FUCHS, Petrolube, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Lubricants Market Strategic Shifts
Formulation chemistry and procurement protocols are diverging from historical mineral-oil baselines as operating conditions intensify and regulatory transparency tightens across the value chain.
Polyalphaolefin (PAO) and gas-to-liquids (GTL) base stocks are rendering obsolete conventional Group I mineral oils in high-performance automotive and industrial segments. Mining contractors at Ma'aden phosphate and bauxite operations are specifying PAO-based hydraulic fluids for their 10,000-hour service life guarantees. The shift is compressing demand for domestically produced Group I volumes while elevating import dependency on specialty synthetic feedstocks.
SASO's alignment with EU REACH chemical disclosure frameworks is forcing reformulation of zinc-based anti-wear additives and certain friction modifiers. Blenders serving European OEM aftermarket channels must now maintain dual inventory streams: REACH-compliant export formulations and legacy domestic grades. The industrial machinery segment bears the heaviest compliance burden, as turbine and compressor oils face the most stringent substance restriction schedules.
Fleet operators at Saudi Aramco, Ma'aden, and SABIC affiliates are consolidating lubricant procurement under corporate supply agreements with technical service bundling. Independent distributors serving fragmented construction and transport fleets are losing share to direct manufacturer relationships that include oil analysis laboratories and predictive maintenance diagnostics. This concentration is most visible in the Eastern Province, where petrochemical and mining clusters have standardized on two to three approved supplier lists.
Saudi Arabia Lubricants Market Segmentation

Segmentation reveals how lubricant demand fragments across incompatible technical specifications, procurement protocols, and end-use operating conditions. Each dimension carries distinct margin structures and regulatory compliance burdens that reshape competitive positioning.
Product Type:
Mature formulations dominate volume, while emerging synthetic grades capture specification upgrades in high-stakes applications.
- Engine Oil:Formulated from Group II/III base stocks with detergent-dispersant additive packages calibrated for high-temperature desert combustion environments. Demand concentrates in Riyadh and Jeddah fleet maintenance depots as OEM drain intervals tighten toward synthetic 5W-30 and 0W-20 grades.
- Hydraulic Fluid:Anti-wear formulations with viscosity index improvers sustaining performance across 40°C to 120°C operating ranges. Eastern Province mining contractors at Ma'aden phosphate operations specify PAO-based synthetics for 10,000-hour service guarantees.
- Gear Oil:Extreme-pressure lubricants with sulfur-phosphorus additive chemistry for differentials and transmissions.
- Grease:Thickened lubricants with lithium or calcium soap bases for bearings and chassis fittings.
Engine Oil retains volume leadership; Hydraulic Fluid holds the steepest expansion curve.
Base Oil:
Cost tier stratification separates commodity mineral grades from premium synthetics with divergent supply security profiles.
- Mineral Oil:Group I and II paraffinic base stocks derived from crude vacuum distillation and hydrotreating. Yanbu and Jubail refinery output anchors domestic supply for independent blenders serving price-sensitive construction equipment operators.
- Synthetic Oil:PAO and GTL base stocks engineered for molecular uniformity and oxidative stability. NEOM giga-project procurement specifications for renewable energy equipment mandate low-temperature synthetic hydraulic fluids unavailable from domestic refiners.
- Semi-Synthetic Oil:Blended formulations combining mineral and synthetic base stocks for mid-tier automotive service fill.
- Bio-Based Oil:Vegetable oil esters and synthetic esters formulated for biodegradability in sensitive environments.
Mineral Oil commands installed base volume; Synthetic Oil is gaining share fastest as OEM specifications harden.
Application:
Customer type fragmentation separates consolidated corporate procurement from fragmented fleet operator purchasing patterns.
- Automotive:Passenger vehicle and commercial fleet lubrication spanning engine, transmission, and axle applications. Saudi Aramco and SABIC affiliate fleets consolidate procurement under corporate supply agreements with bundled oil analysis services.
- Industrial Machinery:Turbine, compressor, and mining equipment lubrication with predictive maintenance integration. Eastern Province petrochemical clusters standardize on approved supplier lists with two to three vendors capturing maintenance contract volumes.
- Marine:Cylinder and stern tube lubricants for Red Sea transshipment traffic at Jeddah Islamic Port.
- Aviation:Jet engine oils and hydraulic fluids meeting international aviation authority specifications.
Automotive maintains broadest demand footprint; Industrial Machinery carries the highest margin realization.
Sales Channel:
Geography determines channel efficiency, with urban concentration favoring direct relationships and dispersed operations requiring distributor intermediaries.
- Direct Sales:Manufacturer-to-fleet agreements with technical service bundling and laboratory diagnostics. Petromin Corporation leverages its nationwide service network to capture Aramco, Ma'aden, and SABIC procurement consolidation.
- Wholesale:Bulk distribution to independent workshops and regional distributors serving construction and agricultural equipment.
- Retail:Branded packaged lubricants through automotive parts retailers and service stations.
- Online:E-commerce platforms for DIY consumers and small fleet operators seeking price transparency.
Direct Sales captures enterprise fleet volume; Online channels are expanding most quickly among fragmented customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's lubricants trade flows reflect a net exporter position in base oils alongside substantial import dependency for high-performance additive packages and synthetic feedstocks. The Kingdom's refining complex supplies regional blenders while specialized formulations enter through Jeddah and Dammam ports.
Eastern Province
Jubail and Yanbu petrochemical clusters generate concentrated demand for turbine oils and hydraulic fluids serving SABIC affiliates and Ma'aden mining operations. SFDA chemical safety mandates require product registration for all formulations entering these industrial zones. Aramco's Yanbu refinery anchors domestic Group II/III base oil supply, with output directed to independent blenders across the Gulf Cooperation Council.
Riyadh
The capital's commercial fleet density drives engine oil consumption across passenger vehicle and heavy-duty transport segments. SASO quality mark requirements govern labeling and performance claims for all lubricants sold through retail channels. Fleet consolidation among Saudi Aramco and government contractors concentrates procurement through direct manufacturer agreements with bundled technical services.
Western Region
Jeddah Islamic Port handles transshipment volumes creating demand for marine cylinder oils and stern tube lubricants serving Africa-bound vessel traffic. MEE environmental discharge regulations shape formulation compliance for port-adjacent blending facilities. The region's underdeveloped used oil collection infrastructure limits circular economy participation compared to Eastern Province benchmarks.
NEOM Northwest
The giga-project's renewable energy and desalination equipment fleets require specialized low-temperature hydraulic fluids unavailable from domestic refiners. Vision 2030 industrial corridor incentives attract foreign blenders establishing localized formulation capabilities. Procurement specifications mandate biodegradable greases for sensitive coastal environments, diverging from standard mineral-oil baselines.
Saudi Arabia Lubricants Market Competitive Environment
On the supply side, the industry is bifurcated between integrated upstream producers and formulation specialists dependent on external base oil procurement. Aramco's captive refining capacity compresses margin pools for independent blenders while redirecting competitive dynamics toward additive chemistry differentiation and technical service bundling. Two strategic archetypes dominate: state-affiliated energy majors leveraging feedstock security, and multinational lubricant marketers deploying OEM certification relationships. Capacity expansion and strategic partnerships constitute the primary competitive moves, with direct sales agreements displacing traditional distributor networks.
Within the state-affiliated tier, Saudi Aramco and Petromin Corporation exemplify upstream-integrated positioning, while Shell PLC occupies a position among multinational formulators competing on premium synthetic specifications. These three entities anchor the competitive structure, with Aramco controlling base oil supply security, Petromin leveraging nationwide service infrastructure, and Shell deploying desert-condition formulation expertise.
| Leading Market Players |
|---|
| BP PLC (Castrol) |
| Petromin Corporation |
| Saudi Aramco |
| Chevron Corporation |
| TotalEnergies |
| Shell PLC |
| FUCHS |
| Petrolube |
| ExxonMobil Corporation |
| Others |
Value Chain & Pricing Dynamics
Yanbu and Jubail refinery clusters anchor domestic base oil capacity, concentrating upstream supply security within Aramco's integrated operations and compressing margin pools for independent blenders who must negotiate captive offtake terms or absorb import premia for synthetic feedstocks.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across the Saudi lubricants sector. Price differentiation rests on certification grade—SASO quality mark compliance versus legacy formulations—and volume scale in corporate fleet agreements. Cost compression in the mid-tier semi-synthetic segment is intensifying because Aramco's Group II/III output floods commodity channels. Fleet operators at SABIC affiliates show lowest price sensitivity due to bundled technical service contracts, while independent construction equipment contractors exhibit acute sensitivity to per-liter mineral oil pricing.
Supply Chain Analysis
EU REACH chemical disclosure frameworks and parallel SFDA registration requirements restrict additive package flows into Saudi formulation facilities. Geographic supply concentration centers on Belgium and Singapore for specialty ester feedstocks, the United States for high-performance additive chemistry, and South Korea for PAO base stocks. Raw material dependencies include zinc dialkyldithiophosphate anti-wear compounds, viscosity index improvers, and Group III+ base oils. Single-source vulnerability runs through Aramco's Yanbu and Jubail refineries, which supply over 70% of domestic Group II/III output. Distribution runs through Petromin's nationwide service network for direct fleet accounts, with wholesale channels serving fragmented independent workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi lubricants sector presents a defensive-moat story. Regulatory entrenchment via SFDA registration timelines and SASO quality mark requirements creates switching costs that protect incumbent positions while delaying challenger market entry.
For Market Incumbents: Pre-empt additive chemist talent scarcity by establishing technical centers in Dammam and Riyadh with direct recruitment from European formulation laboratories. Lock in re-refining feedstock security through reverse logistics partnerships with Ma'aden and Saudi Aramco fleet operators before collection infrastructure matures. Vertical integration into used oil collection in the Western Region closes a gap that threatens circular economy positioning. For New Entrants and Emerging Players: The Western Region's underdeveloped used oil collection infrastructure offers white-space entry for specialized re-refining operators with logistics partnerships. NEOM procurement specifications for biodegradable greases and low-temperature synthetics create a penetrable premium segment unavailable from domestic refiners. Target direct sales agreements with renewable energy EPC contractors rather than competing for saturated Eastern Province petrochemical maintenance contracts. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because formulation expertise scarcity and regulatory compliance burdens favor scaled operators with testing infrastructure and multi-year OEM certification relationships. Acquisition targets include mid-tier blenders with existing SFDA registration portfolios and established relationships with SABIC or Ma'aden procurement committees. The signal to watch is acceleration in SASO energy efficiency labeling implementation, which would force rapid synthetic formulation upgrades and strand mineral-oil-dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Aramco's Yanbu refinery expansion secures captive Group III supply for affiliated blenders. |
| Synthetic Formulation Certification Investment | Early SASO energy efficiency label compliance captures OEM specification shifts toward 0W-20 grades. |
| Used Oil Collection Infrastructure Buildout | Western Province reverse logistics partnerships feed re-refining capacity and circular economy mandates. |
| Technical Service Bundling with Direct Sales | Predictive maintenance diagnostics deepen Petromin's lock on Aramco and SABIC fleet accounts. |
| NEOM Specialized Product Localization | Biodegradable grease formulation capabilities align with giga-project coastal environmental specifications. |
Study Parameters
A spread of perspectives from lubricant formulation chemists, fleet procurement managers at SABIC affiliates, Petromin distribution channel heads, and SFDA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SASO technical standards documentation, SFDA chemical product registration databases, and Aramco refining capacity disclosures. Bottom-up demand modeling from end-use segments triangulated against top-down base oil supply estimates.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework. Segmentation dimensions modeled include product type, base oil grade tier, application sector, and sales channel structure. CAGRs derived from volume trajectory analysis incorporating OEM drain interval specification changes and Vision 2030 industrial corridor development schedules. Industry-specific forecast inputs captured SFDA registration timeline impacts and NEOM equipment procurement specification evolution.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by multinational formulators or accelerated re-refining investment by state-affiliated entities would shift outcomes. Material shifts in EU REACH substance restriction schedules or SASO energy efficiency labeling implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Egypt Lubricants Market
Lubricants
Jordan Lubricants Market
Lubricants
Global Lubrication Systems Market
Lubricants
Cutting Fluid Market
Lubricants
North America Lubricants Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
High Performance Lubricants Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Textile Machine Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
South Korea Automotive Lubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
Engine Oil and Lubricant Market