
 Jordan Lubricants Market | 2026-2036
Jordan Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Jordan Lubricants Market Foresight
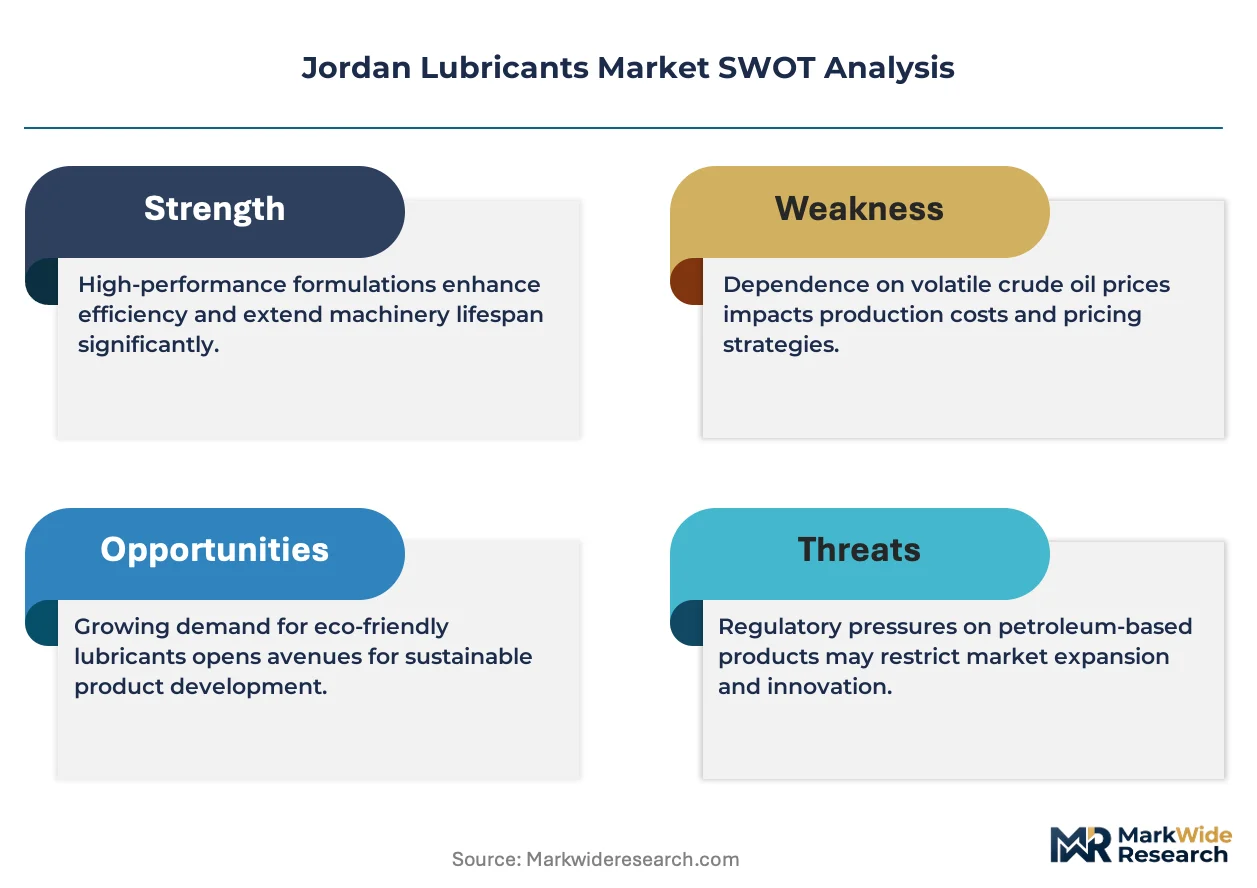
JIS K 2213 certification compliance is redrawing competitive boundaries for lubricant suppliers seeking industrial contracts in Jordan. Shell plc leverages its global blending technology network to sustain premium positioning among fleet operators in Amman. FUCHS anchors its regional reputation through specialized hydraulic oil formulations tailored to local mining equipment. JPRC competes on backward integration into base oil supply, controlling refinery-linked production at its Zarqa facility.
Lubricants are formulated mixtures of base oils and performance-enhancing additives designed to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades typically ranging from ISO VG 32 to VG 680 for industrial applications and SAE 5W-30 to 15W-40 for automotive engines. Engine Oil commands the largest volume share as Jordan's aging vehicle fleet requires frequent drain intervals, while Industrial Lubricants generate disproportionate margin contribution from long-term maintenance contracts with manufacturing plants in the Zarqa-Russeifa corridor. Bulk Containers dominate packaging for B2B supply chains serving mines and power stations, though Bottles sustain higher per-unit margins through retail automotive channels.
Jordan's Ministry of Environment enforces waste oil handling standards that elevate compliance costs for smaller blenders, while the Jordan Institution for Standards and Metrology (JISM) mandates product labeling and quality certification for all commercial lubricant sales. The central bank's foreign exchange policies indirectly shape import costs for additive packages sourced from European and Gulf suppliers. Stakeholders must monitor regulatory alignment between Jordanian standards and evolving Gulf Cooperation Council technical regulations to anticipate cross-border certification requirements.
Market Dynamics
Jordan's lubricants sector operates under tightening environmental enforcement by the Ministry of Environment, which is reshaping compliance costs and procurement criteria across industrial buyers in the Zarqa-Russeifa manufacturing corridor.
Growth Catalysts
- JISM Certification Mandate:The Jordan Institution for Standards and Metrology enforces quality labeling that filters out informal suppliers, consolidating contract flows toward certified blenders serving fleet operators in Amman.
- Synthetic Formulation Uptake:Mining equipment in phosphate extraction zones near Aqaba requires high-performance hydraulic fluids that extend drain intervals beyond conventional mineral grades.
- Waste Oil Recovery Infrastructure:Ministry of Environment protocols for used lubricant collection and re-refining create circular economy revenue streams for integrated operators with Zarqa facility access.
Market Restraints
- Additive Package Import Dependency:Jordan's central bank foreign exchange policies amplify cost volatility for performance chemical imports sourced from European and Gulf suppliers.
- Base Oil Supply Concentration:Domestic production capacity clusters at a single refinery-linked facility, creating geographic single-point vulnerability for industrial contract fulfillment.
- Extended Equipment Lifecycles:Aging automotive and industrial machinery in the Kingdom compresses premium lubricant upgrade cycles as owners defer capital replacement.
Strategic Opportunities
- GCC Regulatory Alignment:Anticipated convergence between Jordanian standards and Gulf Cooperation Council technical regulations would unlock cross-border certification for Zarqa-produced formulations.
- Power Sector Maintenance Contracts:Jordan's expanding renewable energy installations require specialized turbine and transformer oils not currently manufactured domestically.
- Direct Fleet Supply Channels:Bulk delivery partnerships with Amman-based logistics operators bypass traditional distributor markups for high-volume synthetic engine oil consumption.
Industry Challenges
- JIS K 2213 Certification Timeline:Industrial blenders face extended laboratory testing periods to achieve Japanese-standard hydraulic oil approvals required by multinational mining contractors.
- Technical Talent Scarcity:Formulation chemists with additive chemistry expertise remain concentrated in Amman, constraining regional facility expansion toward Aqaba port zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jordan Lubricants Market |
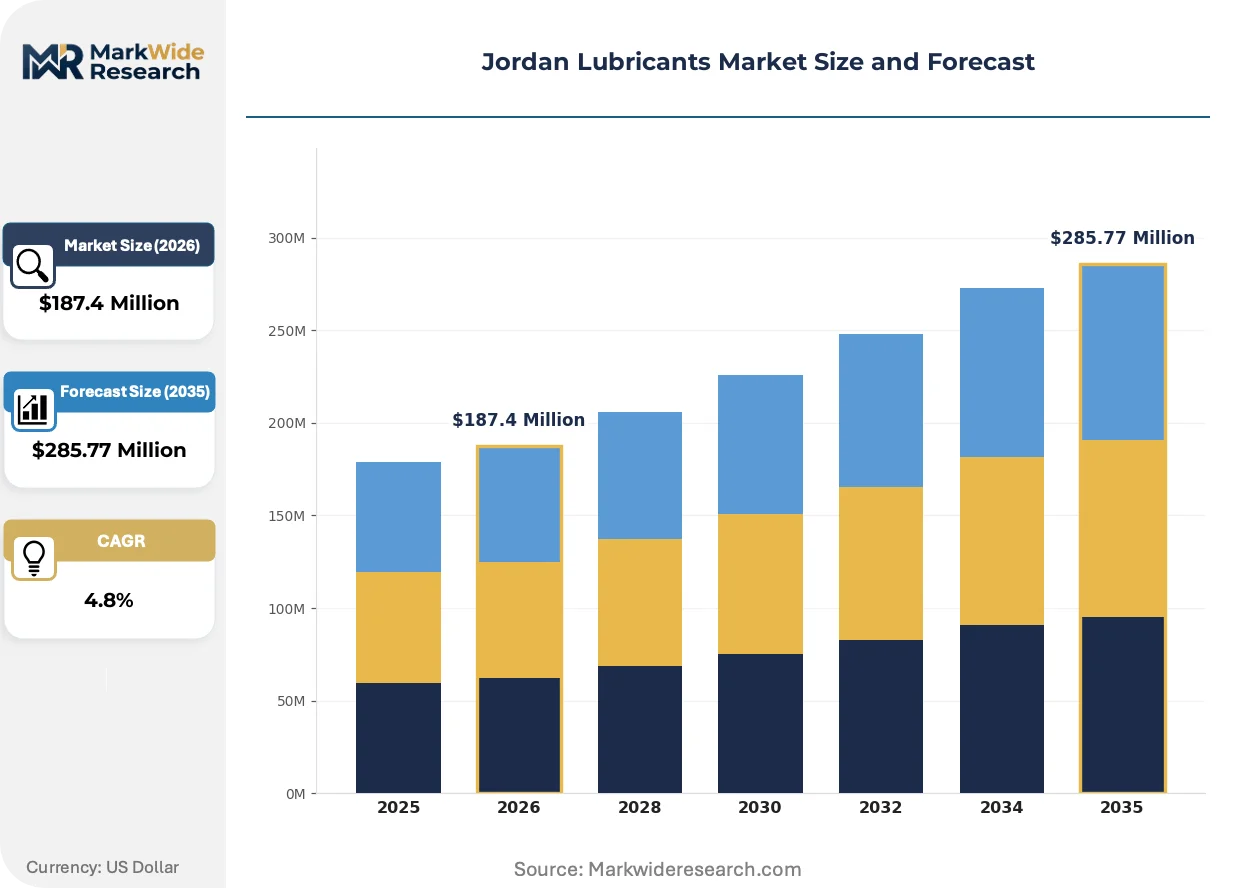
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Oil, Industrial Lubricants End User: Automotive Industry, Manufacturing Sector, Aerospace Sector, Marine Applications Packaging Type: Bulk Containers, Bottles, Drums, Pails Distribution Channel: Supermarkets, Specialized Retailers, Online Platforms, Distributors |
| Companies Covered | Exxon Mobil Corporation, FUCHS, Shell plc, ADNOC Distribution, Jordan Petroleum Refinery Company (JPRC), TotalEnergies, Chevron Corporation, Zaitak (Jordan National Lube Oil Company), Castrol Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jordan Lubricants Market Shifts & Advancements
Formulation chemistry and compliance architecture are the twin forces reshaping competitive positioning in Jordan's lubricants sector, with synthetic base stocks and environmental enforcement driving capital allocation decisions.
Group III and Group IV synthetic base oils are supplanting Group I mineral stocks in heavy-duty diesel applications across Jordan's commercial transport sector. Fleet operators running the Amman-Aqaba corridor now specify synthetic 15W-40 grades to achieve 50,000-kilometer drain intervals under desert thermal stress. This transition is compressing demand for domestically produced Group I base stocks while elevating import dependency on API Group III supply from Gulf refineries.
Jordan's Ministry of Environment waste oil handling standards are tightening collection, storage, and disposal protocols for industrial generators. The regulations mandate licensed transporters and registered re-refining destinations, eliminating informal recovery networks that previously captured 30-40% of used lubricant volume. Manufacturing plants in the Zarqa-Russeifa corridor now face audit documentation requirements that favor suppliers with integrated reverse logistics capabilities.
Long-term maintenance agreements are displacing spot procurement for industrial lubricant consumption in Jordan's mining and power generation sectors. Plant engineering departments in phosphate extraction zones now contract directly with technical service providers for fluid analysis, filtration, and scheduled replacement rather than purchasing packaged products through distributor networks. This pattern concentrates volume with blenders offering on-site laboratory support and inventory management systems.
Jordan Lubricants Market Segmentation
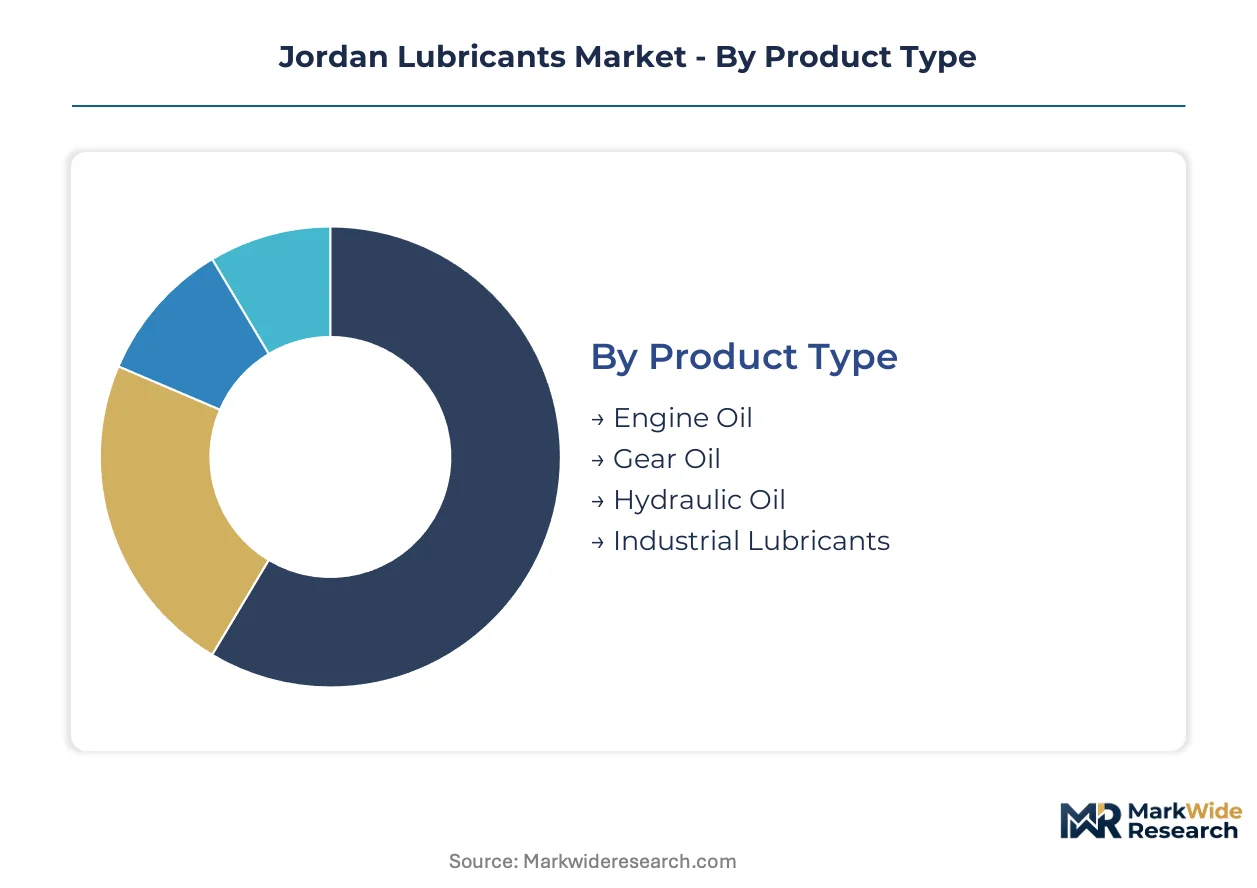
Jordan's lubricants market fragments across product chemistry, end-use equipment, packaging format, and route-to-market dimensions. Each segmentation layer reveals distinct margin profiles and compliance thresholds that shape supplier positioning in the Zarqa-Russeifa industrial corridor and Amman fleet channels.
Product Type:
Substitution pressure from synthetic formulations is redrawing competitive boundaries across mineral-based categories, with drain interval extension and thermal stability now primary procurement criteria.
- Engine Oil:Formulated from base stocks with detergent-dispersant additive packages to manage combustion byproducts and acid neutralization in internal combustion engines. Demand concentrates among Amman-based commercial fleet operators seeking extended drain intervals under desert thermal stress, though aging vehicle ownership compresses premium upgrade cycles.
- Industrial Lubricants:Encompasses compressor, turbine, and metalworking fluids formulated for continuous-duty manufacturing environments. Manufacturing plants in the Zarqa-Russeifa corridor drive disproportionate margin contribution through long-term maintenance contracts requiring on-site technical support and fluid analysis programs.
- Hydraulic Oil:Anti-wear formulations with viscosity index improvers for power transmission in mobile and stationary equipment.
- Gear Oil:Extreme-pressure lubricants with sulfur-phosphorus additive chemistry for enclosed gearboxes in mining and transport applications.
Engine Oil retains volume leadership; Industrial Lubricants holds the steepest expansion curve.
End User:
Cost tier stratification separates commodity procurement in mature sectors from premium specification requirements in capital-intensive installations.
- Manufacturing Sector:Encompasses metalworking, plastics processing, and food-grade lubrication requirements across Zarqa-Russeifa industrial clusters. Continuous production schedules mandate scheduled preventive maintenance programs with integrated fluid management services rather than spot purchasing.
- Automotive Industry:Spans passenger vehicle service shops, commercial fleet maintenance depots, and original equipment fill requirements. Fleet operators running the Amman-Aqaba corridor specify synthetic grades to achieve 50,000-kilometer drain intervals, elevating import dependency on API Group III base stocks.
- Aerospace Sector:Specialized turbine oils and hydraulic fluids for military and civilian aviation maintenance.
- Marine Applications:Stern tube lubricants and trunk piston engine oils for Red Sea port operations at Aqaba.
Automotive Industry commands the widest supplier base; Manufacturing Sector generates the highest contract renewal rates.
Packaging Type:
Volume concentration in B2B channels favors bulk logistics, while retail fragmentation sustains higher per-unit economics in smaller formats.
- Bulk Containers:Tanker and intermediate bulk container deliveries for high-volume industrial consumers with on-site storage infrastructure. Mines and power stations in phosphate extraction zones and Zarqa corridor facilities specify bulk supply to minimize handling costs and packaging waste compliance.
- Drums:200-liter steel containers serving mid-tier manufacturing plants without bulk storage capabilities. Drums bridge the logistics gap between tanker economies and retail packaging, though steel price volatility affects landed cost structures.
- Bottles:Consumer-format packaging for passenger vehicle DIY maintenance and service station retail.
- Pails:20-liter plastic containers for small fleet operators and agricultural equipment servicing.
Bulk Containers capture the highest tonnage throughput; Bottles sustain the widest retail margin spread.
Distribution Channel:
Customer type fragmentation separates technical procurement in industrial accounts from convenience-driven retail transactions.
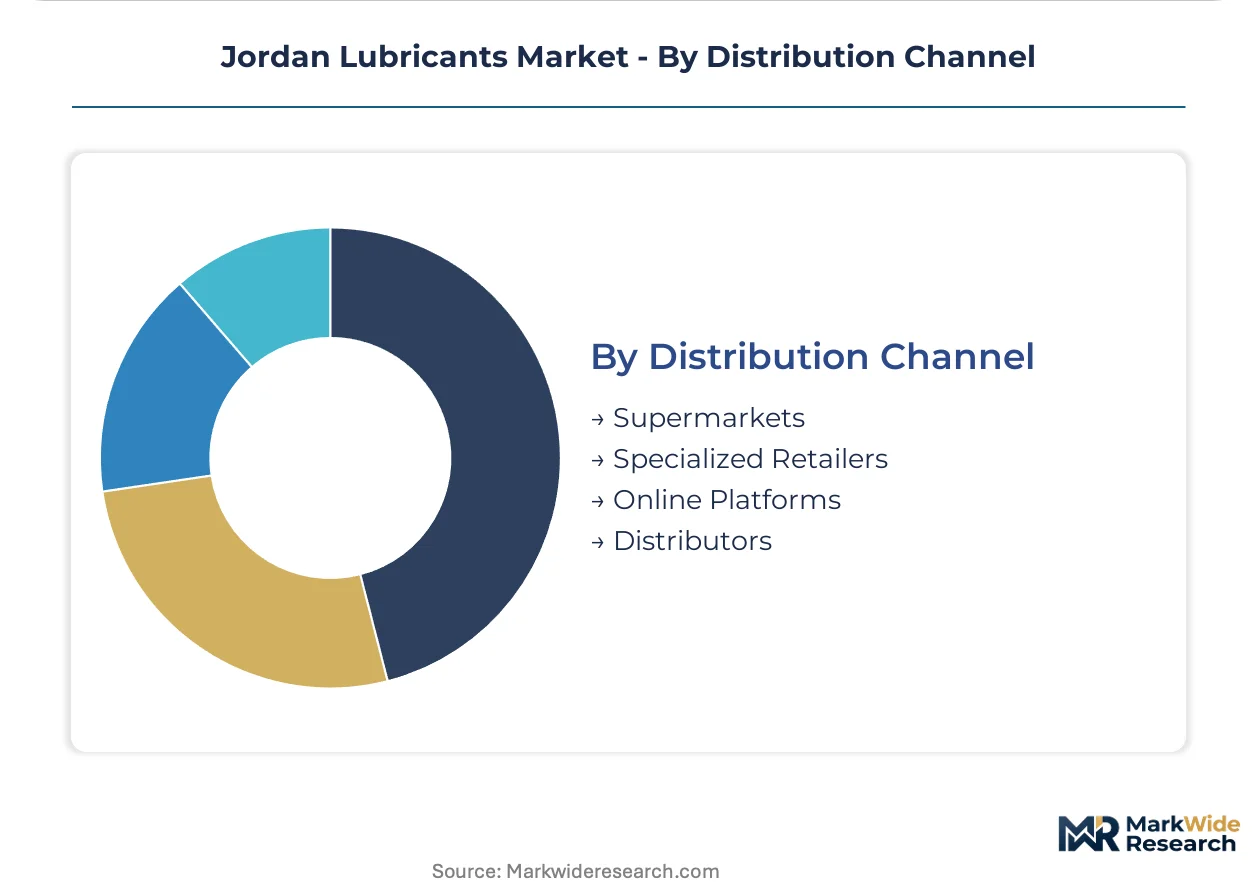
- Distributors:Independent and authorized networks carrying inventory risk and providing credit terms to smaller industrial accounts and automotive service shops. Distributor relationships dominate manufacturing sector penetration where technical consultation and just-in-time delivery offset price premiums.
- Specialized Retailers:Dedicated lubricant and automotive parts stores with formulation expertise and cross-selling capabilities. These outlets capture fleet operator loyalty through bulk order consolidation and waste oil collection program coordination.
- Supermarkets:Mass retail channels for passenger vehicle consumer brands with high recognition.
- Online Platforms:Emerging direct-to-consumer and B2B procurement channels with price transparency.
Distributors retain industrial contract concentration; Online Platforms are gaining share fastest among younger fleet procurement managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jordan's Ministry of Environment waste oil protocols and JISM certification mandates are redrawing procurement criteria across sub-regional industrial clusters, concentrating contract flows toward compliant blenders with Zarqa facility access.
Amman Metropolitan Area
Commercial fleet operators and automotive service depots drive synthetic formulation demand, with the capital's logistics corridors specifying extended-drain engine oils. The Jordan Institution for Standards and Metrology enforces quality labeling that filters informal suppliers from retail channels. Technical service providers cluster in Amman's industrial zones to support fluid analysis programs for fleet maintenance contracts.
Zarqa-Russeifa Industrial Corridor
Manufacturing plants and phosphate processing facilities require continuous-duty hydraulic and industrial lubricants with on-site inventory management. Ministry of Environment audit documentation mandates licensed waste oil collection, favoring suppliers with integrated reverse logistics. JPRC's refinery-linked production facility anchors base oil supply for regional contract fulfillment.
Aqaba Port Zone
Mining equipment in phosphate extraction zones and Red Sea marine operations demand high-performance hydraulic fluids and stern tube lubricants. The port's free trade status shapes import economics for API Group III base stocks from Gulf refineries. Bulk delivery infrastructure serves mining contractors with specialized maintenance agreements.
Irbid Northern Governorate
Agricultural equipment servicing and small-scale manufacturing generate steady demand for pail-format industrial lubricants. Central bank foreign exchange policies amplify cost volatility for additive package imports reaching northern distribution channels. Independent retailers bridge supply gaps for farming cooperatives without bulk storage capabilities.
Jordan Lubricants Market Competitive Landscape
Player mix skews toward multinational oil majors with global blending technology networks and a single domestic refinery-integrated operator. The market structure concentrates premium positioning among Gulf and European suppliers while local production controls base oil supply. Two strategic archetypes dominate: technology licensors leveraging formulation expertise and backward-integrated refiners controlling upstream feedstock. Competitive moves center on JIS K 2213 certification achievement and direct fleet supply channel development bypassing distributor markups.
Within the multinational tier, Shell plc and Exxon Mobil Corporation occupy positions anchored by global supply networks and synthetic formulation portfolios. FUCHS exemplifies the specialized industrial archetype with tailored hydraulic oil development. Among domestically integrated operators, Jordan Petroleum Refinery Company represents the refinery-linked model with captive base oil production at Zarqa. These three anchors illustrate the competitive tension between imported premium formulations and locally manufactured mineral stocks.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| FUCHS |
| Shell plc |
| ADNOC Distribution |
| Jordan Petroleum Refinery Company (JPRC) |
| TotalEnergies |
| Chevron Corporation |
| Zaitak (Jordan National Lube Oil Company) |
| Castrol Limited |
| Others |
Supply & Pricing Matrix
Group III and Group IV synthetic base oil substitution for Group I mineral stocks simultaneously redraws supply geography toward Gulf refineries and compresses pricing power for Zarqa-produced formulations. This input shift elevates import dependency while fragmenting procurement economics across synthetic premium and mineral economy tiers.
Pricing Analysis
Cost-plus contracts with Platts base oil indexation dominate industrial procurement in the Zarqa-Russeifa corridor, insulating blenders from spot volatility while compressing margin capture. Price differentiation separates JIS K 2213-certified hydraulic grades from uncertified alternatives, with fleet operators in Amman least sensitive to per-liter premiums when bundled with fluid analysis services. Cost compression in mineral-based engine oils is intensifying as aging vehicle ownership defers premium upgrades. Retail automotive channels through specialized lubricant retailers sustain the widest margin spread, while bulk B2B contracts to phosphate mines operate on thinnest economics.
Supply Chain Analysis
Saudi Arabia, the United Arab Emirates, and Kuwait anchor API Group III base oil supply for Jordan's synthetic formulation demand, with European additive packages completing the performance chemistry stack. Raw material dependencies draw from Gulf refinery output, German and Belgian additive manufacturing, and domestic Zarqa refinery Group I production. Single-source vulnerability concentrates at the Zarqa facility for mineral base stocks, creating geographic risk for industrial contract fulfillment. Distribution runs through authorized distributor networks for manufacturing accounts, direct fleet supply channels for Amman logistics operators, and specialized retailers for automotive aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Jordan's lubricants market demands substitution defense as synthetic formulation uptake threatens mineral-based incumbents with margin compression and volume displacement.
For Market Incumbents: Shield mineral-based market share by accelerating JIS K 2213 certification timelines for hydraulic oil portfolios serving phosphate extraction contractors, while deepening backward integration into waste oil re-refining infrastructure to capture circular economy revenue streams that informal collectors previously absorbed. For New Entrants and Emerging Players: Anchor in renewable energy maintenance contracts for turbine and transformer oils, a white-space segment with no domestic manufacturing presence and specialized technical requirements that favor formulation expertise over scale economies. Pursue direct supply partnerships with Aqaba port zone mining contractors bypassing Amman-based distributor markups. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors blenders with integrated re-refining capabilities and Gulf-sourced synthetic base oil relationships. Long-term viability hinges on regulatory alignment with GCC technical standards enabling cross-border certification. The signal to watch is Ministry of Environment enforcement intensity on waste oil handling protocols, which will accelerate informal supplier exit and concentrate volume with compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| JIS K 2213 Certification Investment | Unlocks multinational mining contractor contracts in phosphate extraction zones near Aqaba. |
| Waste Oil Re-refining Capacity Expansion | Captures circular economy revenue streams under tightening Ministry of Environment protocols. |
| Direct Fleet Supply Channel Development | Bypasses distributor markups for Amman-based logistics operators consuming synthetic grades. |
| GCC Regulatory Alignment Preparation | Anticipates cross-border certification convergence for Zarqa-produced formulations. |
| Renewable Energy Fluid Portfolio Launch | Addresses specialized turbine and transformer oil demand from Jordan's expanding solar installations. |
Research Methodology
Initial hypotheses were tested against primary input from lubricant plant managers, fleet procurement officers at Amman logistics operators, mining equipment maintenance directors in Aqaba, and Ministry of Environment compliance officers, then refined through secondary validation against JISM certification databases, Jordan Customs trade statistics, JPRC production disclosures, and Gulf refinery export records. Bottom-up volume estimates from end-use equipment populations and top-down value reconciliation from import-export flows were triangulated to establish market sizing.
Variance decomposition across product type, end-use sector, packaging format, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from equipment fleet growth projections, drain interval extension trends, and synthetic penetration curves by application. Industry-specific forecast inputs incorporated Ministry of Environment enforcement intensity scenarios and GCC regulatory convergence probability assessments.
Material uncertainties — central bank foreign exchange volatility, JIS K 2213 certification timeline delays, and GCC technical regulation alignment outcomes — sit outside the modeled envelope. Forecasts reflect assumptions about synthetic substitution velocity and waste oil recovery infrastructure development. Recalibration cycles align with material shifts in environmental enforcement protocols and regional trade integration milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Offshore Lubricants Market
Lubricants
Forestry Lubricants Market
Lubricants
Mexico Lubricants Market
Lubricants
Global Finished Lubricant Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Bulgaria Lubricants Market
Lubricants
Nigeria Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Europe Grease Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Global Grease Market
Lubricants
Malaysia Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Europe Lubricants Market
Lubricants
Morocco Lubricants Market
Lubricants
Spain Automotive Engine Oils Market