
 Poland Metalworking Fluids Market | 2026-2036
Poland Metalworking Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Metalworking Fluids Market Insights
Central European manufacturing capacity is reconfiguring Poland's role as a metalworking fluids demand hub. Blaser Swisslube anchors its position through high-performance neat oil specialization for precision machining. Henkel Polska Sp. z o. o. leverages localized blending operations to sustain just-in-time delivery to automotive OEM customers. FUCHS competes through backward integration into base oil refining, securing margin control across the value chain.
Metalworking fluids are engineered lubricants and coolants formulated with mineral oils, synthetic esters, or semi-synthetic bases, designed to reduce friction, dissipate heat, and prevent corrosion during machining and forming operations. These formulations typically operate at temperatures between 40°C and 80°C and contain EP additives, biocides, and emulsifiers to maintain stability in high-speed cutting environments. Cutting fluids dominate volume consumption due to their ubiquity in CNC machining centers across Polish machinery manufacturing. Cooling fluids represent the fastest-growing product category as thermal management requirements intensify in automated production lines. Neat oils command premium positioning in aerospace applications where surface finish tolerances are tightest.
Poland's metalworking fluids sector operates under REACH chemical registration mandates administered by ECHA, supplemented by national enforcement through Poland's Chief Inspectorate of Environmental Protection. The EU F-Gas Regulation and emerging CSRD sustainability reporting obligations are pressuring formulators to document carbon footprints and biodegradability profiles across their product ranges. Buyers must evaluate fluid recyclability and waste-oil handling protocols before supplier qualification windows narrow further.
Market Dynamics
REACH chemical registration mandates administered by ECHA are compressing formulation flexibility and forcing suppliers to re-engineer base oil chemistries ahead of disclosure deadlines. This regulatory pressure intersects with automotive OEM consolidation in southern Poland, where coolant system specifications are tightening simultaneously.
Growth Catalysts
- EU Green Deal carbon accounting:Machinery manufacturers in the Silesian Voivodeship now require documented biodegradability profiles, pulling advanced ester-based formulations into standard procurement cycles.
- Automotive OEM plant expansion:Southern Poland's CNC machining density is rising as Volkswagen Group and Stellantis operations scale precision component output.
- CSRD sustainability reporting:Large Polish metalworking enterprises must disclose Scope 3 chemical inputs, creating audit-trail demand for certified fluid suppliers.
Market Restraints
- Base oil supply concentration:Polish blenders depend on Group II/III base stock imports from refineries in Germany and the Netherlands, exposing margin compression during feedstock volatility.
- Biocide regulatory friction:ECHA's ongoing substance evaluation of isothiazolinone compounds threatens shelf-life stability in water-miscible coolants.
- Minimum efficient scale:Local toll blending operations face unit cost disadvantages below 500,000 liters annual throughput against integrated Central European competitors.
Strategic Opportunities
- Lesser Poland Voivodeship machinery cluster:Kraków-Tarnów manufacturing corridor shows underpenetrated neat oil demand for aerospace subcontracting growth.
- Fluid-as-a-service models:Centralized coolant management contracts with on-site recycling equipment address waste-oil handling compliance burdens.
- Dual carbon goals technology convergence:Synthetic ester formulations paired with minimum quantity lubrication systems reduce consumption volumes while maintaining cutting performance.
Industry Challenges
- Tribology specialization shortage:Polish technical universities produce insufficient lubricant formulation chemists, forcing suppliers to recruit from German and Czech talent pools.
- REACH registration timeline compression:2027 deadline clustering for substance dossier updates strains regulatory affairs capacity across mid-sized Polish formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Metalworking Fluids Market |
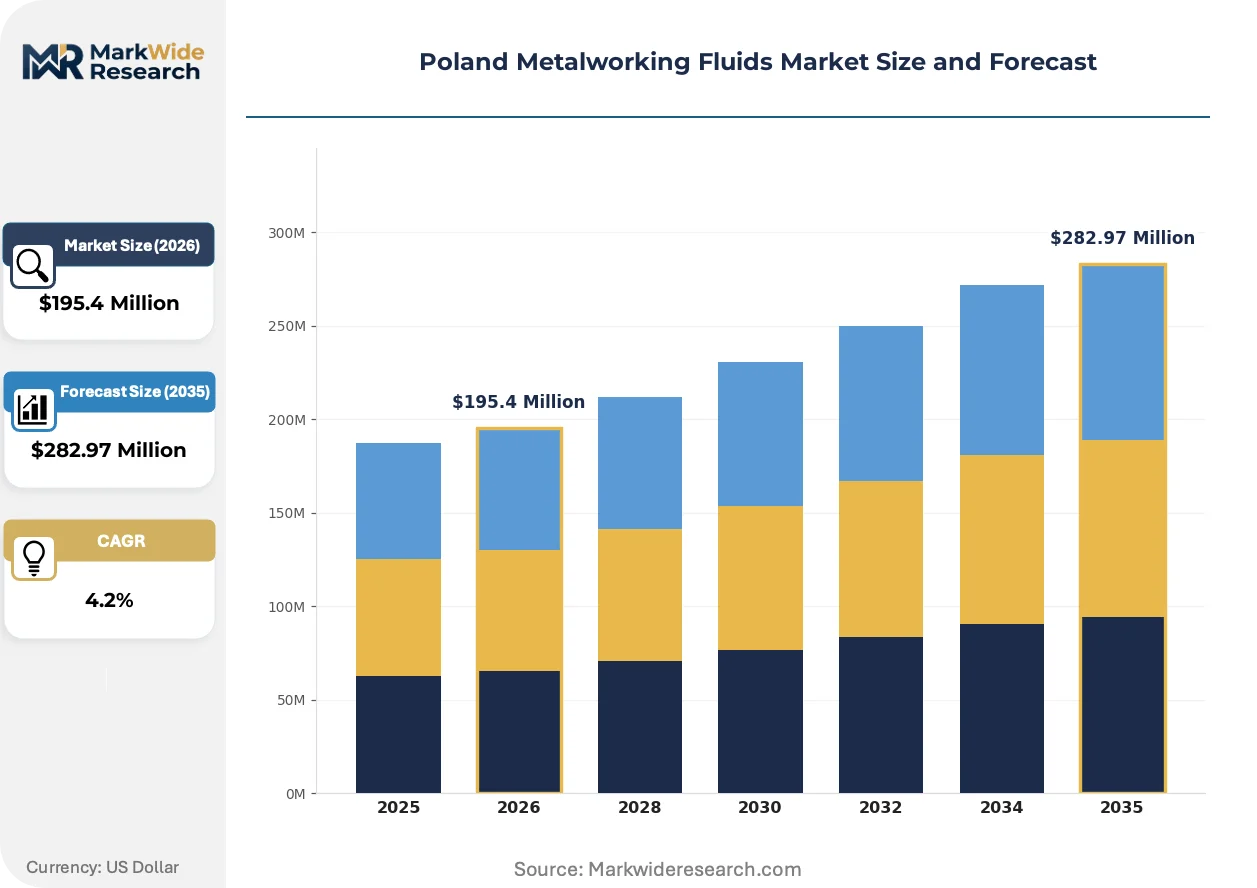
| Market Size in 2026 | $195.4 Million |
| Market Size in 2035 | $282.97 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Fluids, Cooling Fluids, Rust Preventive Oils, Neat Oils End User: Aerospace, Automotive OEM, Machinery Manufacturing, Metal Fabrication Application: Machining, Grinding, Forming, Lapping Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Exxon Mobil Corporation, Blaser Swisslube, Henkel Polska Sp. z o. o, CIMCOOL EUROPE, Quaker Chemical Corporation, Master Fluid Solutions, FUCHS, PCC Group, Oemeta Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Metalworking Fluids Market Trends and Innovations
Metalworking fluid architectures are fragmenting as end-users reject universal formulations in favor of application-specific chemistries. This specialization pressure is driving concurrent investments in synthetic base stocks, real-time contamination monitoring, and circular logistics infrastructure.
Synthetic ester metalworking fluids are hybridizing mineral oil performance with bio-based degradability credentials. Aerospace subcontractors in the Silesian cluster are adopting these chemistries fastest, replacing neat oils in titanium machining operations. The technology is hybridizing procurement categories previously split between performance and sustainability departments.
Poland's Chief Inspectorate of Environmental Protection is intensifying waste-oil tracking enforcement under national implementations of EU Waste Framework Directive revisions. Industrial fluid generators now face cradle-to-grave documentation requirements for spent coolant disposal. Small machining job shops in Łódź Voivodeship are most affected, accelerating consolidation around certified waste management contractors.
Buyer concentration among automotive tier-one suppliers is compressing switching cycles from annual to semi-annual contract reviews. Long-term supply agreements with fixed pricing are being replaced by indexed frameworks tied to base oil futures. This pattern is most visible in Volkswagen Group's Polish supplier network, where fluid procurement now sits within centralized commodity purchasing teams.
Poland Metalworking Fluids Market Segmentation
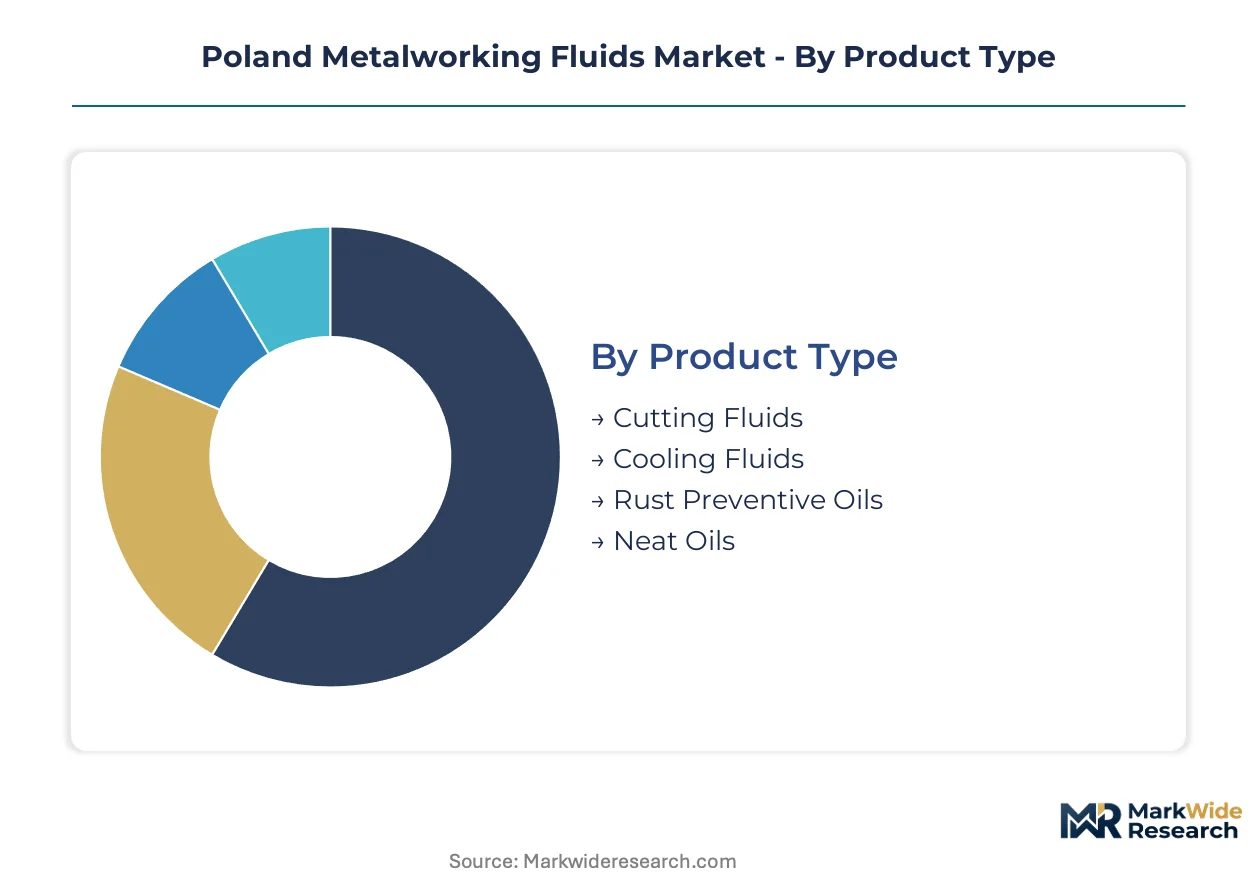
Poland's metalworking fluids market fragments along four distinct dimensions that shape procurement patterns and supplier positioning. Product type determines formulation complexity and regulatory burden. End-user concentration in southern Poland's automotive corridor drives volume aggregation. Application specificity governs technical service intensity. Distribution channel selection reflects customer scale and just-in-time requirements.
Product Type:
Cost tier stratification separates commodity emulsions from premium synthetic formulations serving precision manufacturing.
- Cutting Fluids:Water-miscible emulsions and synthetics formulated with EP additives and biocides for high-speed CNC operations. Volkswagen Group and Stellantis plants in southern Poland specify these for crankshaft and transmission component machining, with REACH compliance documentation now mandatory in supplier qualification.
- Cooling Fluids:Heat-transfer formulations operating at 40°C to 80°C, designed for thermal management in automated production lines. Silesian Voivodeship machinery clusters are expanding consumption fastest as multi-spindle machining centers proliferate, driven by CSRD carbon accounting requirements pulling advanced ester-based chemistries into standard procurement.
- Rust Preventive Oils:Corrosion inhibitors for interim metal storage and shipment protection.
- Neat Oils:Mineral oil or synthetic ester bases without water dilution, commanding premium positioning for tight-tolerance aerospace applications.
Cutting fluids command the established base. The steepest expansion runs through cooling fluids.
End User:
Application maturity varies sharply across customer industries, with automotive OEMs driving standardization while aerospace demands customization.
- Machinery Manufacturing:Broad-spectrum fluid consumption across lathes, milling centers, and gear-cutting equipment. Silesian Voivodeship clusters represent Poland's densest demand concentration, with bulk procurement patterns favoring distributors offering technical service support and waste-oil handling compliance.
- Automotive OEM:Precision coolant systems for powertrain and chassis component production. Southern Poland's Volkswagen Group and Stellantis operations are consolidating specifications and compressing supplier switching cycles to semi-annual reviews, with fluid procurement now centralized in commodity purchasing teams.
- Aerospace:Neat oil and synthetic ester demand for titanium and nickel-alloy machining with tight surface finish tolerances.
- Metal Fabrication:Lower-specification coolants for stamping, bending, and welding preparation operations.
Machinery manufacturing anchors volume throughput. Aerospace generates the highest margin per liter.
Application:
Process severity dictates additive package intensity and fluid lifecycle economics.
- Machining:Turning, milling, and drilling operations consuming the majority of metalworking fluid volume in Poland. CNC machining centers across the Kraków-Tarnów corridor are upgrading to minimum quantity lubrication systems paired with synthetic esters, reducing consumption volumes while maintaining cutting performance.
- Grinding:Precision surface and cylindrical grinding requiring fine-filtration coolant systems with tight contamination control.
- Forming:Stamping, drawing, and forging lubrication with high-pressure additive demands.
- Lapping:Ultra-precision finishing with specialized abrasive suspension fluids for optical and bearing applications.
Machining absorbs the dominant share. Grinding commands the most intensive technical service requirements.
Distribution Channel:
Customer scale and geographic concentration determine channel economics and supplier reach.
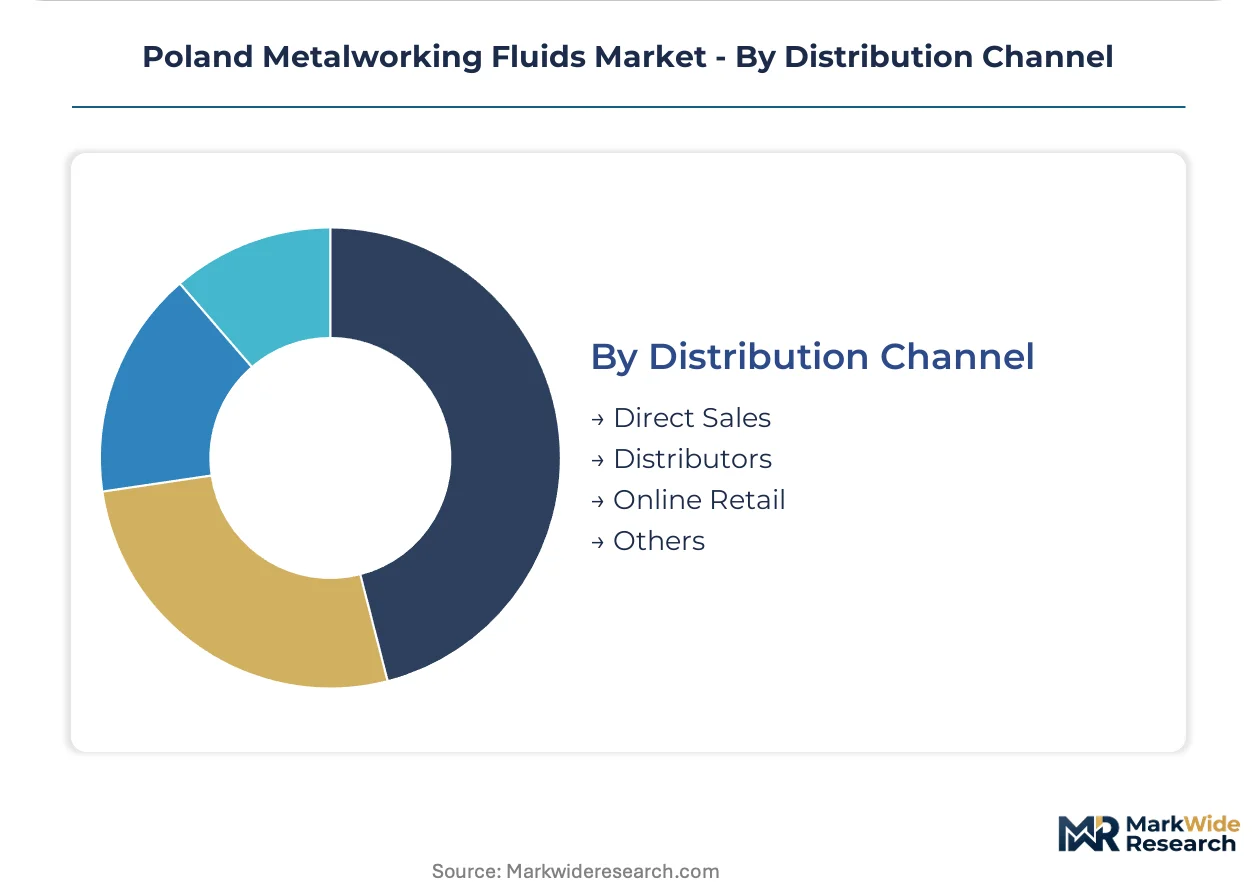
- Distributors:Regional blending and logistics operations serving mid-sized machining job shops across Łódź and Lesser Poland Voivodeships. These intermediaries bundle fluid supply with waste-oil collection services, addressing Poland's Chief Inspectorate of Environmental Protection cradle-to-grave documentation requirements for spent coolant disposal.
- Direct Sales:Supplier-managed relationships with large automotive tier-one accounts and Silesian machinery manufacturing clusters. Henkel Polska and FUCHS leverage localized blending operations for just-in-time delivery, bypassing distributor margins on high-volume contracts.
- Online Retail:Small-package sales to maintenance departments and independent job shops.
- Others:Cooperative purchasing consortia and fluid-as-a-service contract providers.
Distributors retain the broadest geographic coverage. Direct sales capture the highest-value automotive accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base oil refining and blending capacity clusters along the Rhine-Ruhr corridor and Rotterdam-Antwerp port complex, positioning Central European suppliers to serve Polish demand through integrated pipeline and barge networks. This supply architecture shapes procurement economics across the region.
Germany
Group II/III base stock production from refineries in Gelsenkirchen and Karlsruhe feeds Polish blenders through dedicated product pipelines. REACH dossier updates administered by ECHA are compressing formulation timelines for cross-border suppliers. The Cologne-Düsseldorf chemical cluster hosts lubricant R&D operations that transfer technology eastward into Silesian manufacturing zones.
Netherlands
Rotterdam's storage and blending terminals function as the primary import gateway for Polish metalworking fluid distributors sourcing specialty additives. The Dutch Emissions Authority enforces EU F-Gas Regulation compliance on refrigerant-grade base stocks crossing into Central Europe. Pernis and Moerdijk industrial zones supply ester-based synthetic formulations to aerospace subcontractors in southern Poland.
Czech Republic
Machinery manufacturing in the Ostrava-Karviná coal basin generates concentrated coolant demand that competes with Polish Silesian clusters for supplier attention. Czech Environmental Inspectorate enforcement of waste-oil tracking precedes Polish implementation timelines. The Plzeň Škoda Auto supplier network sources metalworking fluids through shared procurement consortia with Polish Volkswagen Group operations.
Slovakia
Košice's U.S. Steel operations and Bratislava's Volkswagen Group plant anchor steel and automotive metalworking fluid consumption. Slovak Trade Inspection alignment with ECHA substance evaluation creates regulatory coherence with Polish enforcement. The Žilina automotive corridor demonstrates minimum quantity lubrication adoption patterns that Polish machinery manufacturers are replicating.
Austria
Linz's voestalpine steel complex and Graz machinery manufacturing sustain premium neat oil demand that sets quality benchmarks for Polish aerospace subcontractors. Austrian Federal Ministry for Climate Action implements EU Green Deal carbon accounting requirements that Polish CSRD-reporting enterprises must mirror. The Vienna-Salzburg industrial axis channels technical service expertise into Kraków-Tarnów manufacturing corridors.
Poland Metalworking Fluids Market Competitive Landscape
Multinational integrated suppliers and regional specialists split the market between scale-driven commodity supply and application-specific technical service. Three strategic archetypes dominate: integrated petrochemical majors with captive base oil refining, European lubricant specialists with localized blending networks, and Polish distributors bundling fluid supply with environmental compliance services. Competitive intensity concentrates on backward integration into base oil supply and forward integration into waste-fluid management contracts.
Within the integrated majors tier, Exxon Mobil Corporation anchors global supply chain relationships that Polish automotive OEMs leverage for volume security. Blaser Swisslube and Henkel Polska Sp. z o. o. exemplify the European specialist archetype, occupying positions that blend technical formulation expertise with proximity to Silesian and southern Poland manufacturing clusters. These named entities represent strategic positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Blaser Swisslube |
| Henkel Polska Sp. z o. o |
| CIMCOOL EUROPE |
| Quaker Chemical Corporation |
| Master Fluid Solutions |
| FUCHS |
| PCC Group |
| Oemeta Inc. |
| Others |
Pricing and Supply Chain Analysis
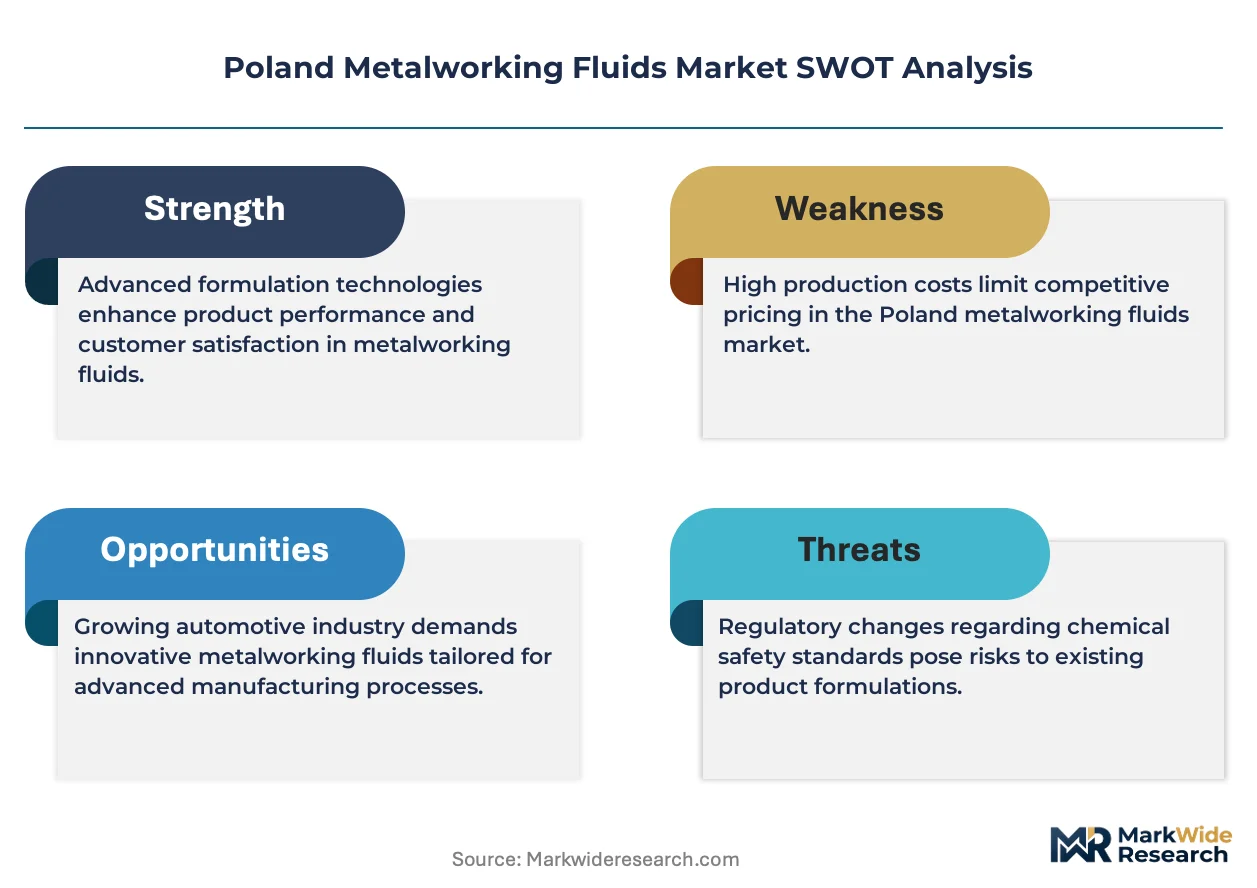
REACH registration timeline compression determines both pricing tier spreads and supply chain shape in Poland's metalworking fluids sector. ECHA-mandated substance dossier updates force formulators to absorb regulatory compliance costs into premium synthetic formulations while commodity emulsion producers face margin compression from base oil import volatility.
Pricing Analysis
REACH chemical registration mandates dictate the pricing tier structure across Poland's metalworking fluids market. Three-tier pricing structure across premium, standard, and economy levels separates synthetic ester formulations with full biodegradability documentation from semi-synthetic intermediates and mineral oil-based commodity emulsions. Price differentiation rests on certification grade for CSRD carbon accounting compliance and volume scale in automotive OEM procurement. Cost compression in standard-tier water-miscible coolants is intensifying because biocide regulatory friction threatens shelf-life stability. Small machining job shops in Łódź Voivodeship demonstrate highest price sensitivity, while aerospace subcontractors in the Silesian cluster accept premium positioning for tight-tolerance neat oils.
Supply Chain Analysis
EU F-Gas Regulation compliance requirements on refrigerant-grade base stocks limit cross-border flows from Rotterdam-Antwerp terminals into Polish blending operations. Geographic supply concentration centers on Group II/III base stock production in Germany's Gelsenkirchen and Karlsruhe refineries, specialty additive manufacturing in the Netherlands' Pernis industrial zone, and ester-based synthetic formulation capacity in Belgium's Antwerp chemical cluster. Raw material dependencies draw from mineral oil feedstocks, isothiazolinone biocide compounds, and EP additive packages. Single-source vulnerability runs through German refinery output disruptions affecting Polish blender margin stability. Distribution runs through regional distributors bundling fluid supply with waste-oil collection services for mid-sized job shops, alongside direct sales channels serving high-volume automotive tier-one accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's metalworking fluids sector is entering a cyclical recovery phase. Automotive OEM plant expansion in southern Poland drives precision coolant system demand as Volkswagen Group and Stellantis operations scale output.
For Market Incumbents: Harden backward integration into base oil refining to secure margin control against feedstock volatility from German and Dutch suppliers. Expand technical service capacity in the Silesian Voivodeship to defend against European lubricant specialists recruiting from Czech and German talent pools. Prioritize fluid-as-a-service contract development with on-site recycling equipment to lock in long-term automotive OEM relationships. For New Entrants and Emerging Players: Pursue underpenetrated neat oil demand in the Kraków-Tarnów manufacturing corridor where aerospace subcontracting growth outpaces established supplier coverage. Target minimum quantity lubrication system integration partnerships with CNC machining centers upgrading across Lesser Poland Voivodeship. Lead with synthetic ester formulations paired with documented biodegradability profiles to bypass incumbent commodity emulsion positioning. For Investors and Strategic Acquirers: CSRD sustainability reporting obligations reshape the acquisition landscape by elevating certified fluid suppliers with audit-trail capabilities into premium valuation tiers. Long-term viability concentrates on formulators with demonstrated REACH compliance infrastructure and established automotive OEM qualification status. The signal to watch is consolidation patterns among toll blending operations below efficient scale thresholds as margin pressure accelerates exit events.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive Group II/III refining secures margin control against Rotterdam import volatility for Polish blenders. |
| Fluid-as-a-Service Contract Expansion | Centralized coolant management with on-site recycling addresses Poland's Chief Inspectorate waste-tracking enforcement burdens. |
| Synthetic Ester Formulation Scale-Up | Advanced ester chemistries satisfy CSRD carbon accounting requirements in Volkswagen Group supplier networks. |
| Regional Blending Capacity Addition | Localized operations in Silesian Voivodeship compress delivery lead times for just-in-time automotive OEM procurement. |
| Technical Service Talent Acquisition | Tribology specialization recruitment from Czech and German pools closes formulation chemistry gaps in Polish universities. |
Research Methodology
Operator-level perspectives from plant managers at Silesian machinery manufacturing clusters, procurement leads at automotive OEM facilities, technical R&D directors at European lubricant specialists, and distribution channel partners across Łódź and Lesser Poland Voivodeships anchored the qualitative base. Secondary validation drew from ECHA substance registration databases, Poland's Chief Inspectorate of Environmental Protection enforcement records, EU F-Gas Regulation implementation documents, and customs trade data on base oil imports. Bottom-up volume modeling across product type, end user, application, and distribution channel segments was triangulated against top-down macroeconomic indicators for Central European manufacturing output.
Scenario-bracketing around regulatory implementation timelines and automotive production cycle variations framed the analytical approach across the projection horizon. Segmentation dimensions modeled encompassed product formulation complexity, end-use industry maturity, process severity requirements, and customer scale logistics patterns. CAGRs were derived from trend extrapolation of historical consumption intensities adjusted for technology substitution effects in minimum quantity lubrication adoption and synthetic ester penetration rates.
Sensitivities concentrate around REACH registration deadline clustering, biocide substance evaluation outcomes from ECHA, and automotive OEM supplier consolidation patterns. Forecasts reflect assumptions on regulatory enforcement intensity and technology adoption curves without predetermined policy outcomes. Material shifts in EU Green Deal carbon accounting implementation timelines or base oil refinery capacity allocation decisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Aerospace Lubricant Market
Lubricants
Polyurea-Based Greases Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
Open Gear Lubricants Market
Lubricants
Global Lubricants Market
Lubricants
Qatar Lubricants Market
Lubricants
America Lubricants Market
Lubricants
Singapore Commercial Vehicles Lubricants Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Hydraulic Fluids and Process Oil Market
Lubricants
Jordan Lubricants Market
Lubricants
Global Group IV and V Lubricants Market