
 UK Automotive Actuators Market | 2026-2036
UK Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
UK Automotive Actuators Market Analytics
Electrification of vehicle architectures is tilting actuator design toward high-precision electric motor-driven units with integrated position sensing. Continental AG leverages its powertrain electronics integration to compete across electric power steering and thermal management actuation. Robert Bosch GmbH anchors its position through in-house production of brushless DC motor cores and control algorithms. ZF Friedrichshafen AG specializes in mechatronic brake actuators that bridge hydraulic and fully electric braking systems.
Automotive actuators are electromechanical or fluid-powered devices that convert control signals into precise mechanical motion to operate valves, throttles, brakes, and transmission components, typically achieving positional accuracy within fractions of a millimeter and response times under 50 milliseconds. Their primary purpose is to enable automated, real-time control of vehicle subsystems without direct mechanical linkage to the driver. Electric actuation technology leads the technology dimension as OEMs phase out pneumatic auxiliary systems in favor of compact, software-controllable electric units. Brake actuators command the largest product type share due to mandatory integration with electronic stability control and autonomous emergency braking systems. The electric vehicles application segment generates the fastest growth trajectory as battery thermal management and active aerodynamic systems multiply actuator counts per platform.
The UK Department for Transport enforces vehicle type approval aligned with UN ECE regulations, while the Vehicle Certification Agency administers emissions and safety conformity assessments that directly specify actuator performance thresholds. The EU-UK Trade and Cooperation Agreement preserves alignment with REACH substance restrictions affecting seal and coating materials used in actuator manufacturing. Stakeholders must monitor how the UK's evolving automotive sector battery regulations and potential divergence from EU type-approval frameworks reshape supplier qualification requirements and component sourcing strategies.
Market Dynamics
The UK automotive actuators market is being fundamentally restructured by the government's zero-emission vehicle mandate, which is forcing OEMs to redesign thermal management and drivetrain architectures around high-precision electric actuation systems.
Growth Catalysts
- Euro 7 Emissions Standards:These tightening requirements are mandating precision control over exhaust gas recirculation and selective catalytic reduction systems, expanding actuator deployment across internal combustion engine platforms.
- Battery Thermal Management:Electric vehicle architectures require actuators for coolant valve control, refrigerant flow modulation, and active grille shutter systems to optimize range and charging speed.
- West Midlands Manufacturing Corridor:England's concentrated OEM assembly footprint and Tier-1 supplier clustering generate procurement scale effects that reduce unit costs and accelerate technology validation cycles.
Market Restraints
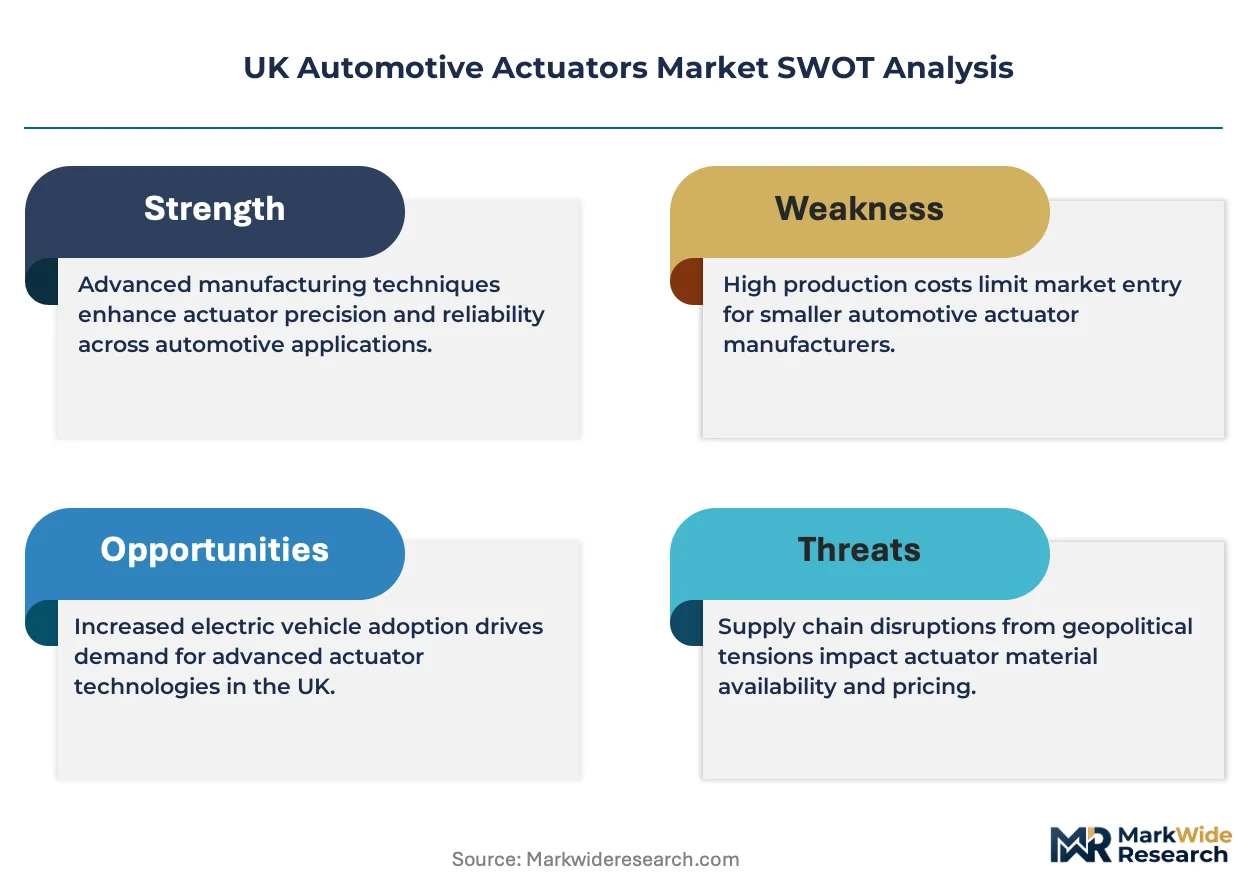
- Rare Earth Magnet Supply Concentration:Brushless DC motor cores depend on neodymium and dysprosium sourced primarily through Chinese processing facilities, exposing UK manufacturers to export restriction risks and price volatility.
- REACH Compliance Costs:The EU-UK Trade and Cooperation Agreement preserves alignment with ECHA substance restrictions on seal materials and coatings, forcing reformulation of actuator housings and gaskets at elevated R&D expense.
- Hydraulic-to-Electric Transition Friction:Brake actuator suppliers maintaining dual technology lines face duplicated tooling and inventory carrying costs while OEMs extend platform life cycles for legacy hydraulic systems.
Strategic Opportunities
- Scottish Battery Supply Chain:Emerging cell manufacturing facilities in Scotland's Central Belt create proximity advantages for thermal management actuator suppliers seeking co-location with battery pack assembly operations.
- Active Aerodynamics Integration:Convergence of electric actuation with sensor fusion algorithms enables deployable spoiler, grille, and underbody panel systems that optimize drag coefficients in real-time driving conditions.
- Vehicle Certification Agency Streamlining:Potential administrative efficiency gains in UN ECE type approval processes could compress supplier qualification timelines for innovative actuator designs.
Industry Challenges
- Mechatronics Engineering Talent Scarcity:The intersection of mechanical design, embedded software, and motor control algorithms requires specialized expertise that UK technical universities are not producing at sufficient scale.
- Legacy Platform Integration Complexity:Tier-1 suppliers must engineer backward-compatible actuator interfaces for vehicle architectures designed before electric powertrain dominance, constraining design optimization.
- Functional Safety Certification Burden:ISO 26262 ASIL-D compliance for brake and steering actuators demands extensive fault injection testing and documentation, extending development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Automotive Actuators Market |
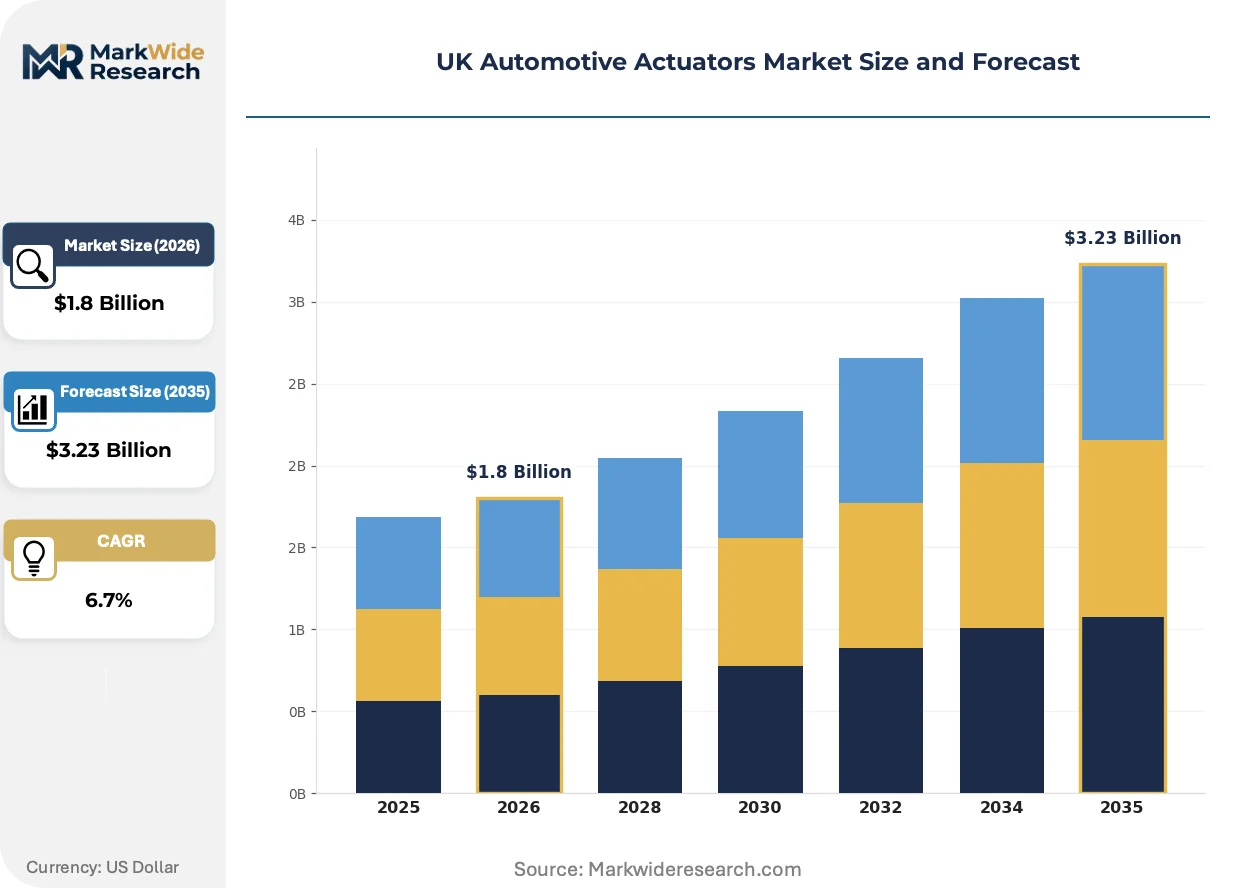
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brake Actuators, Throttle Actuators, Transmission Actuators, Fuel Actuators Technology: Hydraulic, Pneumatic, Electric, Mechanical Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Off-Road Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Continental AG, Robert Bosch GmbH, Hella KGaA Hueck & Co., Wabco Holdings Inc., Sonceboz SA, Denso Corporation, ZF Friedrichshafen AG, BorgWarner Inc., Valeo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Automotive Actuators Market Evolving Landscape
Actuator technology in the UK market is converging around intelligent, software-defined units that integrate position sensing, diagnostics, and predictive maintenance capabilities directly into the electromechanical package.
Integrated smart actuators combining brushless DC motors with Hall-effect position sensors and CAN-FD communication protocols are collapsing the traditional separation between motion control hardware and vehicle network electronics. OEMs adopting these units for thermal management and active aerodynamics are eliminating separate control module procurement and wiring harness complexity. This integration is collapsing supplier tier structures as actuator manufacturers assume responsibilities previously held by ECU vendors.
The UK Department for Transport's alignment with UN ECE regulations is enforcing cybersecurity management system requirements for actuators connected to vehicle safety systems. This policy mandate is compelling suppliers to implement hardware security modules and secure boot architectures that were previously optional features. Brake actuator and steer-by-wire segments are investing most heavily in penetration testing and threat modeling to satisfy Vehicle Certification Agency audit protocols.
Fleet operators and leasing companies are consolidating procurement decisions at the national level rather than delegating to individual dealership networks. This buyer concentration is shifting pricing power toward volume aggregators who demand extended warranty terms and remote diagnostic capabilities as standard features. England's commercial vehicle sector exhibits this pattern most prominently, with large logistics firms specifying actuator data logging requirements directly in supply contracts.
UK Automotive Actuators Market Segmentation
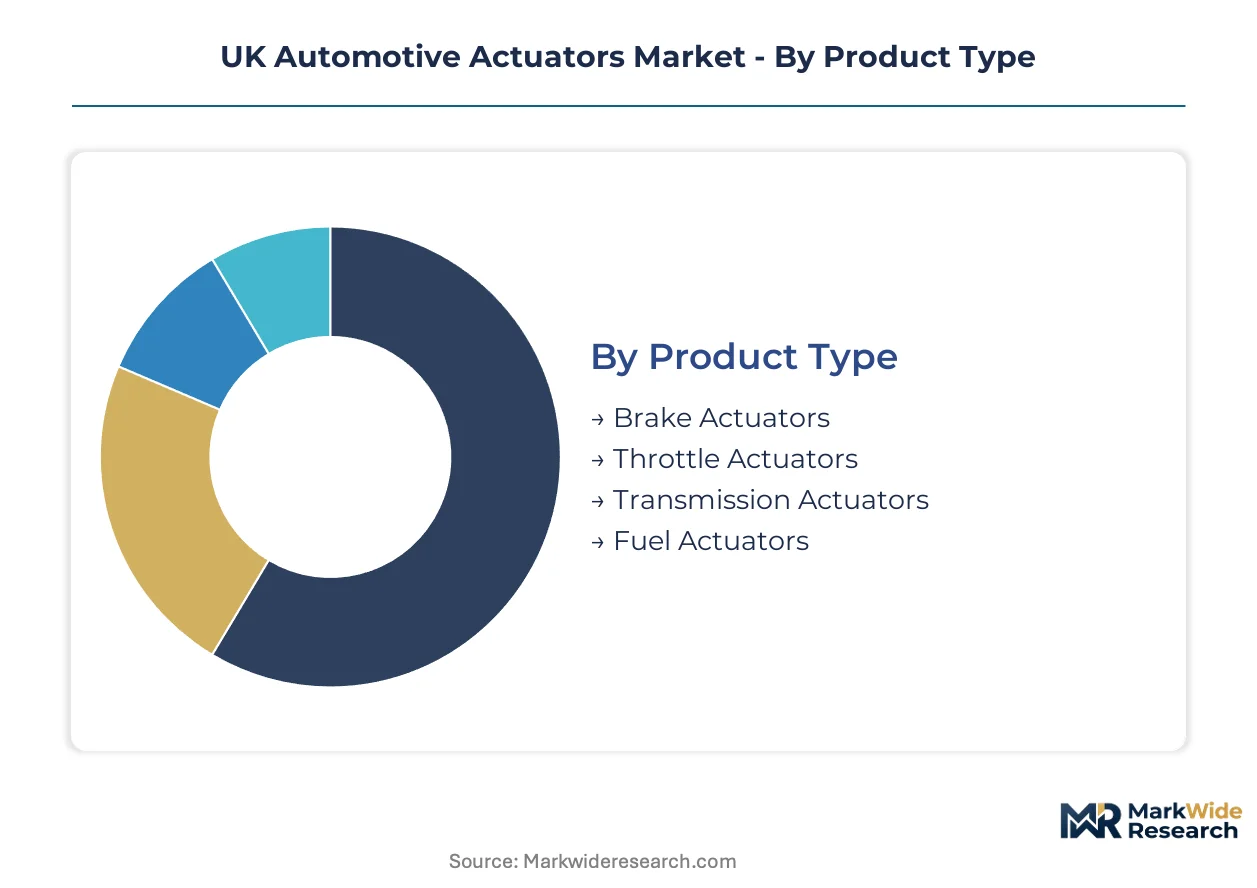
Segmentation of the UK automotive actuators market reveals how electrification is fragmenting traditional procurement patterns. OEMs now specify actuators across incompatible thermal management, braking, and powertrain architectures that demand distinct technical qualifications from suppliers.
Product Type:
After-sales service intensity varies sharply across actuator categories, with brake and throttle units requiring periodic recalibration that aftermarket providers monetize through diagnostic tooling subscriptions.
- Brake Actuators:Electromechanical units integrating motor-driven piston control with ABS modulation valves. Demand concentrates in England's West Midlands corridor where Jaguar Land Rover and Stellantis assembly plants mandate ISO 26262 ASIL-D certification for electronic stability control integration.
- Throttle Actuators:Brushless DC motor assemblies with Hall-effect position feedback enabling drive-by-wire accelerator control. Procurement is accelerating from Tier-1 suppliers serving Euro 7 emissions compliance programs that demand precision air-fuel mixture management.
- Transmission Actuators:Solenoid and motor-driven units for dual-clutch and automated manual gearboxes.
- Fuel Actuators:High-pressure direct injection control valves and common-rail pressure regulators.
Brake actuators hold the largest share; momentum sits with throttle actuators as drive-by-wire architectures displace mechanical linkages.
Technology:
Cost tier stratification separates premium electric units from legacy hydraulic systems that OEMs maintain for platform continuity.
- Electric:Brushless DC motor cores with integrated position sensing and CAN-FD communication. Demand concentrates in battery electric vehicle programs where thermal management valve control and active grille shutters multiply actuator counts per platform.
- Hydraulic:Fluid-powered piston and valve systems with proven durability in heavy braking loads. Procurement persists in commercial vehicle segments where fleet operators prioritize field-serviceability over electronic complexity.
- Pneumatic:Compressed-air-driven units for auxiliary systems and legacy commercial vehicle applications.
- Mechanical:Cable and linkage systems retained in cost-optimized vehicle segments.
Electric technology commands the premium tier; hydraulic systems retain volume in commercial vehicle retrofit markets.
Application:
Customer type differentiation separates fleet procurement specifications from retail vehicle feature bundling.
- Electric Vehicles:High-density actuator deployment across battery thermal management, active aerodynamics, and electric power steering. Demand is climbing the fastest as the UK government's zero-emission vehicle mandate forces platform redesigns around precision electromechanical control.
- Passenger Vehicles:Conventional internal combustion and mild-hybrid architectures with distributed actuator networks. Procurement concentrates with OEMs balancing Euro 7 emissions hardware against platform cost targets.
- Commercial Vehicles:Heavy-duty braking and transmission actuation for logistics and construction fleets.
- Off-Road Vehicles:Ruggedized hydraulic and electric units for agricultural and mining equipment.
Passenger vehicles retain volume dominance; electric vehicles are gaining share fastest on regulatory mandate acceleration.
End User:
Supply concentration shapes how actuator manufacturers route through direct OEM contracts versus Tier-1 system integrator channels.
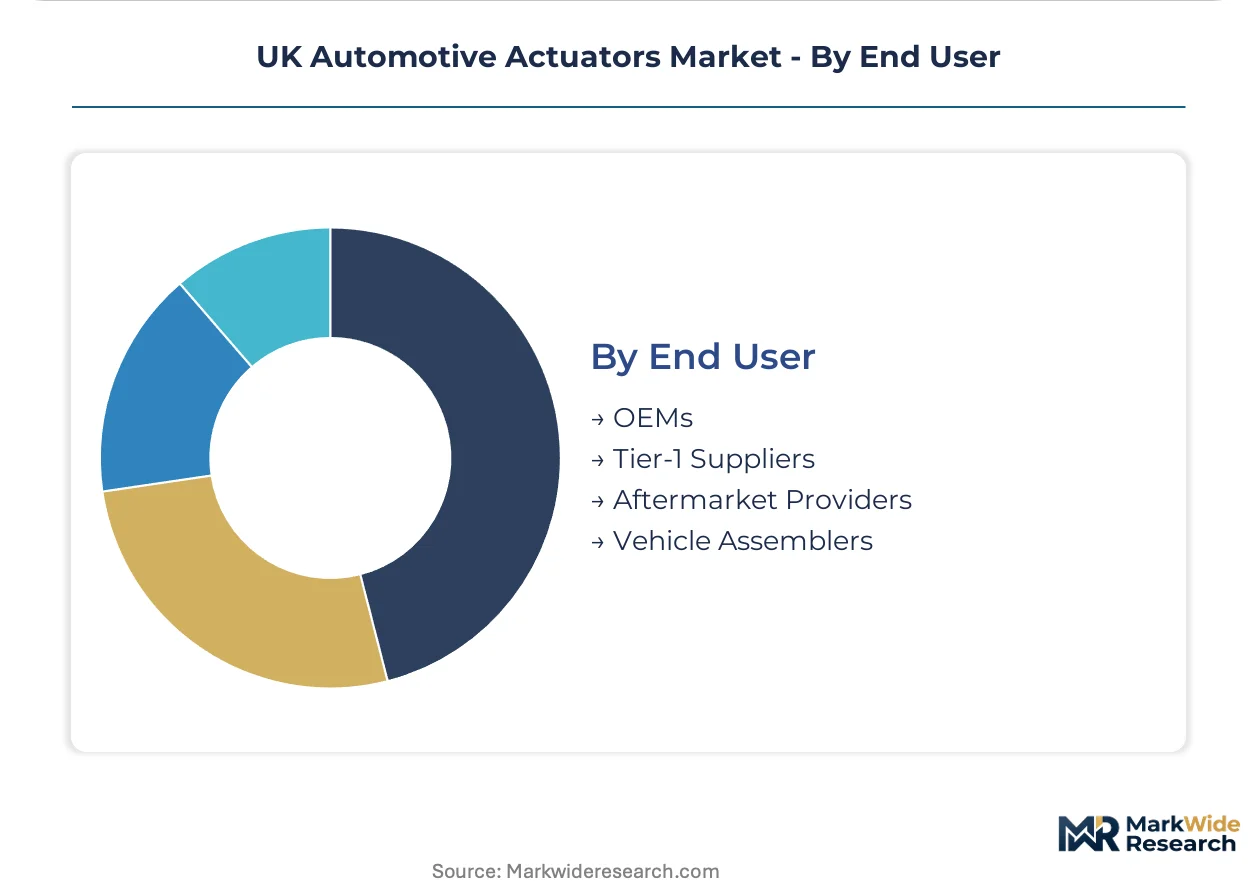
- OEMs:Direct procurement of safety-critical brake and steering actuators with proprietary specification control. Vehicle assemblers in the West Midlands corridor are consolidating supplier panels to reduce qualification overhead for electric platform launches.
- Tier-1 Suppliers:System integrators purchasing actuators for incorporation into braking, transmission, and thermal management modules. Bosch and Continental leverage captive actuator production to defend module-level pricing power.
- Aftermarket Providers:Independent distributors serving collision repair and wear-item replacement demand.
- Vehicle Assemblers:Contract manufacturers and niche producers with limited vertical integration.
Tier-1 suppliers capture the largest procurement volume; momentum sits with OEM direct channels as platform electrification collapses system boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK automotive actuators market operates with a structural trade deficit in precision electromechanical components, importing brushless DC motor cores and rare earth magnets while exporting finished actuator assemblies to EU assembly plants. This exchange pattern concentrates manufacturing investment in England's industrial corridors where Tier-1 supplier clustering reduces logistics costs for just-in-time delivery to OEM plants.
England
The West Midlands automotive corridor generates the dominant share of UK actuator procurement, with Jaguar Land Rover and Stellantis assembly plants mandating ISO 26262 ASIL-D certification for brake and steering actuators. The Department for Transport enforces UN ECE type approval alignment that specifies performance thresholds for electronic stability control integration. Birmingham and Coventry anchor supplier qualification activity, where Bosch and Continental maintain module integration facilities serving platform electrification programs.
Scotland
Emerging battery cell manufacturing in Scotland's Central Belt is creating co-location opportunities for thermal management actuator suppliers. The Scottish Government's automotive transition fund supports supply chain localization around emerging cell production facilities. Glasgow and Edinburgh corridor development zones are attracting precision actuator manufacturers seeking proximity to battery pack assembly operations for coolant valve control systems.
Wales
Commercial vehicle actuator demand concentrates in South Wales, where fleet operators specify hydraulic brake systems for heavy-duty logistics applications. The Welsh Government's advanced manufacturing strategy targets supplier diversification for electric powertrain components. Cardiff and Newport industrial zones host Tier-2 fabricators serving brake actuator refurbishment and aftermarket distribution channels.
Northern Ireland
Agricultural and off-road vehicle actuator procurement anchors Northern Ireland's market segment, with ruggedized hydraulic units dominating construction equipment specifications. The region's alignment with UK vehicle certification requirements preserves access to GB assembly plant supply contracts. Belfast and Lisburn manufacturing zones specialize in cost-optimized mechanical actuator production for export to Irish Republic agricultural equipment assemblers.
UK Automotive Actuators Market Competitive Landscape
On the supply side, the industry is consolidating around integrated system providers that combine captive actuator production with module-level assembly. Continental AG and Robert Bosch GmbH exemplify this structure through in-house manufacturing of brushless DC motor cores and control algorithms. Three strategic archetypes dominate: diversified automotive suppliers with powertrain electronics integration, specialized mechatronics firms focused on brake and thermal applications, and regional component fabricators serving aftermarket channels. Competitive dynamics center on strategic partnerships for rare earth magnet sourcing and capacity expansion for electric vehicle platform qualification.
Within the diversified supplier tier, Continental AG and Robert Bosch GmbH occupy positions defined by powertrain electronics integration and captive motor core production. ZF Friedrichshafen AG exemplifies the mechatronics specialist archetype, bridging hydraulic and electric braking system transitions. These Germany-based corporations anchor the premium tier through module-level supply relationships with UK OEM assembly plants, where qualification timelines and functional safety certification requirements create substantial entry barriers for emerging competitors.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Hella KGaA Hueck & Co. |
| Wabco Holdings Inc. |
| Sonceboz SA |
| Denso Corporation |
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| Valeo |
| Others |
Value Network & Pricing Analysis
England's West Midlands automotive corridor concentrates brushless DC motor core production capacity, and this geographic clustering directly amplifies pricing power for Tier-1 suppliers serving Jaguar Land Rover and Stellantis assembly plants. OEM procurement consolidation around ISO 26262 ASIL-D certified brake actuators reinforces supplier leverage in contract negotiations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by functional safety certification grade and volume scale commitments. Cost compression in the standard tier is intensifying because captive motor core production at Bosch and Continental eliminates third-party margin stacking. Fleet procurement aggregators exhibit highest price sensitivity, while safety-critical brake actuator buyers demonstrate lowest elasticity due to qualification switching costs.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard supply-chain finance facilities that Tier-1 suppliers use to manage working capital through rare earth magnet inventory cycles. Brushless DC motor cores draw from neodymium and dysprosium processing concentrated in China, with seal materials sourcing from Germany and Japan. Single-source vulnerability in Chinese rare earth refining creates structural exposure to export restriction risks. Distribution runs through just-in-time module integration facilities co-located with West Midlands OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK automotive actuators market represents an early-cycle expansion story, with the government's zero-emission vehicle mandate accelerating platform redesigns that multiply actuator counts per battery electric vehicle. Electrification penetration is climbing fastest in thermal management applications.
For Market Incumbents: Insulate margin structures by deepening backward integration into rare earth magnet sourcing partnerships and expanding captive brushless DC motor core capacity in the West Midlands corridor. The emergence of Scottish battery cell manufacturing threatens established supplier geography advantages, making proximity investment to Jaguar Land Rover and Stellantis qualification timelines the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in Scotland's Central Belt thermal management segment, where emerging battery pack assembly operations lack established actuator supplier relationships. The aftermarket recalibration services channel offers the most penetrable entry point, with diagnostic tooling subscriptions providing recurring revenue anchoring against OEM direct procurement consolidation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because Euro 7 and UN ECE cybersecurity mandates embed actuator suppliers into vehicle safety architectures with decade-long qualification cycles. Acquisition targets should display mechatronics engineering depth spanning mechanical design and embedded motor control. The signal to watch is Scottish Government automotive transition fund disbursement velocity as a proxy for supply chain localization commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Magnet Supply Agreement | Secures neodymium and dysprosium access against Chinese export restriction volatility. |
| Software-Defined Actuator Investment | Integrates predictive maintenance capabilities demanded by fleet operator procurement contracts. |
| Scottish Manufacturing Footprint | Positions thermal management actuators adjacent to emerging battery cell production facilities. |
| ISO 26262 ASIL-D Certification Program | Enables brake actuator supply to Jaguar Land Rover and Stellantis safety-critical platforms. |
| Active Aerodynamics Partnership | Combines electric actuation with sensor fusion for deployable spoiler and grille systems. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distributor operations heads, and Vehicle Certification Agency technical assessors provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation from UN ECE regulatory filings, Department for Transport type approval databases, IHS Markit vehicle production data, and SEC disclosures from listed automotive suppliers. Bottom-up actuator deployment modeling triangulated against top-down OEM platform electrification commitments.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with segmentation dimensions spanning propulsion architecture, vehicle class, content per vehicle, and regional production cluster. CAGRs were derived from actuator count per platform trajectories and OEM electrification timeline assumptions. Forecast inputs incorporated rare earth magnet price volatility indices and Scottish battery supply chain development milestones.
Stress conditions across neodymium export restriction severity, Euro 7 implementation timing, and Scottish cell manufacturing ramp speed were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory alignment and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
Automotive Piston System Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
France Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Coolant Aftermarket Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Road Snow Melt Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Global Plastics for Passenger Cars Market