
 Automotive Commutator Market | 2026-2036
Automotive Commutator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Commutator Market Analytics
East Asian copper processing capacity is expanding to serve precision-machined commutator demand for electrified powertrains. Denso leverages vertical integration from raw copper to finished assemblies, sustaining cost discipline across its supplier network. Continental anchors European demand through specialized high-temperature commutator lines for hybrid applications. Nidec competes aggressively in brushless motor-integrated designs, consolidating its position in Japanese OEM supply chains.
An automotive commutator is a rotary electrical switch composed of copper segments insulated by mica or polymer resin, engineered to reverse current direction within DC and universal motor armatures while maintaining continuous torque output under thermal and mechanical stress. Manufacturing employs precision turning, silver-copper alloying, and vacuum pressure impregnation to achieve segment-to-segment voltage withstand above 500V and rotational stability beyond 15,000 rpm. Brushless commutator configurations dominate technical roadmaps as permanent magnet motor architectures displace brushed designs in electric vehicle traction systems, though high-performance brushed variants retain margin pools in racing and specialty aftermarket channels where cost sensitivity remains lower than mass-production EV programs.
NHTSA fuel economy standards and EPA emissions benchmarks in the United States compel OEMs to specify commutators with reduced electrical losses and extended brush life, directly influencing material selection and testing protocols. REACH substance restrictions and EU Green Deal circularity requirements in Europe mandate lead-free copper alloys and documented end-of-life recyclability, adding compliance layers for exporters. Stakeholders must monitor the divergence between brushless technology migration and residual internal combustion engine aftermarket demand to calibrate capacity allocation and R&D spend across product generations.
Market Dynamics
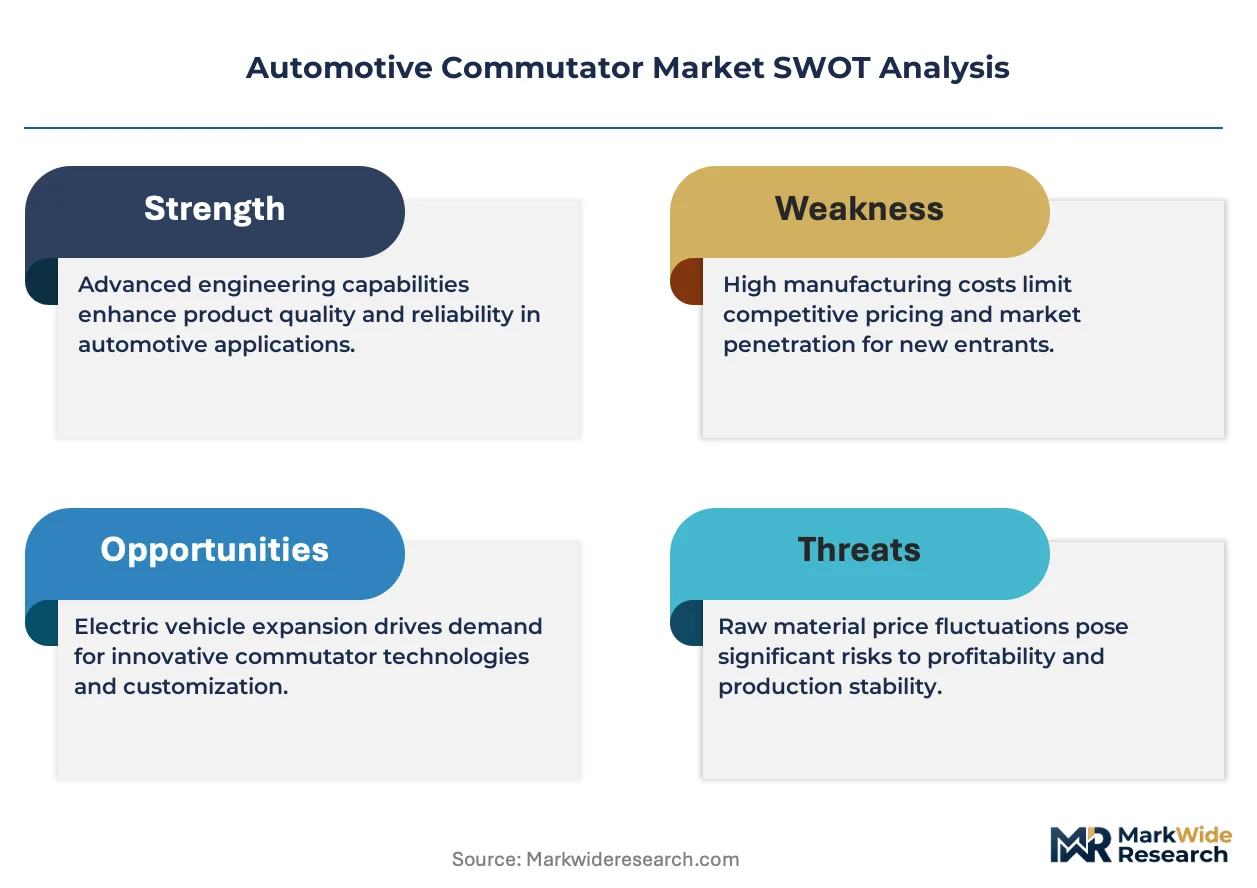
Powertrain electrification is fragmenting demand between brushless motor architectures and residual brushed applications, forcing commutator suppliers to bifurcate R&D portfolios while copper-carbon material science races to meet voltage withstand requirements for 800V EV platforms.
Growth Catalysts
- Copper-carbon composite technology:Hybrid copper-carbon segments achieve superior wear resistance and thermal conductivity, qualifying them for high-speed traction motors in premium EV platforms. NHTSA fuel economy mandates in the United States accelerate OEM specification of low-loss electrical components.
- China's NMPA certification protocols:Tightened vehicle efficiency testing under China's MIIT standards is compelling domestic suppliers to upgrade segment insulation and silver-copper alloying precision.
- East Asian manufacturing concentration:Guangdong and Zhejiang provinces host vertically integrated copper processing clusters that compress lead times for precision-machined commutator assemblies serving regional EV supply chains.
Market Restraints
- Silver price volatility:Silver-copper alloying constitutes a material cost exposure, with silver spot price swings directly compressing margin on high-performance commutator lines.
- Brushless motor substitution:Permanent magnet synchronous motors eliminate mechanical commutation entirely, threatening volume erosion in mass-market EV traction applications.
- REACH substance restrictions:EU ECHA mandates on lead-free copper alloys force reformulation of traditional segment materials, adding compliance certification cycles for exporters.
Strategic Opportunities
- Racing and specialty aftermarket:High-performance brushed motors retain technical relevance in motorsport and restoration segments where cost sensitivity remains below mass-production EV programs.
- EU Green Deal circularity requirements:Documented end-of-life recyclability mandates create first-mover advantage for suppliers establishing closed-loop copper recovery partnerships.
- Hybrid powertrain residual demand:Belt-driven starter-generator systems in 48V mild-hybrid architectures sustain demand for compact, high-temperature commutator designs through the mid-2030s.
Industry Challenges
- Precision machining skill scarcity:Segment-to-segment voltage withstand above 500V requires sub-micron turning tolerances, constraining workforce availability in emerging manufacturing regions.
- Dual technology platform capex:Simultaneous investment in brushed commutator efficiency and brushless motor-integrated designs strains R&D allocation across product generations.
- GB standard harmonization delays:Divergence between China's MIIT efficiency protocols and IEC international standards complicates unified product platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Commutator Market |
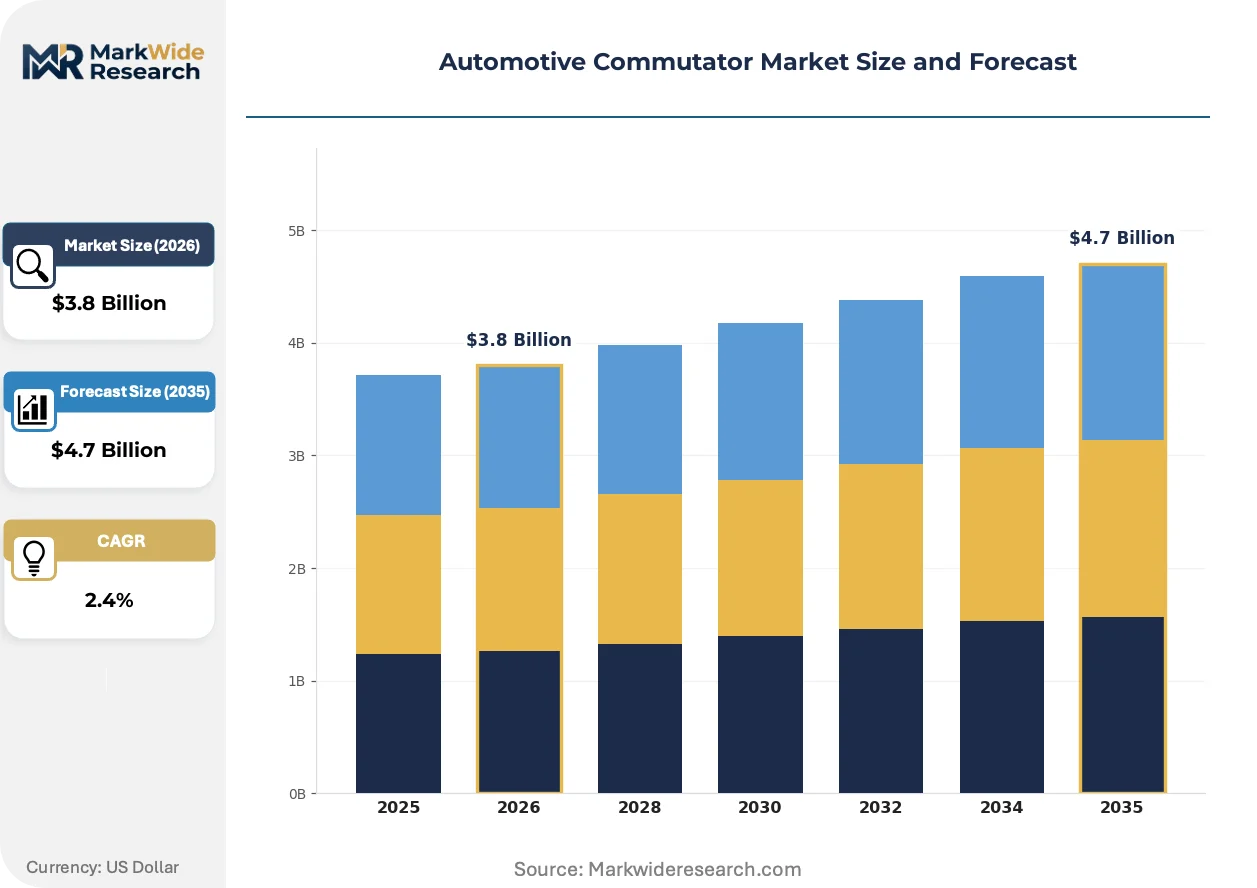
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushed, Brushless, Specialty, High Performance Application: Electric Vehicles, Internal Combustion Engine Vehicles, Hybrid Vehicles, Racing Vehicles Technology: Permanent Magnet, Electromagnetic, Integrated, Variable Speed End User: OEMs, Aftermarket Services, Tier-1 Suppliers, Maintenance Providers |
| Companies Covered | Denso, Continental, Sumitomo Electric, Nidec, Magneti Marelli, Mersen, Mitsubishi Electric, Kolektor, Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Commutator Market Evolving Landscape
Material science breakthroughs and regulatory chemistry restrictions are converging to redefine commutator construction, while procurement patterns in automotive supply chains compress supplier qualification timelines.
Vacuum pressure impregnation with high-temperature polymer resins is rewriting durability benchmarks for copper segment insulation. Tier 1 suppliers are adopting this process for hybrid starter-generator applications where thermal cycling exceeds 180°C. The technology is compressing traditional mica-based insulation market share by enabling thinner, more thermally conductive segment barriers.
REACH substance restrictions from EU ECHA are mandating lead-free copper alloy formulations across all automotive electrical components. Manufacturers serving European OEMs must reformulate segment materials and resubmit material safety datasheets for certification. Asian exporters to Germany and France face the steepest compliance adaptation curves as dual-chemistry inventory management becomes mandatory.
Automotive OEMs are consolidating supplier bases and demanding modular commutator-motor-brush assemblies rather than discrete component sourcing. Tier 1 motor manufacturers are absorbing sub-assembly integration responsibilities previously held by Tier 2 commutator specialists. This consolidation is most visible in Japanese OEM supply chains where Nidec and Denso have captured integrated design authority.
Automotive Commutator Market Segmentation
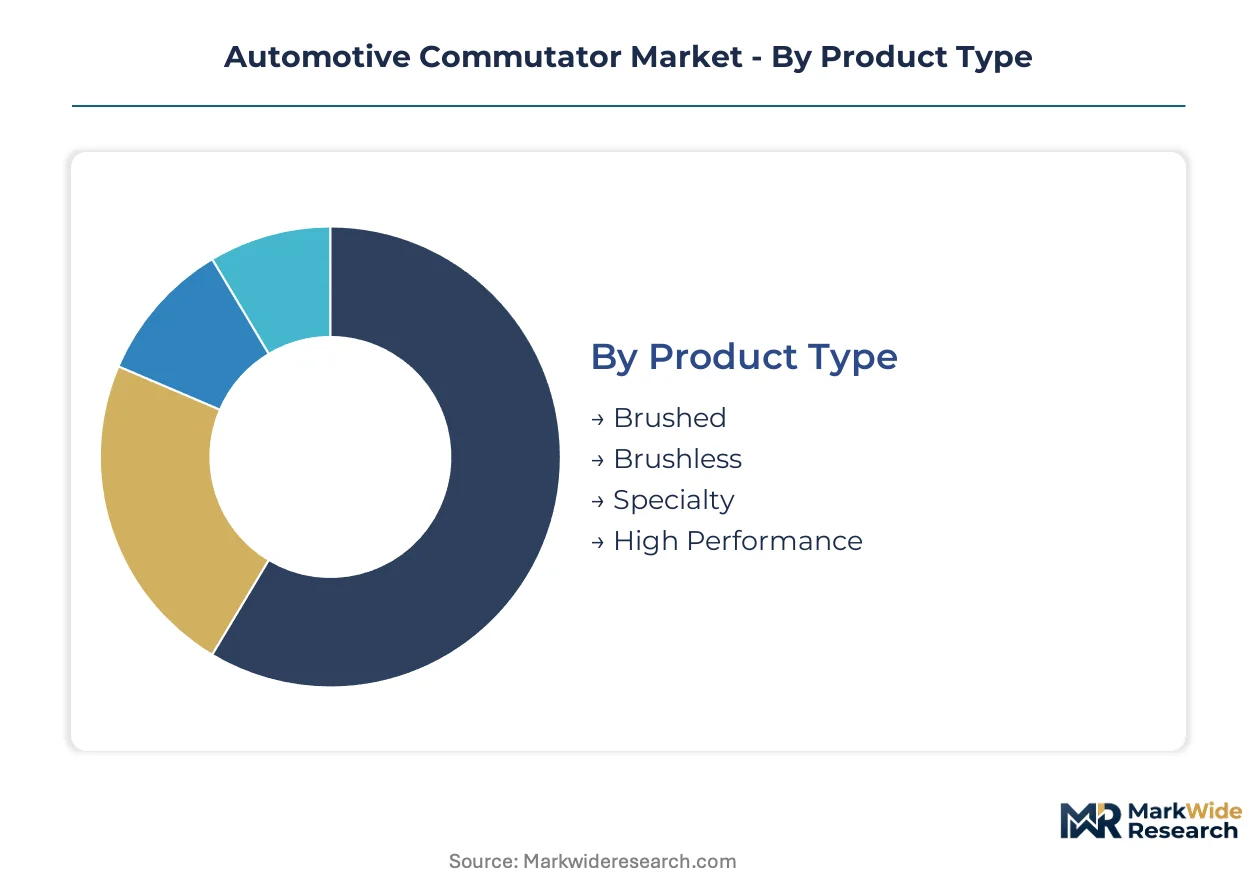
Commutator procurement patterns diverge sharply across product architectures and powertrain electrification stages, with certification requirements multiplying for segments serving 800V EV platforms. Suppliers must maintain parallel qualification tracks for brushed residual demand and brushless-integrated designs.
Product Type:
REACH substance restrictions and NHTSA electrical loss mandates impose divergent testing burdens across these four product classes, with silver-copper alloying precision requirements scaling with voltage withstand specifications.
- Brushed:Copper-mica segment assemblies with mechanical brush contact dominate 48V mild-hybrid starter-generator applications. Guangdong manufacturing clusters supply Denso and Continental with precision-turned segments for belt-driven integrated starter-generators.
- Brushless:Electronic commutation via Hall-effect sensors and inverter-driven field orientation eliminates mechanical wear entirely. Nidec's integrated motor-commutator designs for Japanese OEMs concentrate demand in permanent magnet synchronous traction systems.
- Specialty:Custom-wound armatures for restoration and industrial vehicle retrofits require manual segment alignment and vacuum pressure impregnation with polymer resins.
- High Performance:Silver-copper alloy segments exceeding 500V withstand ratings serve racing applications where thermal cycling exceeds 200°C.
Brushed configurations sit at the top of the volume ranking, with brushless designs climbing the fastest as OEMs eliminate mechanical commutation from EV traction motors.
Application:
Cost tier stratification separates mass-production EV programs from racing and aftermarket segments, with premium pricing pools concentrating where brush life and thermal endurance specifications exceed standard duty cycles.
- Electric Vehicles:800V platform architectures demand copper-carbon composite segments with sub-micron turning tolerances and silver-copper alloying for high-speed traction motors. China's NMPA certification protocols mandate upgraded insulation testing for domestic EV supply chains.
- Internal Combustion Engine Vehicles:Conventional starter motor commutators face volume erosion as 12V systems migrate to 48V mild-hybrid architectures, though residual aftermarket demand sustains production lines in Zhejiang province.
- Hybrid Vehicles:Belt-driven starter-generator systems require compact commutator designs rated for continuous thermal cycling above 180°C, with vacuum pressure impregnation displacing traditional mica insulation.
- Racing Vehicles:High-RPM brushed motors retain technical relevance in motorsport where cost sensitivity remains below mass-production programs and brush replacement intervals are accepted operational overhead.
Internal combustion engine applications retain the largest installed base, with electric vehicle demand expanding most quickly as powertrain electrification accelerates.
Technology:
Customer type determines integration depth, with OEMs demanding modular motor-commutator-brush assemblies while aftermarket channels source discrete replacement segments.
- Permanent Magnet:Neodymium-iron-boron rotor configurations dominate brushless traction motor designs, eliminating mechanical commutation through electronic field orientation controlled by inverter systems.
- Electromagnetic:Wound-field rotor architectures retain niche applications in heavy-duty commercial vehicles where variable torque characteristics outweigh efficiency penalties.
- Integrated:Commutator-motor-brush sub-assemblies consolidated by Tier-1 suppliers compress qualification timelines for OEMs but absorb margin previously captured by discrete component specialists.
- Variable Speed:Electronically commutated motors with sensorless vector control enable torque modulation across wide RPM ranges for HVAC compressor and pump applications.
Permanent magnet technology commands the dominant share, with integrated designs gaining share fastest as Japanese OEM supply chains consolidate procurement authority.
End User:
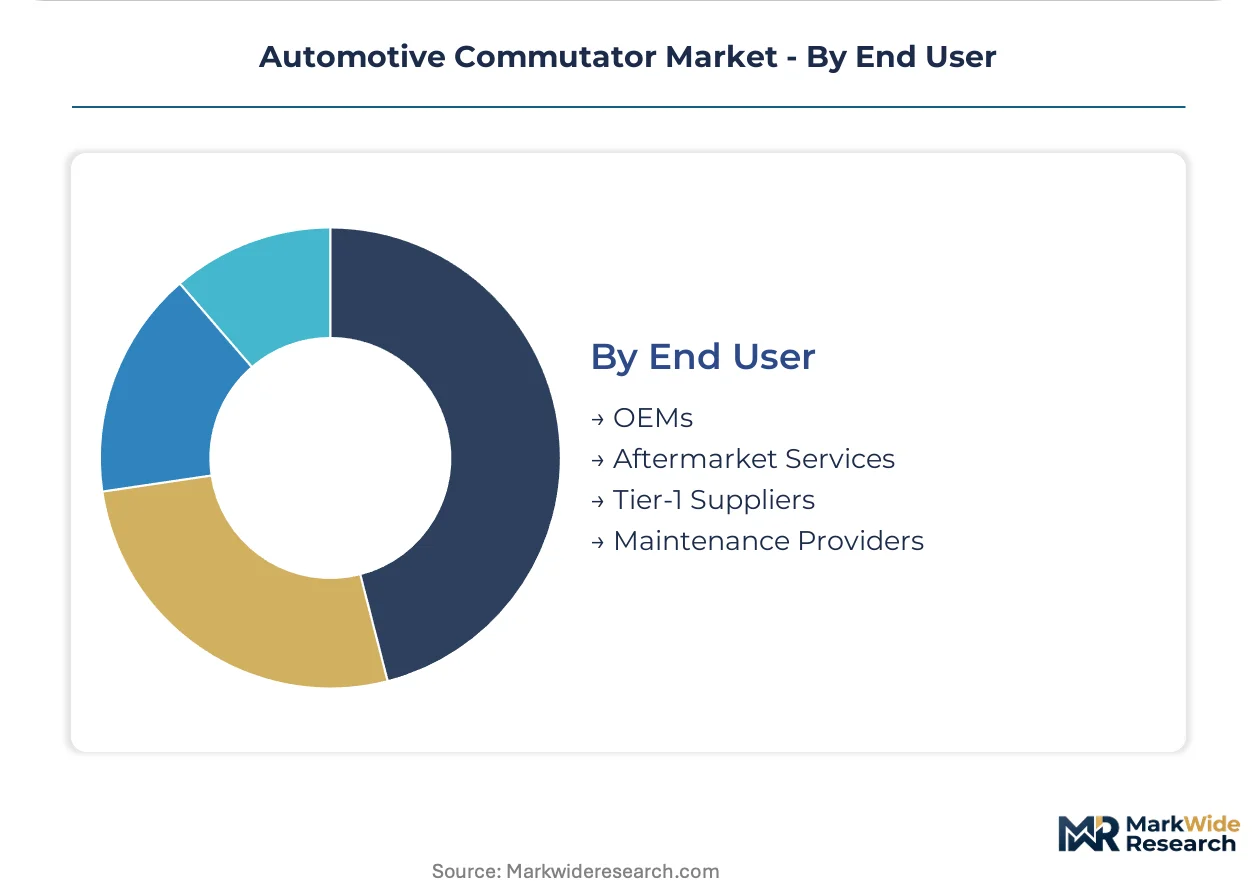
Supply concentration shapes procurement leverage, with OEMs and Tier-1 suppliers anchoring volume in East Asian manufacturing clusters while aftermarket channels fragment across regional distributors.
- OEMs:Vehicle manufacturers specify commutator performance parameters directly, driving silver-copper alloy formulations and vacuum pressure impregnation requirements through technical standards documents.
- Aftermarket Services:Independent repair networks source replacement segments for starter motor rebuilds, with demand concentrating in regions with aging internal combustion engine vehicle fleets.
- Tier-1 Suppliers:Denso, Continental, and Nidec absorb sub-assembly integration responsibilities, establishing captive supply relationships with precision copper processors.
- Maintenance Providers:Fleet operators and commercial vehicle service depots procure commutator assemblies for preventive maintenance programs, prioritizing brush life and warranty terms over initial unit cost.
Tier-1 suppliers anchor the volume ranking, with OEM direct procurement climbing the fastest as technical specification authority consolidates upstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers migrate production toward jurisdictions with streamlined copper-alloy certification protocols, exploiting cost-of-compliance gaps between REACH-mandated European formulations and China's MIIT efficiency standards.
China
NMPA vehicle certification protocols and MIIT efficiency mandates accelerate copper-carbon commutator adoption across domestic EV supply chains. Guangdong and Zhejiang provinces host vertically integrated copper processing clusters that compress lead times for precision-machined assemblies. Denso and Continental source high-volume segments from Dongguan and Ningbo manufacturing hubs serving regional OEM networks.
Germany
KBA homologation requirements and EU Green Deal circularity mandates compel lead-free copper alloy formulations for automotive electrical components. Continental anchors European demand through specialized high-temperature commutator lines for hybrid applications. Bavarian and Baden-Württemberg industrial corridors concentrate precision machining capacity for 800V EV platform segments.
United States
NHTSA fuel economy standards and EPA emissions benchmarks drive OEM specification of low-loss electrical components with extended brush life. Michigan and Ohio manufacturing belts retain residual starter motor demand while California EV programs accelerate brushless motor-integrated designs. Domestic suppliers face margin pressure from silver spot price volatility in high-performance alloying lines.
Japan
METI carbon neutrality roadmaps and JIS standards harmonization support permanent magnet synchronous motor architectures displacing brushed designs. Nidec consolidates integrated motor-commutator design authority across Toyota and Honda supply chains. Kanto and Kansai industrial regions concentrate brushless motor-integrated production for export-oriented Tier-1 programs.
South Korea
MFDS automotive component certification and government EV subsidy programs sustain demand for copper-carbon composite segments in Hyundai-Kia supply chains. Busan-Ulsan manufacturing clusters specialize in high-speed traction motor components for 800V platform architectures. Domestic suppliers compete with Chinese imports on precision turning tolerances for voltage-withstand specifications.
Automotive Commutator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue brushless motor-integrated architectures and specialty aftermarket channels. The vendor base stratifies across three tiers: integrated Tier-1 motor manufacturers capturing design authority, precision copper processors serving as captive suppliers, and independent specialists defending residual brushed demand. Competitive moves concentrate on backward integration into raw copper processing and modular sub-assembly consolidation to absorb margin previously captured by discrete component specialists.
Among Japanese-anchored integrated motor manufacturers, Denso and Nidec exemplify the design-authority archetype through captive supply relationships with precision copper processors. Continental represents the European precision-specialist tier with hybrid-focused high-temperature lines. Kolektor occupies a position within the Central European copper-fabrication cluster serving regional OEM qualification programs.
| Leading Market Players |
|---|
| Denso |
| Continental |
| Sumitomo Electric |
| Nidec |
| Magneti Marelli |
| Mersen |
| Mitsubishi Electric |
| Kolektor |
| Robert Bosch |
| Others |
Value Network & Pricing Analysis
Precision-machining specialists in Guangdong province anchor labor-cost differentials that widen pricing-tier spreads between commodity brushed segments and 800V-rated silver-copper assemblies. Sub-micron turning tolerances command wage premiums that OEMs absorb through tiered procurement contracts.
Pricing Analysis
Distributor margins compress pricing transparency across aftermarket channels, while direct-to-OEM contracts capture volume discounts for integrated motor-commutator assemblies. Three-tier pricing structure across premium, standard, and economy levels reflects silver-copper alloy grades and NMPA certification status. Cost compression in high-performance lines stems from silver spot price volatility. Aftermarket rebuilders exhibit acute price sensitivity; racing segment buyers prioritize thermal endurance over unit economics.
Supply Chain Analysis
Workforce-availability constraints in precision machining limit capacity expansion outside established East Asian clusters. Supply concentrates in China, Germany, and Japan, with Dongguan and Ningbo feeding regional EV supply chains. Raw material dependencies center on copper cathodes, silver bullion, and high-temperature polymer resins. Single-source vulnerability in silver-copper alloying creates exposure to commodity price swings. Distribution runs through Tier-1 motor manufacturers absorbing sub-assembly integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as 800V platform specifications displace commodity-grade segments and reward suppliers with certified silver-copper precision capabilities.
For Market Incumbents: Extend backward integration into captive copper processing to defend margin pools against Chinese import competition. Lock in NMPA and KBA certification pathways ahead of REACH substance restriction deadlines. Consolidate design authority through modular motor-commutator-brush assemblies that absorb Tier-2 margin. For New Entrants and Emerging Players: Launch via specialty aftermarket channels serving racing and restoration segments where cost sensitivity trails mass-production EV programs. Target 48V mild-hybrid starter-generator applications with vacuum pressure impregnation capabilities. Establish technical credibility through Hall-effect sensor integration for brushless architectures. For Investors and Strategic Acquirers: Tier-1 motor manufacturers represent the most active acquirer category in this space, seeking captive supply of precision-machined segments. Five-to-ten-year viability hinges on dual-platform R&D coverage across residual brushed demand and brushless-integrated designs. Acquisition targets should demonstrate closed-loop copper recovery partnerships qualifying for EU Green Deal circularity mandates. Monitor brushless motor penetration rates in Japanese OEM supply chains as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Processing | Denso and Continental secure cost discipline across supplier networks through in-house raw material control. |
| NMPA Certification Investment | Domestic Chinese suppliers capture MIIT efficiency mandate compliance ahead of export competitors. |
| Modular Sub-Assembly Consolidation | Tier-1 motor manufacturers absorb margin previously captured by discrete commutator specialists. |
| Vacuum Pressure Impregnation Scale-Up | Hybrid starter-generator demand drives displacement of traditional mica insulation with polymer resin barriers. |
| Closed-Loop Copper Recovery Partnership | EU Green Deal circularity requirements create first-mover advantage for documented end-of-life recyclability. |
Research Methodology
Bottom-up automotive powertrain modeling reconciled against top-down copper-alloy supply tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and precision machining facility managers combined with secondary validation from vehicle production databases, NMPA certification registries, IHS Markit registration data, and SEC filings from listed component manufacturers. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map segment-level demand across product type, application, technology, and end-user dimensions throughout the forecast period. CAGRs derive from regression analysis against powertrain electrification trajectories and OEM platform rollout schedules. Modeled inputs include 800V architecture penetration rates, MIIT efficiency standard compliance timelines, and silver-copper alloying cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt brushless motor substitution acceleration or silver price spike scenarios. Material deviation in Nidec or Denso design-authority consolidation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Mufflers Market
Automotive Components
Automotive Solenoid Market
Automotive Components
Automotive Heater Core Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Automotive Retarders Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
France Automotive Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Automotive Differential Market