
 Bulgaria Commercial Vehicles Lubricants Market | 2026-2036
Bulgaria Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Bulgaria Commercial Vehicles Lubricants Market Outlook
Market Context
Fleet maintenance operators are rotating toward higher-specification lubricant procurement as vehicle utilization rates climb across Bulgarian road freight corridors. TotalEnergies leverages its European blending network to supply API CK-4 and FA-4 engine oils tailored to Euro VI engine stress profiles. Lukoil anchors its position through captive refinery supply from the Burgas complex, securing cost advantages in bulk hydraulic and transmission fluid sales. Prista Oil differentiates via localized technical service teams that embed directly with transport company maintenance bays.
Technical Definition and Segment Structure
Bulgaria commercial vehicles lubricants comprise formulated petroleum-based and synthetic fluids engineered to reduce friction, dissipate heat, and prevent wear in heavy-duty engines, transmissions, axles, and hydraulic systems operating under load cycles exceeding 500,000 kilometers annually. Engine oil dominates product type value pools due to drain interval compression from severe-duty Bulgarian terrain and climate variability, while grease claims margin concentration in construction applications where contamination resistance commands formulation premiums. Fleet maintenance leads use case volume as centralized procurement by transport companies displaces fragmented workshop buying, and wholesale channels control distribution economics through direct-to-depot contracts that bypass retail markups.
Regulatory Framework and Outlook
EU REACH and the F-Gas Regulation constrain base oil additive chemistries and refrigerant-lubricant compatibility testing for Bulgarian formulators. The country's national environmental regulator enforces waste oil collection quotas that elevate re-refining infrastructure requirements. Stakeholders must monitor EU Green Deal implementation timelines and Euro VII engine standards to anticipate reformulation cycles and service interval recalibration demands.
Market Dynamics
EU REACH and the F-Gas Regulation are compressing formulation flexibility for Bulgarian blenders while simultaneously mandating drain interval extensions that threaten volume-based revenue models.
Growth Catalysts
- Euro VI engine penetration:Heavy-duty fleets operating Sofia-Plovdiv corridors require API CK-4 and FA-4 specifications that command per-liter premiums over legacy CJ-4 formulations.
- REACH additive pre-registration:Bulgarian formulators gaining early REACH compliance capture technical service contracts from pan-European logistics operators.
- Construction sector clustering:Danube River infrastructure projects concentrate hydraulic fluid demand around Ruse and Vidin, creating localized volume spikes.
Market Restraints
- Group II/III base oil import dependency:Bulgaria lacks domestic hydrocracking capacity, exposing blenders to Mediterranean refinery pricing volatility and freight cost swings.
- Waste oil collection quota enforcement:The national environmental regulator mandates collection targets that elevate compliance overhead for mid-sized distributors lacking re-refining partnerships.
- Synthetic ester cost premiums:High-performance biodegradable hydraulic fluids remain economically inaccessible for municipal fleet operators under fixed municipal procurement budgets.
Strategic Opportunities
- Black Sea port electrification:Burgas and Varna container terminal conversions create demand for specialized e-axle and thermal management fluids outside traditional engine oil categories.
- EU Green Deal carbon border adjustments:Early adoption of renewable base oil feedstocks positions Bulgarian suppliers for preferential treatment in cross-border fleet procurement.
- Direct-to-depot digital procurement platforms:Transport management system integration enables predictive lubricant replenishment based on telematics-derived engine stress data.
Industry Challenges
- Tribology specialist scarcity:Bulgarian technical universities produce insufficient lubricant chemists familiar with Euro VI aftertreatment compatibility testing.
- Re-refining infrastructure gaps:Collection network expansion outpaces domestic re-refining capacity, forcing waste oil export to Romanian and Greek processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulgaria Commercial Vehicles Lubricants Market |
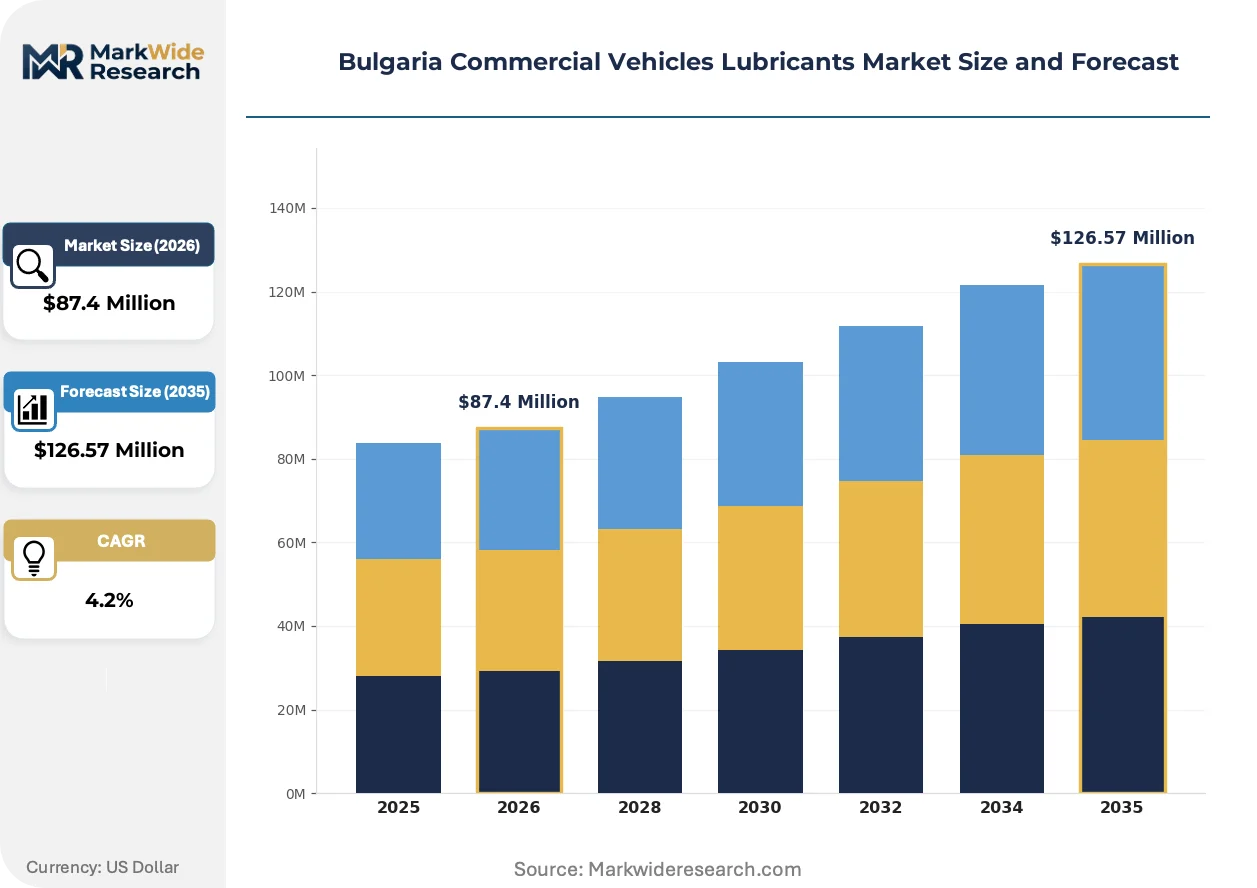
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $126.57 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Oil Use Case: Fleet Maintenance, Construction, Logistics, Transportation Distribution Channel: Retail, Wholesale, Online, Direct Sales End User: Transport Companies, Construction Firms, Public Services, Automotive Workshops |
| Companies Covered | TotalEnergies, BP Plc (Castrol), Chevron Corporation, Motul, Lukoil, ExxonMobil Corporation, Prista Oil, Gazprom, Royal Dutch Shell Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulgaria Commercial Vehicles Lubricants Market Strategic Shifts
Synthetic formulation advances and digital fleet integration are restructuring how lubricant value is captured across Bulgarian commercial vehicle operations, compressing traditional service intervals while elevating technical service intensity.
Polyalphaolefin (PAO) and ester-based full synthetics are supplanting mineral-based formulations in long-haul applications where extended drain intervals offset per-liter cost premiums. Fleet operators running Balkan transit corridors adopt these chemistries to reduce workshop downtime. The shift is compressing volume-based revenue models while expanding technical advisory service contracts.
EU F-Gas Regulation refrigerant phase-down mandates are forcing reformulation of compressor lubricants used in refrigerated transport units. Bulgarian blenders must validate new polyolester chemistries against CO2 and HFO refrigerant compatibility. Refrigerated logistics operators in Plovdiv agricultural export zones face accelerated testing timelines to maintain cold chain certifications.
Consolidated transport procurement departments are displacing fragmented workshop purchasing through multi-year direct supply agreements. Large fleet operators now specify lubricant brands in tender documents, bypassing traditional distributor networks. This concentration is most visible in Sofia-based logistics groups operating cross-border EU routes.
Bulgaria Commercial Vehicles Lubricants Market Segmentation
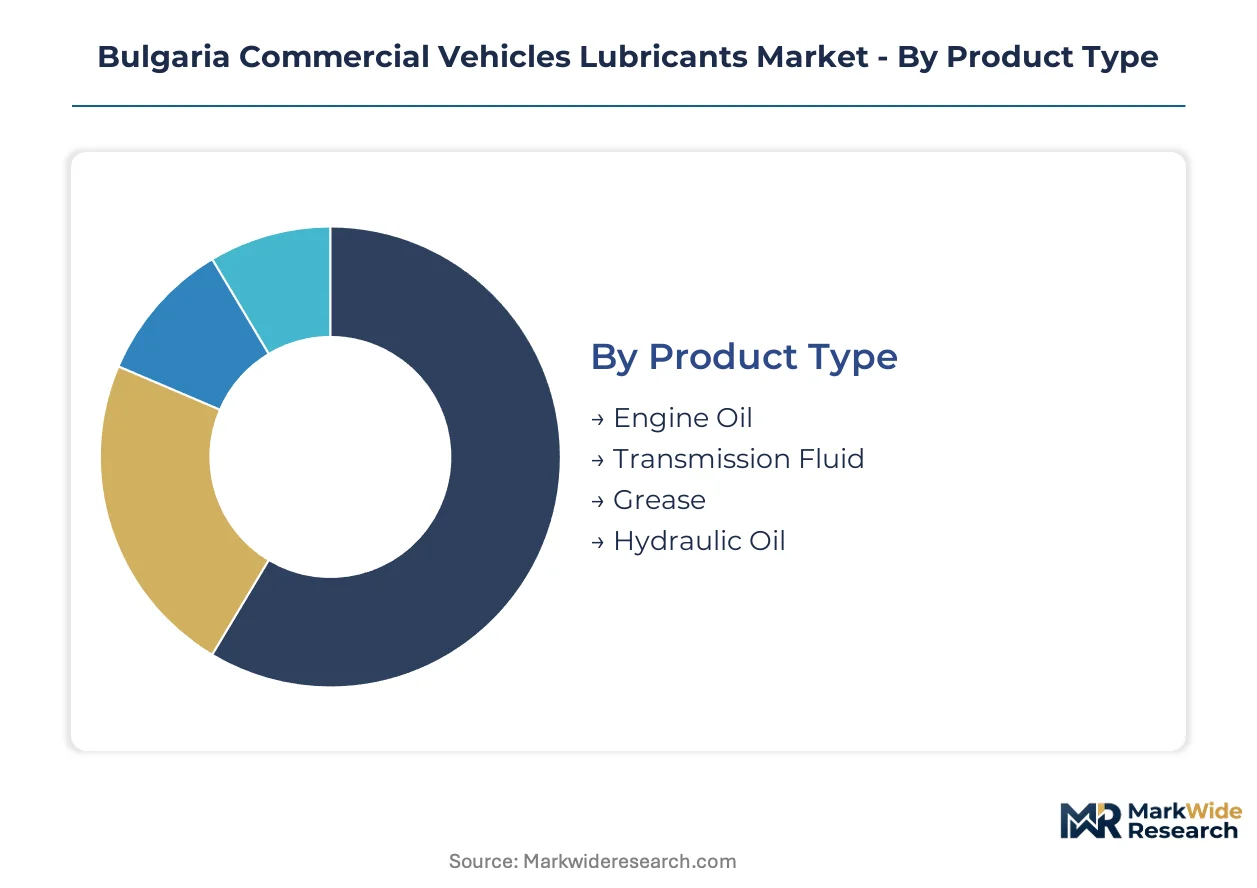
Segmentation in the Bulgaria commercial vehicles lubricants market reveals how procurement centralization and channel consolidation reshape competitive access. Fleet operators and construction firms now dictate specification requirements that flow through distinct distribution pathways.
Product Type:
Channel mix varies sharply by fluid category—engine oils move predominantly through wholesale direct-to-depot contracts, while greases and hydraulic fluids retain more retail workshop penetration due to emergency replenishment needs.
- Engine Oil:Formulated petroleum-based and synthetic lubricants meeting API CK-4, FA-4, and ACEA E6/E9 specifications for heavy-duty diesel engines. Demand concentrates around Sofia and Plovdiv logistics corridors where Euro VI fleet penetration drives specification upgrades and drain interval compression.
- Hydraulic Oil:Anti-wear and biodegradable ester-based fluids engineered for high-pressure construction and materials handling equipment. Danube River infrastructure projects at Ruse and Vidin generate localized volume spikes for zinc-free and ashless formulations.
- Transmission Fluid:Automated manual and dual-clutch transmission lubricants with extended-life additive packages for commercial vehicle drivetrains.
- Grease:Lithium complex and calcium sulfonate thickened lubricants for chassis, wheel bearings, and fifth-wheel applications.
Engine oil dominates installed base volume. Hydraulic oil is where expansion concentrates fastest amid infrastructure investment cycles.
Use Case:
Cost tier stratification separates scheduled preventive programs from reactive maintenance—fleet maintenance commands premium synthetic formulations while construction tolerates broader specification ranges.
- Fleet Maintenance:Centralized procurement by transport operators running scheduled drain-interval programs with telematics monitoring. Sofia-based logistics groups operating EU cross-border routes specify lubricant brands directly in tender documents, bypassing traditional distribution.
- Construction:Heavy equipment lubrication subject to contamination, moisture ingress, and seasonal operating intensity. Plovdiv and Burgas building clusters drive hydraulic fluid demand for excavators and mobile cranes under severe-duty cycles.
- Logistics:Refrigerated transport and container haulage requiring compressor lubricant compatibility with low-GWP refrigerants under F-Gas Regulation phase-down mandates.
- Transportation:Municipal bus fleets and regional passenger services operating under fixed procurement budgets with extended drain interval targets.
Fleet maintenance captures margin concentration through technical service contracts. Construction represents the most price-sensitive tier with fragmented purchasing authority.
Distribution Channel:
Customer type determines channel selection—large transport companies demand direct supply integration while smaller operators remain tethered to retail and workshop networks.
- Wholesale:Bulk supply agreements delivering to fleet depots and construction equipment yards, eliminating retail markups and enabling predictive replenishment based on telematics data.
- Direct Sales:Lubricant supplier technical teams embedding with maintenance bays for specification consulting and used oil analysis programs. This channel is climbing fastest as procurement centralization accelerates.
- Retail:Automotive parts stores and independent workshops serving fragmented owner-operators and emergency replenishment scenarios.
- Online:Digital procurement platforms with transport management system integration for automated reorder triggers.
Wholesale controls volume economics. Direct sales is where supplier relationship investment concentrates.
End User:
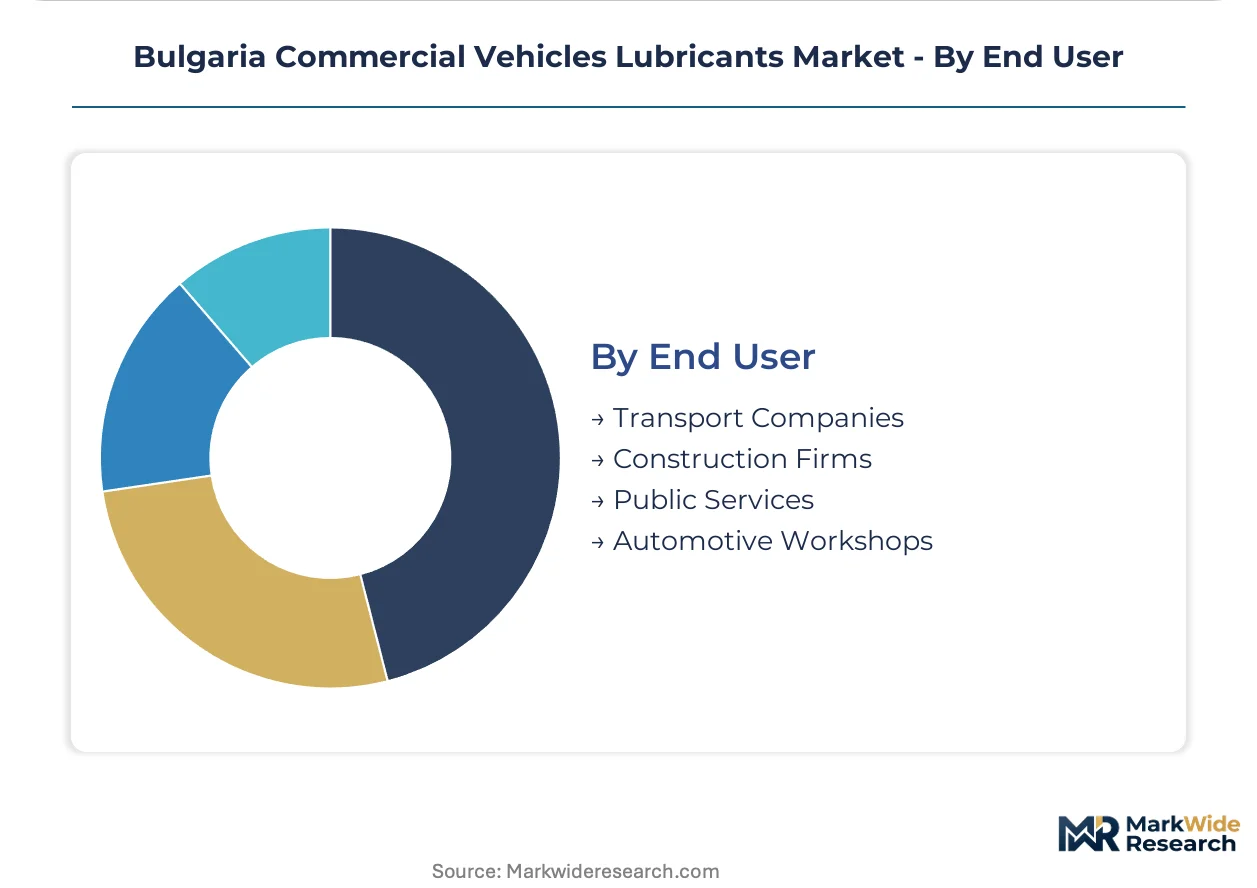
Geography shapes end-user composition—Sofia-Plovdiv corridor density favors transport companies while northern Danube zones tilt toward construction firms and public works.
- Transport Companies:Pan-European logistics operators and domestic freight carriers with centralized technical procurement departments specifying performance-tier lubricants.
- Construction Firms:Civil engineering contractors and equipment rental fleets with seasonal demand patterns and contamination-tolerant formulation requirements.
- Public Services:Municipal waste management, snow removal, and utility fleets operating under constrained procurement budgets with extended drain interval mandates.
- Automotive Workshops:Independent service bays and dealership maintenance centers handling mixed-brand commercial vehicle populations.
Transport companies dominate specification-setting authority. Public services represent the most constrained expansion pathway due to budget rigidity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transport companies and construction firms concentrate procurement authority across distinct Bulgarian economic zones. Fleet operators in Sofia and Plovdiv corridors drive synthetic lubricant specification upgrades. Danube River infrastructure work and Black Sea port activity create localized demand clusters with divergent formulation requirements.
Sofia City Region
Pan-European logistics operators headquartered in Sofia specify API CK-4 and FA-4 engine oils for Euro VI fleets running EU cross-border routes. The municipal environmental regulator enforces waste oil collection quotas that elevate re-refining infrastructure requirements. Centralized procurement departments at transport companies now embed lubricant brands directly into tender documents, bypassing traditional distributor networks.
Plovdiv Region
Construction equipment rental fleets and agricultural exporters generate hydraulic fluid demand for excavators and mobile cranes. The EU F-Gas Regulation refrigerant phase-down mandates reformulation of compressor lubricants for refrigerated transport serving Plovdiv's agricultural export zones. Localized technical service teams embed with maintenance bays to validate polyolester chemistries against CO2 and HFO refrigerant compatibility.
Burgas Region
Black Sea container terminal electrification and port infrastructure expansion create demand for specialized e-axle and thermal management fluids. The Lukoil refinery complex provides captive supply advantages for bulk hydraulic and transmission fluid sales to regional construction clusters. Port operators face accelerated testing timelines for biodegradable ester-based formulations under EU Green Deal implementation pressure.
Danube River Zone
Danube River infrastructure projects at Ruse and Vidin concentrate demand for zinc-free and ashless hydraulic formulations. Municipal fleet operators in northern Bulgaria operate under fixed procurement budgets that constrain synthetic ester adoption despite performance advantages. The national environmental regulator mandates collection targets that force waste oil export to Romanian processors due to domestic re-refining capacity gaps.
Bulgaria Commercial Vehicles Lubricants Market Competitive Environment
Player mix skews toward integrated petroleum majors with captive refinery supply and specialized regional blenders with embedded technical service capabilities. Market structure concentrates around three to four suppliers controlling bulk supply agreements, with mid-sized distributors competing on workshop penetration. Strategic archetypes include European majors leveraging blending network scale, Russian-origin suppliers anchoring cost-position through upstream integration, and local specialists capturing margin via technical advisory intensity. Dominant competitive moves center on direct-to-depot contract consolidation and predictive replenishment platform integration with transport management systems.
Among European-based integrated suppliers, TotalEnergies and BP Plc (Castrol) occupy positions defined by API CK-4 and FA-4 specification leadership for Euro VI engine stress profiles. Lukoil anchors the Russian-origin archetype through captive refinery supply from the Burgas complex, securing cost advantages in bulk hydraulic and transmission categories. Prista Oil exemplifies the regional specialist model, with localized technical service teams embedding directly with transport company maintenance bays to capture advisory-service margin pools.
| Leading Market Players |
|---|
| TotalEnergies |
| BP Plc (Castrol) |
| Chevron Corporation |
| Motul |
| Lukoil |
| ExxonMobil Corporation |
| Prista Oil |
| Gazprom |
| Royal Dutch Shell Plc |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day base oil inventory cycles at Bulgarian blending facilities concentrate purchasing power among Mediterranean refinery suppliers while compressing margin flexibility for mid-sized distributors. This lead-time exposure to Group II/III import flows from Greece and Turkey shapes how formulators negotiate annual offtake contracts and pass through feedstock volatility to fleet customers.
Pricing Analysis
The API FA-4 versus CK-4 versus CJ-4 specification gap drives a three-tier pricing structure across premium synthetic, semi-synthetic, and mineral formulations in Bulgarian commercial vehicle lubricants. Price differentiation hinges on Euro VI aftertreatment compatibility certification and volume-scale procurement tiers negotiated by Sofia-based logistics groups. Cost compression in mineral-based segments is intensifying because Burgas refinery supply advantages allow Lukoil to undercut imported alternatives. Municipal fleet operators under fixed procurement budgets exhibit the highest price sensitivity, while pan-European transport companies prioritize drain interval economics over per-liter cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate among Bulgarian blenders lacking domestic hydrocracking capacity, leaving strategic stockpiling to integrated suppliers with captive refinery access. Geographic supply concentration centers on Greece, Turkey, and Romania for Group II/III base oils, with additive packages sourced from Germany and Belgium. Raw material dependencies include hydrocracked base stocks, zinc dialkyldithiophosphate anti-wear additives, and polyalphaolefin synthetic feedstocks. Single-source vulnerability runs through Mediterranean refinery corridors exposed to freight cost swings. Distribution runs through wholesale direct-to-depot contracts that bypass retail markups for large fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon border adjustments and Euro VII engine standards are disrupting established formulation cycles, creating compressed windows for competitive repositioning across Bulgarian lubricant supply chains.
For Market Incumbents: Secure re-refining partnerships to meet national waste oil collection quotas while insulating against Romanian processor dependency. Deepen backward integration into additive blending capabilities to reduce exposure to German and Belgian chemical supplier pricing power. Lock in multi-year direct-to-depot contracts with Sofia-based logistics groups before procurement centralization completes. For New Entrants and Emerging Players: Lead with biodegradable ester-based hydraulic fluids targeting Burgas port electrification projects and Danube River infrastructure zones where EU Green Deal pressure creates specification openings. Municipal fleet operators in northern Bulgaria represent the most penetrable segment due to incumbent neglect of fixed-budget procurement channels. Embed technical service teams directly with construction equipment rental fleets to validate contamination-resistant formulations. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-sized Bulgarian distributors with established collection networks but lacking re-refining infrastructure, offering bolt-on capacity to European majors. Long-term viability in this market hinges on positioning for renewable base oil feedstock transitions and predictive replenishment platform integration. Monitor EU REACH pre-registration completion rates among Bulgarian formulators as the inflection signal for technical service contract capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Re-refining Infrastructure Buildout | Domestic waste oil processing capacity reduces export dependency to Romanian facilities under national quota enforcement. |
| Renewable Base Oil Feedstock Transition | Early adoption positions Bulgarian suppliers for preferential EU Green Deal carbon border adjustment treatment. |
| Predictive Replenishment Platform Integration | Telematics-derived engine stress data enables automated lubricant reorder triggers with transport management systems. |
| Technical Service Team Embedding | Localized chemists validating polyolester refrigerant compatibility capture advisory-service margin from Plovdiv cold chain operators. |
| Direct-to-Depot Contract Consolidation | Multi-year supply agreements with Sofia logistics groups bypass traditional distributor networks and lock in volume. |
Study Parameters
Cross-validation between fleet maintenance director interviews and Bulgarian customs trade data anchors the qualitative findings on import dependency and specification migration patterns. Primary fieldwork engaged lubricant procurement managers at transport companies, blending plant technical directors, construction equipment rental fleet supervisors, and national environmental regulator enforcement officers. Secondary validation drew from EU REACH registration databases, F-Gas Regulation implementation timelines, Burgas refinery throughput disclosures, and pan-European logistics operator tender documents. Bottom-up volume modeling triangulated against top-down macroeconomic freight activity indicators.
Sensitivity analysis around base oil price volatility and Euro VII implementation timing frames the projection methodology. Segmentation dimensions span product type, use case, distribution channel, and end-user geography across the modeling period. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection points and fleet renewal cycles. Industry-specific forecast inputs include commercial vehicle registration data from Bulgarian transport authorities and Danube River infrastructure project procurement schedules.
Underlying assumptions cover REACH compliance maintenance, F-Gas refrigerant phase-down adherence, and Burgas refinery operational continuity, with deviation risk concentrated in Mediterranean supply corridor disruptions and municipal budget austerity measures. Revision becomes warranted when synthetic ester cost premiums cross accessibility thresholds for municipal fleet procurement committees.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Hardware Market
Automotive Components
Automotive Metal Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Automotive Catalyst Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Automotive Distributor Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Automotive Chromium Market
Automotive Components
Automotive Refrigerant Market
Automotive Components
Australia Automotive Pneumatic Actuators Market