
 North America Plastic Bottles and Containers Market | 2026-2036
North America Plastic Bottles and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plastic Bottles and Containers Market Foresight
Skilled blow molding technician availability is bifurcating the competitive landscape across North America. Amcor plc leverages its integrated PET resin and preform operations to sustain cost advantages in beverage packaging. Berry Global Inc anchors its position through geographic dominance across Midwestern manufacturing hubs. Plastipak Holdings Inc differentiates via specialized pharmaceutical-grade barrier container production.
Plastic bottles and containers are hollow thermoformed or blow-molded vessels manufactured from polyethylene terephthalate, high-density polyethylene, or polyvinyl chloride resins, typically ranging from under 250 milliliters to over five liters in capacity, designed for containment, protection, and distribution of liquid and semi-solid consumer and industrial products. PET bottles command the largest volume share due to their clarity, barrier properties, and established recycling infrastructure, while HDPE containers retain strength in household chemical and personal care segments where chemical resistance and squeezability matter. Food packaging applications generate stable baseline demand, though beverage packaging drives the fastest capacity expansion as brands convert from glass and metal formats.
The FDA governs food-contact substance compliance under 21 CFR, while EPA regulations on resin manufacturing emissions shape plant siting decisions across the United States and Canada. California's SB 54 and Oregon's packaging stewardship laws are forcing brand owners to source post-consumer recycled resin or face escalating compliance fees. Stakeholders must monitor how state-level extended producer responsibility fragmentation reshapes resin procurement and converter contract structures.
Market Dynamics
California's SB 54 extended producer responsibility law is forcing resin lightweighting investments and recycled content mandates across the North American plastic bottles and containers market. Beverage bottlers in Mexico and the United States are expanding PET packaging lines for carbonated soft drinks and functional waters.
Growth Catalysts
- Post-consumer recycled resin mandates:California's SB 54 requires brand owners to source post-consumer recycled resin or face escalating compliance fees, driving converter contract restructuring.
- Functional water packaging expansion:Beverage bottlers across Mexico and the United States are expanding PET packaging lines as brands convert from glass and metal formats.
- Great Lakes manufacturing corridor concentration:Blow molding capacity clusters near automotive and consumer goods supply chains across Ohio, Michigan, and Illinois.
Market Restraints
- Resin input cost volatility:Polyethylene terephthalate and high-density polyethylene resin prices fluctuate with crude oil derivatives and refinery capacity constraints.
- Skilled blow molding technician scarcity:Labor availability bifurcates the competitive landscape as specialized technician training programs lag equipment deployment timelines.
- State-level regulatory fragmentation:Oregon's packaging stewardship laws and California's SB 54 create divergent compliance frameworks across state borders.
Strategic Opportunities
- Pharmaceutical-grade barrier containers:Specialized barrier container production for pharmaceutical applications represents underpenetrated white space with stringent FDA compliance requirements.
- Mexico beverage bottling expansion:Carbonated soft drink and functional water packaging lines in Mexico offer geographic diversification beyond United States capacity saturation.
- Lightweighting technology convergence:Advanced preform design software combined with high-speed reheat stretch blow molding enables material reduction without performance degradation.
Industry Challenges
- Blow molding technician skill gaps:Skilled technician availability constraints limit production ramp rates and equipment utilization across Midwestern manufacturing hubs.
- Recycled resin certification timelines:FDA food-contact substance compliance under 21 CFR requires extended validation periods for post-consumer recycled content integration.
- Legacy equipment reconfiguration:Existing blow molding assets require substantial modification to process higher percentages of post-consumer recycled resin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plastic Bottles and Containers Market |
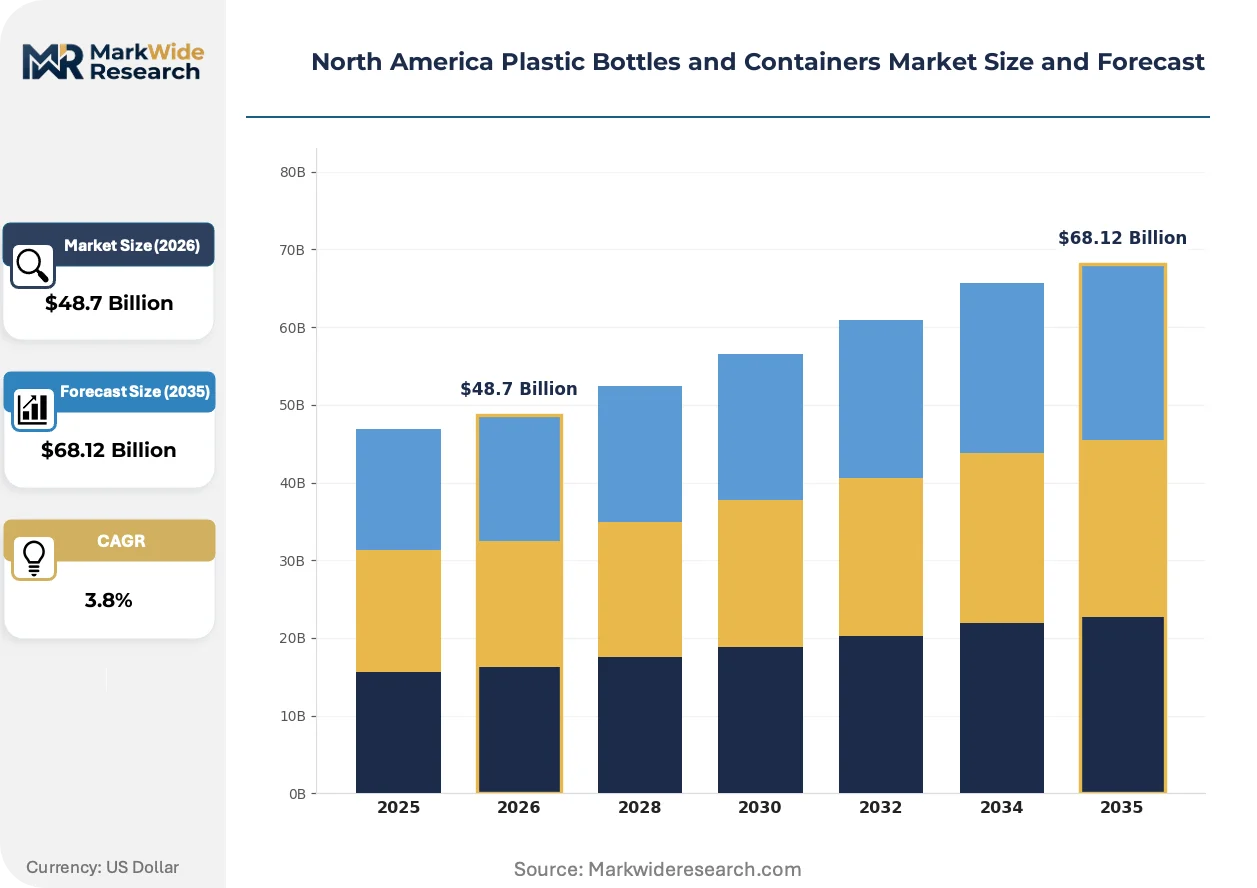
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $68.12 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET Bottles, HDPE Containers, LDPE Bottles, PVC Containers Application: Food Packaging, Beverage Packaging, Personal Care, Household Products Capacity: Small (Under 250ml), Medium (250ml-1L), Large (1L-5L), Extra Large (Over 5L) Distribution Channel: Hypermarkets, Supermarkets, Online Retailers, Convenience Stores |
| Companies Covered | Amcor plc, Berry Global Inc, Plastipak Holdings Inc, Alpha Packaging Inc, AptarGroup Inc, Sonoco Products Company, CKS Packaging, Graham Packaging Company, ALPLA Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plastic Bottles and Containers Market Shifts & Advancements
Active reshaping of the North American plastic bottles and containers market centers on three concurrent developments: advanced barrier technologies for shelf-life extension, state-level extended producer responsibility frameworks, and procurement model evolution toward recycled content verification.
Mono-material barrier coatings are supplanting multi-layer coextruded structures in sensitive food and beverage applications. Premium juice and functional water brands are adopting plasma-enhanced chemical vapor deposition barriers at accelerated pilot-to-commercial timelines. This technology is supplanting ethylene vinyl alcohol and nylon interlayers while simplifying mechanical recycling streams.
California's SB 54 extended producer responsibility law mandates escalating post-consumer recycled content thresholds and establishes producer financing for collection infrastructure. Brand owners must source verified recycled resin or pay escalating compliance fees into state-managed producer responsibility organizations. Beverage packaging converters across the Great Lakes corridor and California are restructuring supplier contracts to secure recycled resin allocation.
Buyer verification of recycled content claims is displacing traditional resin certification documentation. Large beverage brand owners now require third-party mass balance auditing and blockchain-tracked chain of custody from preform suppliers. This behavioral shift is most visible in California and Oregon, where state stewardship laws attach financial penalties to unsubstantiated recycled content marketing.
North America Plastic Bottles and Containers Market Segmentation
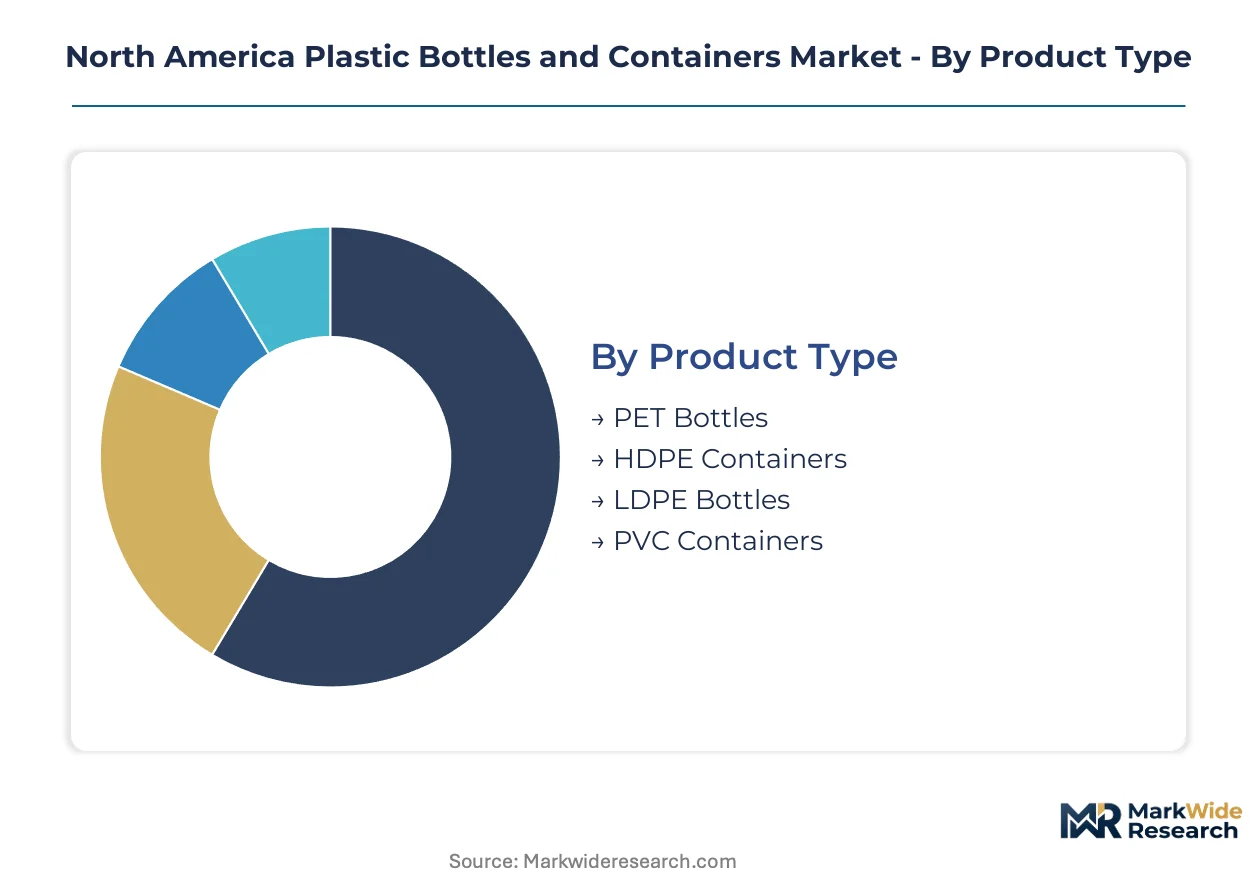
Segmentation in the North America plastic bottles and containers market reveals how regulatory pressure and end-use performance requirements reshape procurement decisions. Material specifications, capacity ranges, and channel access determine converter contract structures and resin procurement strategies across the United States, Mexico, and Canada.
Product Type:
FDA 21 CFR compliance timelines and recycled content mandates under California SB 54 create divergent certification burdens across resin chemistries.
- PET Bottles:Thermoplastic polyester resin delivers clarity, barrier properties, and established mechanical recycling infrastructure. Beverage bottlers across Mexico and the United States prioritize PET for carbonated soft drinks and functional waters as brands convert from glass and metal formats.
- HDPE Containers:High-density polyethylene provides chemical resistance and squeezability for household chemical applications. Demand concentrates in the Great Lakes manufacturing corridor where blow molding capacity clusters near automotive and consumer goods supply chains.
- LDPE Bottles:Low-density polyethylene offers flexibility and impact resistance for squeeze applications.
- PVC Containers:Polyvinyl chloride retains niche pharmaceutical and chemical containment roles despite recycling infrastructure limitations.
Established volume favors PET bottles; emerging adoption favors HDPE containers in chemical-resistant applications.
Application:
End-use performance specifications determine barrier technology investments and sterilization validation requirements.
- Food Packaging:Mono-material barrier coatings supplant multi-layer coextruded structures as plasma-enhanced chemical vapor deposition simplifies mechanical recycling streams. FDA food-contact substance compliance under 21 CFR requires extended validation periods for shelf-life extension technologies.
- Beverage Packaging:Carbonated soft drink and functional water brands drive fastest capacity expansion. California SB 54 mandates force brand owners to source post-consumer recycled resin or face escalating compliance fees into state-managed producer responsibility organizations.
- Personal Care:Squeezable HDPE and LDPE formats dominate shampoo and lotion containment.
- Household Products:Chemical resistance requirements sustain HDPE demand for cleaners and detergents.
Procurement scale favors beverage packaging; margin expansion favors food packaging barrier upgrades.
Capacity:
Preform design complexity and blow molding equipment specifications vary discretely across size thresholds.
- Small (Under 250ml):Travel-size and sample formats require precision preform design. Pharmaceutical-grade barrier container production represents underpenetrated white space with stringent FDA compliance requirements.
- Medium (250ml-1L):Standard beverage and personal care volumes dominate unit economics. Lightweighting technology convergence enables material reduction without performance degradation through advanced preform design software.
- Large (1L-5L):Family-size beverage and household chemical formats.
- Extra Large (Over 5L):Bulk industrial and institutional containment applications.
Equipment utilization peaks in medium capacity; specialized margins concentrate in small format pharmaceutical applications.
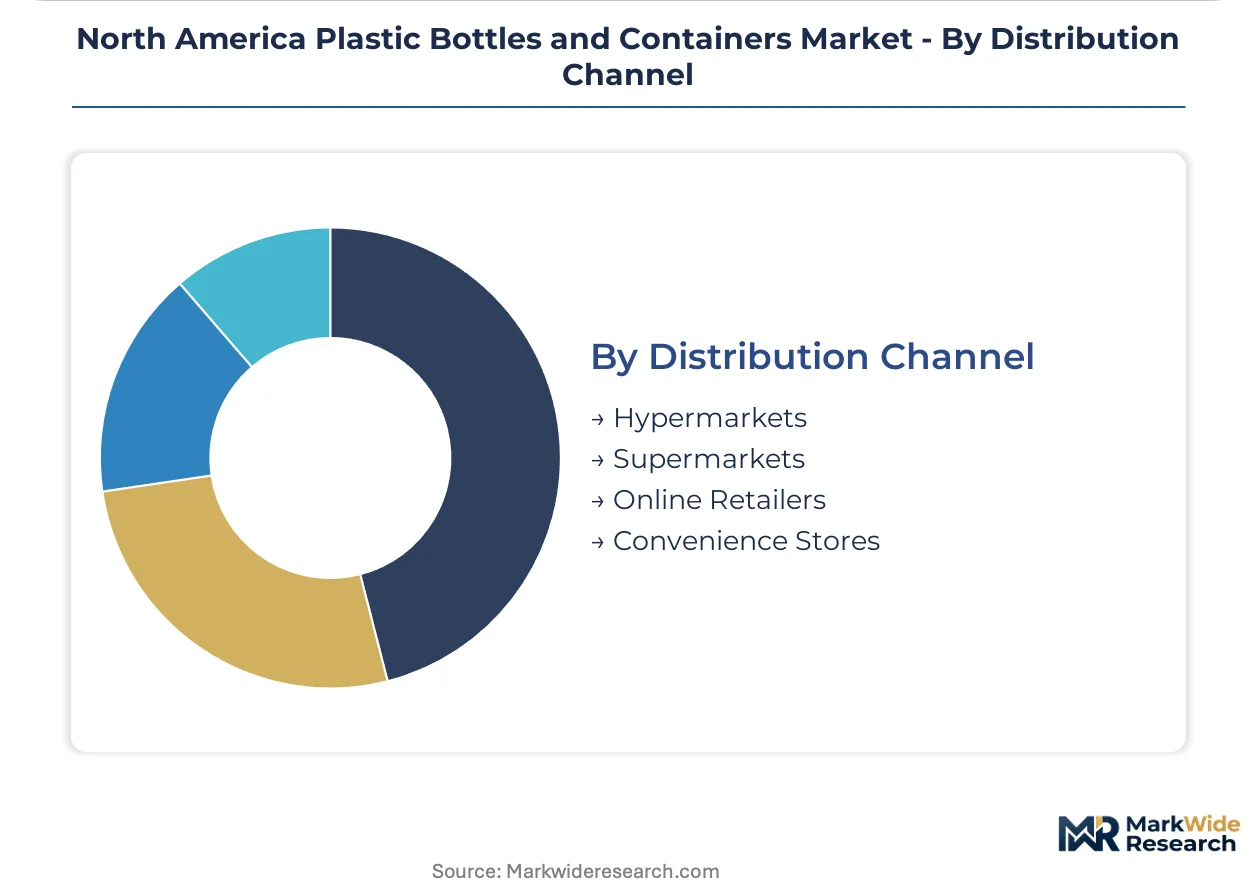
Distribution Channel:
Packaging specification divergence reflects retail format handling requirements and private label concentration.
- Hypermarkets:High-volume palletized logistics demand stack stability and label adhesion performance. Great Lakes manufacturing corridor proximity reduces freight costs for Ohio, Michigan, and Illinois retail distribution.
- Supermarkets:Regional chain specifications drive SKU proliferation and shorter production runs.
- Online Retailers:E-commerce shipment durability requirements reshape wall thickness specifications.
- Convenience Stores:Cold-chain beverage immediacy sustains single-serve PET demand.
Volume concentration favors hypermarkets; specification complexity favors online retailer durability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply by end-use concentration. The United States dominates beverage packaging demand while Mexico drives carbonated soft drink capacity expansion. Canada concentrates pharmaceutical-grade barrier container procurement.
United States
Beverage bottlers in California and Texas are expanding PET packaging lines for functional waters and carbonated soft drinks. The FDA governs food-contact substance compliance under 21 CFR while California's SB 54 mandates escalating post-consumer recycled content thresholds. Blow molding capacity clusters in the Great Lakes corridor spanning Ohio, Michigan, and Illinois near automotive and consumer goods supply chains.
Canada
Pharmaceutical packaging demand concentrates in Ontario and Quebec where barrier container specifications exceed standard beverage requirements. Health Canada regulates food-contact materials under the Food and Drugs Act while provincial extended producer responsibility programs in British Columbia shape resin procurement decisions. Toronto and Montreal anchor blow molding operations serving North American pharmaceutical distribution networks.
Mexico
Carbonated soft drink bottlers are expanding PET packaging capacity to serve domestic and export markets. The country's environmental regulator SEMARNAT implements packaging waste management frameworks while state-level industrial incentives attract converter investment. Mexico City and Nuevo León concentrate blow molding operations near beverage brand manufacturing facilities.
North America Plastic Bottles and Containers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North American plastic bottles and containers. The market structure bifurcates between resin-integrated converters with captive preform supply and independent blow molders sourcing commodity resin. Three archetypes dominate: integrated resin-to-preform operators, geographic cluster specialists, and pharmaceutical-grade barrier container experts. Capacity expansion and recycled resin procurement partnerships constitute the dominant competitive moves as brand owners restructure supplier contracts.
Among integrated converters, Amcor plc exemplifies the resin-integrated archetype through its captive PET operations. Berry Global Inc represents geographic cluster dominance across Midwestern manufacturing hubs. Plastipak Holdings Inc occupies a specialized position in pharmaceutical-grade barrier container production. These three companies anchor the competitive landscape without exhausting its structural variation.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc |
| Plastipak Holdings Inc |
| Alpha Packaging Inc |
| AptarGroup Inc |
| Sonoco Products Company |
| CKS Packaging |
| Graham Packaging Company |
| ALPLA Group |
| Others |
Supply & Pricing Matrix
Blow molding capacity utilization above 85 percent across Ohio, Michigan, and Illinois creates durable price floors for PET preforms and finished containers. Scale concentration near resin production and brand manufacturing facilities lets integrated converters extract margin while independent molders absorb volatility.
Pricing Analysis
Long-term offtake contracts dominate resin procurement between converters and petrochemical suppliers, with spot market exposure limited to 15-20 percent of volume. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and industrial grades reflects FDA 21 CFR validation burdens. Pricing pressure stems from California SB 54 compliance fees pushing brand owners to demand cost absorption from converters. Small-format pharmaceutical buyers show lowest price sensitivity due to barrier performance requirements.
Supply Chain Analysis
Inbound logistics costs from Gulf Coast resin production centers to Great Lakes blow molding facilities run through rail and truck networks vulnerable to weather disruptions. Supply concentrates in the United States, Mexico, and Canada with resin production anchored in Texas and Louisiana. Raw material dependencies include purified terephthalic acid, ethylene glycol, and colorant additives. Single-source vulnerability exists for pharmaceutical-grade barrier coating chemistries. Distribution runs through direct-to-plant delivery for large beverage bottlers and regional warehouse networks for fragmented personal care brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-consumer recycled resin mandates under California SB 54 are accelerating an early-cycle expansion story as brand owners restructure supplier contracts ahead of compliance deadlines.
For Market Incumbents: Compound geographic dominance across the Great Lakes corridor by adding high-speed reheat stretch blow molding lines before technician scarcity worsens. Defend margin position through backward integration into preform manufacturing to capture lightweighting value. Threat of emerging Mexican capacity requires securing long-term beverage bottler contracts with recycled resin allocation guarantees. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade barrier container production where FDA 21 CFR compliance timelines deter commodity converters. Target underpenetrated small-format pharmaceutical applications in Ontario and Quebec. Go-to-market angle should emphasize plasma-enhanced chemical vapor deposition barrier validation and third-party mass balance auditing capabilities. For Investors and Strategic Acquirers: Regional cluster specialists with captive resin supply and established recycler partnerships represent the most defensible acquisition profile across the analysis window. Long-term viability hinges on converter ability to process 30-plus percent post-consumer recycled resin without equipment reconfiguration. Watch for inflection when Oregon and Washington adopt packaging stewardship laws mirroring California SB 54.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Resin Procurement Partnership | Secures post-consumer PET allocation ahead of California SB 54 compliance deadlines. |
| Lightweighting Technology Deployment | Advanced preform design software reduces material per unit without barrier degradation. |
| Pharmaceutical Barrier Certification | FDA 21 CFR validation opens margin-rich small-format containment applications. |
| Mexico Manufacturing Footprint Expansion | Nuevo León proximity to beverage brand facilities captures carbonated soft drink growth. |
| Blockchain Chain-of-Custody Implementation | Third-party mass balance auditing satisfies California and Oregon recycled content verification. |
Research Methodology
A spread of perspectives from blow molding plant managers, beverage brand procurement leads, resin supplier technical directors, and FDA regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade data, American Chemistry Council resin production reports, EPA emissions filings, and state-level extended producer responsibility program documentation. Bottom-up capacity utilization estimates triangulated against top-down brand owner packaging spend projections.
Segmentation dimensions modeled include material chemistry, capacity range, end-use application, and distribution channel across the projection horizon. CAGRs derived from weighted capacity expansion announcements, resin price elasticity assumptions, and regulatory compliance cost pass-through coefficients. Forecast inputs incorporated California SB 54 recycled content phase-in schedules and Great Lakes manufacturing corridor labor availability constraints.
The analysis sits within stated boundaries; outcomes outside sustained resin price stability, unaltered SB 54 enforcement timelines, or unchanged FDA food-contact validation requirements would require recalibration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Mini Spray Bottles Market
Containers
Jars Market
Containers
Club Store Packaging Tray Market
Containers
Bulk Container Packaging Market
Containers
Hinged Lid Compostable Container Market
Containers
Concentrate Containers Market
Containers
Stackable Plastic Trays Market
Containers
Jerry Cans Market
Containers
PUR Containers Packaging Market
Containers
Composite Ibcs System Market
Containers
Acrylic Container Market
Containers
Sandwich Containers Market
Containers
Half Height Containers Market
Containers
Injection Molding Containers Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Tin Containers Market