
 Cylindrical Cans Market | 2026-2036
Cylindrical Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Cylindrical Cans Market Outlook
Project finance tied to greenfield canning lines is narrowing the competitive field to capitalized incumbents. Ball Corporation leverages vertical integration across aluminum sourcing and can forming to sustain margin control. Crown Holdings Inc. anchors its position through geographic dominance in North American beverage packaging. Ardagh Group competes via specialization in steel and tinplate formats for food preservation.
Cylindrical cans are sealed metal containers formed from aluminum, steel, or tinplate, typically featuring double-seamed ends and wall thicknesses calibrated to internal pressure ratings, designed primarily for shelf-stable containment of beverages, processed foods, and industrial chemicals. The aluminum product type leads volume due to lightweighting advantages in beverage logistics, while BPA-Free coatings represent the fastest-growing specification as food safety standards tighten. Beverage application dominates value generation, though chemical packaging commands premium margin pools owing to corrosion resistance requirements and lower price sensitivity among industrial buyers.
EPA regulations in the United States govern volatile organic compound emissions during can coating processes, while REACH in Europe restricts bisphenol-A migration limits into food contact surfaces, collectively elevating compliance costs for non-specialized producers. China's SAMR enforces GB standards for food contact materials that foreign exporters must satisfy for market access. Stakeholders must monitor evolving coating chemistries and regional certification divergence to align capital deployment with compliant supply positions.
Market Dynamics
Aluminum can sheet supply concentration among a handful of smelters and rolling mills is forcing beverage brand owners to secure multi-year offtake agreements, locking in capacity ahead of greenfield line expansions and reshaping competitive access to lightweight packaging inputs.
Growth Catalysts
- REACH Phase-Out Mandates:European bisphenol-A restrictions on food contact surfaces are accelerating BPA-free epoxy and polyester coating adoption, opening specification windows for compliant suppliers.
- China Domestic Beverage Scaling:Local brand canning capacity buildouts are concentrating demand for two-piece aluminum beverage cans within the country's eastern manufacturing corridor.
- Steel Food Preservation Demand:Extended shelf-life requirements for processed vegetables and ready meals are sustaining tinplate and tin-free steel specifications in ambient food logistics.
Market Restraints
- Aluminum LME Price Volatility:Primary metal input cost swings compress converter margins and complicate long-term contract pricing with beverage customers.
- Coating Chemical Supply Concentration:Specialty resin and additive production clusters in Germany and Japan create geographic chokepoints for BPA-free formulation transitions.
- Glass and PET Substitution:Premium beverage segments in hospitality and direct-to-consumer channels retain preference for alternative primary packaging formats.
Strategic Opportunities
- India Organized Retail Expansion:Modern trade and e-commerce grocery penetration is creating first-time canning demand for domestic edible oil and beverage brands.
- US EPA VOC Compliance Windows:Staggered emission reduction deadlines for can coating operations are creating service and equipment retrofit demand for environmental compliance providers.
- Aseptic Canning Convergence:Integration of retort sterilization with two-piece aluminum forming is enabling ambient distribution of sensitive nutritional beverages without refrigeration.
Industry Challenges
- Coating Chemist Talent Scarcity:Formulation expertise for BPA-free internal lacquers resides with a narrow cohort of specialists, constraining R&D velocity for mid-tier converters.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA, EFSA, and SAMR food contact approvals extend product launch cycles by 18-24 months for novel coating systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cylindrical Cans Market |
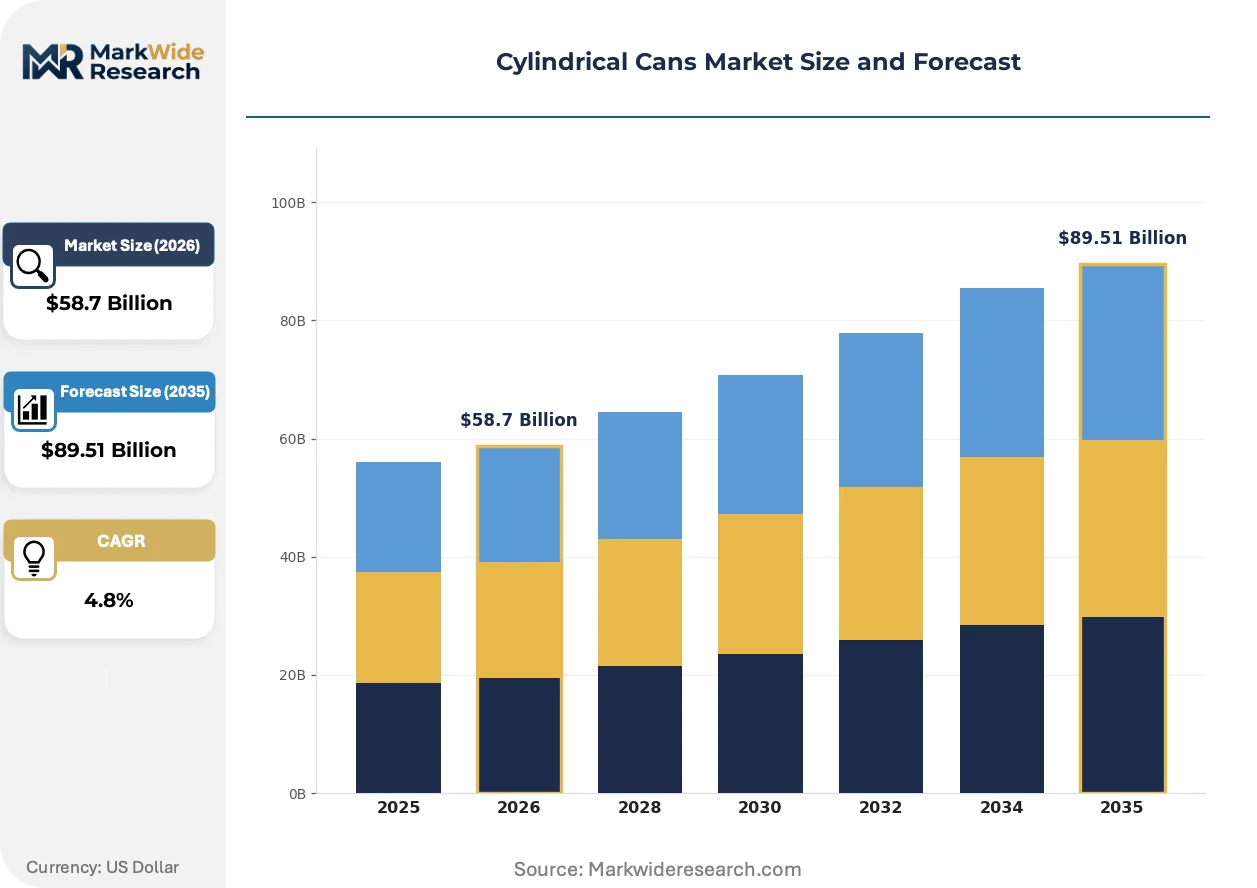
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $89.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Tinplate, BPA-Free Application: Beverages, Food, Chemicals, Personal Care Capacity: 250ml, 500ml, 1L, 2L End User: Retail, Food Service, Industrial, Home Use |
| Companies Covered | Ball Corporation, Crown Holdings Inc., Ardagh Group, Silgan Holdings Inc., Can-Pack S.A., Huhtamaki Group, Consolidated Container Company, Graphic Packaging International, Shanghai Metal Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cylindrical Cans Market Strategic Shifts
Digital printing and smart packaging integration are compressing minimum order quantities and enabling batch-level traceability, while regulatory chemistry shifts and retail channel fragmentation are forcing simultaneous adaptation across specification, logistics, and brand communication layers.
Polymer-based internal powder coatings are replacing solvent-borne liquid systems for high-acid beverage contact. Craft brewers and functional drink startups are specifying these finishes for short-run SKUs with rapid flavor rotation. The elimination of thermal curing ovens and VOC capture equipment is rendering obsolete traditional wet-coating line configurations in smaller-footprint canning facilities.
EPA New Source Performance Standards for coating operations are tightening volatile organic compound emission thresholds for greenfield and modified lines. Capital expenditure requirements for thermal oxidizers and carbon capture systems are elevating entry costs for new market entrants. US-based beverage can manufacturers are consolidating coating operations into fewer, larger facilities to amortize environmental compliance infrastructure.
Direct-store-delivery beverage brands are compressing packaging specification cycles from annual to quarterly review periods. DSD distributors are demanding smaller lot sizes with variable graphic versioning for regional and seasonal programming. Mexico and Southeast Asian markets exhibit the most pronounced acceleration in short-run aluminum can procurement, reflecting fragmented retail consolidation patterns and localized brand competition.
Cylindrical Cans Market Segmentation
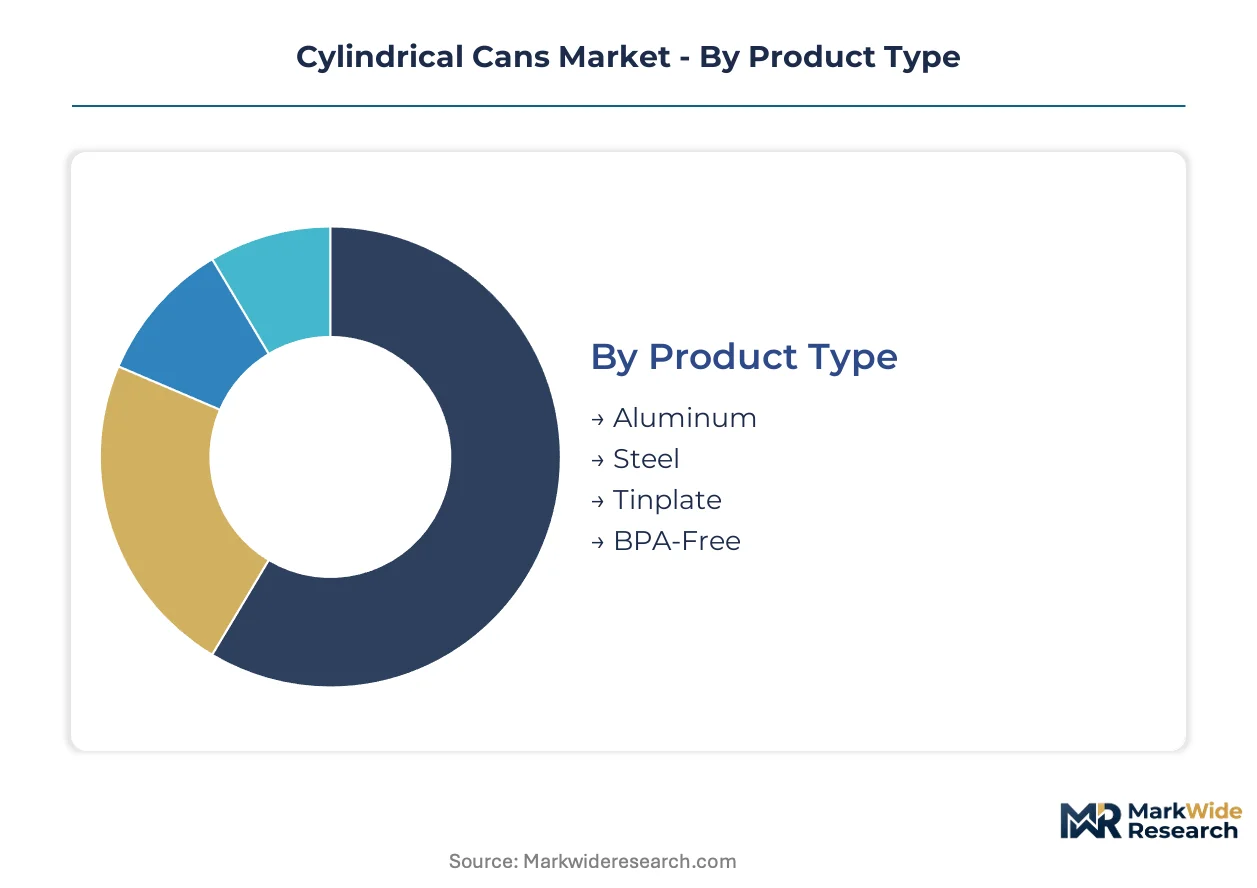
Cylindrical can specifications diverge sharply across end-use cycles, with beverage SKUs turning over quarterly and chemical formats holding specifications for years. Procurement teams must align inventory velocity with tooling amortization across these heterogeneous demand patterns.
Product Type:
Cycle times compress from aluminum beverage cans at weeks to tinplate food formats at months, creating divergent working capital intensity across converter portfolios.
- Aluminum:Two-piece drawn-and-ironed construction delivers sub-0.3mm wall thickness for carbonated beverage pressure containment. Demand concentrates in China's eastern manufacturing corridor where domestic beverage brands scale canning capacity for carbonated soft drinks and beer. Lightweighting advantages in logistics networks sustain premium positioning against alternative substrates.
- Steel:Three-piece welded construction with tin or chrome coating provides structural rigidity for vacuum-packed food preservation. European processed vegetable and ready-meal producers anchor demand as extended shelf-life requirements tighten across ambient food logistics. REACH compliance costs for coating migration limits compress margins for non-specialized converters.
- Tinplate:Cold-rolled low-carbon steel with electrolytic tin coating offers solderability and corrosion resistance for high-acid food contact. Traditional specifications persist in legacy canning infrastructure across Southeast Asian fish and fruit processing clusters.
- BPA-Free:Polyester and epoxy-phenolic lacquer systems replace bisphenol-A-based coatings for food safety compliance. EPA VOC emission standards and EFSA migration limits are accelerating specification transitions in North American and European beverage canning lines.
Aluminum anchors the volume base while BPA-Free specifications gain share at the steepest rate.
Application:
Margin structures stratify from commodity beverage volumes to premium chemical containment, with specification stringency scaling inversely with price sensitivity.
- Beverages:Carbonated soft drinks, beer, and energy drinks dominate aluminum two-piece consumption. China's SAMR enforces GB standards for food contact materials that foreign exporters must satisfy for market access. Direct-store-delivery brands compress specification cycles from annual to quarterly review periods.
- Food:Processed vegetables, ready meals, and pet food sustain three-piece steel and tinplate demand. Retort sterilization requirements drive wall thickness specifications and double-seam integrity standards for ambient distribution without refrigeration.
- Chemicals:Paints, coatings, and agricultural formulations command premium pricing for corrosion-resistant internal lacquers and UN-certified structural ratings. Lower price sensitivity among industrial buyers sustains margin pools despite smaller volume bases.
- Personal Care:Aerosol hairsprays, deodorants, and shaving foams specify pressure-rated aluminum monobloc construction. Propellant compatibility testing and valve crimp specifications extend qualification timelines versus standard beverage formats.
Beverage applications anchor the volume base while chemical packaging climbs the fastest on value-per-unit metrics.
Capacity:
Volume scale economics favor mid-range formats where production line utilization peaks, while niche sizes fragment tooling amortization across shorter production runs.
- 250ml:Single-serve beverage and personal care formats target on-premise consumption and travel retail channels. Premium positioning in energy drinks and functional beverages sustains per-unit margins despite lower absolute volume.
- 500ml:Standard beer and carbonated soft drink specification across retail and food service channels. Ball Corporation and Crown Holdings concentrate forming capacity around this format for maximum line efficiency.
- 1L:Family-size beverage and edible oil applications in emerging market retail expansion. India's organized grocery penetration is creating first-time canning demand for domestic brands in this capacity tier.
- 2L:Industrial chemical and bulk food service formats with specialized handling requirements. Lower production frequency and custom seaming equipment elevate unit costs versus standard beverage lines.
500ml anchors the volume base while 250ml expands most quickly in premium beverage segmentation.
End User:
Channel concentration shapes specification stability, with industrial procurement holding formats for years and retail cycling graphics seasonally.
- Retail:Supermarket, convenience, and e-commerce grocery channels drive high-volume aluminum beverage demand. Mexico and Southeast Asian markets exhibit pronounced acceleration in short-run aluminum can procurement with variable graphic versioning.
- Food Service:Restaurants, catering, and institutional kitchens specify food cans for back-of-house ingredient storage. Extended shelf-life requirements sustain tinplate specifications despite higher unit costs versus flexible alternatives.
- Industrial:Manufacturing and agricultural operations procure chemical containment with corrosion resistance priorities. UN certification and hazardous material labeling requirements extend supplier qualification timelines.
- Home Use:Direct-to-consumer and subscription formats in craft beverages and specialty foods. Digital printing integration enables batch-level traceability and compressed minimum order quantities for micro-brand launches.
Retail anchors the volume base while home use gains share fastest in craft and specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in cylindrical cans diverge sharply by substrate: aluminum flows concentrate in primary metal trade corridors, while finished can exports track beverage brand manufacturing footprints. China's net exporter position in two-piece aluminum beverage cans contrasts with Europe's coating chemistry import dependency.
United States
Carbonated soft drink and craft beer canning lines drive aluminum two-piece consumption across the Midwest and Southeast manufacturing belts. EPA New Source Performance Standards tighten VOC emission thresholds for coating operations, elevating capital requirements for greenfield facilities. Chicago and Milwaukee anchor beverage can forming clusters where Ball Corporation and Crown Holdings concentrate production capacity.
China
Domestic beverage brands scaling canning capacity for carbonated drinks and beer concentrate demand in the Yangtze River Delta and Pearl River Delta corridors. SAMR enforces GB standards for food contact materials that foreign coating suppliers must satisfy for market access. Zhengzhou and Guangzhou host expanding two-piece aluminum forming operations serving local brand procurement.
Germany
Processed vegetable and ready-meal producers sustain tinplate and steel can demand for ambient food preservation across Bavaria and North Rhine-Westphalia. REACH bisphenol-A restrictions on food contact surfaces accelerate BPA-free coating transitions in canning lines. Hamburg and Düsseldorf anchor coating formulation clusters where specialty resin suppliers serve European converter networks.
India
Organized retail and e-commerce grocery penetration creates first-time canning demand for edible oil and domestic beverage brands in Maharashtra and Gujarat. FSSAI food contact material standards govern import and domestic production compliance for can coatings. Mumbai and Ahmedabad concentrate forming capacity buildouts targeting 1L family-size beverage specifications.
Mexico
Direct-store-delivery beverage brands compress specification cycles and demand short-run aluminum cans with variable graphics in Mexico City and Monterrey markets. USMCA rules of origin influence aluminum sheet sourcing patterns for cross-border can production. Nuevo León hosts expanding two-piece forming operations serving North American beverage brand procurement.
Cylindrical Cans Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in coating chemistry and metal forming equipment. The vendor base stratifies between capital-intensive integrated converters and regional specialists in steel or tinplate formats. Two archetypes dominate: aluminum beverage can integrators with captive metal supply agreements, and steel food can specialists with retort sterilization expertise. Competitive moves concentrate on multi-year aluminum offtake contracting and coating line consolidation for environmental compliance scale.
Among North American integrated converters, Ball Corporation exemplifies the aluminum beverage can archetype with upstream metal sourcing control, while Crown Holdings occupies a parallel position in geographic coverage density. Ardagh Group represents the steel and tinplate specialization vector with food preservation format concentration. These three entities anchor distinct competitive positions without overlapping segment focus.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings Inc. |
| Ardagh Group |
| Silgan Holdings Inc. |
| Can-Pack S.A. |
| Huhtamaki Group |
| Consolidated Container Company |
| Graphic Packaging International |
| Shanghai Metal Corporation |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta aluminum rolling capacity governs downstream pricing power for beverage can converters across Asia-Pacific. Contract structures for two-piece aluminum sheet now embed volatility clauses tied to LME benchmarks, transferring input risk from mills to brand owners.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure with quarterly renegotiation windows. Price differentiation separates corrosion-resistant chemical grades from standard beverage specifications, with certification tier and volume scale as secondary drivers. Cost compression in standard aluminum beverage cans is intensifying because domestic Chinese brands are consolidating procurement volumes. Food service distributors exhibit highest price sensitivity due to thin margins in institutional catering, while chemical containment buyers show lowest sensitivity given UN certification requirements.
Supply Chain Analysis
Export-control regimes on specialty coating resins from Germany and Japan are constraining BPA-free formulation flows to non-aligned converters. Primary aluminum supply concentrates in China, Russia, and Australia, while rolling mill capacity clusters in China, South Korea, and the United States. Raw material dependencies include aluminum ingot, tinplate coil, and epoxy-phenolic lacquer systems. Single-source vulnerability in German specialty resin production creates chokepoint exposure for European coating transitions. Distribution runs through multi-year offtake agreements directly from rolling mills to integrated converters, bypassing merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
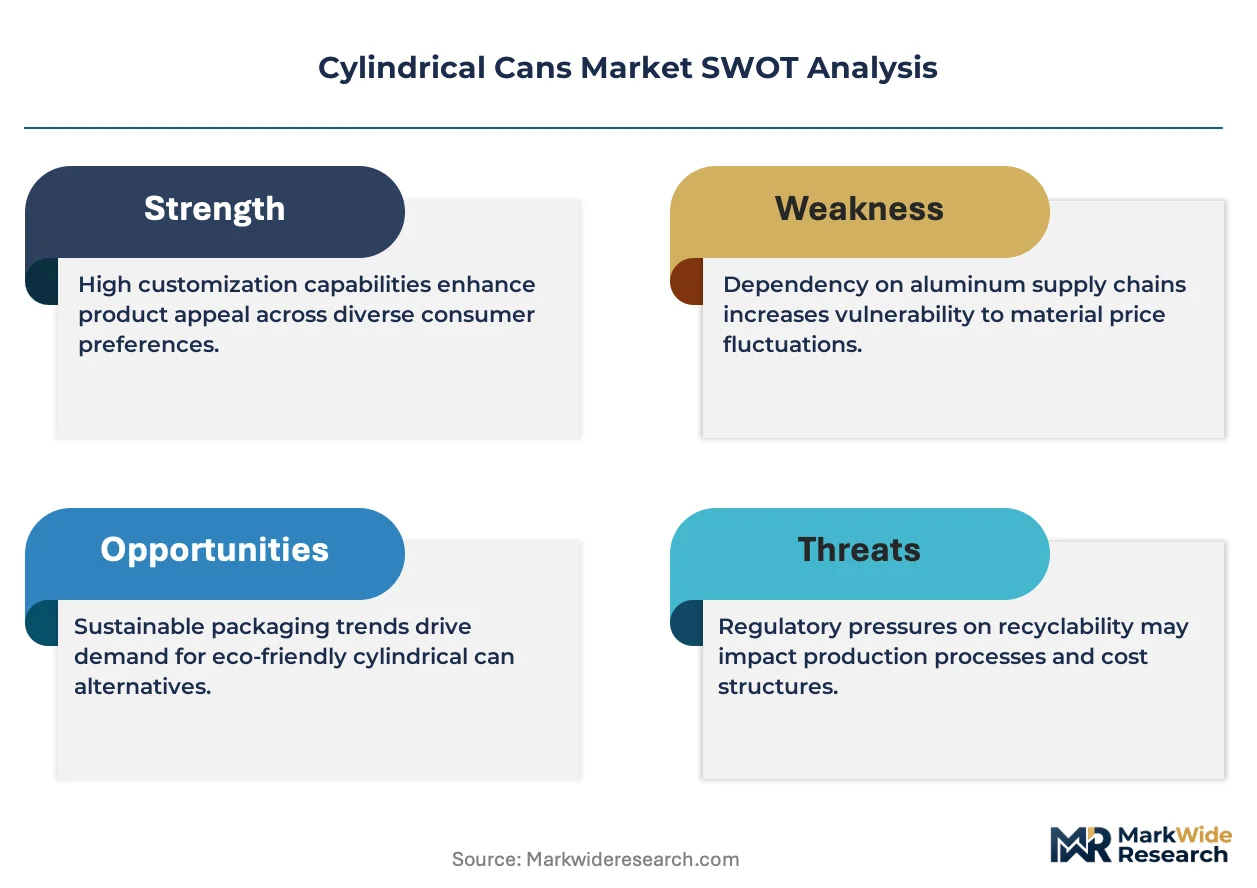
Environmental compliance services represent a faster-expanding recurring-revenue layer than hardware sales, as coating line retrofits for EPA VOC standards generate multi-year service attach opportunities.
For Market Incumbents: Build captive aluminum supply moats through multi-year offtake agreements with Yangtze River Delta rolling mills. Secure BPA-free coating formulation expertise through targeted hiring from German specialty resin suppliers. Defend against glass and PET substitution in premium beverage channels by accelerating digital printing capabilities for short-run versioning. For New Entrants and Emerging Players: Build out aseptic canning convergence capabilities for ambient nutritional beverages, where retort sterilization integration creates white-space opportunity. Target India's 1L family-size edible oil segment in Maharashtra and Gujarat, where organized retail penetration is creating first-time canning demand. Pursue equipment-as-a-service models to lower capital barriers for craft beverage micro-brands. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among coating formulation specialists with multi-jurisdiction certification portfolios. Long-term viability favors converters with backward integration into aluminum sourcing and captive environmental compliance infrastructure. Monitor EPA New Source Performance Standards implementation timelines as inflection signal for consolidation acceleration among sub-scale coating operations.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Aluminum Offtake Agreement | Ball Corporation leverages Yangtze River Delta capacity to lock in lightweighting inputs ahead of competitor expansion. |
| BPA-Free Coating Line Retrofit | EPA VOC compliance windows create service attach revenue for environmental technology providers serving Crown Holdings facilities. |
| Aseptic Canning Convergence | Retort sterilization integration enables Ardagh Group to capture ambient nutritional beverage demand without refrigeration infrastructure. |
| Digital Printing Platform Deployment | Direct-store-delivery brands in Mexico compress specification cycles through variable graphic versioning on short-run aluminum cans. |
| India Forming Capacity Buildout | Can-Pack S.A. targets Maharashtra and Gujarat to capture first-time edible oil canning demand from organized retail expansion. |
Study Parameters
Operator-level perspectives from beverage brand procurement directors, coating line plant managers, aluminum rolling mill sales executives, and EPA compliance officers anchored the qualitative base. Primary interview findings were cross-validated against secondary sources including SEC 10-K filings from integrated converters, SAMR GB standard publications, ECHA REACH restriction dossiers, and customs trade data for aluminum sheet flows. Bottom-up segment sizing was triangulated with top-down macroeconomic anchoring.
Scenario-bracketing across regulatory implementation timelines, aluminum LME price bands, and coating chemistry transition speeds framed the analytical envelope. Segmentation dimensions modeled include substrate type, application end-use, capacity tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trend analysis. Industry-specific inputs incorporated beverage brand canning capacity buildout announcements and EPA New Source Performance Standards compliance deadlines.
Stress conditions across aluminum price volatility, REACH bisphenol-A restriction acceleration, and China domestic brand procurement consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding coating chemistry substitution rates and regional certification timeline convergence. Material shifts in EPA VOC emission threshold stringency or SAMR food contact material enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Disposable Cups and Lids Market
Containers
Container Stacking Machine Market
Containers
Global Food Containers Market
Containers
Light Resistant Containers Market
Containers
Thin Wall Containers Market
Containers
Car Lube Container Market
Containers
Global Styrene Compartment Boxes Market
Containers
Trigger Sprayer Market
Containers
Foldable Steel Containers Market
Containers
Latin America Intermediate Bulk Container Liner Market
Containers
Modular Container Market
Containers
Snap Secure Containers Market
Containers
Containerboard Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Pocket Containers Market
Containers
USA and Canada Packer Bottle Market