
 India Metal Cans Market | 2026-2036
India Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
India Metal Cans Market Foresight
Modern trade and e-commerce distribution is reshaping how metal cans reach Indian consumers. Crown Holdings Inc leverages its beverage can technology leadership to sustain supply relationships with major bottlers. Oricon Enterprises Limited anchors its position through integrated tinplate manufacturing in western India. Kaira Can Company Limited specializes in dairy and processed food canisters, competing on regional proximity to Gujarat's milk cooperatives.
Metal cans are cylindrical containers fabricated from aluminum, steel, or tinplate, typically featuring double-seamed ends and interior linings to prevent corrosion and preserve contents. They are engineered to withstand internal pressure, block light and oxygen, and enable thermal processing for shelf-stable packaging across food, beverage, and industrial applications. Aluminum cans dominate beverage applications due to lightweight properties and infinite recyclability, while tinplate cans retain structural importance in processed food and aerosol segments where barrier performance commands premium positioning. Steel cans occupy industrial and household product applications where cost efficiency and durability outweigh weight considerations.
BIS standards for food-contact metals, CDSCO guidelines for pharmaceutical aerosol containers, and FSSAI packaging safety regulations collectively determine material grades, coating chemistries, and migration limits for can manufacturers. The PLI scheme for specialty steel and aluminum downstream products is incentivizing domestic substrate production, altering raw material sourcing economics for can makers. Stakeholders must monitor evolving extended producer responsibility frameworks and state-level plastic substitution mandates that will redirect packaging procurement toward metal alternatives.
Market Dynamics
Food & Beverage manufacturers in Maharashtra and Gujarat are consolidating procurement volumes around beverage bottling clusters and dairy cooperatives, tightening supply-side concentration and reshaping competitive access for can suppliers.
Growth Catalysts
- PLI scheme for specialty steel:Domestic substrate production incentives are altering raw material sourcing economics for can makers, reducing import dependence.
- FSSAI packaging safety regulations:Tightening food-contact standards are disqualifying non-compliant packaging alternatives and redirecting procurement toward certified metal can suppliers.
- Maharashtra beverage bottling clusters:Concentrated demand from carbonated soft drink and beer manufacturers is anchoring regional capacity expansion and supplier co-location.
Market Restraints
- Tinplate price volatility:Global steel substrate fluctuations transmit directly to can manufacturing costs, compressing margin buffers for non-integrated producers.
- BIS certification timelines:Extended approval cycles for new coating chemistries and material grades delay product launches and lock out speculative innovation.
- Flexible pouch substitution:Retortable plastic laminates are capturing shelf-stable food segments where barrier performance requirements have relaxed.
Strategic Opportunities
- Uttar Pradesh and Bihar underpenetration:Low canned beverage consumption per capita relative to western India offers whitespace for distribution network expansion.
- E-commerce direct-to-consumer channels:Platform logistics are enabling smaller batch sizes and specialized can formats previously uneconomical through traditional retail.
- Extended producer responsibility frameworks:Pending state-level plastic substitution mandates will redirect packaging procurement toward infinitely recyclable aluminum alternatives.
Industry Challenges
- Coating chemistry expertise scarcity:Qualified formulators capable of optimizing interior linings for acidic and sulfur-rich food matrices remain concentrated among legacy suppliers.
- Double-seam equipment capex intensity:High-speed canning line investments require multi-year volume commitments that strain mid-tier food processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Metal Cans Market |
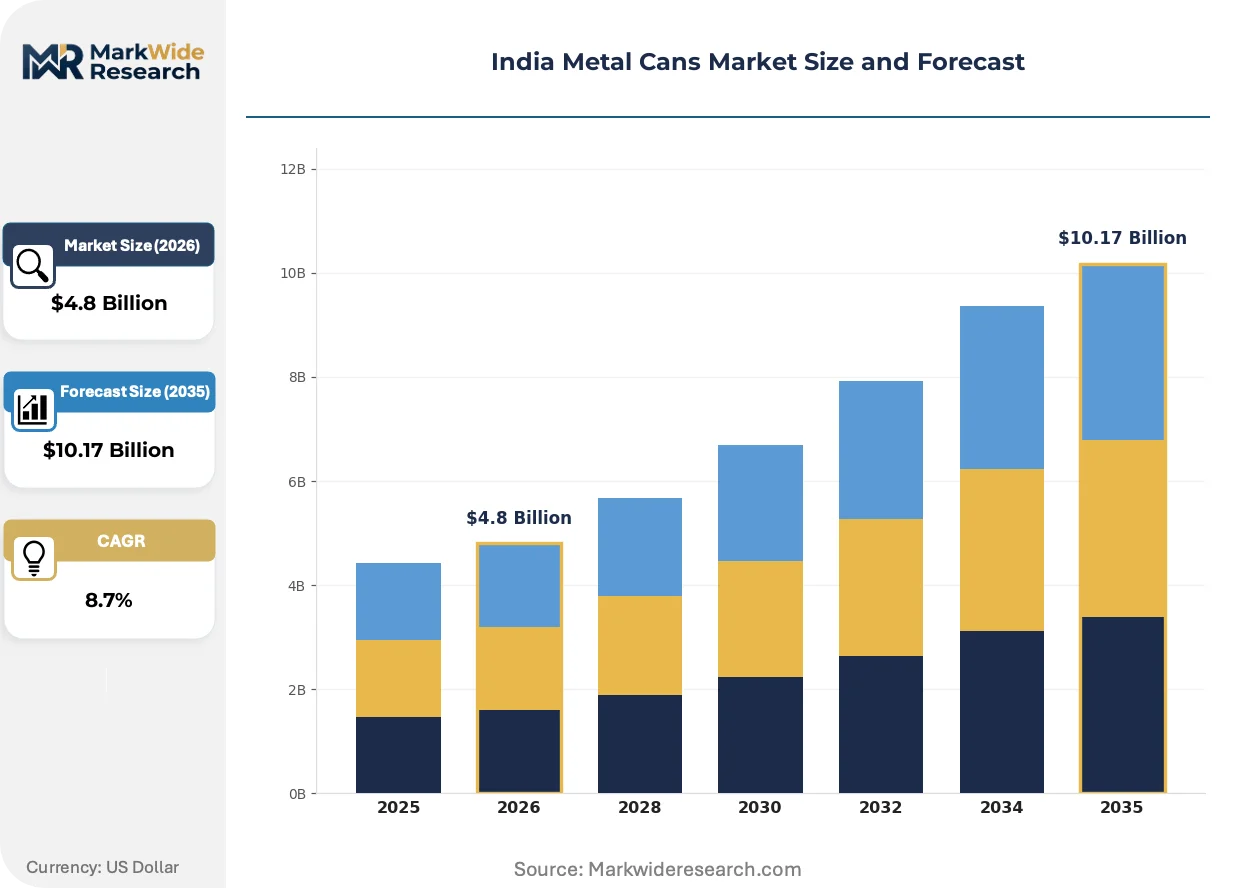
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Tinplate Cans, Composite Cans End Use Industry: Food & Beverage, Personal Care, Household Products, Industrial Goods Size: Small Cans, Medium Cans, Large Cans, Extra-Large Cans Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Crown Holdings Inc, Oricon Enterprises Limited, Kaira Can Company Limited, Can-Pack S.A., Shetron Limited, Hindustan Tin Works Ltd, Casablanca Industries Pvt Ltd, Silgan Containers LLC, Ball Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Metal Cans Market Shifts & Advancements
Digital manufacturing integration and regulatory tightening are compressing product development cycles while opening differentiation pathways for suppliers capable of rapid specification turnaround.
Lightweighting algorithms and finite element modeling are virtualizing traditional trial-and-error can design processes. Beverage bottlers in Gujarat are adopting simulation-driven wall-thickness optimization to reduce aluminum consumption per unit. This technology is virtualizing the historical reliance on physical prototyping, collapsing development timelines from months to weeks.
FSSAI has proposed stricter migration limits for epoxy-based interior coatings, accelerating industry transition toward polyester and acrylic alternatives. Can makers are reformulating product lines to preempt compliance deadlines and avoid batch disqualification. Dairy and infant food segments face the most acute reformulation pressure given their zero-tolerance regulatory thresholds.
Modern trade consolidation is concentrating buyer power among organized retail chains and quick-commerce platforms. Traditional distributor networks serving kirana stores are losing share to direct supplier-platform arrangements. This channel rotation is most visible in Mumbai, Bangalore, and Delhi NCR where delivery-time compression has become the primary competitive variable.
India Metal Cans Market Segmentation
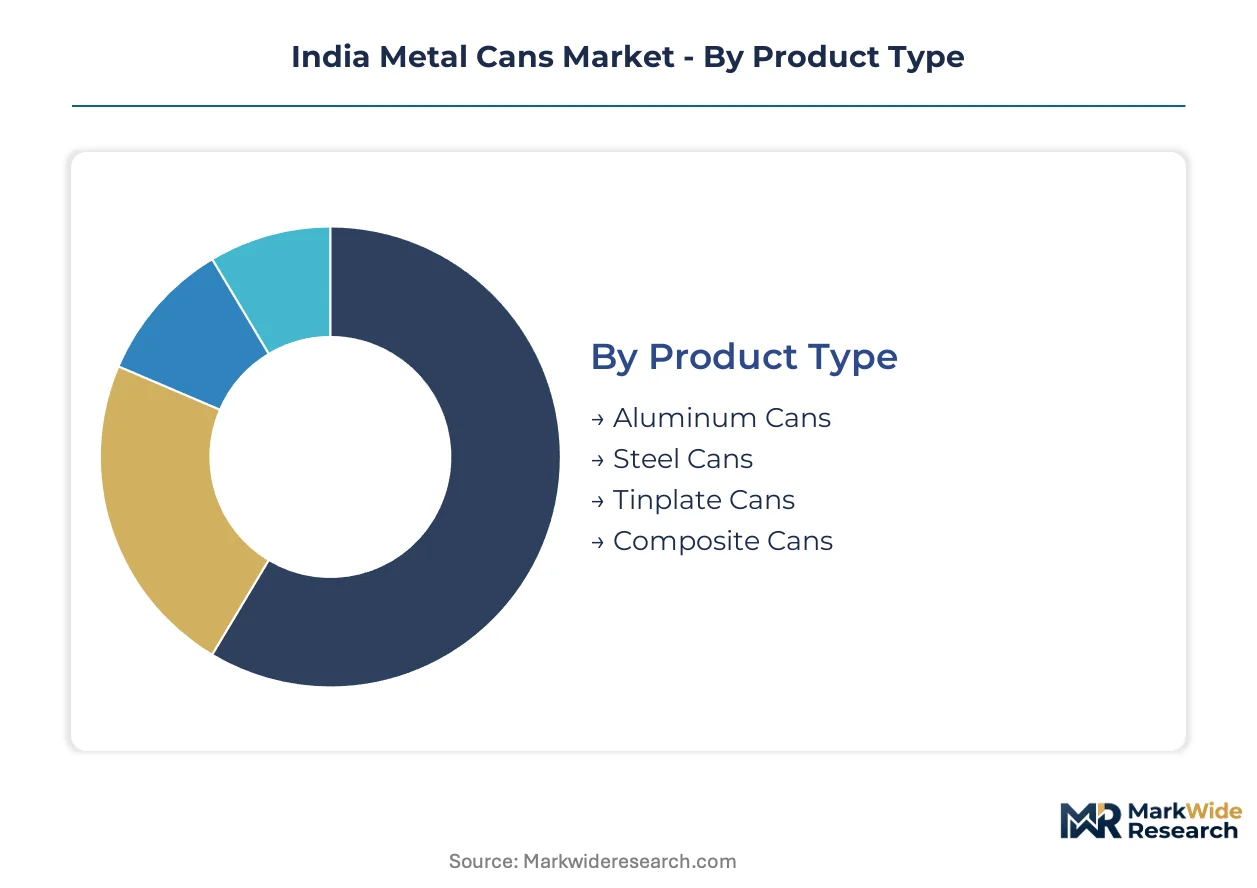
Metal can manufacturers in India configure production lines around substrate metallurgy, end-use performance specifications, and channel logistics requirements. Segmentation discipline separates commodity beverage volumes from specialized food-contact and industrial applications with divergent coating and seam specifications.
Product Type:
Cost tier differentiation across metal substrates determines raw material sourcing strategies and margin profiles for Indian can makers.
- Aluminum Cans:Lightweight, infinitely recyclable beverage containers with drawn-and-ironed wall construction. Demand concentrates in Maharashtra's carbonated soft drink and beer bottling clusters where weight-based logistics savings justify aluminum premiums.
- Tinplate Cans:Cold-rolled steel substrate with electrolytic tin coating provides superior barrier performance for acidic and sulfur-rich food matrices. Gujarat's dairy cooperatives and processed food processors anchor procurement volumes given FSSAI's stringent migration limits for infant nutrition applications.
- Steel Cans:Uncoated or lacquered carbon steel for industrial and household product applications where cost efficiency outweighs weight considerations.
- Composite Cans:Spiral-wound paperboard bodies with metal ends for dry goods and specialty food segments requiring decorative flexibility.
Aluminum commands the established base. The steepest expansion runs through tinplate as BIS tightens food-contact compliance thresholds.
End Use Industry:
Application-specific performance requirements create divergent specification regimes across consumer and industrial segments.
- Food & Beverage:Thermal processing compatibility and interior lining integrity for shelf-stable packaging. Maharashtra beverage bottlers and Gujarat dairy processors drive volume concentration with divergent substrate preferences.
- Personal Care:Aerosol propellant pressure resistance and valve compatibility for deodorants and hair sprays. CDSCO guidelines for pharmaceutical-grade containers elevate coating chemistry requirements.
- Household Products:Chemical resistance for solvents, polishes, and insecticides where cost minimization dominates procurement.
- Industrial Goods:Structural durability for lubricants, adhesives, and coatings with less stringent food-contact regulatory burden.
Food & Beverage retains volume leadership. Personal Care is climbing the fastest on aerosol format adoption in urban markets.
Size:
Volume-to-surface ratio economics and filling line compatibility shape can dimension selection across customer segments.
- Small Cans:Single-serve beverage and personal care formats with premium positioning. Quick-commerce platforms in Mumbai and Delhi NCR are driving demand for portion-controlled packaging.
- Medium Cans:Standard food and beverage volumes balancing material efficiency with retail shelf presence.
- Large Cans:Family-size beverage and institutional food service applications.
- Extra-Large Cans:Industrial and bulk food service formats with specialized handling equipment requirements.
Medium cans anchor production throughput. Small formats are gaining share fastest on e-commerce logistics optimization.
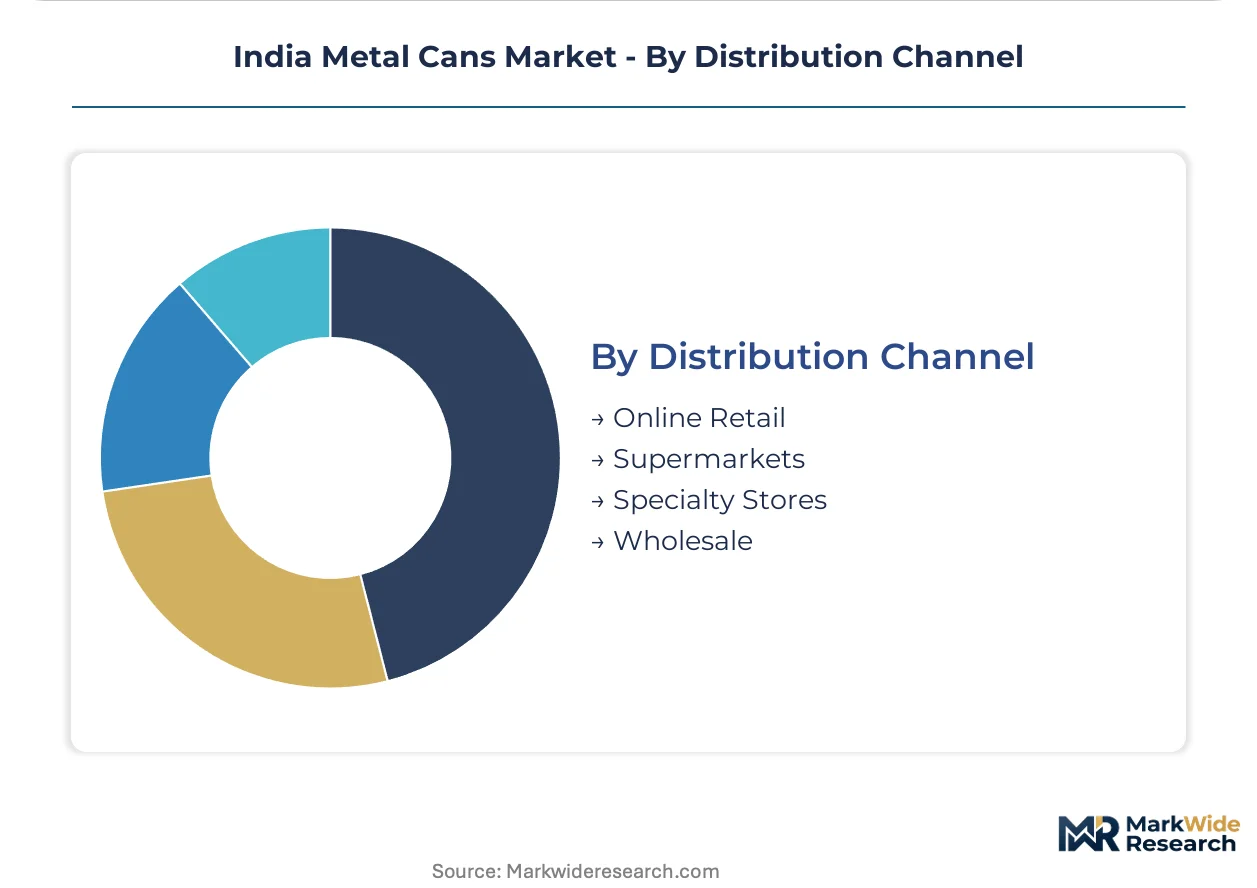
Distribution Channel:
Customer type and order fragmentation determine channel economics and working capital intensity for can suppliers.
- Supermarkets:Organized retail chains in Bangalore and Delhi NCR consolidating procurement through direct supplier arrangements with volume commitment structures.
- Online Retail:Platform-direct fulfillment enabling smaller batch sizes and specialized formats previously uneconomical through traditional wholesale.
- Specialty Stores:Premium and imported product retailers requiring decorative customization and shorter production runs.
- Wholesale:Traditional distributor networks serving kirana stores with standardized formats and extended payment terms.
Supermarkets dominate value capture. Online retail is expanding most quickly on quick-commerce platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Maharashtra and Gujarat where beverage bottling clusters and dairy cooperatives anchor procurement volumes, while eastern and northern states operate at a discount due to fragmented demand and higher logistics costs.
Maharashtra
Carbonated soft drink and beer manufacturers drive concentrated demand for aluminum beverage cans in Mumbai and Pune. FSSAI packaging safety regulations enforce strict migration limits for food-contact materials. Thane and Nashik bottling corridors are expanding canning line capacity to serve organized retail chains.
Gujarat
Dairy cooperatives and processed food processors anchor tinplate procurement for infant nutrition and shelf-stable milk products. BIS certification requirements for food-contact metals tighten compliance thresholds for regional suppliers. Anand and Vadodara milk processing clusters are upgrading to epoxy-free interior coatings ahead of regulatory deadlines.
Karnataka
Bangalore quick-commerce platforms are driving demand for small-format beverage cans in premium positioning. PLI scheme incentives for specialty steel are altering raw material sourcing economics for regional can makers. The city is emerging as a testbed for e-commerce-optimized packaging formats.
Uttar Pradesh
Low per-capita canned beverage consumption relative to western India offers whitespace for distribution network expansion. State-level plastic substitution mandates are redirecting procurement toward metal alternatives in urban centers. Lucknow and Kanpur are seeing initial quick-commerce platform consolidation for packaged goods.
Tamil Nadu
Chennai industrial corridors are developing aerosol can capacity for personal care manufacturers serving southern markets. CDSCO guidelines for pharmaceutical-grade containers elevate coating chemistry requirements for regional producers. The state is leveraging port infrastructure for tinplate substrate imports.
India Metal Cans Market Competitive Landscape
Global technology leaders and domestic integrated manufacturers split the market between premium beverage applications and cost-optimized food packaging. The structure tilts toward consolidation in aluminum beverage cans while remaining fragmented in tinplate food segments. Two archetypes dominate: multinational technology licensors with proprietary lightweighting algorithms, and domestic mid-caps with backward integration into tinplate substrate. Capacity expansion and coating chemistry reformulation represent the dominant competitive moves as suppliers preempt FSSAI compliance deadlines.
Within the multinational tier, Crown Holdings Inc and Ball Corporation exemplify technology-led positioning through beverage can engineering leadership. Oricon Enterprises Limited anchors the domestic integrated manufacturer archetype through western India production presence. Kaira Can Company Limited occupies a specialist position serving dairy and processed food segments with regional proximity to Gujarat's milk cooperatives.
| Leading Market Players |
|---|
| Crown Holdings Inc |
| Oricon Enterprises Limited |
| Kaira Can Company Limited |
| Can-Pack S.A. |
| Shetron Limited |
| Hindustan Tin Works Ltd |
| Casablanca Industries Pvt Ltd |
| Silgan Containers LLC |
| Ball Corporation |
| Others |
Supply & Pricing Matrix
Tinplate price volatility determines both margin compression severity for non-integrated producers and the geographic clustering of competitive capacity. BIS certification timelines for new coating chemistries create regulatory chokepoints that widen pricing spreads between compliant and non-compliant supplier tiers.
Pricing Analysis
The customization-premium spread separates standard beverage can formats from configured-to-order food-contact specifications. Three-tier pricing structure across premium, standard, and economy levels tracks FSSAI certification grade and interior lining complexity. Pricing pressure stems from retortable plastic laminate substitution in shelf-stable segments. Small-format beverage processors exhibit highest price sensitivity due to quick-commerce volume fragmentation, while dairy cooperatives accept premiums for infant nutrition compliance.
Supply Chain Analysis
Contract-manufacturing concentration rests with Crown Holdings and Ball Corporation for beverage can technology, while Oricon Enterprises anchors domestic tinplate substrate supply. Raw material dependencies draw from imported aluminum ingot, electrolytic tin coating, and specialty steel under PLI scheme incentives. Single-source vulnerability concentrates in epoxy-free interior coating formulators. Distribution runs through direct supplier arrangements with organized retail chains and quick-commerce platforms, bypassing traditional kirana distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating chemistry expertise scarcity constrains competitive entry, as qualified formulators capable of optimizing interior linings for acidic and sulfur-rich food matrices remain concentrated among legacy suppliers with decades of FSSAI compliance experience.
For Market Incumbents: Entrench supply relationships with Maharashtra beverage bottlers through co-located canning line investments. Secure captive tinplate substrate supply via backward integration or long-term offtake agreements to buffer against global steel price swings. Preempt FSSAI migration limit deadlines by accelerating polyester and acrylic coating reformulation ahead of regulatory enforcement. For New Entrants and Emerging Players: Establish a beachhead in Uttar Pradesh and Bihar distribution networks where per-capita canned beverage consumption remains underdeveloped relative to western India. Target quick-commerce platform direct-supplier arrangements in Lucknow and Kanpur as channel entry points. Leverage e-commerce-optimized small-format production capabilities to serve platform logistics requirements with minimal legacy retail infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated manufacturers with captive substrate supply and established BIS certification portfolios. Long-term viability hinges on coating chemistry R&D capabilities and regulatory pre-approval asset bases. Monitor FSSAI enforcement intensity on epoxy-based interior coatings as inflection indicator for reformulation-driven M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tinplate Substrate | PLI scheme incentives reduce import dependence and stabilize raw material cost structures for western India producers. |
| Epoxy-Free Coating Reformulation | FSSAI migration limit proposals accelerate industry transition toward polyester and acrylic interior lining alternatives. |
| Quick-Commerce Platform Partnership | Direct supplier arrangements with Mumbai and Delhi NCR platforms enable smaller batch sizes and specialized formats. |
| Maharashtra Bottling Cluster Expansion | Thane and Nashik capacity additions anchor regional procurement concentration for carbonated soft drink manufacturers. |
| Uttar Pradesh Distribution Network Buildout | State-level plastic substitution mandates redirect procurement toward metal alternatives in underpenetrated urban centers. |
Research Methodology
The analysis maps aluminum beverage can, tinplate food can, steel industrial can, and composite specialty can sub-sectors, each validated through production directors at can manufacturing facilities, procurement leads at Maharashtra beverage bottlers, coating chemistry formulators, and FSSAI regulatory affairs specialists. Primary interview data triangulates against secondary sources including BIS certification registries, FSSAI packaging safety notifications, PLI scheme beneficiary disclosures, and organized retail chain procurement databases. Bottom-up volume aggregation from state-level production facilities cross-checks against top-down demand estimates from end-use industry consumption patterns.
Assumption sets held PLI scheme continuation and FSSAI regulatory timelines fixed while varying raw material price trajectories and quick-commerce platform penetration rates. The analytical framework models substrate metallurgy, end-use application, can dimension, and distribution channel segmentation dimensions throughout the forecast period. CAGRs derive from installed capacity expansion schedules, per-capita consumption convergence assumptions, and substitution elasticity parameters between metal and flexible packaging alternatives.
Sensitivities concentrate around tinplate price volatility, BIS certification approval delays, and retortable plastic laminate technology advancement. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and subsidy scheme continuity. Quarterly review of FSSAI coating migration limit proposals and state-level extended producer responsibility framework implementations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Aluminum Foil Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Metal Containers Market
Metal Packaging
Metal Aerosol Packaging Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Novelty Tins Market
Metal Packaging
Cans Market