
 Pocket Containers Market | 2026-2036
Pocket Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Pocket Containers Market Analytics
Multi-source procurement toward regional resin suppliers is realigning cost structures across the pocket containers value chain. Gerresheimer AG leverages its glass-forming expertise to dominate pharmaceutical-grade mini-container segments. Plastipak Packaging anchors North American blow-molding capacity for single-serve beverage formats. Silgan Holdings specializes in metal closure systems that extend shelf stability for condiment and sauce applications.
Pocket containers denote small-format, portable vessels engineered for individual-portion containment, typically ranging from 15 mL to 500 mL capacity and manufactured through injection molding, blow molding, or thermoforming processes depending on material and barrier requirements. Plastic formats lead unit volume due to polyethylene terephthalate and polypropylene cost efficiency, though silicone segments gain traction in reusable travel accessories where foldability and temperature resistance command premium positioning. Food storage applications concentrate margin pools in barrier-enhanced multilayer constructions, while personal care segments favor glass and aluminum for perceived quality differentiation.
FDA food-contact substance notifications govern polymer selection and additive migration limits for US-bound products, while EU REACH and F-Gas Regulation constrain fluorinated barrier coatings and propellant choices across European supply chains. ISO 22000 and BRCGS certification requirements shape market access for food-contact manufacturers serving retail private-label programs. Stakeholders must monitor evolving extended producer responsibility frameworks and chemical disclosure mandates to preempt compliance-driven reformulation cycles.
Market Dynamics
Extended producer responsibility mandates are forcing rapid material transitions across pocket container supply chains, with EU Green Deal targets and US state-level plastic bans accelerating investment in mono-material and bio-based alternatives.
Growth Catalysts
- Urban Commuter Lifestyles:Dense metropolitan populations in Germany, Japan, and South Korea generate sustained demand for single-serve food and beverage formats. Precision molding clusters near Frankfurt and Osaka deliver sub-48-hour fulfillment cycles for quick-service restaurant chains.
- FDA Food-Contact Modernization:Streamlined substance notification pathways reduce polymer approval timelines from 24 months to 12 months. US-based converters expand barrier-enhanced PET capacity for condiment and sauce applications.
- Silicone Reusability Premium:Temperature-resistant foldable formats command 3-4x price multiples in travel accessories and outdoor recreation segments. Japanese and South Korean consumers drive category expansion through gift-giving and subscription box channels.
Market Restraints
- Resin Price Volatility:Propylene and ethylene feedstock swings compress converter margins by 8-15 percentage points during petrochemical cycle peaks. Hedging instruments remain underutilized among mid-tier blow-molding specialists.
- Fluorinated Barrier Constraints:EU F-Gas Regulation and state-level PFAS restrictions in California, Maine, and Washington eliminate per- and polyfluoroalkyl substances from high-barrier food-contact applications. Multilayer coextrusion alternatives require capital-intensive retooling.
- Aluminum Substitution Threat:Infinitely recyclable metal formats gain shelf space in premium personal care and pharmaceutical mini-containers. Glass-forming expertise at specialized German and Italian facilities enables thin-wall aluminum migration.
Strategic Opportunities
- Indian Quick-Service Restaurant Expansion:FSSAI-compliant localized production addresses 400+ million urban consumer base. Domestic injection molding capacity in Pune and Ahmedabad scales to serve pan-Asian export demand.
- EU CSRD-Driven Circularity:Corporate sustainability reporting mandates create procurement preference for post-consumer recycled content and design-for-recycling formats. Premium brand owners specify mono-material constructions with digital watermark traceability.
- Pharmaceutical-Grade Mini-Containers:Blow-fill-seal integration with biologic stability requirements opens adjacent revenue pools. ISO 15378 certification barriers protect margin structures for qualified European and North American converters.
Industry Challenges
- Migration Testing Bottlenecks:FDA and EFSA notification backlogs extend product launch timelines by 6-9 months. Specialized toxicology consulting capacity concentrates in Basel, Rotterdam, and Washington DC metro areas.
- Legacy Thermoforming Asset Stranding:Single-layer PS and EPS capacity faces accelerated obsolescence under single-use plastic directives. Site remediation and workforce retraining costs burden family-owned European converters.
- Digital Print Integration Complexity:Direct-to-object decoration on curved mini-container surfaces requires vision-system calibration and ink adhesion chemistry coordination. Brand owner artwork approval cycles conflict with just-in-time production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pocket Containers Market |
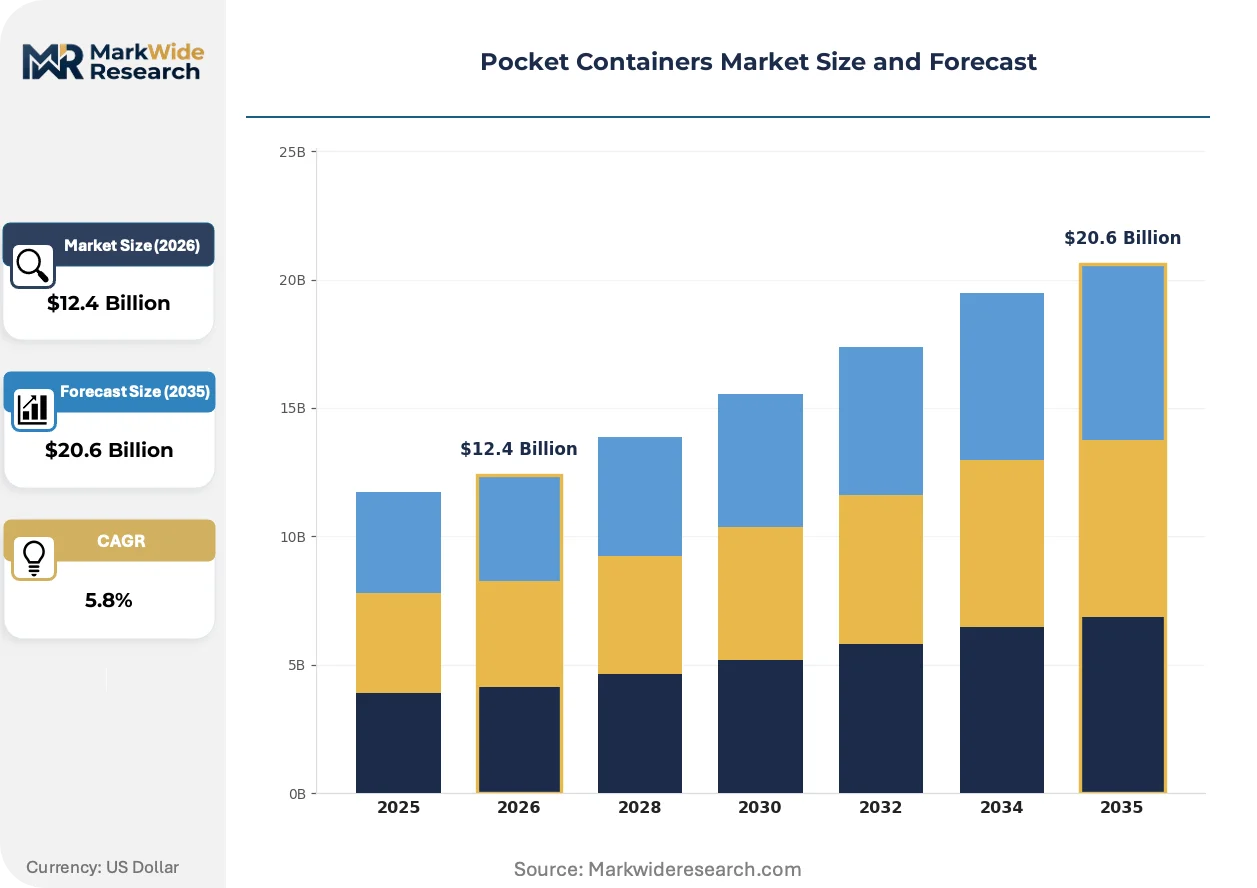
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Plastic, Glass, Silicone Size: Small, Medium, Large, Extra Large Application: Food Storage, Liquid Transport, Travel Accessories, Personal Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Gerresheimer AG, Alpha Packaging Holdings, APTACA Spa, USON Plast, Graham Packaging, Plastipak Packaging, Tupperware Brands Corporation, CKS Packaging, Silgan Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pocket Containers Market Evolving Landscape
Material science breakthroughs and regulatory disclosure mandates are compressing traditional format lifecycles, with sustainability credentials now functioning as primary purchase qualifiers rather than secondary attributes.
Mono-material polyethylene terephthalate constructions with built-in oxygen scavenger functionality are overtaking multilayer EVOH-barrier formats in shelf-stable condiment applications. Japanese convenience store chains and German discount retailers specify these formats for simplified recycling stream sorting. The shift compresses converter technical service requirements while enabling closed-loop bottle-to-bottle recovery economics.
EU Digital Product Passport requirements under the Ecodesign for Sustainable Products Regulation mandate granular material composition disclosure by 2027. Pocket container manufacturers serving European retail private-label programs must deploy spectroscopic verification and blockchain-anchored chain-of-custody documentation. Food-contact applications face the steepest compliance curves due to multi-ingredient supply chain complexity.
Quick-service restaurant procurement departments now specify annual carbon intensity reductions alongside unit cost targets. Chains operating in France, the Netherlands, and California impose lifecycle assessment thresholds that disqualify virgin-only formats. Supplier scorecards weight transport emissions and renewable energy share equally with defect rates and on-time delivery performance.
Pocket Containers Market Segmentation
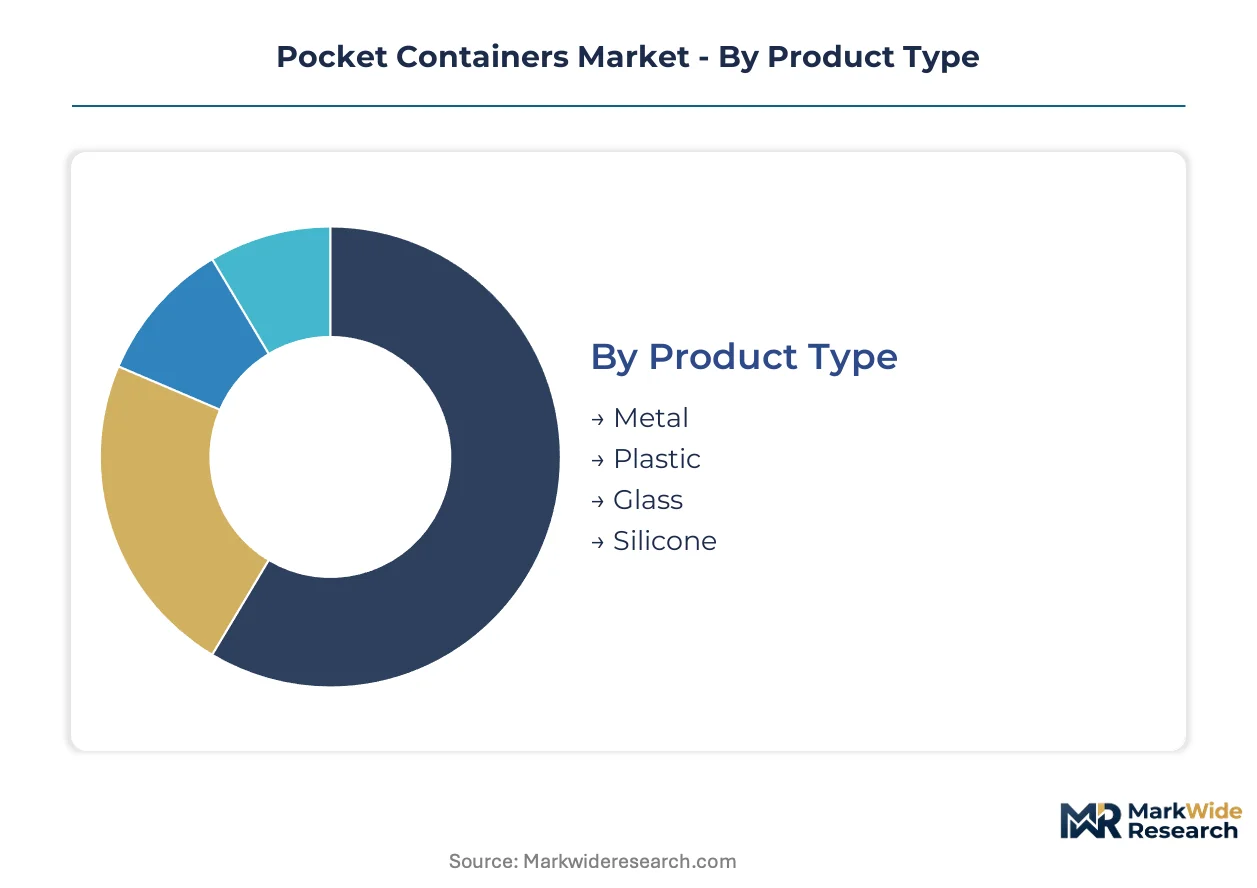
Pocket container formats diverge sharply across material barriers, dimensional thresholds, and end-use performance requirements. Each segmentation axis carries distinct regulatory footprints and margin architectures that reshape procurement priorities across converter tiers.
Product Type:
Supply concentration clusters around injection molding and blow molding corridors in Germany, Japan, and the US Gulf Coast, with material selection dictating capital intensity and barrier specification pathways.
- Metal:Thin-wall aluminum and stainless steel formats leverage infinite recyclability credentials for premium personal care and pharmaceutical mini-containers. German and Italian forming facilities command 48-72 hour fulfillment cycles for European cosmetic houses. EU Green Deal circularity mandates accelerate mono-material aluminum substitution against multilayer plastic barriers.
- Plastic:Polyethylene terephthalate and polypropylene dominate unit economics through blow-molding scale efficiencies near Frankfurt and Osaka. FDA food-contact substance notifications govern additive migration limits for US-bound condiment and sauce applications. Resin price volatility compresses converter margins during petrochemical cycle peaks.
- Glass:Borosilicate and soda-lime constructions serve pharmaceutical-grade stability requirements through specialized German and Italian forming expertise.
- Silicone:Temperature-resistant foldable formats command premium multiples in Japanese travel accessories and outdoor recreation subscription channels.
Today's leader: Plastic. Tomorrow's challenger: Metal.
Size:
Dimensional thresholds segment manufacturing equipment footprints and automation economics across converter facilities.
- Small (15-100 mL):Pharmaceutical and cosmetic mini-containers demand precision molding tolerances and ISO 15378 certification barriers. Blow-fill-seal integration protects margin structures for qualified European converters serving biologic stability requirements.
- Medium (100-250 mL):Single-serve condiment and sauce applications concentrate in German discount retailer specifications with oxygen scavenger PET constructions.
- Large (250-400 mL):Quick-service restaurant procurement departments specify these formats for urban commuter meal bundles across dense metropolitan corridors.
- Extra Large (400-500 mL):Bulk travel accessories and outdoor recreation kits favor silicone foldability for space-constrained luggage configurations.
Medium formats anchor current volume. Small formats are climbing the fastest on pharmaceutical-grade certification premiums.
Application:
End-use performance requirements fragment barrier specifications and regulatory compliance burdens across distinct value pools.
- Food Storage:Barrier-enhanced multilayer constructions concentrate margin pools in shelf-stable condiment applications. Japanese convenience store chains specify mono-material PET with built-in oxygen scavengers for simplified recycling stream sorting.
- Liquid Transport:Leak-proof seal integrity drives silicone and metal format premiums in commuter beverage and personal hydration segments. California and EU state-level PFAS restrictions eliminate fluorinated barriers from high-performance specifications.
- Travel Accessories:Foldability and temperature resistance command 3-4x price multiples in Japanese gift-giving and subscription box channels.
- Personal Care:Perceived quality differentiation favors glass and aluminum formats for premium cosmetic and pharmaceutical mini-container positioning.
Food Storage dominates procurement volume. Travel Accessories show steepest expansion trajectory on reusability premiums.
Distribution Channel:
Channel configuration dictates packaging specification, lot size economics, and traceability documentation requirements.
- Online Retail:Direct-to-consumer fulfillment demands damage-resistant formats with digital watermark traceability for EU Digital Product Passport compliance. Amazon and specialized subscription platforms specify lightweight constructions to optimize shipping cost structures.
- Supermarkets:Private-label procurement programs require BRCGS certification and ISO 22000 documentation for food-contact market access. German discount retailers impose annual carbon intensity reduction targets alongside unit cost specifications.
- Specialty Stores:Premium positioning enables glass and metal format penetration in cosmetic and outdoor recreation segments with extended shelf-facing negotiations.
- Direct Sales:Quick-service restaurant chains operating in France, the Netherlands, and California specify lifecycle assessment thresholds that disqualify virgin-only formats from supplier scorecards.
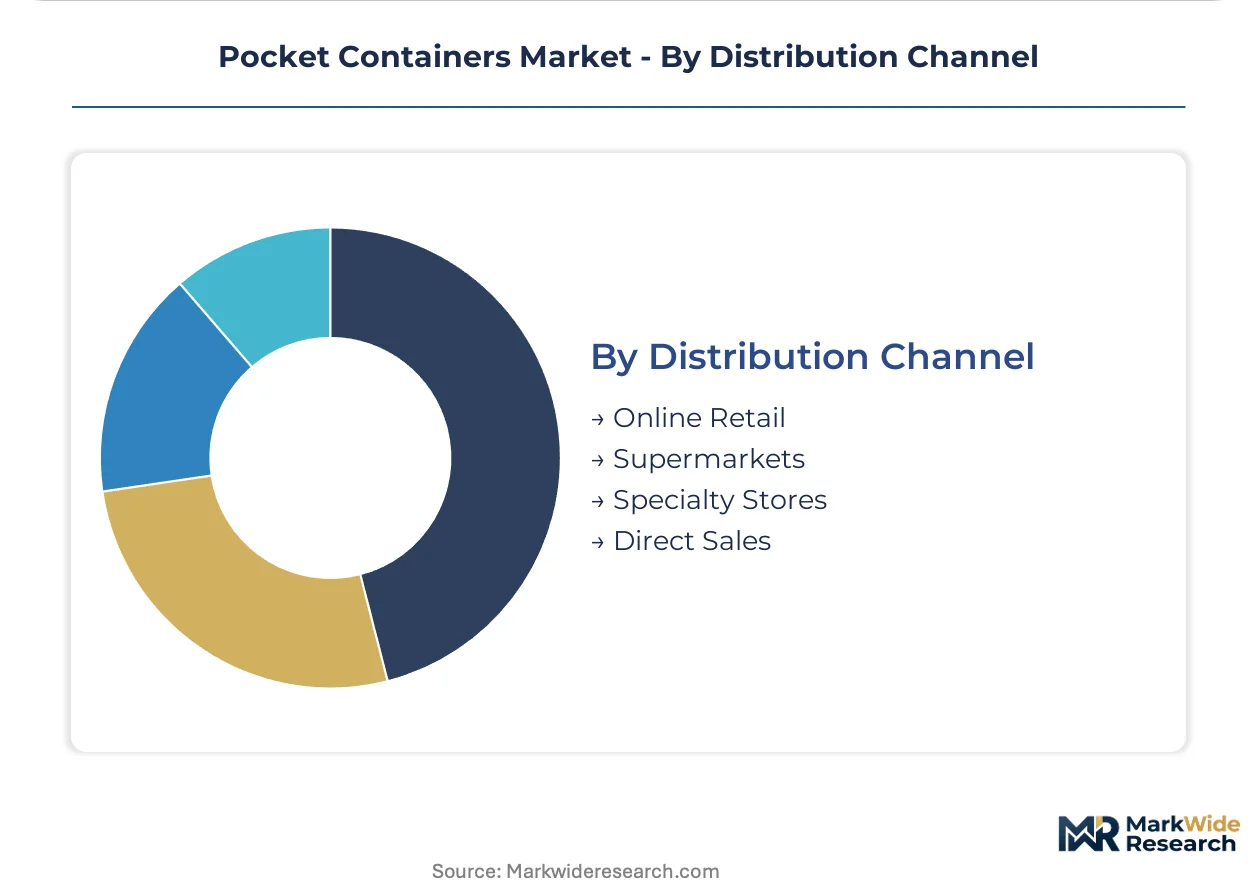
Supermarkets anchor volume throughput. Online Retail gains share fastest on digital traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision molding clusters near Frankfurt anchor global pocket container production, with specialized forming expertise concentrated in Germany, Japan, and the United States driving format innovation and sub-48-hour fulfillment cycles for quick-service restaurant chains.
Germany
Urban commuter lifestyles in dense metropolitan corridors sustain demand for single-serve food and beverage formats. EU REACH and F-Gas Regulation compliance requirements shape material selection and migration testing protocols for converters serving European retail private-label programs. Precision molding clusters in the Frankfurt-Rhine-Main region deliver rapid fulfillment cycles for discount retailers specifying mono-material PET constructions with oxygen scavenger functionality.
United States
FDA food-contact substance notification pathways streamline polymer approval timelines for US-bound condiment and sauce applications. State-level PFAS restrictions in California, Maine, and Washington eliminate fluorinated barriers from high-performance specifications. Blow-molding capacity concentrates along the Gulf Coast petrochemical corridor, where converters expand barrier-enhanced PET production for quick-service restaurant procurement departments.
Japan
Gift-giving culture and subscription box channels drive premium positioning for temperature-resistant silicone foldable formats. METI industrial standards govern food-contact material specifications for convenience store chains. Osaka-Kansai molding clusters specialize in small-format pharmaceutical and cosmetic mini-containers requiring precision tolerances and rapid turnaround times.
India
FSSAI-compliant localized production addresses the expanding quick-service restaurant market serving over 400 million urban consumers. Domestic injection molding capacity in Pune and Ahmedabad scales to meet pan-Asian export demand. Central government PLI scheme incentives accelerate capital investment in food-grade packaging infrastructure across western manufacturing corridors.
South Korea
Outdoor recreation and travel accessory segments command premium multiples for reusable format innovations. MFDS pharmaceutical-grade certification requirements protect margin structures for qualified converters serving biologic stability applications. Seoul-Incheon industrial zones concentrate blow-fill-seal integration capabilities for pharmaceutical mini-container production.
Pocket Containers Market Competitive Landscape
Global majors compete with regional champions across material specialization and certification tiers, creating a layered structure where glass-forming expertise, blow-molding scale, and metal closure systems occupy distinct competitive positions. The vendor base separates into three strategic archetypes: precision pharmaceutical-grade specialists, high-volume plastic converters, and diversified packaging conglomerates with integrated closure capabilities. Dominant competitive moves include backward integration into resin compounding and geographic expansion through qualified facility replication in high-growth Asian corridors.
Among German-based precision formers, Gerresheimer AG exemplifies the pharmaceutical-grade mini-container archetype through specialized glass-forming expertise. Plastipak Packaging anchors North American blow-molding capacity for single-serve beverage formats, representing the scale-driven converter tier. Silgan Holdings occupies a position within diversified metal closure systems, extending shelf stability applications for condiment and sauce segments. These three entities collectively illustrate the material-based segmentation governing competitive positioning across the pocket containers value chain.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Alpha Packaging Holdings |
| APTACA Spa |
| USON Plast |
| Graham Packaging |
| Plastipak Packaging |
| Tupperware Brands Corporation |
| CKS Packaging |
| Silgan Holdings |
| Others |
Value Network & Pricing Analysis
EU Digital Product Passport mandates gate qualified supply access and premium-tier pricing power by forcing converters to deploy spectroscopic verification and blockchain-anchored chain-of-custody documentation. Brand owners in France, the Netherlands, and California now disqualify virgin-only formats from supplier scorecards, compressing margins for non-compliant tiers while rewarding certified mono-material constructions with 3-4x price multiples.
Pricing Analysis
Resin cost pass-through dynamics dominate converter economics, with propylene and ethylene feedstock swings compressing margins by 8-15 percentage points during petrochemical cycle peaks. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and economy virgin tiers reflects ISO 15378 and FDA notification barriers. Pricing pressure stems from aluminum substitution in premium personal care segments where German and Italian thin-wall metal formats command shelf space. Quick-service restaurant procurement departments exhibit highest price sensitivity, while pharmaceutical mini-container buyers prioritize stability certification over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from quick-service restaurant chains and retail private-label programs mandate qualified backup capacity across Germany, Japan, and the US Gulf Coast. Feedstock dependencies center on Saudi and Qatari ethylene supply, German precision molding equipment, and Japanese silicone polymer grades. Single-source vulnerability concentrates in blow-fill-seal pharmaceutical integration where Seoul-Incheon and Frankfurt-Rhine-Main clusters hold qualified capacity. Distribution runs through converter-direct relationships with pan-Asian quick-service networks and European discount retail procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pocket containers constitute a late-cycle quality story as urban commuter demand shifts toward barrier-enhanced mono-material formats with digital traceability credentials. Premium specifications now function as primary purchase qualifiers rather than secondary attributes across European and North American procurement.
For Market Incumbents: Acquire spectroscopic verification and blockchain documentation capabilities to defend pharmaceutical-grade and food-contact certified tier positioning against aluminum substitution threats. Backward integration into regional resin compounding protects margin structures during petrochemical volatility cycles. Priority investment targets ISO 15378-qualified blow-fill-seal capacity in Seoul-Incheon and Pune-Ahmedabad corridors.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription channels targeting Japanese gift-giving and outdoor recreation segments where silicone foldability commands premium multiples. White-space concentration exists in FSSAI-compliant localized production for Indian quick-service expansion and EU CSRD-driven circularity procurement. Go-to-market leverage rests on digital watermark traceability integration ahead of 2027 Ecodesign mandate deadlines.
For Investors and Strategic Acquirers: Roll-up economics work for precision pharmaceutical-grade formers because certification barriers and biologic stability requirements protect margin structures from commodity converter competition. Five-to-ten year viability hinges on qualified facility replication in high-growth Asian corridors and mono-material technical service capabilities. Signal to monitor: FDA and EFSA notification backlog resolution timelines as inflection indicator for product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of food-contact certified polymers hedges converter margins against Gulf Coast feedstock volatility. |
| Digital Watermark Traceability Deployment | Blockchain-anchored chain-of-custody documentation satisfies EU Digital Product Passport mandates for private-label access. |
| Qualified Facility Replication in India | FSSAI-compliant Pune and Ahmedabad capacity captures quick-service procurement serving 400 million urban consumers. |
| Mono-material PET Oxygen Scavenger Transition | Built-in barrier functionality displaces multilayer EVOH constructions for simplified recycling stream sorting. |
| Blow-Fill-Seal Pharmaceutical Integration | ISO 15378 certification protects margin pools in biologic stability applications with limited qualified supplier base. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with converter plant managers, quick-service restaurant procurement directors, retail category buyers, and regulatory affairs specialists with secondary validation from FDA food-contact substance notifications, ECHA REACH registrations, EU F-Gas Regulation filings, and customs trade data. Bottom-up capacity modeling across German, Japanese, and US Gulf Coast precision molding clusters triangulated against top-down demand segmentation.
Historical reference periods anchored volume and value projections across the modeling period, with analytical frameworks disaggregating by material barrier tier, dimensional threshold, end-use application, and regional regulatory cluster. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers and petrochemical cycle positioning. Industry-specific forecast inputs incorporated quick-service restaurant expansion pipelines and EU extended producer responsibility implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction adoption or resin price volatility spikes. Projections reflect assumptions on regulatory compliance cost pass-through and certification backlog resolution. Deviation in FDA notification streamlining or EU Digital Product Passport enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Slide Top Tins Market
Containers
Conipack Pails Market
Containers
Multi Cavity Tray Market
Containers
Food Grade Stainless Steel Container Market
Containers
Shipping Container Liners Market
Containers
Spout Containers Market
Containers
Algeria Container Glass Market
Containers
Global Food Storage Container Market
Containers
Steel Containers Market
Containers
Roll Containers Market
Containers
Jug Shipper Market
Containers
Essential Oil Containers Market
Containers
Single Wall Jars Market
Containers
Sanitary Cans Market
Containers
Oblong Jar Market
Containers
HDPE Bottles Market