
 PUR Containers Packaging Market | 2026-2036
PUR Containers Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
PUR Containers Packaging Market Analytics
Modular cold-chain packaging configurations are pivoting buyer choice away from single-use expanded polystyrene toward reusable PUR-insulated container systems with interchangeable gel-pack inserts. Sonoco Products Company leverages its ThermoSafe division to sustain pharmaceutical lane dominance across North American and European corridors. Cold Chain Technologies anchors its position through specialized phase-change material integration for ultra-frozen vaccine distribution. Dow Chemical Company differentiates via upstream polyurethane chemistry control, supplying formulated systems to molded container fabricators.
PUR containers packaging denotes rigid or semi-rigid vessels fabricated from polyurethane foam cores laminated with polyethylene or polypropylene skins, achieving thermal insulation values of 0.020–0.025 W/m·K and maintaining 2–8°C stability for 96+ hours in ambient summer profiles. Rigid containers currently occupy the largest value share due to pharmaceutical validation requirements and multi-turn asset depreciation models, while stand-up pouches with PUR-insulated gussets represent the fastest-growing configuration as meal-kit and specialty food brands seek collapsible thermal protection. Semi-rigid formats concentrate margin pools where converters blend injection-molded structural frames with in-situ foamed PUR cores for customized dimensional stability.
FDA 21 CFR Part 211 guidelines and EU GDP Chapter 9 standards shape demand by mandating documented temperature continuity for pharmaceutical distribution, forcing packagers toward validated PUR solutions with embedded data loggers. The EPA Significant New Alternatives Policy program and REACH restrictions on isocyanate exposure limits are simultaneously constraining formulation chemistry and opening market access for low-emission, water-blown systems with certified occupational safety profiles. Stakeholders must monitor how evolving pharmacopeial thermal-mapping protocols and state-level extended producer responsibility laws for packaging waste redefine total cost of ownership calculations across container lifecycles.
Market Dynamics
Pharmaceutical cold-chain validation requirements are compressing buyer decision cycles toward pre-qualified, reusable PUR container systems with embedded temperature logging capabilities. This structural pull is reshaping converter investment priorities across formulation chemistry, molding automation, and asset-tracking software integration.
Growth Catalysts
- EU F-Gas Regulation phase-down:Hydrofluorocarbon blowing agent restrictions are accelerating converter migration to pentane and water-blown polyurethane systems with lower global warming potential.
- Biologics shipment expansion:Cell and gene therapy distribution networks are demanding validated thermal packaging with 96-hour-plus temperature stability for international lane integrity.
- GDP Chapter 9 compliance:European pharmaceutical distributors must document temperature continuity across supply chains, forcing adoption of qualified PUR-insulated containers with data logger integration.
Market Restraints
- Isocyanate feedstock concentration:MDI and TDI supply is consolidating among Asian petrochemical producers, exposing converters to input cost volatility and freight exposure.
- REACH occupational exposure limits:ECHA restrictions on diisocyanate handling are increasing formulation complexity and requiring certified worker training programs.
- Expanded polystyrene substitution threat:Low-cost EPS shippers retain share in single-use, short-duration food delivery where validation requirements remain minimal.
Strategic Opportunities
- Meal-kit channel expansion:Collapsible PUR-insulated stand-up pouches with gusseted thermal cores are capturing share in subscription food delivery requiring collapsible return logistics.
- Indian pharmaceutical export growth:CDSCO-aligned cold-chain infrastructure investment is creating demand for GDP-compliant reusable containers in Mumbai and Hyderabad distribution corridors.
- Water-blown system certification:EPA Significant New Alternatives Policy recognition of low-emission formulations is opening federal procurement channels for sustainable PUR packaging.
Industry Challenges
- Thermal validation protocol complexity:ISTA 7E and pharmacopeial mapping standards require extensive chamber testing, extending new product qualification timelines.
- Multi-material recycling infrastructure:PUR foam cores laminated with polyolefin skins lack established mechanical recycling streams, complicating extended producer responsibility compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PUR Containers Packaging Market |
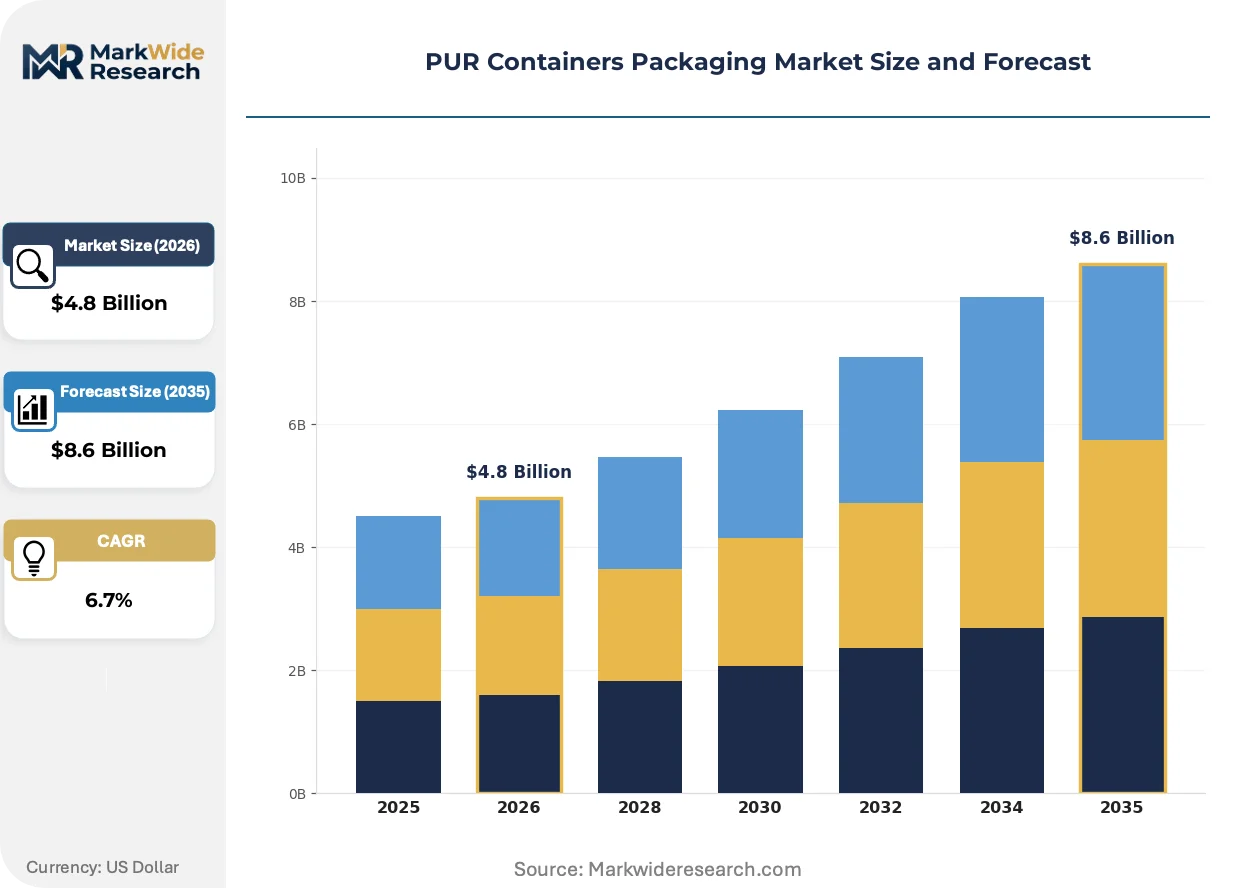
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, Semi-Rigid, Stand-Up Pouches Material: Polyethylene, Polypropylene, PET, Polystyrene End Use Industry: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Distribution Channel: Online Retail, Direct Sales, Supermarkets, Convenience Stores |
| Companies Covered | Sonoco Products Company, Cyropak Industries Inc., Cold Chain Technologies, Sæplast, IP-Group, Dow Chemical Company, Berry Global, Mauser Packaging Solutions, AptarGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PUR Containers Packaging Market Evolving Landscape
Formulation chemistry, regulatory compliance architecture, and procurement logic are simultaneously evolving in PUR container markets. These intersecting shifts are compressing product development cycles and redefining supplier-buyer relationships across pharmaceutical and food distribution networks.
In-situ foamed PUR core injection into injection-molded structural frames is consolidating semi-rigid container manufacturing around hybrid fabrication lines. Pharmaceutical contract packagers are adopting these systems to achieve customized dimensional stability without tooling costs for low-volume specialty biologics. This consolidation is compressing lead times for validated container configurations from 16 weeks to under 8 weeks.
REACH restrictions on isocyanate exposure are forcing reformulation toward low-monomer residual systems and automated closed-cell foaming equipment. German converters are investing in pentane-blown lines ahead of the 2030 F-Gas phase-down milestones. The pharmaceutical segment is absorbing these cost premiums to maintain EU distribution lane access.
Asset-as-a-service rental models are displacing capital purchase for reusable PUR container fleets. Third-party logistics providers in the Netherlands and Belgium are bundling container provisioning with lane validation and data logger retrieval. This shift is most visible in temperature-sensitive generic pharmaceutical distribution where working capital constraints favor operational expenditure structures.
PUR Containers Packaging Market Segmentation
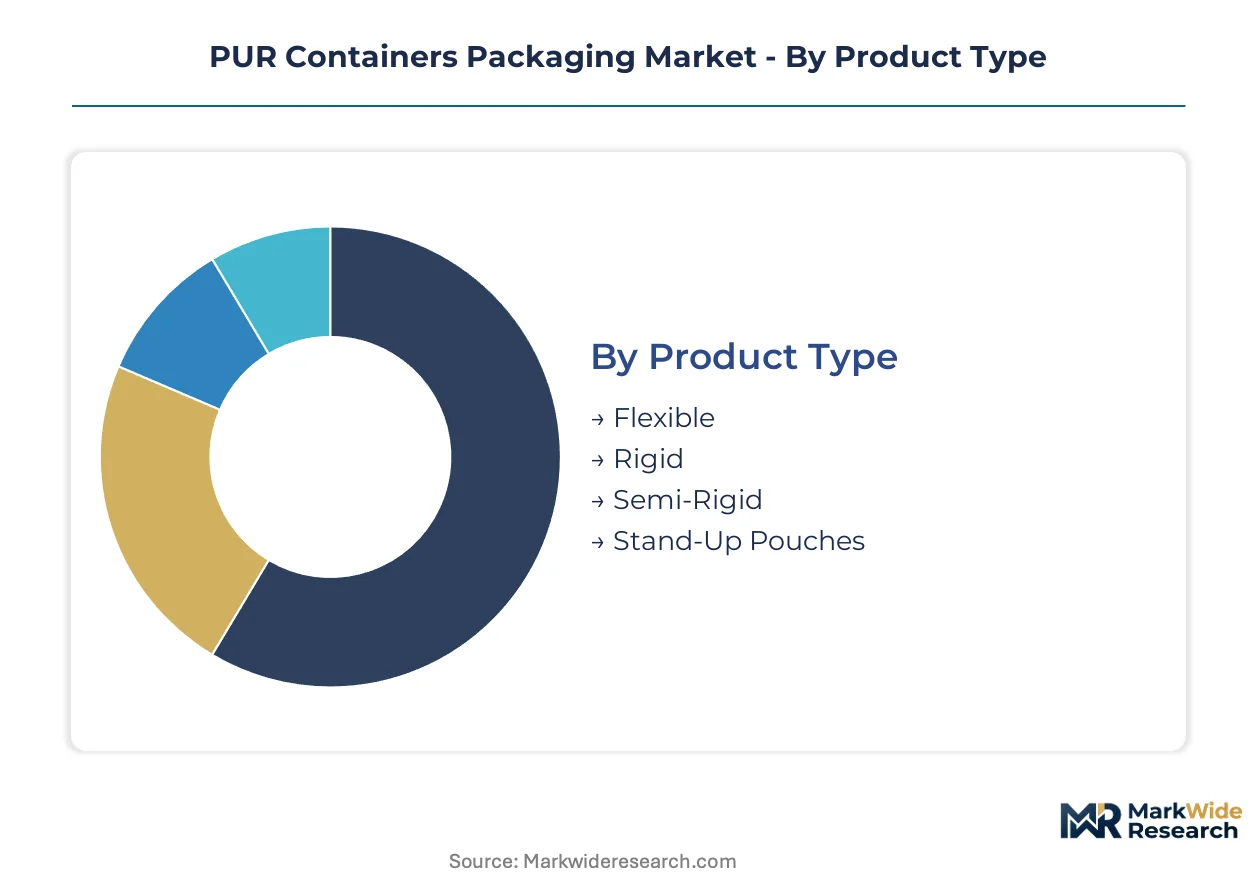
PUR container segmentation reveals how converter capabilities align with divergent thermal performance requirements across pharmaceutical validation tiers and food logistics economics. Material choices and structural formats determine insulation value, regulatory compliance pathways, and total cost of ownership across reuse cycles.
Product Type:
Converter tooling investments concentrate around rigid formats where pharmaceutical validation protocols and multi-turn asset depreciation models lock in premium pricing.
- Rigid:Molded PUR foam cores laminated with polyolefin skins achieve thermal conductivity of 0.020–0.025 W/m·K and maintain 2–8°C stability for 96+ hours. German pharmaceutical exporters drive demand through GDP Chapter 9 compliance requirements for documented temperature continuity.
- Stand-Up Pouches:Gusseted configurations with PUR-insulated cores offer collapsible return logistics for subscription meal-kit brands. Netherlands-based third-party logistics providers bundle these with lane validation services under asset-as-a-service rental models.
- Flexible:Lightweight formats prioritize cost efficiency for short-duration food delivery where thermal mapping validation remains minimal.
- Semi-Rigid:Hybrid fabrication combines injection-molded structural frames with in-situ foamed PUR cores for customized dimensional stability in low-volume specialty biologics.
Today's leader: Rigid. Tomorrow's challenger: Stand-Up Pouches.
Material:
Skin material selection governs moisture barrier performance, chemical resistance, and compatibility with automated filling lines across pharmaceutical and food processing environments.
- Polyethylene:Low-density and linear low-density variants dominate laminated skin applications for moisture resistance and heat-seal compatibility. REACH restrictions on diisocyanate exposure are pushing German converters toward PE-skinned pentane-blown systems ahead of F-Gas phase-down milestones.
- Polypropylene:Higher melting point suits autoclave sterilization requirements in pharmaceutical contract packaging. Indian CDSCO-aligned cold-chain infrastructure investment in Mumbai and Hyderabad corridors is absorbing PP-skinned container output for generic pharmaceutical distribution.
- PET:Clarity and printability advantages concentrate in personal care and household product segments where shelf aesthetics drive procurement.
- Polystyrene:Cost-competitive skins retain position in single-use applications where extended producer responsibility compliance pressures remain limited.
Polyethylene commands current volume. Polypropylene gains fastest on pharmaceutical sterilization demand.
End Use Industry:
Industry-specific regulatory architectures determine validation depth, data logger integration requirements, and acceptable cost premiums per thermal protection tier.
- Pharmaceuticals:FDA 21 CFR Part 211 and EU GDP Chapter 9 mandate documented temperature continuity, forcing adoption of qualified PUR containers with embedded data loggers. Cell and gene therapy distribution networks require 96-hour-plus stability for international lane integrity.
- Food & Beverage:Meal-kit subscription models favor collapsible PUR-insulated formats with reverse logistics optimization. EPA Significant New Alternatives Policy recognition of water-blown systems is opening federal procurement channels for sustainable packaging in this segment.
- Personal Care:Temperature-sensitive formulations drive insulated container demand for prestige skincare distribution.
- Household Products:Concentrated chemical formulations require thermal stability during seasonal shipping peaks.
Pharmaceuticals anchor premium tier economics. Food & Beverage scales volume through collapsible format adoption.
Distribution Channel:
Channel structure determines order fragmentation, lead time compression, and the viability of reusable container return logistics.
- Direct Sales:Pharmaceutical contract packagers and large-format food manufacturers procure validated container systems through converter-direct relationships. ISTA 7E thermal validation protocol requirements extend qualification timelines, favoring established direct channels with technical service capabilities.
- Online Retail:E-commerce fulfillment centers demand collapsible, lightweight thermal protection for temperature-sensitive last-mile delivery. Belgian logistics providers are bundling PUR container provisioning with data logger retrieval services for this channel.
- Supermarkets:Centralized distribution models support reusable container pooling systems for fresh and frozen categories.
- Convenience Stores:Fragmented ordering patterns and limited storage capacity constrain insulated container adoption to high-value frozen categories.
Direct Sales dominates pharmaceutical validation economics. Online Retail scales fastest on meal-kit and specialty food e-commerce expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PUR container fabrication originated in post-war Germany where Bayer AG pioneered polyurethane chemistry for industrial insulation, establishing the Rhine-Ruhr corridor as the foundational production cluster before technology transfer to North American and Asian markets during the 1970s-1980s.
Germany
Pharmaceutical exports from Baden-Württemberg and Bavaria drive demand for GDP Chapter 9-compliant reusable containers with embedded data loggers. The EU F-Gas Regulation accelerates converter migration to pentane-blown systems ahead of 2030 phase-down milestones. The Rhine-Ruhr industrial corridor hosts specialized molders supplying validated thermal packaging to European distribution networks.
United States
FDA 21 CFR Part 211 compliance requirements anchor pharmaceutical cold-chain investment in Massachusetts and North Carolina biotech clusters. The EPA Significant New Alternatives Policy program certifies low-emission water-blown formulations for federal procurement channels. Sonoco Products Company leverages its ThermoSafe division across Midwestern pharmaceutical distribution corridors.
India
CDSCO-aligned cold-chain infrastructure expansion in Mumbai and Hyderabad corridors creates demand for GDP-compliant reusable containers serving generic pharmaceutical exports. The PLI scheme for active pharmaceutical ingredients indirectly supports upstream packaging investment. Gujarat-based converters are scaling fabrication capacity for temperature-sensitive vaccine distribution.
Netherlands
Third-party logistics providers in Rotterdam and Eindhoven pioneer asset-as-a-service rental models bundling container provisioning with lane validation. REACH occupational exposure limits on diisocyanates drive reformulation toward low-monomer residual systems. Dutch meal-kit subscription brands adopt collapsible PUR-insulated stand-up pouches for reverse logistics optimization.
China
NMPA regulatory alignment with ICH guidelines elevates validation requirements for biologics cold-chain distribution in Shanghai and Suzhou pharmaceutical clusters. Dual carbon goals under MEE direction accelerate water-blown system adoption versus HFC-based alternatives. Yangtze River Delta converters supply both domestic vaccine distribution and export markets.
PUR Containers Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across validation depth and reuse-cycle economics, with pharmaceutical-certified specialists commanding pricing multiples over food-logistics generalists. The market structure concentrates around three strategic archetypes: integrated chemical-to-container conglomerates controlling upstream polyurethane formulation, specialized cold-chain engineering firms with pharmacopeial validation capabilities, and diversified packaging converters leveraging existing customer relationships. Dominant competitive moves include M&A targeting thermal validation expertise and capacity expansion in water-blown fabrication lines ahead of regulatory phase-downs.
Among North American-based diversified packaging groups, Sonoco Products Company and Cold Chain Technologies exemplify contrasting positioning archetypes within the cold-chain engineering tier. Dow Chemical Company anchors the integrated chemical-to-container segment through formulated system supply to downstream fabricators. These three entities collectively represent the spectrum from upstream chemistry control through specialized engineering to diversified packaging scale.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Cyropak Industries Inc. |
| Cold Chain Technologies |
| Sæplast |
| IP-Group |
| Dow Chemical Company |
| Berry Global |
| Mauser Packaging Solutions |
| AptarGroup |
| Others |
Value Network & Pricing Analysis
GDP Chapter 9 compliance mandates from European pharmaceutical distributors are compressing procurement timelines toward pre-qualified reusable container systems, forcing converters to absorb pentane-blown formulation premiums and embedding these costs into long-term rental contracts rather than spot pricing.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-validated, food-logistics, and single-use economy levels dominates converter revenue models. Price differentiation hinges on ISTA 7E thermal certification depth and embedded data logger integration. Cost compression in the food-logistics tier is intensifying because meal-kit brands prioritize collapsible return logistics over 96-hour stability. Single-use EPS substitution retains price-sensitive short-duration food delivery segments.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Eindhoven anchor European hub-and-spoke patterns for reusable container pooling. Supply concentrates in Germany, the United States, and China. MDI and TDI feedstock draws from Asian petrochemical producers. Single-source vulnerability in isocyanate supply exposes converters to freight cost volatility. Distribution runs through third-party logistics providers bundling asset provisioning with lane validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU F-Gas Regulation compliance costs and Indian CDSCO-aligned infrastructure investment creates margin expansion opportunities for converters with dual-hemisphere fabrication footprints.
For Market Incumbents: Deploy water-blown formulation certification to capture EPA Significant New Alternatives Policy procurement channels before 2030 F-Gas phase-down milestones. Backward integration into MDI supply hedges Asian petrochemical concentration risk. Reinforce pharmaceutical lane dominance through embedded temperature logging capabilities that GDP Chapter 9 mandates render non-negotiable. For New Entrants and Emerging Players: Direct-to-food-brand digital channels bypass established converter-distributor relationships in the meal-kit segment. White-space concentration sits with collapsible stand-up pouches for subscription delivery. Target Indian pharmaceutical export corridors where CDSCO infrastructure investment outpaces domestic converter capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized cold-chain engineering firms possessing pharmacopeial validation capabilities. Five-to-ten-year viability favors asset-light rental model operators over capital-intensive molders. Watch for ISTA 7E protocol revisions as inflection indicators for qualification cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Blown Formulation Certification | EPA SNAP recognition opens federal procurement channels for sustainable PUR packaging. |
| Asset-as-a-Service Rental Model | Dutch logistics providers bundle container provisioning with GDP Chapter 9 lane validation. |
| In-Situ Foaming Line Investment | German converters compress lead times from 16 weeks to under 8 weeks for biologics. |
| Backward Integration into MDI Supply | Captive isocyanate sourcing hedges Asian petrochemical concentration and freight exposure. |
| Indian Fabrication Footprint Expansion | CDSCO-aligned cold-chain infrastructure in Mumbai and Hyderabad corridors absorbs premium container output. |
Research Methodology
Bottom-up pharmaceutical and food-logistics modeling reconciled against top-down polyurethane formulation tracking forms the analytical core. Primary interviews with cold-chain engineering directors, pharmaceutical procurement managers, third-party logistics operators, and converter plant managers combined with secondary validation from FDA 21 CFR Part 211 filings, ECHA REACH restriction updates, EU F-Gas Regulation phase-down schedules, and customs trade data. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map container fabrication capacity against end-use demand across product type, material skin, end-use industry, and distribution channel dimensions. CAGRs derive from segment-level growth rate reconciliation against macroeconomic drivers. Pentane-blown system adoption curves and pharmacopeial thermal-mapping protocol evolution serve as industry-specific forecast inputs across the projection horizon.
Regulatory acceleration, feedstock supply disruption, and pharmacopeial protocol revision are the dominant revision risks. Forecasts reflect documented assumptions about F-Gas phase-down timing and biologics shipment expansion trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Hinged Lid Tins Market
Containers
Metal IBC Market
Containers
Metal Crates Market
Containers
Clear Hinged Container Market
Containers
Kuwait Container Glass Market
Containers
Foldable Steel Containers Market
Containers
Container Market
Containers
Wire Containers Market
Containers
Pail Lids Market
Containers
Snap-Lock Container Market
Containers
Laboratory Sample Container Market
Containers
Cylindrical Cans Market
Containers
PET Hinged Containers Market
Containers
Lever Lid Cans Market
Containers
Vacuum Formed Tray Market
Containers
Light Resistant Containers Market