
 Cut and Stack Labels Market | 2026-2036
Cut and Stack Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Cut and Stack Labels Market Analysis
REACH is restructuring material sourcing protocols for European label converters, forcing reformulation of adhesive chemistries and substrate coatings. CCL Industries leverages captive film extrusion capacity to control substrate cost volatility across its European plants. Fort Dearborn Company anchors North American beverage label supply through dedicated flexographic operations in Wisconsin and California. Avery Dennison Corporation extends its materials science portfolio into sustainable facestock grades that compete on performance parity with conventional vinyl.
Cut and stack labels are individual, pre-cut paper or film substrates applied to containers with wet-glue adhesives, typically printed through offset lithography or flexography at resolutions up to 175 lines per inch for premium graphic reproduction. These labels serve beverage, food, and pharmaceutical packaging where brand differentiation, regulatory compliance printing, and cost-efficient high-volume decoration remain essential. Pressure-sensitive labels dominate value capture in pharmaceutical serialization where tamper-evidence mandates command premium pricing, while shrink sleeves expand fastest in craft beverage segments demanding 360-degree decorative coverage. Paper substrates retain volume leadership in wine and spirits applications where tactile embossing and foil stamping reinforce brand heritage positioning.
FDA food-contact substance notifications govern adhesive migration limits for labels applied to beverage containers in the United States, while EU F-Gas Regulation phases out solvent-based drying systems that historically supported gravure and flexographic throughput. ISO 9001 quality management and ISO 14001 environmental management certifications function as baseline qualifiers for supplier qualification at multinational consumer goods firms. Stakeholders must monitor evolving extended producer responsibility frameworks that shift end-of-life label recovery costs upstream to converters and brand owners.
Market Dynamics
REACH compliance is restructuring material sourcing protocols across European label converters, forcing wholesale reformulation of adhesive chemistries and substrate coatings while compressing supplier margins.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightened material compliance requirements are accelerating substrate innovation toward recyclable facestocks in beverage applications.
- Craft brewery expansion:Premium glass-bottle aesthetics in Germany and neighboring markets are pulling wet-glue label specifications toward higher-resolution offset reproduction.
- Solvent recovery systems:Regenerative thermal oxidizer retrofits are enabling flexographic converters to maintain throughput under EU F-Gas Regulation solvent restrictions.
Market Restraints
- Petrochemical substrate volatility:Film-grade polypropylene and polyethylene pricing swings directly compress converter gross margins on long-term beverage contracts.
- Gravure cylinder lead times:Extended tooling procurement from specialized engravers in Italy and Japan delays brand owner packaging refresh cycles.
- Pressure-sensitive substitution:Self-adhesive label formats are capturing pharmaceutical serialization volumes where tamper-evidence mandates command premium positioning.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging label recovery cost-shifting mechanisms in France and Germany create first-mover advantage for closed-loop substrate designers.
- Wine export corridor expansion:German and Italian producers are upgrading tactile embossing and foil stamping capabilities to access Asian duty-free channels.
- Water-based adhesive convergence:Hybrid drying systems combining infrared and hot-air technologies are opening formulation flexibility previously locked to solvent platforms.
Industry Challenges
- ISO 14001 certification timelines:Environmental management system audits are extending supplier qualification periods at multinational consumer goods firms.
- Legacy press integration:Retrofitting existing offset lithography lines for UV-LED curing requires capital outlays that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cut and Stack Labels Market |
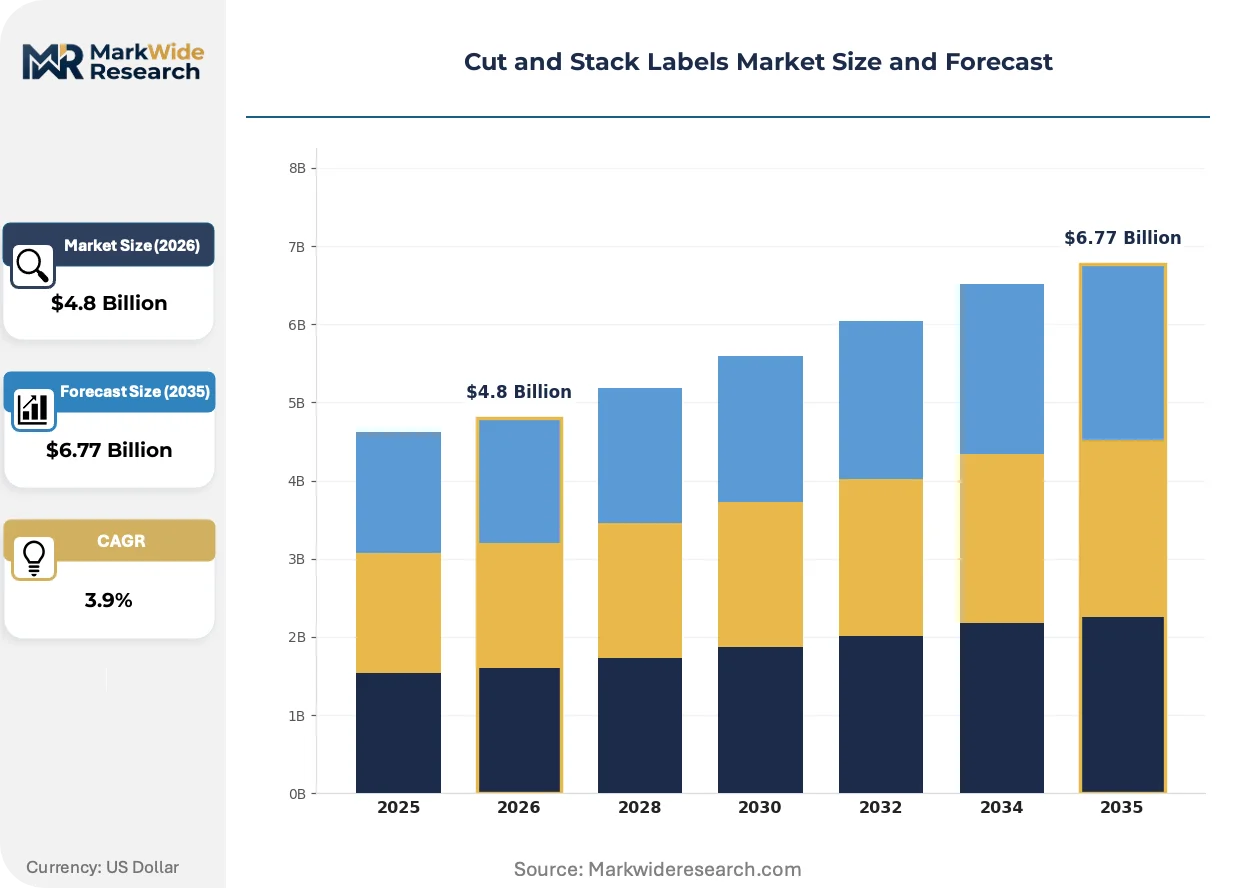
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Labels, Shrink Sleeves, Roll Labels, Heat Transfer Labels Material: Plastic, Paper, Aluminum, Vinyl End User: Food & Beverage, Consumer Goods, Pharmaceuticals, Personal Care Printing Technology: Flexographic Printing, Lithographic Printing, Digital Printing, Gravure Printing |
| Companies Covered | Fort Dearborn Company, Sato Holdings Corporation, CCL Industries, Smyth Companies, Resource Label Group, Multi-Color Corporation, WS Packaging Group, OMET, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cut and Stack Labels Market Emerging Trajectories
Digital prepress workflows and sustainable substrate development are compressing traditional competitive advantages in label conversion, while regulatory chemistry constraints are accelerating equipment replacement cycles.
Water-based adhesive technology is consolidating its position in beverage labeling applications previously dominated by solvent-borne systems. Major German brewers and sparkling water producers are specifying these formulations to preempt REACH substance restrictions. The shift is consolidating procurement leverage among adhesive compounders with captive resin synthesis capabilities, squeezing smaller blenders from approved vendor lists.
EU F-Gas Regulation phase-out schedules for solvent-based drying systems are forcing gravure and flexographic converters toward regenerative thermal oxidation or UV-LED alternatives. The industrial consequence is stranded asset risk for equipment under seven years of age. Italian wine label specialists and Spanish citrus exporters are most affected, with many deferring capacity expansion until technology pathways stabilize.
Brand owner sustainability scorecards are reshaping supplier selection criteria beyond unit cost metrics. Beverage multinationals now weight circularity certifications and carbon disclosure intensity in annual vendor reviews. This behavioral pivot is most visible in German retail channels, where private-label beer and mineral water lines carry packaging recyclability claims that cascade to wet-glue label specifications.
Cut and Stack Labels Market Segmentation
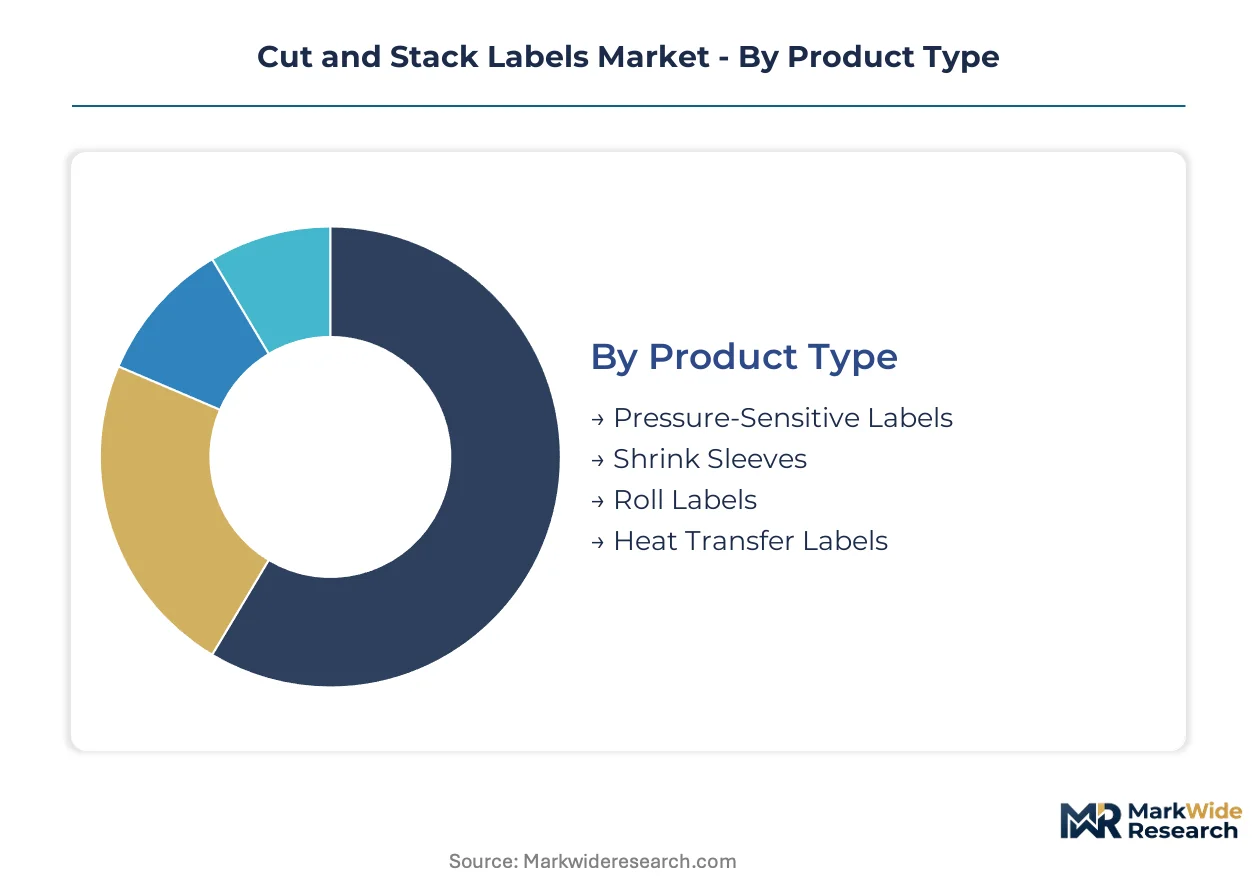
Cut and stack labels compete within a broader label technology ecosystem where substrate choice, adhesive chemistry, and printing resolution determine suitability across beverage, pharmaceutical, and consumer goods applications. Segmentation reveals how wet-glue formats defend volume positions against pressure-sensitive and shrink sleeve alternatives while regulatory chemistry constraints reshape material procurement.
Product Type:
Volume leadership in beverage wet-glue applications contrasts with premium positioning in tamper-evident and full-body decoration formats.
- Pressure-Sensitive Labels:Self-adhesive construction with release liner backing enables high-speed automatic application without glue systems. Pharmaceutical serialization demand in Germany and Switzerland concentrates here, where EMA tamper-evidence mandates command specification premiums that wet-glue formats cannot match.
- Shrink Sleeves:Polyolefin or PETG substrates conform to container contours through heat tunnel application, delivering 360-degree graphic coverage. Craft beverage producers in Bavaria and Baden-Württemberg specify these for premium beer and sparkling water lines where shelf differentiation justifies higher per-unit decoration cost.
- Roll Labels:Continuous web formats suit high-speed rotary labeling equipment common in mid-volume mineral water bottling operations.
- Heat Transfer Labels:Sublimation-based decoration transfers ink directly onto container surfaces, eliminating substrate separation for reusable glass programs.
Mature deployment sits with roll-fed wet-glue systems in mass-market mineral water. Newer deployment is concentrated in shrink sleeve formats for craft brewery limited releases.
Material:
Substrate selection tracks the tension between tactile brand expression and EU Packaging and Packaging Waste Regulation recyclability mandates.
- Paper:Cellulosic facestocks from 60 to 120 gsm basis weights support embossing, foil stamping, and high-resolution offset lithography. German Riesling and Italian Prosecco exporters specify these substrates for Asian duty-free channels where heritage tactile cues command price premiums.
- Plastic:Biaxially oriented polypropylene and polyethylene films offer moisture resistance for refrigerated beverage logistics. REACH substance restrictions are forcing reformulation of film coatings and adhesive primers, compressing converter margins on long-term supply contracts.
- Aluminum:Metallized substrates provide barrier properties and decorative reflectivity for spirits applications.
- Vinyl:PVC-based facestocks retain niche positions where chemical resistance and conformability outweigh sustainability scorecard penalties.
Established specification dominance belongs to paper in wine and spirits. Steepest expansion trajectory is occurring in recyclable film grades engineered for beverage circularity claims.
End User:
Customer procurement patterns diverge between multinational scorecard compliance and regional craft producer flexibility.
- Food & Beverage:Wet-glue labels remain essential for returnable glass bottle systems in German brewing and mineral water, where wash-off adhesive performance determines reuse cycle economics. Brand owner sustainability scorecards now weight circularity certifications in annual vendor reviews.
- Pharmaceuticals:Serialization mandates under EU Falsified Medicines Directive favor pressure-sensitive formats with integrated tamper-evidence features.
- Consumer Goods:Household chemical and automotive product labeling demands chemical-resistant substrates and adhesives.
- Personal Care:Cosmetic and fragrance applications prioritize tactile embellishment and premium substrate aesthetics.
Concentrated procurement leverage rests with beverage multinationals. Emerging specification influence is accumulating in pharmaceutical serialization compliance.
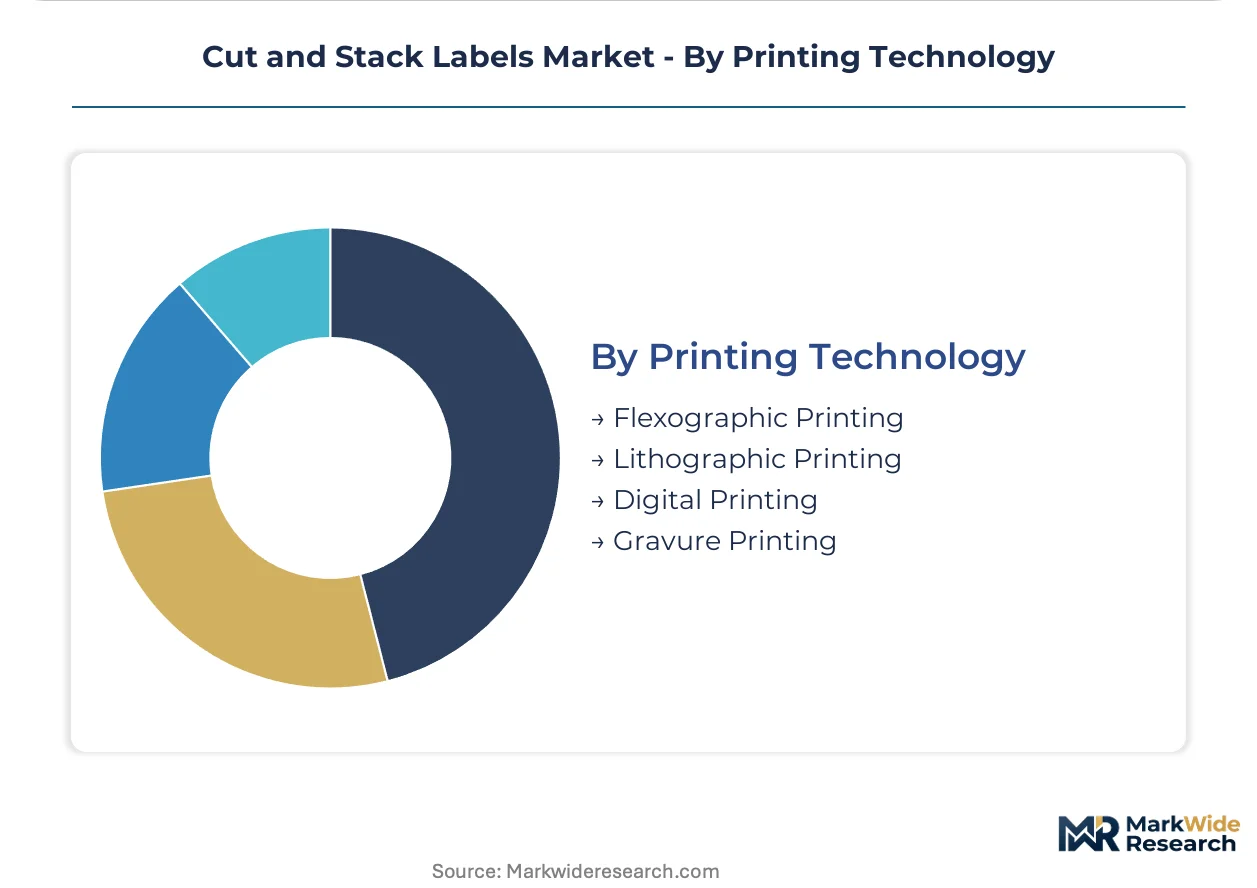
Printing Technology:
Equipment investment cycles reflect regulatory drying system constraints and brand owner resolution requirements.
- Flexographic Printing:Rotary relief printing with photopolymer plates delivers economical medium-resolution output at speeds exceeding 500 feet per minute. Wisconsin and California beverage label specialists anchor North American supply through dedicated flexographic operations with regenerative thermal oxidizer solvent recovery.
- Lithographic Printing:Planographic offset systems achieve 175-line screen resolution for premium wine and spirits label reproduction. Extended gravure cylinder lead times from Italian and Japanese engravers are compressing brand owner packaging refresh timelines.
- Digital Printing:Electrophotographic and inkjet systems enable short-run versioning without plate tooling.
- Gravure Printing:Intaglio cylinder engraving delivers consistent ink density for high-volume commodity labels.
Installed capacity concentration favors flexographic lines in beverage volume production. Technology transition pressure is intensifying on gravure operations facing EU F-Gas Regulation solvent phase-out schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany's Baden-Württemberg and Bavaria regions concentrate wet-glue label manufacturing for premium beverage exports. REACH compliance requirements are restructuring converter supply chains across these zones.
Germany
Craft brewery expansion in Bavaria and mineral water bottling in the Rhineland drive wet-glue label specifications toward higher-resolution offset reproduction. ECHA substance restrictions under REACH are forcing adhesive reformulation across converter operations. Heidelberg and Stuttgart host specialized gravure cylinder engravers serving wine label specialists.
United States
FDA food-contact substance notifications govern adhesive migration limits for beverage container labels nationwide. Wisconsin and California beverage label specialists anchor North American supply through dedicated flexographic operations. Fort Dearborn Company maintains dedicated flexographic capacity in these states for national beverage brand supply.
Italy
Prosecco and wine exporters in Veneto specify tactile embossing and foil stamping for Asian duty-free channel access. EU F-Gas Regulation solvent phase-out schedules are compressing gravure converter margins. Bologna and Modena industrial clusters face stranded asset risk on equipment under seven years of age.
France
Extended producer responsibility frameworks in France are shifting end-of-life label recovery costs upstream to converters and brand owners. ANSM pharmaceutical packaging requirements favor tamper-evident formats in serialization applications. The Champagne region maintains heritage paper substrate specifications for export positioning.
Japan
METI industrial standards influence adhesive chemistry specifications for beverage export compatibility. Japanese printing equipment manufacturers supply rotary label presses to German and Italian converters. Osaka-based machinery specialists dominate gravure cylinder engraving technology exports.
Cut and Stack Labels Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate, adhesive, and printing technology vectors. The market structure tiers between multinational materials science corporations with captive film extrusion and regional converters serving single-country beverage markets. Three archetypes dominate: integrated substrate-to-label manufacturers, dedicated wet-glue specialists, and diversified packaging conglomerates with label divisions. Competitive moves concentrate on M&A for geographic coverage and strategic partnerships for sustainable substrate development.
Among North American fabricators, Fort Dearborn Company and Resource Label Group exemplify the dedicated beverage-label specialist archetype. CCL Industries represents the integrated multinational model with captive film extrusion capacity. Avery Dennison Corporation occupies a position bridging materials science and finished label supply. These three anchors illustrate the competitive tension between scale-driven substrate control and regional converter flexibility.
| Leading Market Players |
|---|
| Fort Dearborn Company |
| Sato Holdings Corporation |
| CCL Industries |
| Smyth Companies |
| Resource Label Group |
| Multi-Color Corporation |
| WS Packaging Group |
| OMET |
| Avery Dennison Corporation |
| Others |
Supply Flow & Price Mechanics
UV-LED curing retrofits on legacy offset lithography lines are simultaneously elevating capital recovery thresholds and compressing converter pricing power across European beverage label supply. The technology transition strands mid-tier operators with equipment under seven years of age while concentrating volume leverage among converters with hybrid drying capabilities.
Pricing Analysis
Short lead-time premiums for gravure cylinder engraving from Italian and Japanese specialists separate rush pricing from standard procurement cycles. Three-tier pricing structure across premium offset reproduction, standard flexographic output, and economy gravure commodity labels reflects resolution grade and tooling investment. Price differentiation hinges on REACH-compliant adhesive certification tiers and volume scale commitments. Cost compression in standard flexographic tiers is intensifying because petrochemical substrate volatility compresses converter margins on long-term beverage contracts. Mass-market mineral water bottlers exhibit highest price sensitivity; premium wine exporters in Germany and Italy demonstrate lowest sensitivity due to heritage positioning requirements.
Supply Chain Analysis
Freight cost differentials between biaxially oriented polypropylene substrate sources in Germany, Italy, and Japan shape converter location economics for Asian export corridors. Raw material dependencies rest on petrochemical resin feedstocks, specialized gravure cylinder steel, and water-based adhesive resin compounds. Single-source vulnerability concentrates in Japanese gravure engraving technology exports. Distribution runs through beverage multinational procurement hubs in Baden-Württemberg and Bavaria, with secondary channels serving regional craft brewery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cut and stack labels market sits in a solvent-to-water-based adhesive transition phase. UV-LED and regenerative thermal oxidation systems are displacing solvent-borne drying platforms under EU F-Gas Regulation mandates.
For Market Incumbents: Extend substrate certification portfolios to capture sustainability scorecard weighting in multinational beverage procurement. Deepen backward integration into captive film extrusion to hedge petrochemical volatility. Acquire specialized gravure engraving capacity in Heidelberg or Stuttgart to compress cylinder lead times and defend against digital prepress substitution. For New Entrants and Emerging Players: Launch via direct-to-craft-brewery distribution in Bavaria and Baden-Württemberg, bypassing multinational procurement gatekeepers. Target pharmaceutical serialization adjacent services where pressure-sensitive tamper-evidence premiums exceed wet-glue economics. White-space exists in closed-loop substrate recovery systems for French extended producer responsibility frameworks. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated substrate-to-label manufacturers with REACH-compliant adhesive compound capabilities. Long-term viability favors converters with hybrid drying technology and circularity certification infrastructure. Watch water-based adhesive specification penetration in German retail private-label lines as inflection signal for technology pathway stabilization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | CCL Industries leverages captive polypropylene capacity to insulate margin from petrochemical volatility. |
| Regenerative Thermal Oxidizer Retrofit | Flexographic converters in Wisconsin maintain solvent-based throughput under EPA emissions constraints. |
| Water-Based Adhesive Formulation Partnership | German brewers specify REACH-compliant chemistries to preempt ECHA substance restrictions. |
| Gravure Cylinder Engraving Acquisition | Italian wine label specialists compress packaging refresh timelines for Prosecco export positioning. |
| Circularity Certification Program | Beverage multinationals weight ISO 14001 and carbon disclosure intensity in annual vendor reviews. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with label converter operations managers, beverage brand procurement directors, adhesive compounder technical leads, and gravure cylinder engraving specialists combined with ECHA REACH substance databases, EU F-Gas Regulation implementation reports, and flexographic equipment manufacturer disclosures. Bottom-up volume modeling triangulated against top-down packaging industry expenditure benchmarks.
Data-stream reconciliation across substrate consumption metrics, printing equipment installation records, and beverage production volumes shaped the analytical framework. Segmentation dimensions modeled include substrate material, adhesive chemistry compliance tier, printing resolution grade, and end-use application across the analysis window. CAGRs were derived from trend extrapolation of equipment replacement cycles and regulatory phase-out schedules. Forecast inputs incorporated EU Packaging and Packaging Waste Regulation recyclability mandate timelines and extended producer responsibility cost-shifting mechanisms.
Regulatory enforcement delays, adhesive formulation performance gaps, and substrate cost volatility are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Wrap Around Labels Market
Labels
Multi-Part Labels Market
Labels
Thermal Labels Market
Labels
Healthcare and Laboratory Labels Market
Labels
Kraft Labels Market
Labels
Global Security Labels Market
Labels
High Gloss Labels Market
Labels
Freezer Label Market
Labels
Wire Marking Labels Market
Labels
Global Label Market
Labels
Wet Glue Labeling Machines Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Non-Adhesive Tags Market
Labels
Sustainable Labels Market
Labels
ESD Protective Signage Labels Market
Labels
North America Self-Adhesive Labels Market